
 Hot Cast Elastomers Market | 2026-2036
Hot Cast Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Cast Elastomers Market Analytics
Capital-intensity divergence between integrated polyol producers and compound-only specialists is collapsing as raw material volatility erodes margin buffers for non-integrated players. BASF SE leverages captive adipic acid and MDI capacity to sustain cost positions across European automotive supply chains. Huntsman International LLC anchors its competitiveness through differentiated aliphatic polyurethane systems for light-stable medical and aerospace applications. Wanhua Chemical Group dominates Asia-Pacific feedstock economics through backward integration into crude MDI and polyether polyol production.
Hot cast elastomers are thermoset polymers formed by reactive casting of liquid prepolymers with curatives into molds, typically achieving Shore hardness from 70A to 75D and tensile strength exceeding 25 MPa for load-bearing industrial components. Polyurethane formulations lead volume consumption due to their tunable abrasion resistance and load-bearing capacity in mining and material handling equipment. Silicone cast elastomers represent the fastest-growing product category as medical device manufacturers specify implant-grade platinum-cured systems for catheters and seals. The automotive parts application segment concentrates margin pools where OEMs qualify formulations for chassis bushings, jounce bumpers, and steering column isolators requiring 100,000-cycle durability.
EPA air toxics standards and OSHA isocyanate exposure limits shape formulation choices and plant capital requirements across US manufacturing bases. REACH registration and the EU Green Deal's chemical sustainability criteria restrict certain aromatic amine curatives while accelerating bio-based polyol qualification programs. Manufacturers must monitor evolving automotive electrification specifications that demand cast elastomers with enhanced thermal stability for electric motor mounts and battery isolation systems.
Market Dynamics
Automotive electrification specifications are compressing formulation development cycles as OEMs demand cast elastomers with thermal stability above 120°C for battery isolation systems and electric motor mounts, forcing compounders to accelerate qualification timelines.
Growth Catalysts
- EPA Air Toxics Standards:Tightening volatile organic compound limits on US casting operations are accelerating investment in closed-mold systems and low-emission curatives among domestic manufacturers.
- Mining Equipment Retrofit Cycles:Abrasion-resistant polyurethane rollers and wheels in Australian and Canadian open-pit operations are driving replacement demand as ore throughput intensifies.
- Platinum-Cured Silicone Systems:Medical device manufacturers in Germany and Switzerland are specifying implant-grade cast elastomers for catheter seals and surgical instrument grips requiring biocompatibility certification.
Market Restraints
- Crude MDI Price Volatility:Non-integrated compounders face margin compression when feedstock costs spike, eroding competitiveness against backward-integrated producers with captive polyol supply.
- Aromatic Amine Curative Restrictions:REACH registration requirements and EU Green Deal chemical sustainability criteria are eliminating certain traditional curatives from European formulations.
- Thermoplastic Polyurethane Substitution:Injection-moldable TPU is capturing lower-load bearing applications in consumer goods and light industrial equipment where processing speed outweighs cast elastomer performance.
Strategic Opportunities
- India Industrial Belt Expansion:Material handling equipment manufacturers in Pune and Chennai are qualifying high-performance cast polyurethane for conveyor systems and forklift wheels as domestic logistics infrastructure scales.
- OSHA Isocyanate Exposure Rulemaking:Anticipated tightening of workplace exposure limits is creating first-mover advantage for aliphatic polyurethane system houses with established low-monomer prepolymer capabilities.
- Bio-Based Polyol Convergence:Castor oil-derived polyols combined with recycled content certifications are opening premium positioning in European automotive supply chains subject to Scope 3 emissions accounting.
Industry Challenges
- Formulation Chemist Shortage:Specialized expertise in reactive casting chemistry and curative selection is scarce as veteran technologists retire without sufficient apprenticeship pipeline replacement.
- OEM Qualification Timelines:Automotive chassis component approval cycles extending 18-24 months strain working capital for compounders awaiting volume commitments from tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Cast Elastomers Market |
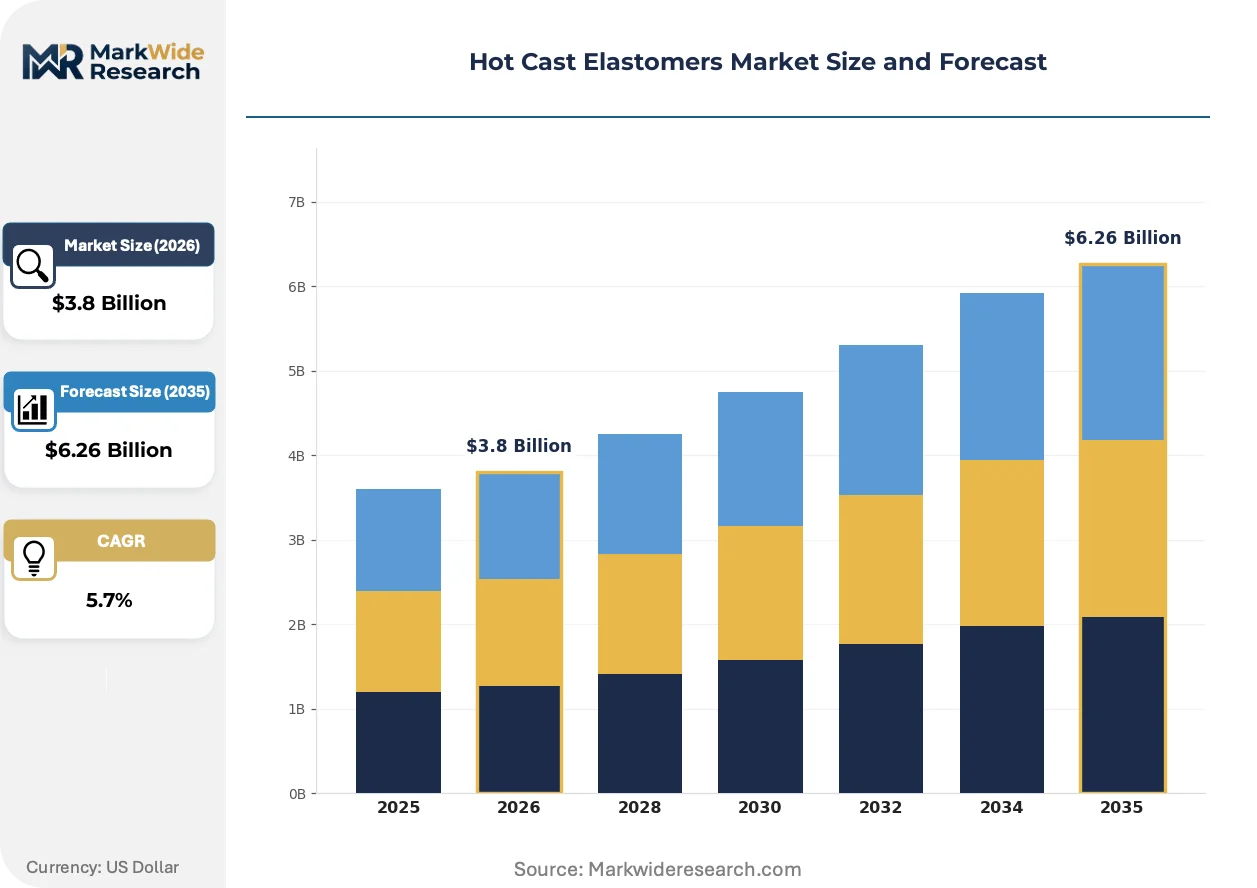
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Thermoplastic, Rubber Application: Aerospace, Automotive Parts, Industrial Equipment, Medical Devices End User: Manufacturers, OEMs, Construction, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Third-party Retailers |
| Companies Covered | BASF SE, Dow, Huntsman International LLC, Covestro AG, LANXESS, Wanhua Chemical Group, Mitsui Chemicals, Era Polymers Pty Ltd, Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Cast Elastomers Market Evolving Landscape
Reactive processing technologies and sustainability mandates are reconfiguring competitive advantage around emission control, bio-based feedstock integration, and thermal performance thresholds for electrified transportation.
Water-blown microcellular polyurethane systems are decomposing the traditional density-performance tradeoff in load-bearing industrial wheels. Mining equipment operators in Western Australia and Chile are adopting these formulations for haul truck tires and conveyor rollers where reduced weight improves fuel efficiency without sacrificing abrasion resistance. The technology is decomposing established supply relationships as regional compounders with blown-system expertise capture specification authority from legacy solid-cast suppliers.
REACH registration renewal deadlines for aromatic amine curatives are forcing European formulators toward aliphatic alternatives and bio-based polyol platforms. The industrial consequence is reformulation cost inflation and extended qualification cycles for abrasion-resistant rollers and seals. German machinery OEMs are responding by consolidating supplier bases to integrated producers with verified sustainable chemistry pipelines and ECHA-compliant substance portfolios.
Automotive tier suppliers are unbundling after-sales service contracts from initial component procurement, shifting toward performance-guaranteed supply agreements with penalty clauses for premature failure. This compresses risk onto cast elastomer compounders for chassis bushings and jounce bumpers in electric vehicle platforms. The pattern is most pronounced in California and Michigan where OEMs demand 100,000-cycle durability validation before contract award.
Hot Cast Elastomers Market Segmentation
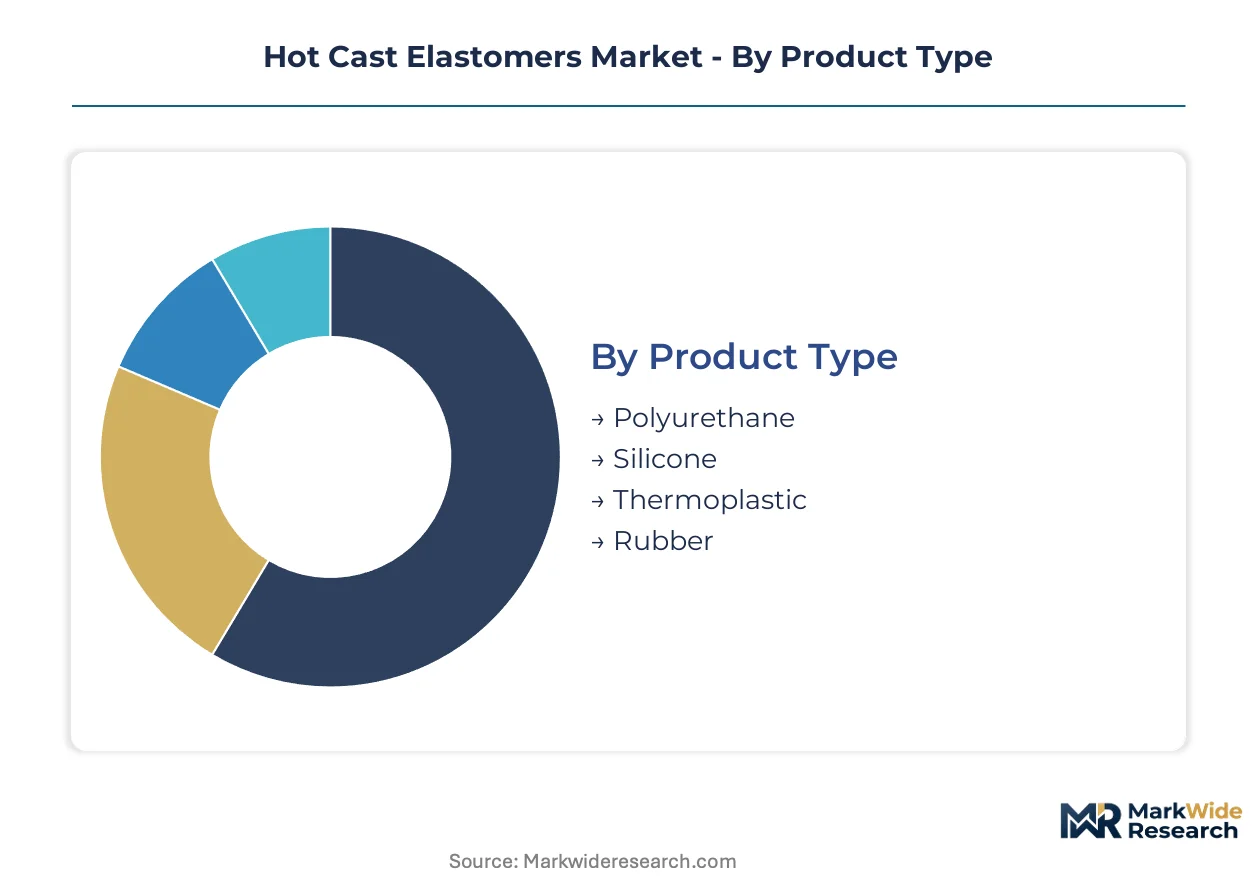
Formulation chemistry and curing technology create divergent performance envelopes across product categories. Application requirements from automotive electrification and medical implantation are compressing specification windows and reshaping segment priorities.
Product Type:
Thermoplastic and rubber alternatives are eroding volume positions in lower-performance tiers where processing speed trumps load-bearing durability.
- Polyurethane:Reactive casting of liquid prepolymers with curatives produces Shore hardness from 70A to 75D and tensile strength exceeding 25 MPa. Mining equipment operators in Western Australia and Chile specify these formulations for haul truck tires and conveyor rollers where abrasion resistance governs replacement cycles.
- Silicone:Platinum-cured systems achieve biocompatibility certification for implant-grade applications. Medical device manufacturers in Germany and Switzerland are qualifying these for catheter seals and surgical instrument grips where thermal stability above 150°C is mandatory.
- Thermoplastic:Injection-moldable variants capture consumer goods and light industrial equipment where rapid cycle times outweigh cast elastomer performance thresholds.
- Rubber:Conventional sulfur-cured formulations retain position in cost-sensitive sealing applications with moderate dynamic load requirements.
Polyurethane retains volume leadership; silicone holds the steepest expansion curve.
Application:
Electrification timelines are reordering qualification priorities across end-use categories as thermal performance thresholds climb.
- Automotive Parts:OEMs demand cast elastomers with thermal stability above 120°C for battery isolation systems and electric motor mounts. Tier suppliers in Michigan and California face 100,000-cycle durability validation requirements before contract award.
- Medical Devices:Implant-grade specifications require platinum-cured silicone systems with extractables testing and USP Class VI certification. German machinery OEMs are consolidating supplier bases to integrated producers with verified sustainable chemistry pipelines.
- Industrial Equipment:Abrasion-resistant polyurethane rollers and wheels serve material handling and mining retrofit cycles.
- Aerospace:Aliphatic polyurethane systems provide light stability for exterior seals and interior cabin components.
Automotive parts command the densest margin pools; medical devices are climbing the fastest.
End User:
Procurement centralization is compressing supplier counts as large-scale buyers consolidate specification authority.
- OEMs:Automotive and aerospace original equipment manufacturers drive formulation qualification through extended 18-24 month approval cycles. REACH registration renewal deadlines for aromatic amine curatives are forcing reformulation cost inflation onto compounders serving European OEM supply chains.
- Manufacturers:Industrial equipment producers in Germany's industrial belt specify high-performance formulations for abrasion-resistant rollers and wheels. These buyers concentrate demand in machinery clusters where performance-guaranteed supply agreements with penalty clauses are becoming standard.
- Construction:Infrastructure projects specify cast elastomer bearings and expansion joint seals with moderate performance requirements.
- Electronics:Electric vehicle battery pack manufacturers require thermal isolation components with dielectric properties.
OEMs retain specification authority; electronics represents the fastest-emerging demand vector.
Distribution Channel:
Technical complexity and qualification requirements are filtering channel viability across customer tiers.
- Direct Sales:Integrated producers with captive polyol supply deploy technical service teams for automotive and aerospace OEM qualification. BASF SE leverages captive adipic acid and MDI capacity to sustain these relationships across European automotive supply chains.
- Distributors:Regional compounders rely on distributor networks for mining and industrial equipment accounts in Australian and Canadian open-pit operations.
- Online Retail:Standard-grade formulations for maintenance and repair operations move through digital procurement platforms.
- Third-party Retailers:Consumer-accessible channels serve small-scale fabrication and prototyping demand.
Direct sales captures the highest-value contracts; distributors span the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders command pricing premiums through REACH-compliant formulations while US manufacturers absorb EPA compliance costs without equivalent margin recovery. This asymmetry reshapes procurement patterns across automotive supply chains.
Germany
Automotive OEMs in Stuttgart and Munich specify high-performance polyurethane bushings with 100,000-cycle validation. ECHA registration renewal deadlines for aromatic amine curatives are forcing reformulation toward aliphatic systems. The Ruhr industrial belt concentrates machinery manufacturers qualifying abrasion-resistant rollers from integrated suppliers with verified sustainable chemistry pipelines.
United States
EPA air toxics standards and anticipated OSHA isocyanate exposure rulemaking are accelerating investment in closed-mold systems. Michigan and California tier suppliers face compressed development cycles for electric motor mounts requiring thermal stability above 120°C. Detroit-area compounders anchor automotive qualification relationships through direct technical service deployment.
China
Wanhua Chemical Group's captive MDI and polyether polyol production dominates Asia-Pacific feedstock economics. MIIT industrial standards and dual carbon goals are tightening emissions protocols for casting operations. The Yangtze River Delta concentrates material handling equipment manufacturers scaling domestic logistics infrastructure with high-performance cast polyurethane.
India
Material handling equipment producers in Pune and Chennai are qualifying cast polyurethane for conveyor systems and forklift wheels. BIS standards and PLI scheme incentives support domestic manufacturing scale-up. The Maharashtra industrial corridor attracts compounders establishing regional formulation capabilities for mining and logistics retrofit demand.
Australia
Open-pit mining operators in Western Australia specify abrasion-resistant polyurethane rollers for haul truck tires as ore throughput intensifies. The country's national environmental regulator monitors VOC emissions from casting operations in Queensland and New South Wales. Perth-based distributors capture specification authority for replacement cycles in Pilbara iron ore operations.
Hot Cast Elastomers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated polyol producers sustaining margin buffers against compound-only specialists facing raw material volatility. The vendor base concentrates around three strategic tiers: backward-integrated chemical conglomerates with captive adipic acid and MDI capacity; differentiated system houses specializing in aliphatic polyurethane for medical and aerospace applications; and regional compounders serving mining and industrial equipment accounts through distributor networks. Dominant competitive moves include capacity expansion in bio-based polyol platforms and strategic partnerships for electric vehicle qualification programs.
Among integrated chemical conglomerates, BASF SE exemplifies the European archetype with captive supply chain control, while Wanhua Chemical Group anchors Asia-Pacific feedstock economics through in-house MDI production. Huntsman International LLC occupies a position within the differentiated system house tier, representing specialization in light-stable formulations for premium applications.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Huntsman International LLC |
| Covestro AG |
| LANXESS |
| Wanhua Chemical Group |
| Mitsui Chemicals |
| Era Polymers Pty Ltd |
| Tosoh Corporation |
| Others |
Value Network & Pricing Analysis
Aliphatic curative substitution for restricted aromatic amine systems is redrawing supply geography toward integrated European producers while inflating formulation costs for non-integrated compounders. This input transition simultaneously compresses margin buffers for specialists lacking captive polyol supply and concentrates pricing power with backward-integrated conglomerates.
Pricing Analysis
Configured-to-order pricing for automotive qualification programs commands substantial premiums over standard-grade mining and industrial formulations. Three-tier pricing structure across premium, standard, and economy levels separates implant-grade silicone systems from industrial polyurethane rollers and commodity rubber seals. Price differentiation rests on REACH compliance certification and volume scale, with OEM contract minimums insulating top-tier suppliers. Cost compression in standard industrial grades is intensifying because thermoplastic polyurethane substitutes capture speed-sensitive applications. Mining equipment buyers exhibit highest price sensitivity due to replacement-cycle procurement, while medical device manufacturers prioritize biocompatibility certification over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for European compounders sourcing MDI and specialty curatives from Chinese producers. Feedstock supply concentrates in China through Wanhua Chemical Group's captive production, Germany via BASF SE's integrated adipic acid operations, and the US through Huntsman International LLC's regional system houses. Raw material dependencies center on crude MDI, polyether polyols, and platinum-cure catalysts for silicone grades. Single-source vulnerability around Chinese MDI exports exposes non-integrated compounders to allocation risk during supply disruptions. Distribution runs through direct technical service teams for automotive OEM qualification and regional distributor networks for mining replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against thermoplastic polyurethane erosion in lower-load bearing tiers. Incumbents must differentiate through performance-guaranteed supply agreements that TPU suppliers cannot match.
For Market Incumbents: Consolidate supplier relationships with German automotive OEMs by accelerating aliphatic polyurethane qualification ahead of REACH aromatic amine deadlines. Deepen backward integration into bio-based polyol platforms to capture Scope 3 emissions accounting premiums in European supply chains. Capacity expansion in India serves mining and logistics retrofit demand while insulating against Chinese feedstock volatility.
For New Entrants and Emerging Players: After-sales service contract unbundling by automotive tier suppliers creates white-space for performance-guaranteed supply agreements with penalty clause expertise. Target medical device manufacturers in Switzerland requiring implant-grade platinum-cured silicone systems where incumbent concentration remains low. Establish formulation capabilities in Pune or Chennai to serve Indian material handling equipment qualification programs through direct technical partnership.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional compounders serving Australian mining replacement cycles through distributor networks. Long-term viability hinges on electric vehicle thermal stability specifications above 120°C that sustain cast elastomer relevance against TPU substitution. Watch OSHA isocyanate exposure rulemaking as inflection indicator for aliphatic system house valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polyols | Captures EU Green Deal compliance premiums from automotive OEMs facing Scope 3 accounting. |
| Aliphatic System Qualification Acceleration | Positions compounders ahead of OSHA isocyanate exposure rulemaking and REACH aromatic amine restrictions. |
| India Regional Formulation Buildout | Serves domestic logistics infrastructure scaling in Pune and Chennai industrial corridors. |
| Performance-Guaranteed Supply Agreements | Locks in automotive tier supplier contracts with 100,000-cycle durability validation requirements. |
| Closed-Mold System Capital Investment | Meets EPA air toxics standards while reducing VOC exposure liability in US manufacturing bases. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polyurethane formulation chemists, automotive Tier 1 procurement managers, mining equipment maintenance directors, and medical device regulatory affairs specialists. Secondary validation drew from ECHA substance registration databases, EPA air toxics compliance filings, SEC 10-K disclosures from integrated chemical producers, and ACC industry shipment statistics. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework modeled formulation chemistry tiers, application thermal requirements, end-user procurement centralization patterns, and regional regulatory compliance clusters. CAGRs were derived from segment-level volume trajectories weighted by price realization trends. Industry-specific inputs included electric vehicle platform thermal stability specifications, mining equipment replacement cycle intensities, and medical implant-grade certification timelines.
Underlying assumptions cover sustained automotive electrification penetration, stable crude MDI feedstock availability, and incremental REACH registration compliance costs, with deviation risk concentrated in OSHA isocyanate exposure rulemaking timing and thermoplastic polyurethane substitution acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market