
 Modified Silicone Fluids Market | 2026-2036
Modified Silicone Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Silicone Fluids Market Analysis
Personal care formulation is realigning toward high-performance silicone emulsions as cosmetic brands seek enhanced sensory profiles and extended wear properties. Dow leverages its integrated siloxane supply chain to sustain cost advantages across premium fluid grades. Shin-Etsu Chemical Co., Ltd. anchors its position through proprietary polymerization technology that dominates ultra-high-purity segments for semiconductor applications.
Modified silicone fluids consist of polydimethylsiloxane backbones with functional group substitutions—alkyl, aryl, amino, or polyether moieties—delivering tailored surface tension, thermal stability from -60°C to 300°C, and controlled compatibility with organic systems. Fluids and emulsions capture the largest volume share, with resins commanding superior margins in electronics conformal coating and automotive underhood applications. Construction-grade compounds face slower growth as building activity moderates in key European markets, while personal care emulsions accelerate on clean-label formulation trends.
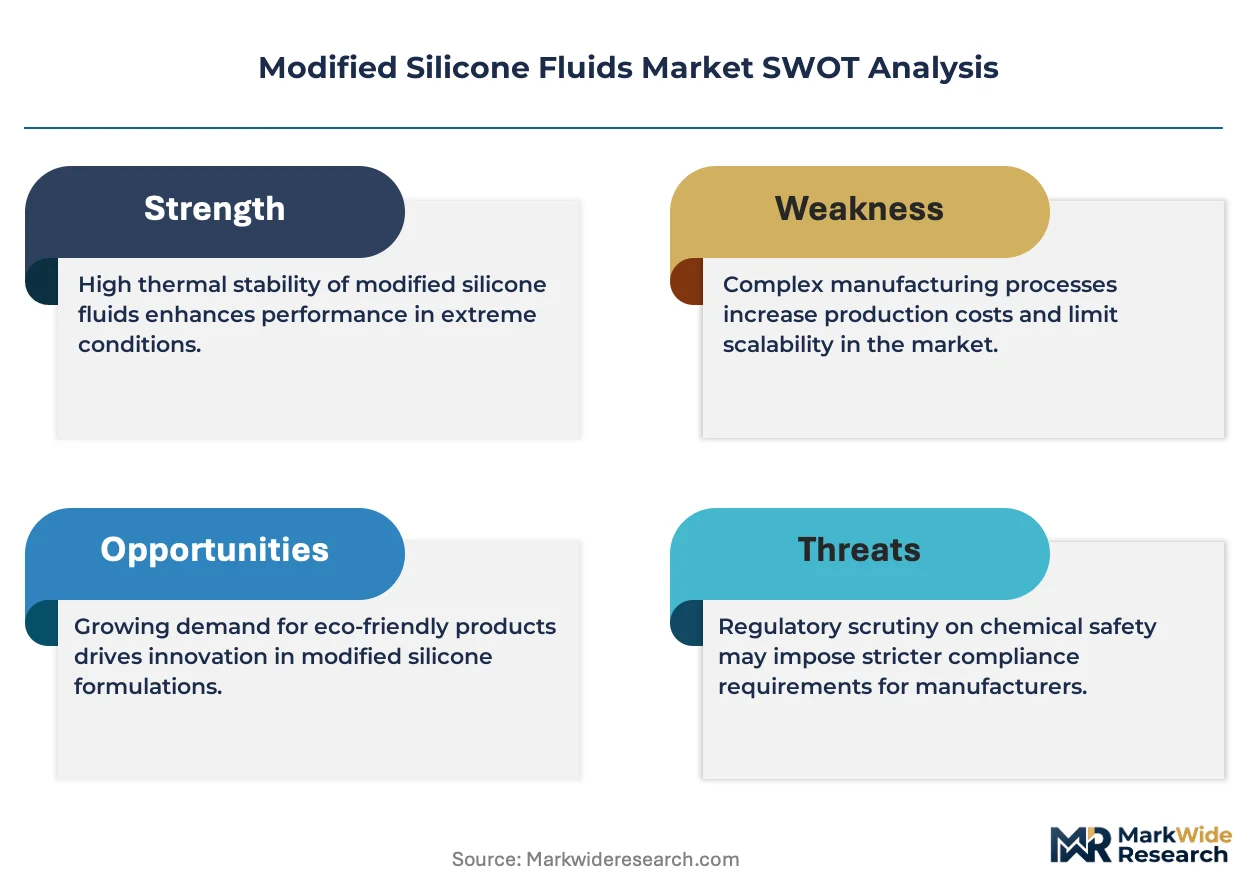
EPA oversees volatile organic compound limits affecting silicone solvent carriers in U.S. industrial coatings, while REACH registration requirements in Europe constrain import fluid compositions and drive reformulation costs. China's GB standards and SAMR oversight enforce consistent quality thresholds for silicone materials entering domestic electronics supply chains. Stakeholders must weigh regulatory compliance investments against the margin compression risk from bio-based silicone alternatives gaining technical viability.
Market Dynamics
Automotive electrification is restructuring demand patterns across silicone fluid applications, redirecting volume from traditional engine cooling toward battery thermal management and power electronics conformal coating. This shift compresses legacy automotive segments while opening high-specification niches requiring ultra-pure, thermally stable formulations.
Growth Catalysts
- EPA volatile organic compound limits:Tightening solvent carrier restrictions in U.S. industrial coatings are accelerating waterborne and high-solids silicone fluid adoption, particularly in automotive refinish applications.
- Semiconductor manufacturing expansion:Wafer fabrication facilities in Taiwan and South Korea are consuming escalating volumes of ultra-high-purity silicone fluids for photoresist processing and chemical mechanical planarization.
- EV battery thermal management:Liquid cooling systems for lithium-ion packs require specialty silicone fluids with dielectric stability across extreme temperature cycles, creating dedicated demand from cell manufacturers.
Market Restraints
- Siloxane raw material concentration:Four integrated chemical conglomerates control over three-quarters of upstream dimethylsiloxane supply, exposing formulators to oligopolistic pricing and allocation risk.
- REACH registration compliance costs:European Chemicals Agency substance dossier requirements impose six-figure euro expenditures per modified fluid variant, constraining product line breadth for mid-scale suppliers.
- Plant oil-derived surfactant substitution:Bio-based emollients from rapeseed and coconut feedstocks are capturing share in mass-market personal care applications where sensory performance specifications permit.
Strategic Opportunities
- India electronics manufacturing:Production-linked incentive schemes for semiconductor and mobile device assembly are attracting specialty chemical investments, with silicone fluid demand projected to track fab construction timelines.
- Two-fluid immersion cooling:Data center operators are piloting dielectric silicone formulations for direct-to-chip thermal management, displacing traditional air and water cooling architectures.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases in refrigeration and heat pump systems are creating openings for silicone-based working fluids with favorable global warming potential profiles.
Industry Challenges
- Semiconductor-grade purification expertise:Formulators lack sufficient personnel trained in parts-per-billion contamination control and cleanroom manufacturing protocols required for advanced node chip production.
- Multi-jurisdictional registration synchronization:Divergent substance notification timelines across EPA, ECHA, and China's Ministry of Ecology and Environment extend product launch cycles and inflate regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Silicone Fluids Market |
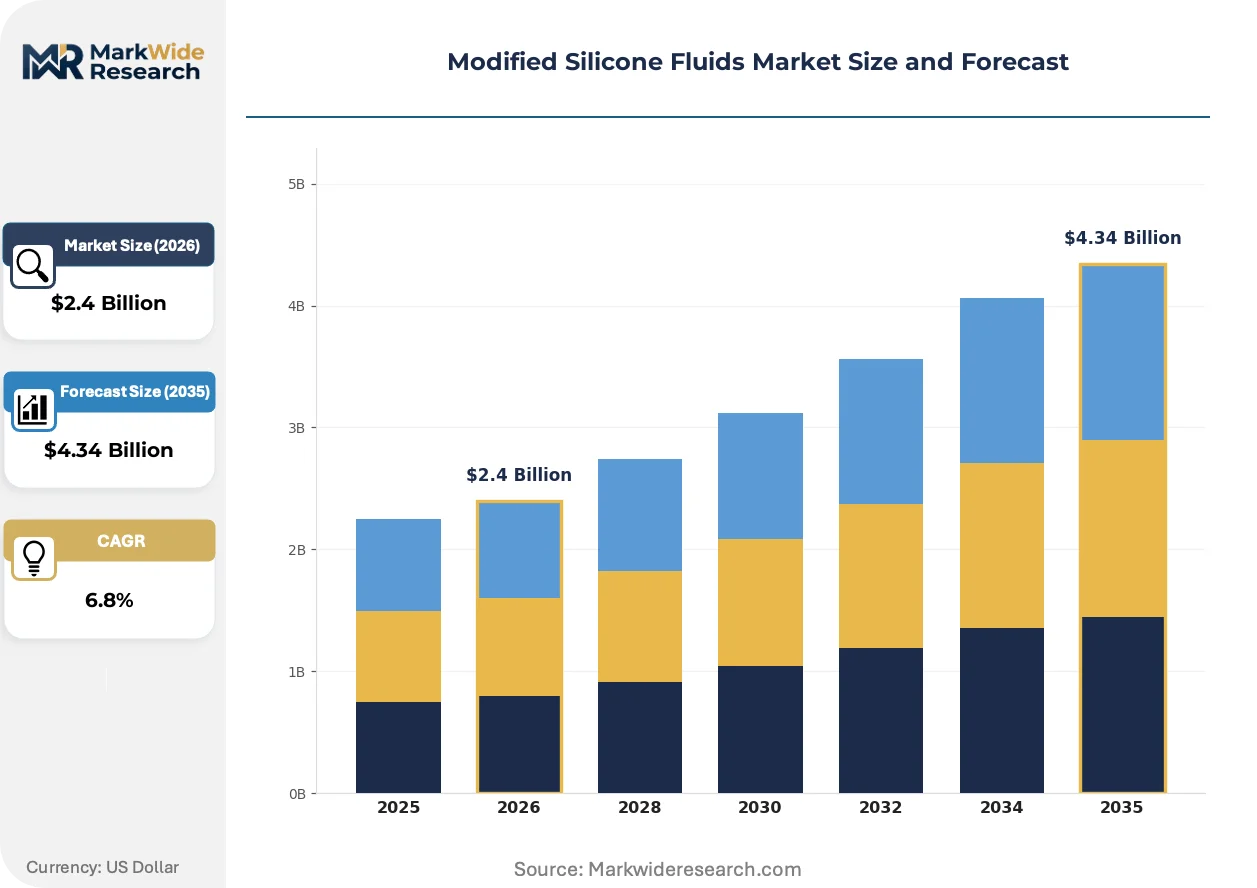
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Fluids, Resins, Compounds Application: Automotive, Personal Care, Construction, Electronics End User: Manufacturers, Consumers, Contractors, Retailers Distribution Channel: Online, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Dow, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials, Elkem ASA, Gelest Incorporated, Siltech Corporation, BRB International, KCC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Silicone Fluids Market Emerging Trajectories
Functional group engineering is enabling silicone fluids to bridge previously incompatible material systems, opening formulation possibilities in hybrid organic-inorganic composites. This capability expansion is redrawing competitive boundaries between specialty chemical suppliers and integrated materials science platforms.
Fluorosilicone copolymer technology is rewriting performance benchmarks for fuel system and aerospace applications. These materials deliver chemical resistance to aromatic hydrocarbons and jet fuels that unmodified polydimethylsiloxane cannot match. Tier-1 automotive suppliers are qualifying fluorosilicone grades for next-generation hydrogen fuel cell sealing and methanol-compatible fuel lines. The technology is compressing addressable market scope for conventional fluorocarbon elastomers in transportation fluid handling.
REACH authorization procedures for cyclic siloxanes are tightening purity specifications for personal care and medical device applications. Downstream formulators face reformulation mandates as D4, D5, and D6 compounds move toward restricted substance status. European cosmetics manufacturers are accelerating qualification of low-cyclic-content emulsions, while Asian exporters to EU markets are investing in distillation upgrades to maintain market access.
Specification-driven procurement is consolidating supplier relationships around full-service formulation partners capable of co-developing application-optimized grades. Personal care brands are reducing approved vendor lists from dozens to single-digit rosters, favoring suppliers with integrated emulsion manufacturing and regulatory documentation capabilities. This concentration is most pronounced in Western European and North American markets where clean-label and sustainability certification requirements multiply technical collaboration demands.
Modified Silicone Fluids Market Segmentation
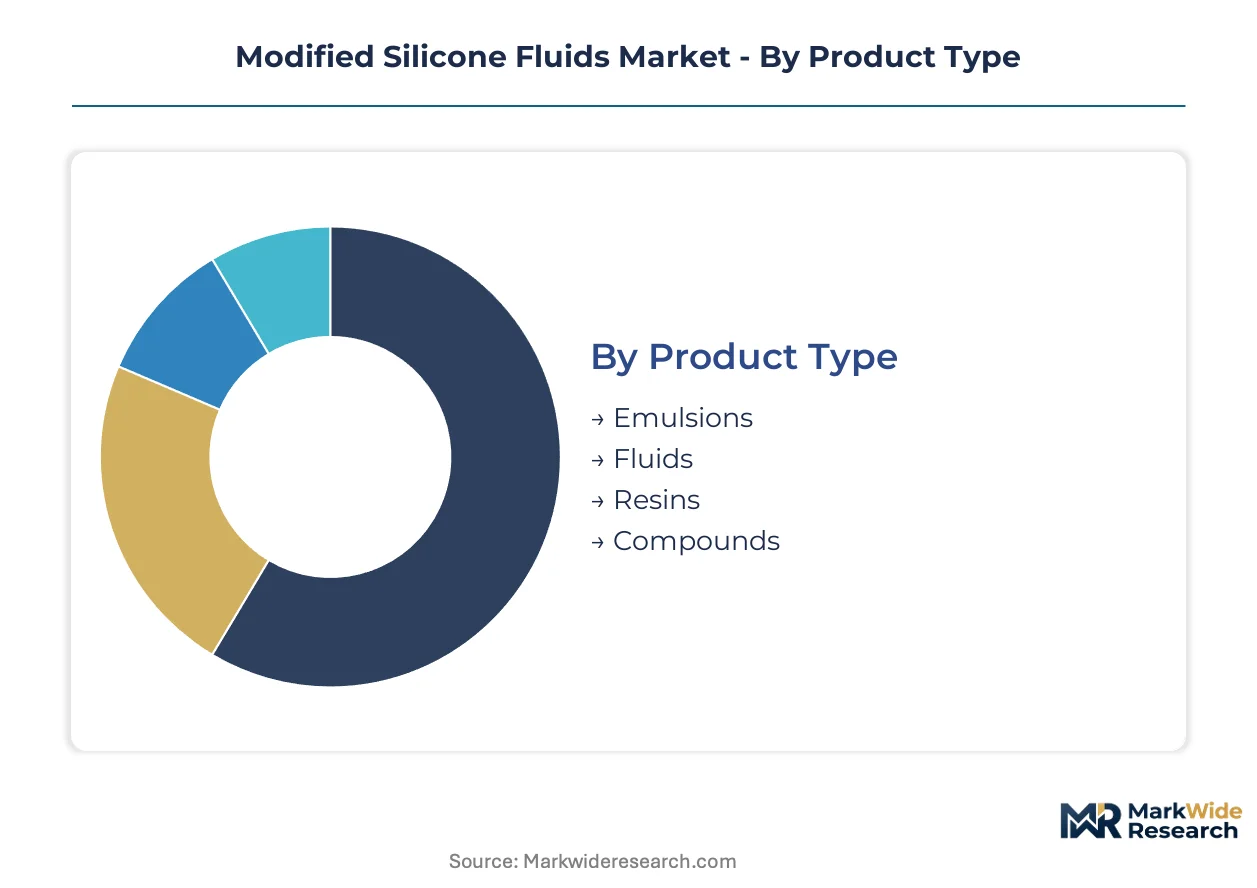
Modified silicone fluids span a spectrum from commodity emulsions to ultra-pure semiconductor grades. Segmentation reveals how functional group engineering and purity tiers partition value capture across end-use verticals.
Product Type:
Customization intensity varies sharply across this category, from standardized emulsion concentrates to application-engineered resins demanding co-development partnerships.
- Fluids:Polydimethylsiloxane backbones with alkyl, aryl, or polyether substitutions deliver tunable viscosity and thermal stability from -60°C to 300°C. Automotive electrification in Germany and South Korea is redirecting volume toward battery thermal management and power electronics conformal coating, compressing legacy engine cooling applications.
- Emulsions:Water-dispersed silicone systems enable personal care formulators to achieve specific sensory profiles without organic solvents. Clean-label trends in Western Europe are accelerating qualification of low-cyclic-content grades as REACH authorization tightens D4, D5, and D6 restrictions.
- Resins:Three-dimensional siloxane networks command superior margins in electronics conformal coating and automotive underhood applications requiring chemical resistance and dielectric stability.
- Compounds:Filler-reinforced silicone formulations serve construction sealing and industrial gasket applications where compression set resistance and weatherability specifications dominate procurement criteria.
Most installed capacity flows through Fluids. Expansion is steepest in Resins.
Application:
Margin structure inverts across this category, with automotive and electronics commanding specification premiums while construction faces cyclical pressure.
- Electronics:Ultra-high-purity silicone fluids enable photoresist processing and chemical mechanical planarization in wafer fabrication. Taiwan and South Korean fabs are consuming escalating volumes as advanced node production expands.
- Automotive:Electrification is restructuring demand from engine cooling toward battery thermal management and fuel cell sealing. Fluorosilicone copolymers are displacing conventional fluorocarbon elastomers in hydrogen-compatible fuel lines.
- Personal Care:Silicone emulsions provide extended wear properties and enhanced sensory profiles in color cosmetics and skin care. Specification-driven procurement is consolidating supplier relationships around full-service formulation partners.
- Construction:Building activity moderation in Germany and France is slowing volume growth for sealants and weatherproofing compounds. Procurement favors regional compounders with local technical service capabilities.
Electronics and Automotive concentrate value capture. Personal Care is gaining share fastest.
End User:
Technical collaboration intensity distinguishes this category, with manufacturers demanding co-development while retailers prioritize supply security.
- Manufacturers:Tier-1 automotive suppliers and electronics OEMs specify application-optimized grades requiring cleanroom manufacturing protocols and parts-per-billion contamination control. Multi-jurisdictional registration synchronization across EPA, ECHA, and China's MEE extends qualification timelines.
- Contractors:Construction applicators source through distribution networks emphasizing local technical support and just-in-time availability for project-based demand.
- Consumers:Direct purchases concentrate in premium personal care segments where clean-label and sustainability certifications influence brand selection.
- Retailers:Mass-market personal care chains are reducing approved vendor lists from dozens to single-digit rosters, favoring suppliers with integrated emulsion manufacturing and regulatory documentation capabilities.
Manufacturers absorb the majority of specialty grade volume. Retailers are consolidating supplier relationships most aggressively.
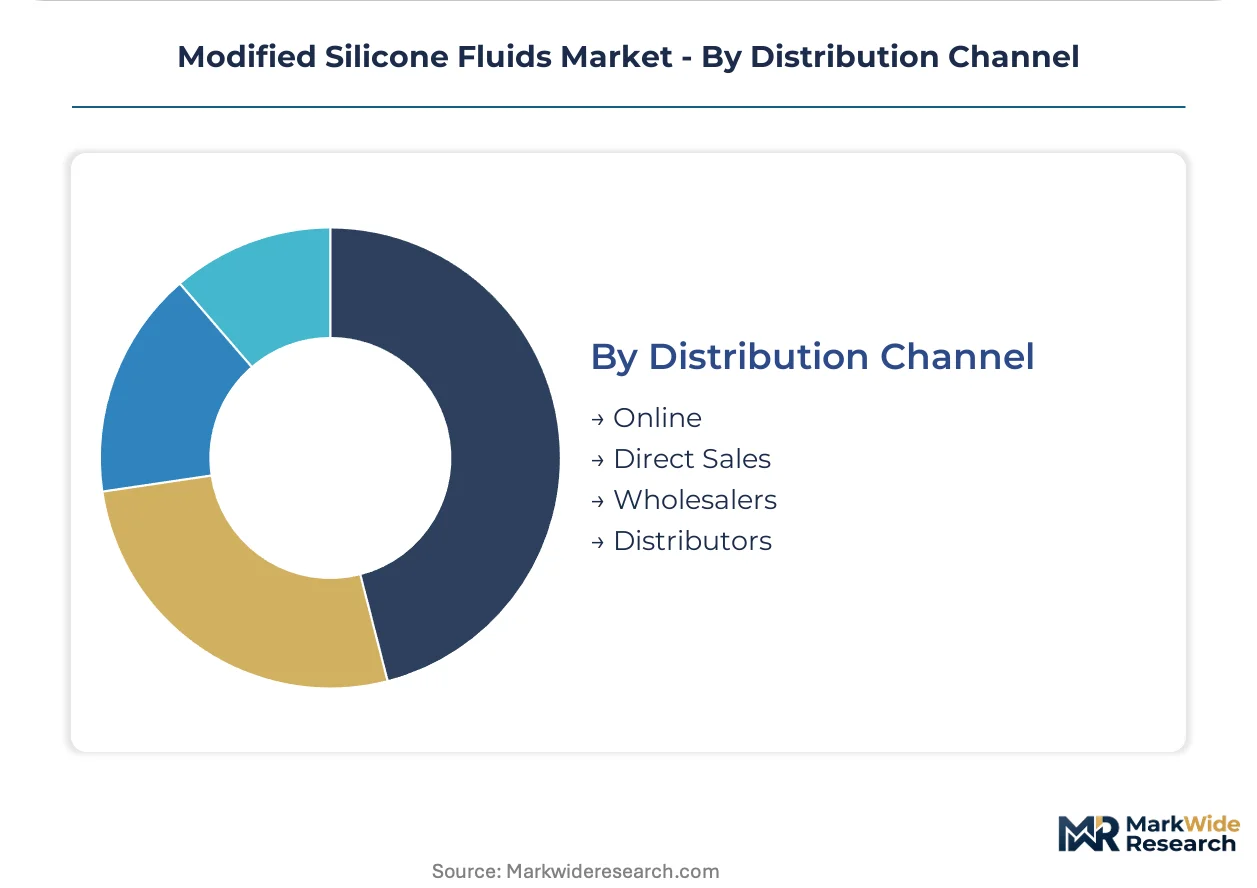
Distribution Channel:
Service intensity and order fragmentation define channel economics in this category.
- Direct Sales:Integrated silicone producers serve high-volume automotive and electronics manufacturers through dedicated technical account teams. Dow and Shin-Etsu leverage captive siloxane supply to sustain cost advantages across premium fluid grades.
- Distributors:Regional chemical distributors provide formulation support and inventory management for mid-scale personal care and construction customers. REACH registration costs constrain product line breadth for distributors serving European markets.
- Wholesalers:Construction-grade compounds flow through building material wholesalers emphasizing local availability and project-scale packaging.
- Online:E-commerce penetration concentrates in standardized emulsion concentrates and small-volume specialty grades where technical consultation requirements are minimal.
Direct Sales channels handle the highest-value specialty grades. Online is expanding fastest in standardized product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting modified silicone fluid manufacturing toward jurisdictions with streamlined chemical registration frameworks. Producers are optimizing plant locations to minimize REACH compliance expenditures while maintaining proximity to electronics and automotive demand clusters.
China
GB standards and SAMR oversight enforce consistent quality thresholds for silicone materials entering domestic electronics supply chains. The country's dual carbon goals are accelerating demand for thermally stable fluids in EV battery production. Yangtze River Delta fabrication facilities consume specialty grades for semiconductor and display manufacturing.
Germany
Automotive electrification in Baden-Württemberg and Bavaria is redirecting volume toward battery thermal management applications. ECHA substance dossier requirements impose six-figure euro expenditures per modified fluid variant, constraining product line breadth. REACH authorization procedures for cyclic siloxanes are tightening purity specifications for personal care formulations.
United States
EPA volatile organic compound limits are accelerating waterborne and high-solids silicone fluid adoption in automotive refinish applications. The Inflation Reduction Act incentives for domestic battery manufacturing are expanding demand for dielectric thermal management fluids. Texas and Michigan host concentrated processing capacity serving North American electronics and automotive OEMs.
South Korea
Wafer fabrication facilities in Gyeonggi Province and Seoul Capital Area consume escalating volumes of ultra-high-purity silicone fluids for photoresist processing. MFDS oversight aligns with international purity benchmarks for medical device applications. Samsung and SK Hynix supply chains drive specification requirements for chemical mechanical planarization fluids.
India
Production-linked incentive schemes for semiconductor and mobile device assembly are attracting specialty chemical investments. BIS certification requirements are harmonizing with international standards for electronics-grade materials. Karnataka and Tamil Nadu fab construction timelines are projected to track silicone fluid demand growth.
Modified Silicone Fluids Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated producers add specialty fluid lines to capture automotive electrification demand. The vendor base separates into three tiers: multinational chemical conglomerates with captive siloxane supply, regional formulators with application expertise, and niche specialists serving semiconductor purity requirements. Strategic archetypes include backward-integrated siloxane producers, formulation-focused mid-scale suppliers, and ultra-high-purity specialists. M&A activity and technology licensing partnerships represent the dominant competitive moves as firms seek to bridge capability gaps in cleanroom manufacturing protocols.
Within the integrated chemical tier, Dow and Wacker Chemie AG exemplify producers with in-house control over upstream dimethylsiloxane supply. Shin-Etsu Chemical Co., Ltd. occupies a position representing ultra-high-purity specialists serving semiconductor fabrication requirements. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning in a market where purity tiers and regulatory documentation capabilities determine supplier selection.
| Leading Market Players |
|---|
| Dow |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials |
| Elkem ASA |
| Gelest Incorporated |
| Siltech Corporation |
| BRB International |
| KCC Corporation |
| Others |
Supply Flow & Price Mechanics
Dimethylsiloxane monomer spot indices cascade through modified silicone fluid supply chains into sharply tiered pricing bands, with semiconductor-grade ultra-purity commanding multiples over construction-grade emulsions as oligopolistic upstream concentration transmits into downstream margin capture.
Pricing Analysis
Distributor markups of 15-25% separate bulk fluid concentrate prices from formulated emulsion delivered costs to personal care compounders. Three-tier pricing structure across semiconductor-grade, automotive-specification, and industrial-standard levels reflects purity certification and cleanroom manufacturing overhead. Cost compression in industrial-grade segments stems from bio-based surfactant substitution in mass-market personal care. Tier-1 automotive OEMs exhibit lowest price sensitivity due to co-development partnerships and qualification lock-in effects.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Samsung, SK Hynix, and EV battery manufacturers in South Korea and China. Upstream dimethylsiloxane production concentrates in Germany, China, and Japan, drawing from methyl chloride and silicon metal feedstocks. Siloxane raw material dependencies rest on chlorosilane intermediates and high-purity silicon metal sourcing. Single-source vulnerability from four integrated conglomerates controlling upstream supply creates allocation risk during demand surges. Distribution runs through regional chemical distributors for mid-scale personal care and construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified silicone fluids function as a stable compounder anchored by irreplaceable thermal management demand from semiconductor and EV battery manufacturing expansion.
For Market Incumbents: Deepen backward integration into siloxane monomer production to defend margin position against oligopolistic raw material pricing. Prioritize cleanroom capacity expansion in Taiwan and South Korea to capture semiconductor-grade specification premiums. Lock in long-term offtake agreements with EV battery cell manufacturers before qualification cycles extend. For New Entrants and Emerging Players: Begin with fluorosilicone copolymer specialties for hydrogen fuel cell sealing applications where incumbent qualification gaps persist. Target India's emerging electronics manufacturing clusters ahead of fab construction completion. Pursue co-development partnerships with Tier-2 automotive suppliers seeking second-source qualification for thermal management fluids. For Investors and Strategic Acquirers: Asymmetric upside sits with ultra-high-purity specialists possessing semiconductor cleanroom protocols and ECHA registration dossiers. Five-to-ten-year viability hinges on automotive electrification and advanced node chip production sustaining specialty grade demand. Monitor EU F-Gas Regulation implementation pace as inflection signal for silicone-based working fluid substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomer | Captive methyl chloride and silicon metal supply insulates margin from Dow, Wacker, and Shin-Etsu pricing power. |
| Cleanroom Manufacturing Scale-Up | Parts-per-billion contamination control capability unlocks Taiwan and South Korean wafer fabrication facility contracts. |
| REACH Registration Dossier Investment | ECHA substance authorization maintains European personal care and medical device market access as cyclic siloxane restrictions tighten. |
| Fluorosilicone Copolymer R&D Partnership | Hydrogen fuel cell sealing qualification with Hyundai and Toyota displaces conventional fluorocarbon elastomer incumbents. |
| India Electronics Manufacturing Joint Venture | Production-linked incentive alignment with Karnataka and Tamil Nadu fab construction timelines captures emerging demand. |
Methodological Framework
Bottom-up electronics and automotive OEM demand modeling reconciled against top-down siloxane producer capacity tracking forms the analytical core of this study. Primary interviews with silicone fluid plant managers, procurement leads at semiconductor fabs, personal care formulation chemists, and automotive thermal management engineers combined with secondary validation from ECHA substance registrations, EPA solvent emission filings, and customs trade data. Top-down triangulation against ACC and Cefic chemical industry reports verified volume estimates.
Input-output matrices linking methyl chloride and silicon metal feedstock availability to fluid grade production capacity generated volume projections across the analysis window. Segmentation dimensions modeled include purity tier, functional group substitution chemistry, end-use vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating EV battery production forecasts and wafer fabrication capacity expansion timelines. Forecast inputs encompassed REACH authorization timelines for cyclic siloxanes and EPA volatile organic compound limit phase-in schedules.
Several conditions sit outside the modeled scope, including unforeseen bio-based silicone breakthroughs achieving cost parity and abrupt automotive platform standardization eliminating specification diversity. Forecasts reflect base-case assumptions regarding sustained semiconductor capital expenditure and EV adoption trajectories. Periodic stress-testing of base assumptions is recommended against battery chemistry shifts and alternative thermal management technologies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
High Temperature Elastomers Market