
 Elastic Laminates Market | 2026-2036
Elastic Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Elastic Laminates Market Analysis
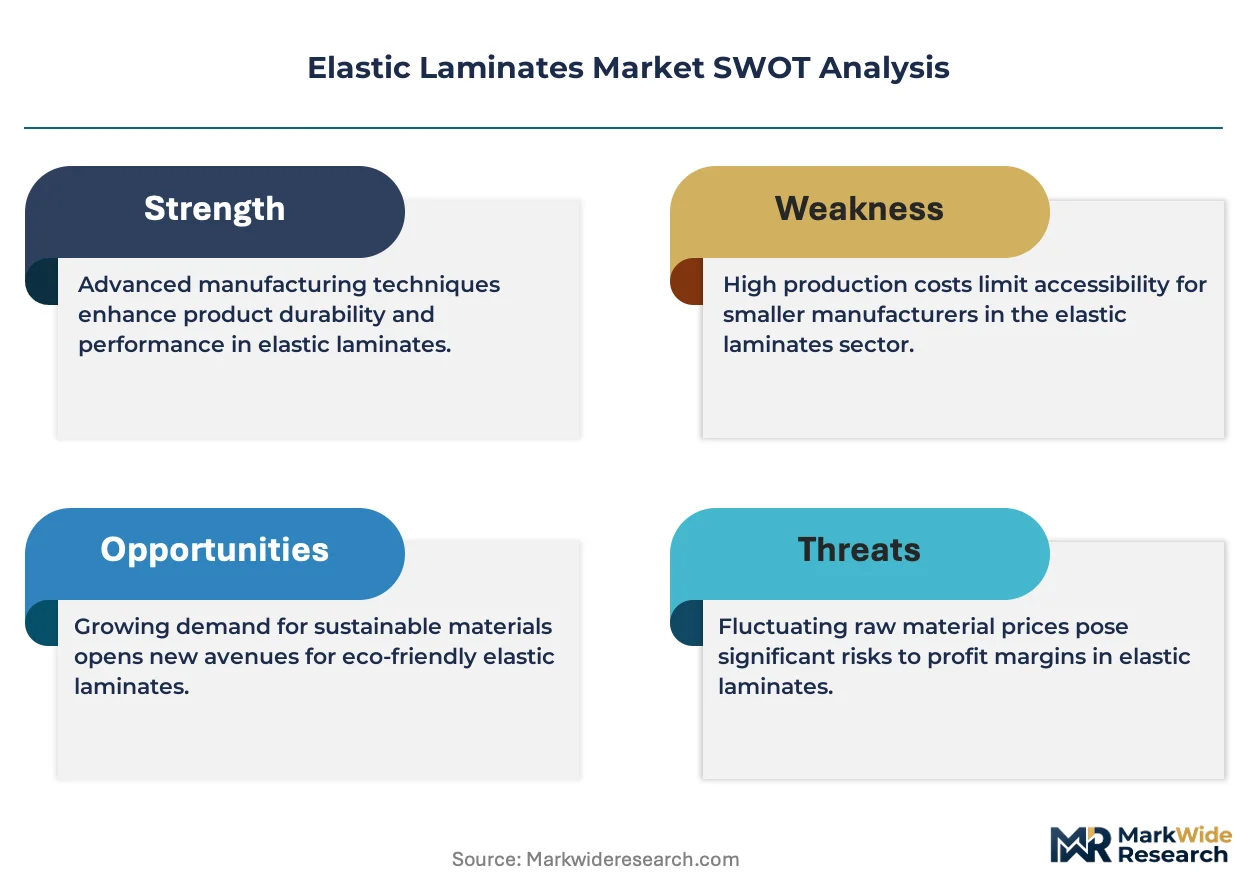
Medical-grade specification tiers are redrawing competitive boundaries in elastic laminates. Berry Global Group leverages backward integration into polymer resin production to control input costs for breathable film substrates. Tredegar Corporation anchors North American supply through specialized extrusion capacity for hygiene and medical applications. Kraton Corporation differentiates via styrenic block copolymer formulations that deliver elastic recovery in thin-gauge constructions.
Elastic laminates bond stretchable polymer layers to nonwoven or woven substrates through extrusion, adhesive bonding, or heat sealing to create fabrics that recover shape after deformation. Non-woven laminates dominate hygiene applications where softness and fluid management outweigh durability requirements. Coated laminates command margin pools in medical end uses where ISO 10993 biocompatibility certification creates qualification barriers for new entrants. Composite laminates represent the fastest-growing product type as automotive seating and interior panel applications demand multi-functional performance from single substrates.
FDA biocompatibility guidance and REACH substance restrictions in Europe constrain material choices for medical and consumer contact applications. EPA emissions standards for solvent-based adhesive processes push manufacturers toward hot-melt and reactive adhesive bonding technologies. Stakeholders must monitor evolving ECHA candidate list additions for substances used in polyurethane and PVC laminate formulations that could trigger reformulation cycles.
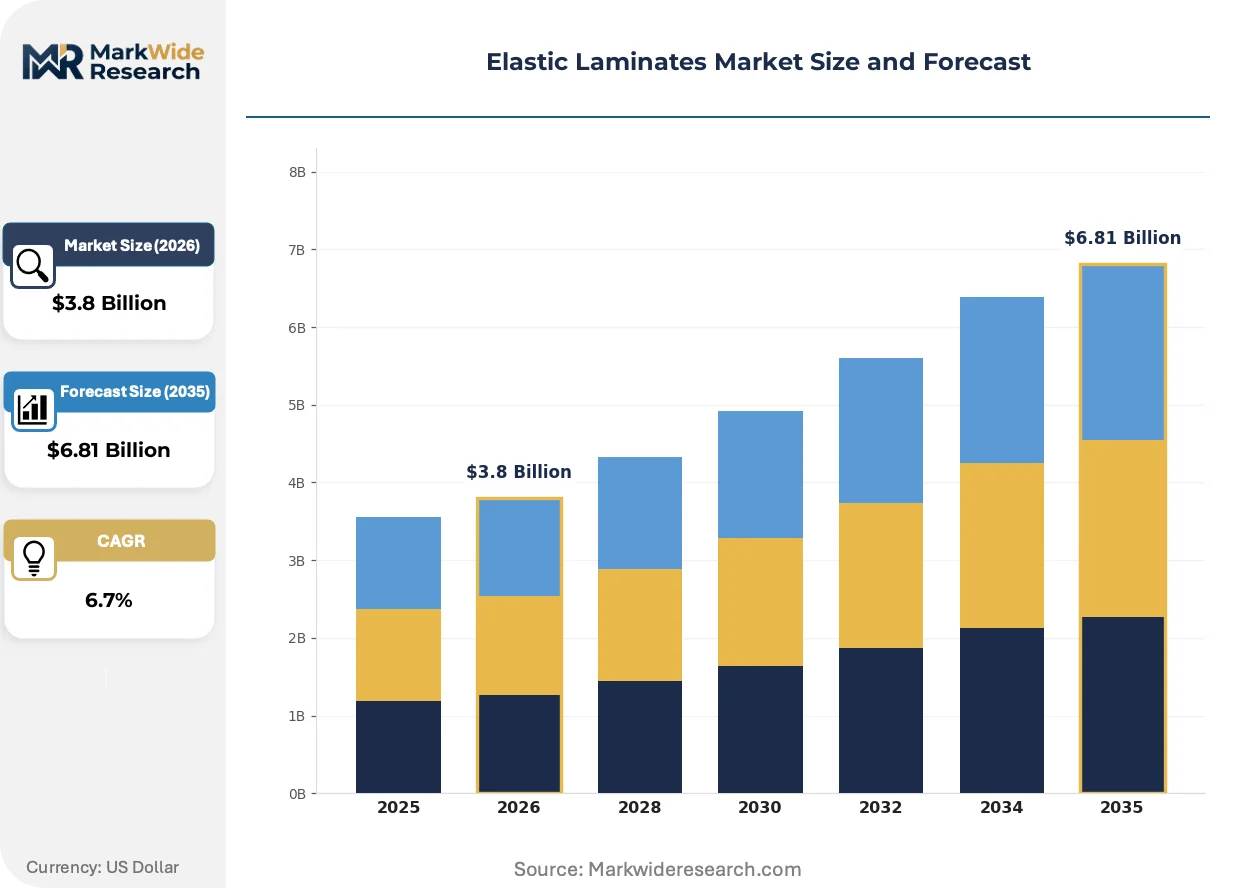
Market Dynamics
REACH substance restrictions and FDA biocompatibility guidance are compressing formulation freedom for medical-grade elastic laminates while simultaneously erecting qualification barriers that favor incumbent producers with certified supply chains.
Growth Catalysts
- ISO 10993 Certification Requirements:Medical device OEMs in Germany and the United States now mandate biocompatibility documentation for surgical drape substrates, locking in qualified laminate suppliers and extending contract durations.
- Automotive Interior Panel Specifications:Multi-functional composite laminates that combine acoustic dampening with elastic recovery are displacing separate substrate layers in seating and headliner assemblies across German and Chinese OEM supply chains.
- Hot-Melt Adhesive Conversion:EPA emissions standards for solvent-based bonding processes are accelerating capital redeployment toward reactive adhesive systems that eliminate volatile organic compound exposure in hygiene product manufacturing.
Market Restraints
- Styrenic Block Copolymer Feedstock Concentration:Specialty elastomer supply concentrates among a limited set of polymer producers, creating input cost volatility for thin-gauge elastic recovery formulations.
- ECHA Candidate List Expansion Risk:Polyurethane and PVC laminate chemistries face recurring reformulation cycles as REACH adds substances of very high concern, forcing qualification retesting and inventory write-downs.
- Mechanical Recycling Incompatibility:Multi-layer bonded constructions resist standard thermoplastic reprocessing, exposing hygiene and medical laminate producers to extended producer responsibility fees in EU member states.
Strategic Opportunities
- Underpenetrated Wound Care Applications:Silicone-adhesive elastic laminates for advanced wound dressing fixation remain undersupplied in outpatient and home care channels across China and India.
- EU Green Deal Procurement Mandates:Public hospital systems in France and Italy are incorporating recycled content thresholds into surgical drape tender specifications, creating first-mover advantage for laminate producers with certified circular feedstock.
- Bio-Based Polyurethane Convergence:Plant-derived diisocyanate chemistry combined with mechanical recycling infrastructure is opening qualification pathways for medical-grade laminates in Nordic markets with carbon-neutral procurement targets.
Industry Challenges
- Multi-Site Certification Coordination:ISO 13485 quality management system audits across extrusion, adhesive bonding, and finishing operations require specialized regulatory affairs personnel that mid-cap laminate producers struggle to retain.
- Legacy Solvent System Depreciation:Capital equipment for solvent-based adhesive lines faces accelerated obsolescence as EPA enforcement tightens, stranding unamortized investments for producers with delayed technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastic Laminates Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Laminates, Non-Woven Laminates, Coated Laminates, Composite Laminates Material: Polyester, Polyurethane, Polyethylene, PVC End Use: Textiles, Medical, Automotive, Packaging Technology: Extrusion, Adhesive Bonding, Heat Sealing, Coating |
| Companies Covered | Berry Global Group, Tredegar Corporation, Kraton Corporation, Mondi Group, Pantex International, Golden Phoenix Fiberwebs, Aplix, Schweitzer-Mauduit International, Kimberly-Clark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastic Laminates Market Emerging Trajectories
Bonding technology selection is splitting the competitive field between capital-intensive reactive systems and flexible hot-melt platforms, while regulatory chemistry constraints and buyer consolidation reshape value capture.
Reactive polyurethane adhesive technology is bifurcating the medical laminate supply base. These systems deliver bond strength and breathability in thin-gauge constructions that meet ISO 10993 cytotoxicity thresholds. German and US surgical drape OEMs are adopting at pace, with qualification cycles compressing from 18 to 12 months. The technology is bifurcating margin pools toward producers with in-house adhesive formulation capability and certified cleanroom coating capacity.
ECHA REACH candidate list additions for isocyanates and plasticizers are forcing laminate producers into defensive formulation archives. Industrial consequence includes dual-track inventory management and customer notification protocols for affected product lines. Medical-grade coated laminates face the tightest constraints, with producers in the Netherlands and Belgium accelerating substitution testing for aliphatic polyurethane alternatives.
Automotive seating procurement is consolidating specification authority at Tier 1 integrators with direct OEM relationships. This concentration is displacing fragmented converter networks that historically supplied cut-and-sew operations. Long-term supply agreements with volume commitments and technical co-development clauses are replacing transactional spot purchasing. The shift is most visible in German and Chinese automotive supply chains where platform standardization across vehicle lines amplifies buyer leverage.
Elastic Laminates Market Segmentation
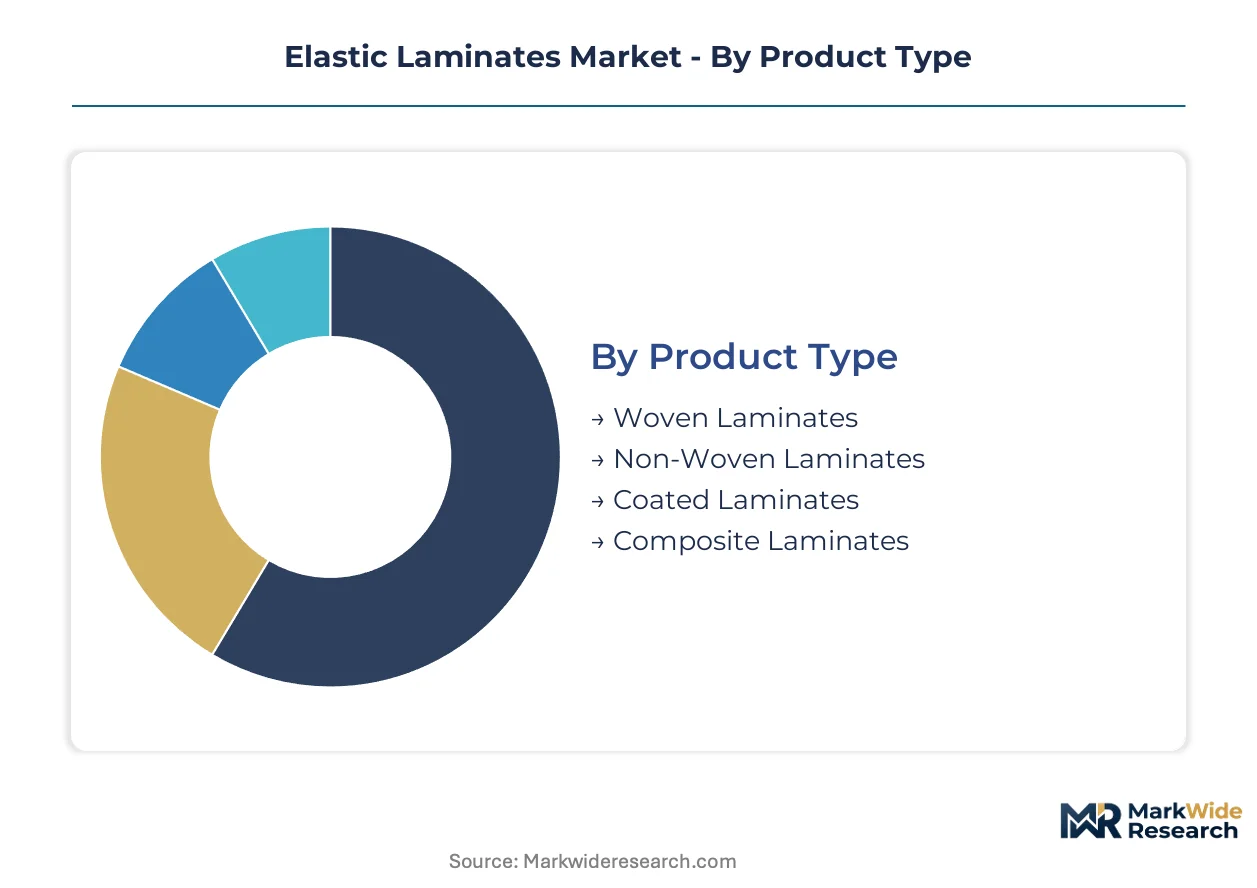
Segmentation in elastic laminates reveals how technical specifications and regulatory requirements fragment supply chains across end-use verticals. Material choices and bonding technologies determine qualification pathways and margin structures for producers serving hygiene, medical, and automotive OEMs.
Product Type:
Non-woven laminates dominate domestic procurement in Germany and the United States where hygiene manufacturers anchor volume, while coated and composite grades concentrate in export-oriented medical and automotive supply chains.
- Non-Woven Laminates:These constructions bond elastic films to spunbond or meltblown substrates, delivering softness and fluid management for disposable hygiene products. Demand concentrates in German and US diaper and feminine care manufacturing where FDA and REACH compliance requirements lock in qualified suppliers. ISO 10993 certification barriers extend contract durations and protect incumbent margins.
- Composite Laminates:Multi-layer constructions integrate acoustic dampening, elastic recovery, and thermal stability for automotive seating and interior panels. German and Chinese OEM supply chains specify these substrates for platform-standardized vehicle lines, displacing separate material layers. Technical co-development clauses in long-term agreements concentrate procurement at Tier 1 integrators with direct OEM relationships.
- Woven Laminates:Elastic polymers bond to woven textile substrates for applications requiring dimensional stability and durability. Industrial textile manufacturers in Italy and Turkey specify these for performance apparel and technical applications.
- Coated Laminates:Surface-coated constructions command premium positioning in medical end uses where biocompatibility certification creates qualification barriers. REACH substance restrictions and FDA guidance constrain formulation freedom while protecting certified producers.
Non-woven laminates hold the largest share; momentum sits with composite laminates as automotive interior specifications consolidate.
Material:
Polyurethane and polyester grades concentrate in medical and automotive export channels where REACH and FDA compliance requirements drive specification authority, while polyethylene and PVC serve cost-sensitive domestic hygiene and packaging applications.
- Polyurethane:Aliphatic polyurethane formulations deliver elastic recovery and biocompatibility for thin-gauge medical laminates. ECHA candidate list additions for isocyanates force substitution testing among Dutch and Belgian producers, accelerating plant-derived diisocyanate chemistry development for Nordic carbon-neutral procurement targets.
- Polyester:PET-based elastic laminates provide thermal stability and mechanical strength for automotive seating and industrial textile applications. German OEM specifications favor recycled content integration, aligning with EU Green Deal procurement mandates in French and Italian hospital systems.
- Polyethylene:PE elastic films dominate hygiene applications where cost optimization outweighs durability requirements. Berry Global Group's backward integration into polymer resin production controls input costs for breathable film substrates.
- PVC:Plasticized PVC laminates face recurring reformulation cycles as REACH adds substances of very high concern, forcing inventory management protocols and customer notification systems for affected product lines.
Polyurethane captures the steepest expansion trajectory in medical-grade specifications; polyethylene maintains volume leadership in hygiene procurement.
End Use:
Medical and automotive applications concentrate specification authority among German and Chinese OEMs and device manufacturers, while textiles and packaging fragment across regional converter networks.
- Medical:Surgical drape and wound care substrates require ISO 10993 cytotoxicity certification and ISO 13485 quality management systems. German and US device OEMs mandate biocompatibility documentation, locking in qualified laminate suppliers. Silicone-adhesive elastic laminates for advanced wound dressing fixation remain undersupplied in outpatient and home care channels across China and India.
- Automotive:Seating and interior panel specifications demand multi-functional performance combining acoustic dampening with elastic recovery. Procurement consolidates at Tier 1 integrators in German and Chinese supply chains, displacing fragmented converter networks.
- Textiles:Performance apparel and technical textile applications specify elastic laminates for stretch recovery and shape retention. Italian and Turkish manufacturers drive regional demand.
- Packaging:Flexible packaging applications utilize elastic laminates for puncture resistance and seal integrity. Food contact compliance requirements vary across EU member state implementations.
Medical commands premium margin pools; automotive shows the fastest volume scaling as platform standardization amplifies buyer leverage.
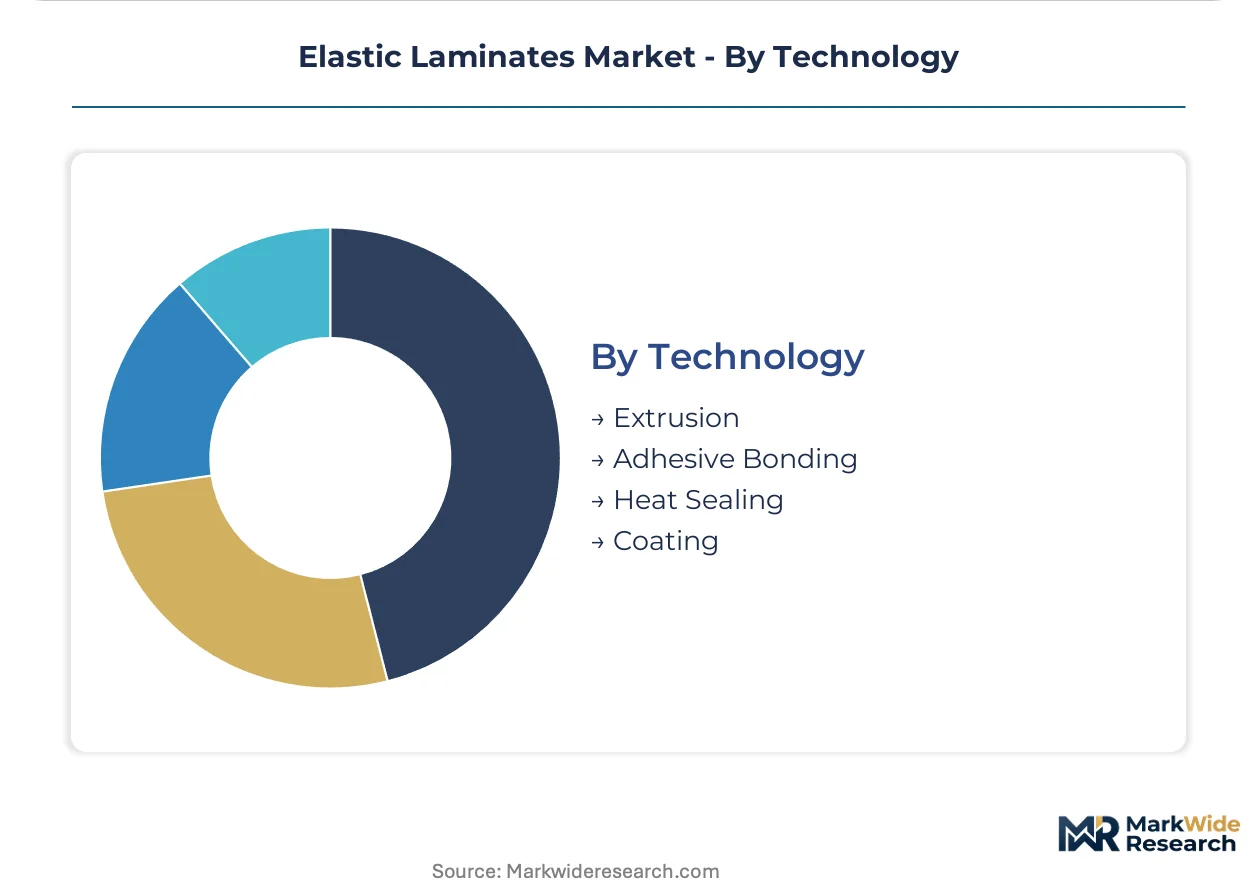
Technology:
Extrusion and adhesive bonding technologies concentrate in high-volume hygiene and medical supply chains with capital-intensive equipment requirements, while heat sealing and coating serve specialized applications with lower scale thresholds.
- Extrusion:Cast film and blown film extrusion of elastic polymers onto nonwoven substrates dominates hygiene manufacturing. Tredegar Corporation anchors North American supply through specialized extrusion capacity.
- Adhesive Bonding:Hot-melt and reactive polyurethane adhesive systems displace solvent-based processes under EPA emissions standards. Reactive systems deliver bond strength and breathability for ISO 10993-certified medical laminates, bifurcating margin toward producers with in-house formulation capability.
- Heat Sealing:Thermal bonding of elastic layers suits applications requiring clean, adhesive-free interfaces. Medical device manufacturers specify these for sensitive skin contact layers.
- Coating:Direct coating of elastic polymers onto textile substrates enables precise gauge control and surface modification. Cleanroom coating capacity creates qualification barriers for medical-grade production.
Adhesive bonding holds the largest installed base; reactive polyurethane systems gain share fastest as qualification cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty extrusion capacity concentrates in Germany and the United States where hygiene OEMs anchor procurement volumes. Automotive supply chains in China and medical device clusters in Belgium and the Netherlands drive specification complexity.
United States
Hygiene product manufacturers in Wisconsin and North Carolina consume breathable film laminates for diaper and feminine care applications. EPA emissions standards accelerate hot-melt adhesive conversion away from solvent-based bonding systems. Tredegar Corporation anchors North American supply through specialized extrusion capacity serving medical and hygiene end uses.
Germany
Automotive OEMs specify multi-functional composite laminates for seating and interior panels across platform-standardized vehicle lines. REACH substance restrictions constrain polyurethane and PVC formulation choices for medical-grade applications. The Rhine-Ruhr industrial corridor hosts laminate producers serving surgical drape OEMs with ISO 10993-certified substrates.
China
Domestic automotive production drives elastic laminate demand for seating assemblies and headliner components. GB standards and dual carbon goals shape material selection criteria for interior panel specifications. Yangtze River Delta manufacturing clusters supply laminate converters for both domestic consumption and export-oriented medical device assembly.
Belgium
Medical-grade coated laminate production serves wound care and surgical drape OEMs requiring ISO 13485 quality management systems. ECHA candidate list additions for isocyanates force substitution testing among producers. The Antwerp chemical cluster supports aliphatic polyurethane development for Nordic carbon-neutral procurement targets.
Netherlands
Rotterdam-area converters supply elastic laminates to European hygiene and medical device supply chains. EU Green Deal procurement mandates in neighboring France and Italy create recycled content requirements for hospital tender specifications. Dutch producers accelerate plant-derived diisocyanate chemistry development to capture first-mover advantage in circular feedstock certification.
Elastic Laminates Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the elastic laminates supply base. The market exhibits tiered concentration with global resin producers and specialized converters occupying distinct margin pools. Three archetypes dominate: backward-integrated polymer producers controlling input costs, specialized extrusion houses with certified medical capacity, and regional converters serving hygiene spot markets. Competitive moves center on reactive adhesive technology licensing and ISO 10993 certification acquisition to lock in medical OEM contracts.
Among North American fabricators, Berry Global Group and Tredegar Corporation exemplify scale-driven positioning with captive resin production and specialized extrusion assets respectively. Kraton Corporation represents the formulation-specialist archetype with styrenic block copolymer expertise. These three occupy positions across the technology-cost spectrum, with Berry Global Group anchoring the integrated-resin tier, Tredegar Corporation sitting within the dedicated-extrusion segment, and Kraton Corporation exemplifying the polymer-chemistry differentiation vector.
| Leading Market Players |
|---|
| Berry Global Group |
| Tredegar Corporation |
| Kraton Corporation |
| Mondi Group |
| Pantex International |
| Golden Phoenix Fiberwebs |
| Aplix |
| Schweitzer-Mauduit International |
| Kimberly-Clark |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with Tier 1 automotive OEMs and surgical drape manufacturers lock in volume commitments and price visibility across the forecast window, insulating qualified producers from styrenic block copolymer feedstock volatility while exposing non-contracted hygiene suppliers to spot market polyethylene fluctuations.
Pricing Analysis
REACH substance restrictions and FDA biocompatibility guidance dictate the pricing tier structure across medical-grade elastic laminates. Three-tier pricing structure across premium certified, standard industrial, and economy hygiene levels separates ISO 10993-validated substrates from uncertified alternatives. Cost compression in standard-grade polyethylene laminates is intensifying because of backward integration by resin producers and oversupply in breathable film capacity. Hygiene manufacturers exhibit highest price sensitivity due to commoditized product specifications, while automotive OEMs prioritize performance consistency over unit cost.
Supply Chain Analysis
Inventory cycles for specialty elastomers now stretch to six months as German and Chinese automotive OEMs pre-position composite laminate stock ahead of platform launches. Supply concentrates in Germany, the United States, and China where extrusion capacity serves hygiene and medical end uses. Raw material flows draw from styrenic block copolymer producers, aliphatic polyurethane resin specialists, and spunbond nonwoven manufacturers. Single-source vulnerability concentrates in medical-grade adhesive formulation where reactive polyurethane cleanroom capacity remains limited to Belgian and Dutch producers. Distribution runs through Tier 1 integrators in automotive and direct OEM relationships in medical device supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The elastic laminates market is entering a cyclical recovery phase as automotive production schedules normalize and surgical drape OEMs restock ISO 10993-certified substrates following qualification cycle compression from eighteen to twelve months.
For Market Incumbents: Shield certified supply chain positions by accelerating reactive polyurethane adhesive capacity expansion in Belgium and the Netherlands before ECHA candidate list additions trigger further reformulation mandates. Secure backward integration into polymer resin production to offset styrenic block copolymer feedstock concentration risk among limited specialty elastomer suppliers. For New Entrants and Emerging Players: Outpatient wound care channels in China and India present service-layer gaps where silicone-adhesive elastic laminates for advanced dressing fixation remain undersupplied by incumbent producers focused on hospital system contracts. Target home care distribution partnerships with regional medical device distributors as the primary go-to-market angle, bypassing capital-intensive cleanroom coating requirements through toll manufacturing arrangements. For Investors and Strategic Acquirers: Capital is best deployed toward specialized extrusion houses with ISO 13485 quality management systems and existing medical OEM qualification relationships rather than commodity hygiene converters facing mechanical recycling incompatibility penalties under extended producer responsibility frameworks. Monitor ECHA candidate list publication timing as the critical inflection signal for reformulation-driven consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Adhesive Capacity Expansion | Captures margin bifurcation toward producers with in-house formulation and certified cleanroom coating operations. |
| Backward Integration into Polymer Resin | Berry Global Group's model demonstrates input cost control for breathable film substrates in hygiene applications. |
| ISO 10993 Certification Acquisition | Locks in surgical drape OEM contracts as German and US device manufacturers mandate biocompatibility documentation. |
| Plant-Derived Diisocyanate Development | Opens Nordic procurement pathways as Dutch and Belgian producers accelerate substitution chemistry for carbon-neutral targets. |
| Mechanical Recycling Infrastructure Partnership | Addresses EU Green Deal mandates in French and Italian hospital systems requiring recycled content thresholds. |
Methodological Framework
Initial hypotheses were tested against primary input from extrusion plant managers, surgical drape procurement leads at German medical device OEMs, automotive Tier 1 supplier quality directors, and hygiene product manufacturing heads, then refined against secondary validation from FDA 510(k) filings, ECHA REACH candidate list updates, SEC 10-K disclosures by laminate producers, and automotive platform production databases. Bottom-up capacity utilization estimates and top-down end-use demand projections were triangulated to reconcile volume figures.
Variance decomposition across product type, material chemistry, bonding technology, and end-use vertical shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate assembly rather than single-point extrapolation. Key forecast inputs included automotive seating content per vehicle trends and surgical drape substrate specification migration timelines.
Underlying assumptions cover REACH substance restriction implementation schedules and automotive platform standardization continuity, with deviation risk concentrated in ECHA candidate list timing and EPA enforcement intensity for solvent-based adhesive processes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Global Thermoplastic Elastomers (TPE) Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Specialty Elastomer Market