
 Solar Cell Front Side Silver Paste Market | 2026-2036
Solar Cell Front Side Silver Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Cell Front Side Silver Paste Market Insights
High-conductivity specification tiers is reorganizing procurement standards across the Solar Cell Front Side Silver Paste Market. Heraeus Holding GmbH leverages its German metallurgy heritage to dominate ultra-fine silver flake supply for premium paste recipes. DuPont de Nemours, Inc. sustains competitive positioning through proprietary glass frit chemistry that reduces contact resistance on textured silicon wafers. Samsung SDI Co., Ltd. anchors its regional footprint with integrated silver powder-to-paste manufacturing in South Korean photovoltaic corridors.
Solar cell front side silver paste comprises a screen-printable conductive formulation containing silver powder, glass frit, organic vehicle, and additives, engineered to form low-resistance ohmic contacts on the illuminated surface of crystalline silicon photovoltaic cells. The paste must achieve fine-line printability below 20 micrometers while maintaining adhesion through firing peaks exceeding 800 degrees Celsius, directly determining cell conversion efficiency and module power output. Photovoltaic modules application segment leads absolute volume consumption as utility-scale project developers specify paste performance in procurement tenders. High conductivity feature category commands margin concentration because paste resistivity directly correlates with module wattage ratings and downstream revenue per panel.
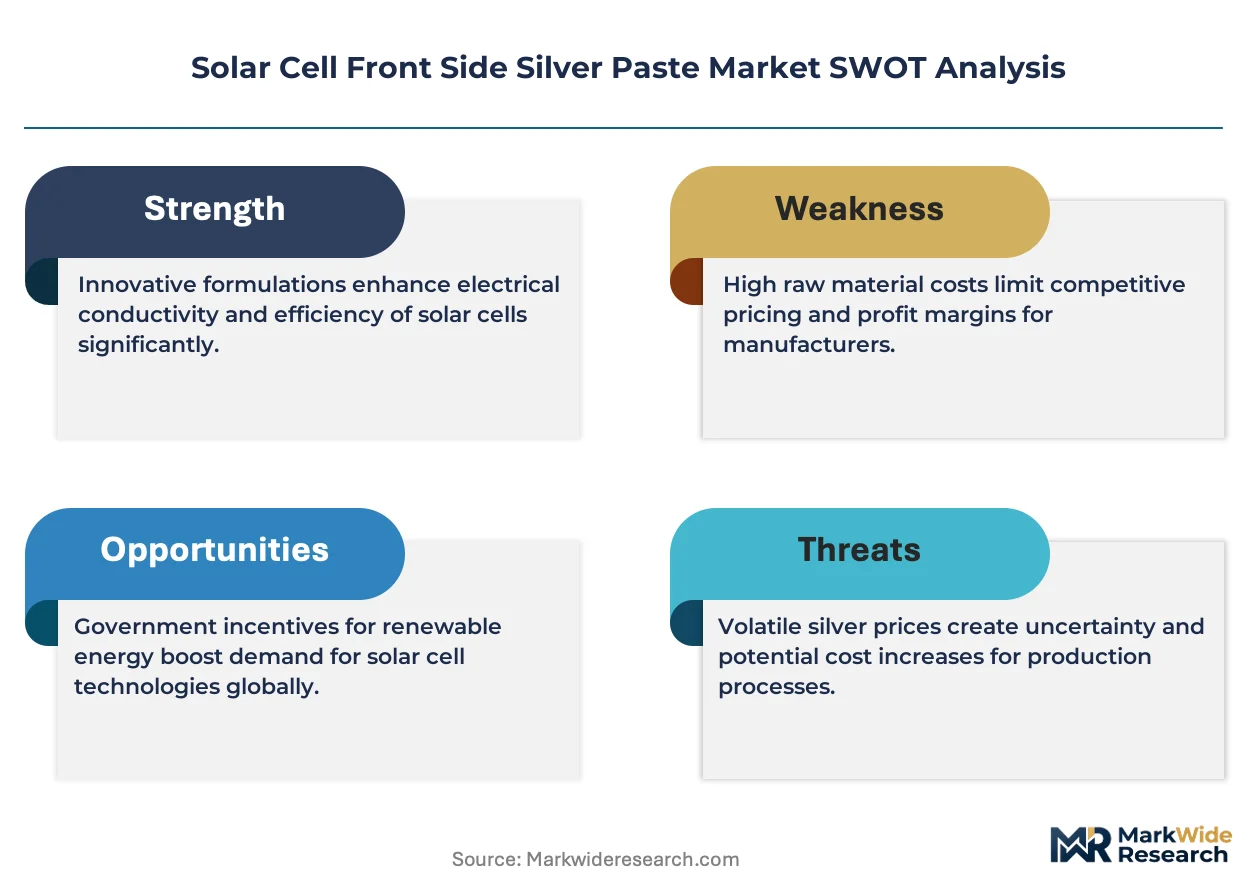
REACH and RoHS frameworks in Europe restrict cadmium and lead content in electronic materials, forcing reformulation of legacy glass frit systems that historically contained these elements. China's MEE enforces wastewater discharge standards on silver paste blending facilities, adding environmental compliance costs that favor larger producers with captive treatment infrastructure. India's BIS certification requirements for imported solar materials create non-tariff barriers that condition market access for foreign paste suppliers. Stakeholders must monitor how silver price volatility and substitutional copper metallization research reshape procurement risk models for front side paste commitments.
Market Dynamics
Silver powder supply concentration and TOPCon cell architecture migration are restructuring procurement relationships between paste blenders and photovoltaic cell fabricators. The shift from PERC to tunnel oxide passivated contact designs demands finer silver flake morphologies and modified glass frit chemistries that legacy formulations cannot satisfy.
Growth Catalysts
- China's dual carbon goals:National carbon neutrality mandates accelerate gigawatt-scale cell fabrication capacity expansion in Jiangsu and Zhejiang provinces, concentrating paste demand in manufacturing corridors with direct supplier partnerships.
- Utility-scale procurement specifications:Project developers now embed paste conductivity thresholds into module tenders, forcing cell manufacturers to upgrade from standard-grade to high-conductivity formulations.
- TOPCon firing profiles:Lower-temperature processing requirements enable thinner silver layers without contact resistance penalties, expanding addressable paste volume per cell wattage.
Market Restraints
- Silver price volatility:Precious metal cost swings compress blending margins and destabilize long-term supply contracts between paste producers and cell fabricators.
- Chinese supply concentration:Silver powder refining and flake production cluster in Shandong and Henan provinces, creating geographic single-point vulnerability for global paste supply chains.
- Copper metallization research:Academic and industrial laboratories advance plated copper finger technologies that threaten silver paste incumbency on front side applications.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for domestic solar module assembly create localized paste demand that foreign suppliers can capture through BIS-certified manufacturing partnerships.
- Glass frit reformulation:Lead-free and cadmium-free compositions aligned with REACH and RoHS frameworks open premium pricing tiers for compliant European and North American supply.
- Direct supplier integration:Cell fabricators in South Korea's photovoltaic corridors seek captive paste blending operations to secure formulation intellectual property and reduce logistics exposure.
Industry Challenges
- Screen printing skill scarcity:Fine-line patterning below 20 micrometers demands specialized process engineers that cell fabrication facilities struggle to recruit and retain.
- Firing profile optimization:Each TOPCon cell architecture variant requires paste-specific thermal curve calibration, extending qualification timelines and raising technical service costs.
- Environmental compliance infrastructure:China's MEE wastewater discharge standards force paste blending facilities to invest in captive treatment systems or face operational shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cell Front Side Silver Paste Market |
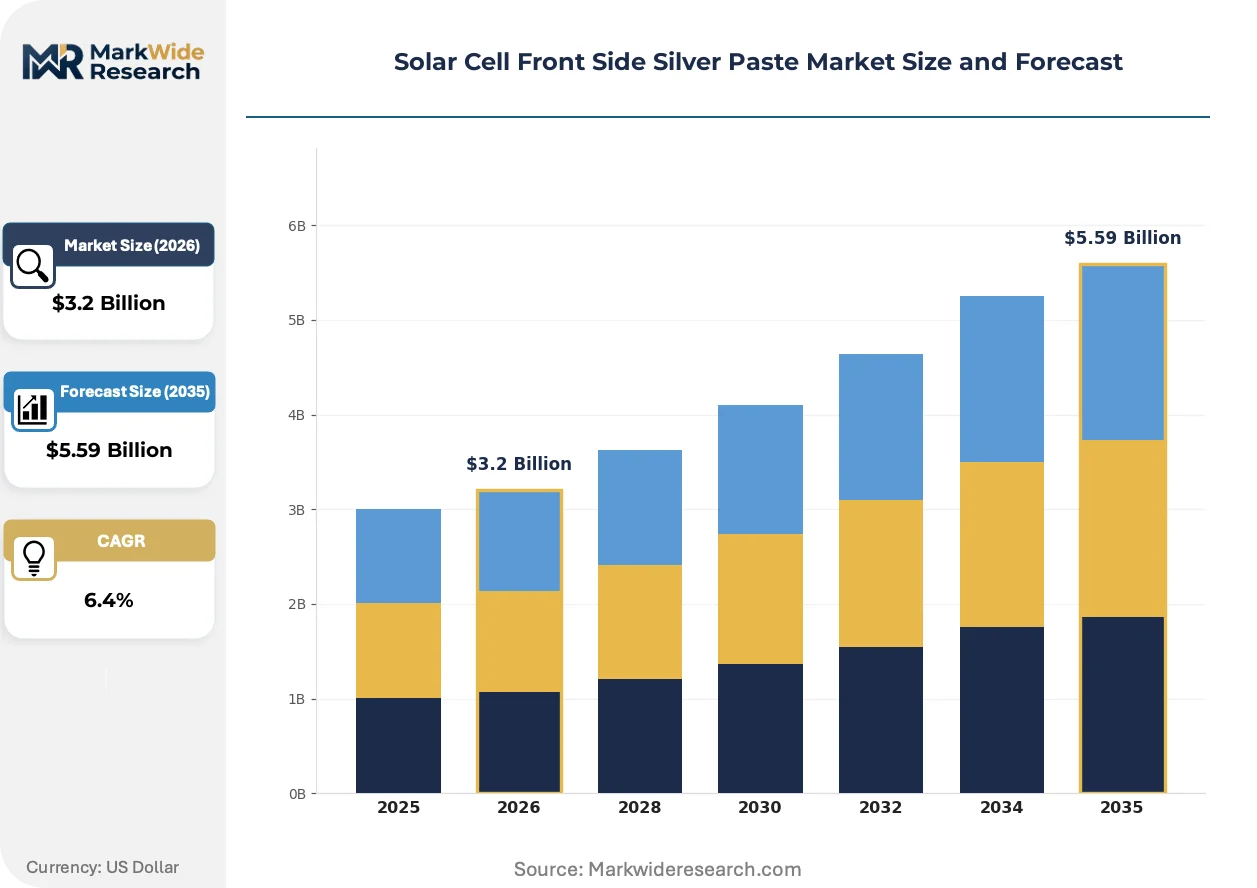
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Paste, Front Side Paste, Silver Paste, Nano Paste Feature: High Conductivity, Low Cost, Reduced Weight, Environmental Stability Application: Photovoltaic Modules, Solar Panels, Thin Film Solar, BIPV End User: Manufacturers, Installers, Research Institutions, Suppliers |
| Companies Covered | Heraeus Holding GmbH, DuPont de Nemours, Inc., Samsung SDI Co., Ltd., Giga Solar Materials Corporation, Daejoo Electronic Materials Co., Ltd., Dongjin Semichem, Noritake Co., Limited, Namics Corporation, Hunan LEED Electronic Ink Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cell Front Side Silver Paste Market Trends and Innovations
Metallization chemistry and procurement architecture are undergoing parallel transformation as cell efficiency roadmaps collide with sustainability mandates and supply security imperatives. These intersecting pressures favor technical differentiation over commodity positioning.
Fine-line screen printing pastes with sub-20-micrometer resolution capabilities are supplanting legacy 25-30 micrometer formulations in premium cell manufacturing. Tier-one module producers in Jiangsu province specify these advanced pastes for utility-scale tenders where wattage ratings determine project financing terms. The transition compresses margin for standard-grade paste suppliers while concentrating volume with metallurgy specialists capable of ultra-fine silver flake production.
REACH and RoHS frameworks in Europe restrict cadmium and lead content in electronic materials, compelling reformulation of historical glass frit systems. Paste blenders must validate alternative oxide chemistries that maintain contact adhesion through 800-degree Celsius firing peaks without prohibited heavy metals. German and Dutch cell fabricators now require full material disclosure documentation as a condition of supply contract execution.
Direct long-term agreements between silver paste blenders and gigawatt-scale cell manufacturers are displacing spot market and distributor-mediated transactions. Cell fabricators in South Korea and China seek multi-year volume commitments with locked pricing corridors to hedge silver commodity exposure. This contractual evolution favors producers with captive silver powder supply and integrated blending capacity over merchant paste specialists dependent on external flake procurement.
Solar Cell Front Side Silver Paste Market Segmentation
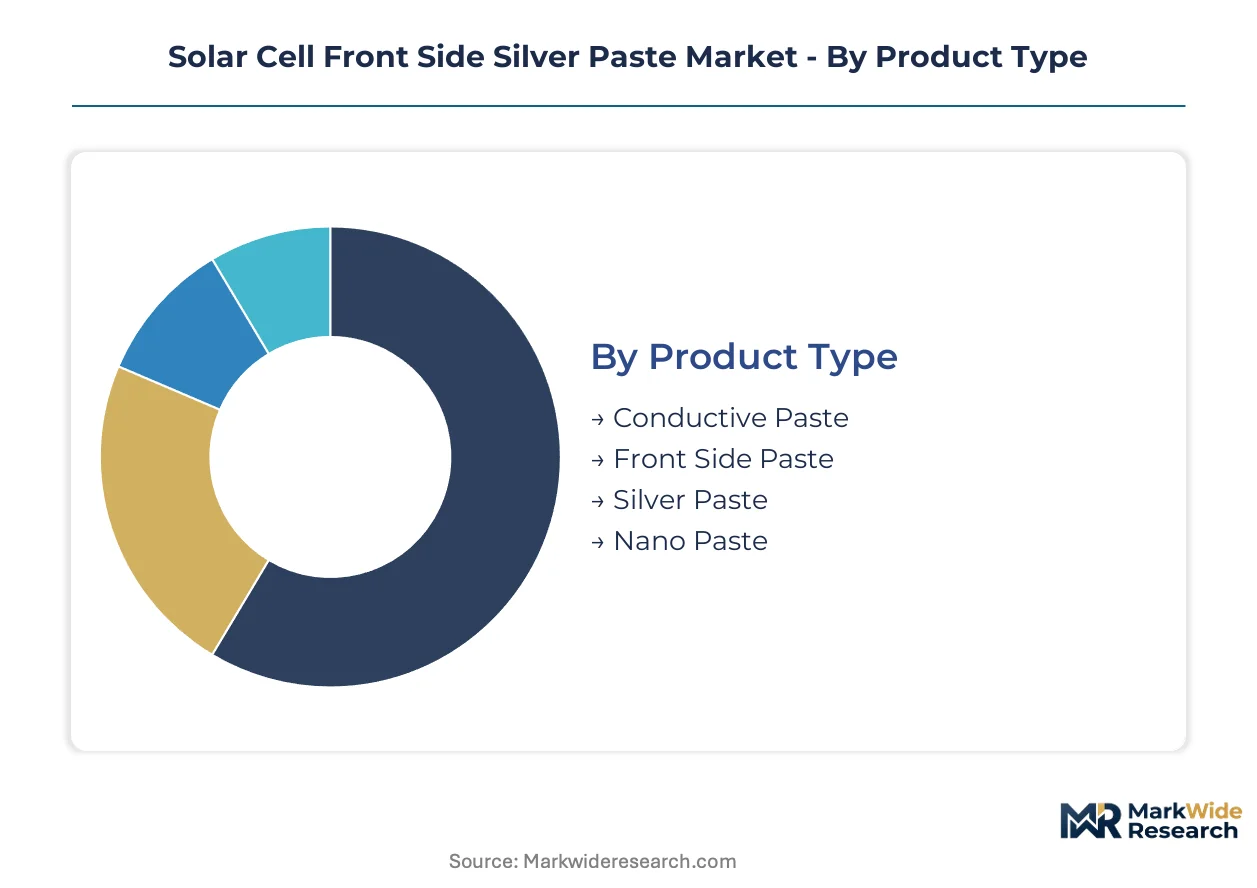
Silver paste segmentation determines procurement specifications across cell architectures. Each dimension — product chemistry, performance tier, application format, and customer type — carries distinct substitution risk from copper metallization and alternative contact schemes.
Product Type:
Front side formulations face acute displacement pressure from plated copper research, while specialized nano variants command defensive positioning through fine-line printability barriers.
- Conductive Paste:Broad-category formulation encompassing silver-bearing and silver-alternative metallization systems. Jiangsu province cell fabricators specify this grade for standard PERC lines where conductivity thresholds remain commoditized.
- Front Side Paste:Illuminated-surface formulation engineered for ohmic contact formation on textured silicon wafers. TOPCon migration in Zhejiang manufacturing corridors demands sub-20-micrometer printability that only ultra-fine silver flake recipes satisfy.
- Silver Paste:Conventional high-loading formulation with established firing profiles and contact resistance benchmarks. Legacy PERC facilities in South Korean photovoltaic corridors continue procurement for capacity not yet converted to tunnel oxide passivated contact designs.
- Nano Paste:Ultra-fine particle dispersion enabling sub-15-micrometer line resolution and reduced silver consumption per cell. Research institutions in Germany and Japan pilot this chemistry for next-generation interdigitated back contact architectures.
Front Side Paste anchors the volume base while Nano Paste gains share at the steepest rate.
Feature:
Performance tiering separates procurement specifications by module wattage ratings and environmental compliance requirements.
- High Conductivity:Low-resistivity formulation commanding premium positioning in utility-scale tenders where revenue per panel scales with efficiency ratings. Tier-one module producers in Jiangsu province embed conductivity thresholds directly into supplier qualification protocols.
- Low Cost:Standard-grade chemistry for price-sensitive distributed generation markets. Indian module assemblers under PLI scheme constraints prioritize this tier for rooftop and agricultural pump applications.
- Reduced Weight:Optimized solids loading for flexible and lightweight module formats. BIPV integrators in European markets specify this feature for building-integrated installations where structural load limits constrain conventional glass-glass constructions.
- Environmental Stability:Lead-free and cadmium-free glass frit systems aligned with REACH and RoHS frameworks. Dutch and German cell fabricators require full material disclosure documentation as a condition of contract execution.
High Conductivity captures the margin concentration while Environmental Stability climbs the fastest as regulatory deadlines approach.
Application:
Format-specific requirements dictate paste rheology, firing window, and adhesion chemistry.
- Photovoltaic Modules:Dominant consumption format for crystalline silicon cell strings encapsulated in glass-backsheet or glass-glass constructions. Gigawatt-scale project developers specify paste performance in procurement tenders that determine financing terms.
- Solar Panels:Distributed generation and off-grid applications with relaxed efficiency requirements. Standard-grade pastes suffice for these installations where cost per watt dominates procurement criteria.
- Thin Film Solar:Cadmium telluride and copper indium gallium selenide formats using alternative contact metallization. Silver paste penetration remains limited to specialized hybrid architectures and research prototypes.
- BIPV:Building-integrated photovoltaics demanding aesthetic uniformity and reduced visual impact. Semi-transparent and colored cell variants require modified paste formulations with adjusted optical properties.
Photovoltaic Modules anchor the volume base while BIPV expands most quickly as architectural integration mandates proliferate.
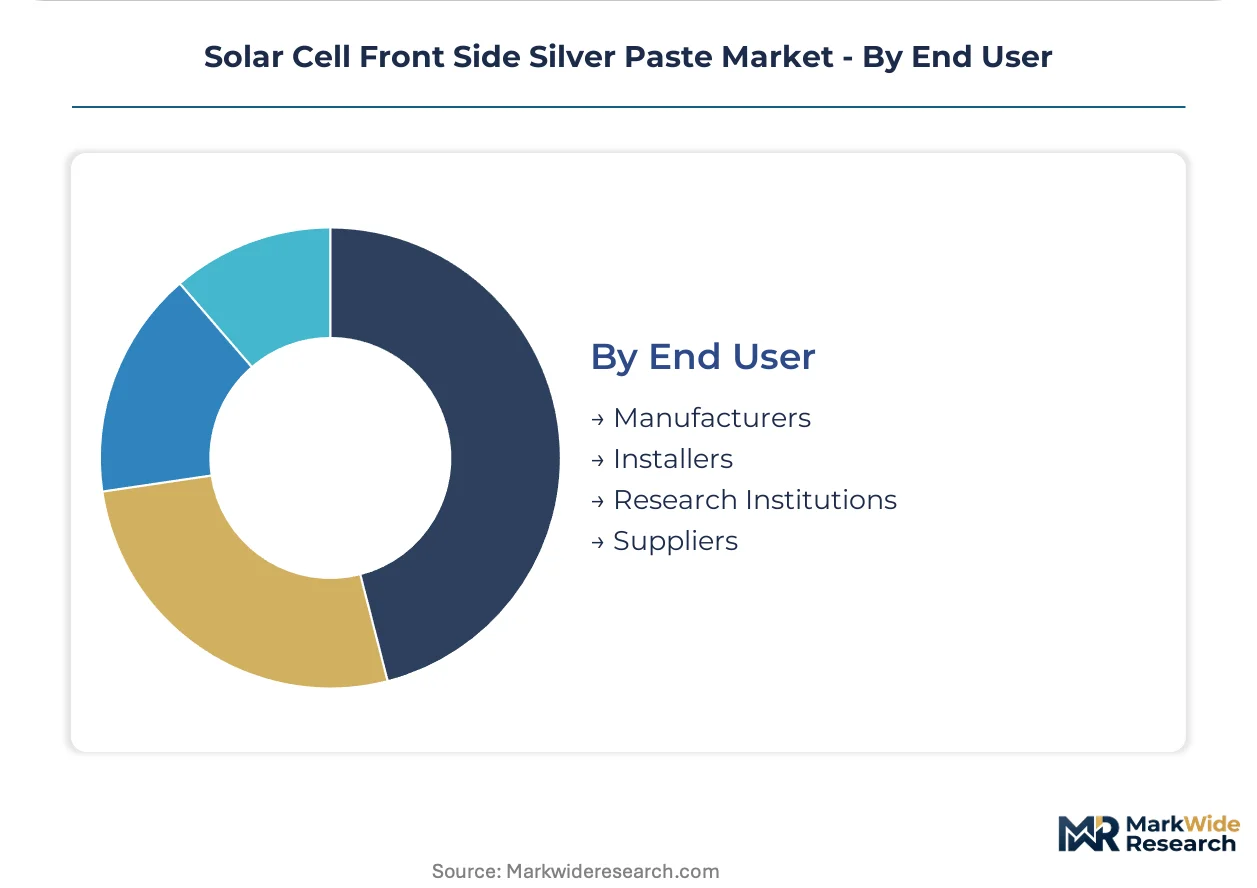
End User:
Customer type determines technical service intensity, contract structure, and qualification timeline.
- Manufacturers:Cell fabrication facilities with captive screen printing and firing lines. Direct supplier partnerships in China's Jiangsu and Zhejiang provinces concentrate procurement volume among metallurgy specialists with integrated silver powder capacity.
- Installers:Module assembly and system integration contractors with limited paste specification authority. These stakeholders influence procurement indirectly through module brand preferences and warranty requirements.
- Research Institutions:Academic and national laboratory facilities piloting next-generation cell architectures. Nano paste sampling and custom formulation development dominate this segment's technical engagement.
- Suppliers:Distributor and trading company intermediaries serving smaller cell fabricators without direct blender relationships. Spot market exposure and silver price volatility compress margins in this channel.
Manufacturers anchor the volume base while Research Institutions drive formulation innovation at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silver powder refining clusters in Shandong and Henan provinces create geographic chokepoints that condition paste supply security for cell fabricators worldwide. Procurement relationships are restructuring around direct supplier partnerships in manufacturing corridors with captive metallurgy infrastructure.
China
Jiangsu and Zhejiang provinces host gigawatt-scale cell fabrication clusters that source front side paste through integrated supplier relationships. MEE wastewater discharge standards force blending facilities to invest in captive treatment systems or face operational shutdowns. Zhejiang manufacturing corridors demand sub-20-micrometer printability specifications that only ultra-fine silver flake recipes satisfy.
South Korea
Photovoltaic corridors in the Seoul Capital Area and Busan-Ulsan region anchor integrated silver powder-to-paste manufacturing operations. Domestic cell fabricators seek multi-year volume commitments with locked pricing corridors to hedge silver commodity exposure. Daegu-Gyeongbuk industrial zones concentrate technical service teams for firing profile optimization on TOPCon architectures.
Germany
REACH and RoHS frameworks restrict cadmium and lead content in electronic materials, compelling reformulation of historical glass frit systems. Dutch and German cell fabricators require full material disclosure documentation as a condition of supply contract execution. Bavaria-based research institutions pilot nano paste sampling for next-generation interdigitated back contact architectures.
India
Production-linked incentives for domestic solar module assembly create localized paste demand that foreign suppliers capture through BIS-certified manufacturing partnerships. Standard-grade chemistry dominates procurement for price-sensitive distributed generation markets under PLI scheme constraints. Gujarat and Maharashtra industrial zones concentrate module assembly capacity with indirect paste specification influence through warranty requirements.
Japan
METI efficiency roadmaps drive fine-line screen printing adoption in premium cell manufacturing for building-integrated photovoltaic applications. JIS standards compliance creates non-tariff barriers that condition market access for foreign paste suppliers. Kansai region research consortia advance plated copper finger technologies that threaten silver paste incumbency on front side applications.
Solar Cell Front Side Silver Paste Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Solar Cell Front Side Silver Paste Market. German and Japanese metallurgy specialists dominate ultra-fine silver flake supply for premium formulations, while Korean and Chinese integrated producers compete on scale and captive powder supply. The vendor base separates into three strategic archetypes: integrated silver powder-to-paste manufacturers, specialized glass frit chemistry developers, and regional merchant blenders dependent on external flake procurement. Dominant competitive moves include backward integration into silver powder refining and direct long-term contractual lockups with gigawatt-scale cell fabricators.
Among German heritage metallurgy houses, Heraeus Holding GmbH and DuPont de Nemours, Inc. occupy positions that exemplify technology-driven premium positioning through proprietary formulation intellectual property. Korean integrated producers including Samsung SDI Co., Ltd. represent the scale-driven archetype with captive manufacturing in domestic photovoltaic corridors. These three anchors illustrate how geographic concentration of silver refining capacity and cell fabrication demand reshape competitive boundaries between regional supply blocs.
| Leading Market Players |
|---|
| Heraeus Holding GmbH |
| DuPont de Nemours, Inc. |
| Samsung SDI Co., Ltd. |
| Giga Solar Materials Corporation |
| Daejoo Electronic Materials Co., Ltd. |
| Dongjin Semichem |
| Noritake Co., Limited |
| Namics Corporation |
| Hunan LEED Electronic Ink Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between silver paste blenders and gigawatt-scale cell fabricators lock in both supply access and price visibility across multi-year procurement horizons. These contractual structures concentrate volume with metallurgy specialists possessing captive silver powder capacity in China's Shandong and Henan provinces.
Pricing Analysis
REACH and RoHS frameworks dictate the pricing tier structure across European and North American supply corridors. Three-tier pricing structure across premium, standard, and economy levels separates lead-free glass frit formulations from legacy compositions and commodity-grade alternatives. Cost compression in standard-grade tiers is intensifying because Chinese cell fabricators in Jiangsu province negotiate volume-driven discounts. Distributed generation installers in India exhibit the highest price sensitivity, while utility-scale developers in South Korea prioritize conductivity performance over unit cost.
Supply Chain Analysis
Strategic stockpiling of silver powder prevails over just-in-time preferences as cell fabricators hedge against commodity volatility and geographic concentration risks. Raw material sourcing draws from refining clusters in China, South Korea, and Germany, with ultra-fine silver flake production resting on specialized metallurgy infrastructure. Single-source vulnerability emerges from Shandong and Henan province concentration, where wastewater discharge enforcement by China's MEE threatens operational continuity. Distribution runs through direct supplier partnerships in manufacturing corridors rather than distributor-mediated spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silver paste incumbents face a substitution defense against plated copper metallization research advancing in Japanese and German laboratories. Copper finger technologies threaten to displace silver on front side applications if contact resistance benchmarks achieve parity.
For Market Incumbents: Consolidate backward integration into silver powder refining to secure flake supply against Chinese geographic concentration. Lock in multi-year direct contracts with TOPCon cell fabricators in Zhejiang province before copper metallization reaches commercial viability. Captive powder capacity and formulation intellectual property form the core defensive perimeter against commodity volatility and substitute threats.
For New Entrants and Emerging Players: BIS certification fast-track through Indian manufacturing partnerships unlocks PLI-scheme module assembly demand in Gujarat and Maharashtra. Target price-sensitive distributed generation segments where standard-grade paste specifications dominate procurement. Establish technical service capabilities for firing profile optimization to differentiate from merchant blenders lacking process engineering depth.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated silver powder-to-paste manufacturers with captive metallurgy infrastructure and established direct supplier relationships. Long-term viability hinges on defensible positioning against copper substitution through the next cell architecture transition. Watch for plated copper pilot line announcements from tier-one cell fabricators as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Powder Refining | Captive flake supply insulates margin from Shandong province concentration and commodity volatility. |
| Lead-Free Glass Frit Reformulation | REACH-compliant compositions unlock premium European procurement tiers and long-term contract eligibility. |
| Direct Supplier Partnership Expansion | Multi-year volume commitments with Jiangsu cell fabricators reduce spot market exposure and pricing uncertainty. |
| Technical Service Capacity Buildout | Firing profile optimization teams accelerate TOPCon qualification timelines and deepen customer switching costs. |
| Indian BIS Certification Investment | PLI-scheme module assembly demand in Gujarat creates localized revenue anchor against Chinese supply concentration. |
Research Methodology
Initial hypotheses were tested against primary input from silver paste formulation chemists, photovoltaic cell fabrication engineers, procurement managers at tier-one module producers, and glass frit technical directors, then refined through secondary validation. Bottom-up triangulation combined trade data from Chinese customs filings, SEC disclosures from listed metallurgy suppliers, MEE environmental compliance records, and IEA photovoltaic deployment statistics. Top-down cross-checks anchored volume estimates against installed capacity projections and silver consumption intensity benchmarks.
Variance decomposition across the modeling period isolates volume, price, and mix effects within each segmentation dimension. Product chemistry tiers, performance feature categories, application formats, and end-user archetypes structure the analytical framework. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate TOPCon migration timelines, silver price trajectory assumptions, and copper metallization research progress indicators.
Decision-makers should treat outputs as directional under base assumptions of continued crystalline silicon dominance and moderate silver commodity volatility; material deviation would warrant model refresh. Revision becomes warranted when plated copper contact resistance benchmarks cross commercial parity thresholds or when Chinese environmental enforcement disrupts powder refining capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
Prils Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Salt Hydrate Market