
 Elastomeric Foam Insulation Market | 2026-2036
Elastomeric Foam Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomeric Foam Insulation Market Analysis
Market Context
Specialized polymer chemists and certified insulation technicians is reorganizing how quickly manufacturers can scale output for high-performance grades. Armacell International S.A. leverages its European manufacturing footprint to serve HVAC OEMs with consistent lead times. Dow Inc. anchors its position through captive supply of nitrile rubber precursors. Huntsman Corporation differentiates via R&D intensity in low-smoke, low-toxicity formulations for marine and transit applications.
Technical Definition and Segment Structure
Elastomeric foam insulation comprises closed-cell or open-cell synthetic rubber materials, typically manufactured through continuous extrusion or expansion processes with densities ranging from 40 to 80 kg/m³, engineered to prevent condensation on cold surfaces and reduce thermal bridging in mechanical systems. Closed-cell nitrile rubber dominates volume shipments due to its moisture resistance and flexibility in tight mechanical spaces, while EPDM-based grades capture premium positioning for outdoor and UV-exposed installations. HVAC applications anchor demand through replacement cycles and new commercial construction, though refrigeration is accelerating fastest as cold-chain logistics expands and refrigerant regulations force equipment upgrades.
Regulatory Framework
The EU F-Gas Regulation, REACH chemical compliance, and EPA SNAP program in the United States collectively shape material selection by restricting high-GWP blowing agents and mandating lower-flammability specifications in occupied buildings. OSHA workplace exposure limits and country-specific fire-safety codes further segment product certification requirements across installation types. Stakeholders must monitor evolving refrigerant-phase-down schedules and building performance standards to align R&D pipelines with compliance windows.
Market Dynamics
The EU F-Gas Regulation and parallel refrigerant-phase-down mandates are compressing equipment replacement cycles across commercial refrigeration, forcing simultaneous upgrades to compatible insulation systems and reshaping procurement priorities for cold-chain operators.
Growth Catalysts
- Building energy code tightening:ASHRAE Standard 90.1 updates in the United States are mandating lower thermal conductivity values for mechanical piping, directly specifying closed-cell nitrile rubber for chilled-water applications.
- Cold-chain infrastructure investment:China is expanding pharmaceutical and food logistics networks, creating concentrated demand for low-temperature insulation in automated warehousing and last-mile distribution.
- REACH chemical compliance:The European regulation's restrictions on legacy blowing agents are accelerating reformulation investments that yield higher-performance thermal barriers.
Market Restraints
- Acrylonitrile price volatility:Nitrile rubber precursor costs fluctuate with petrochemical feedstock markets, compressing margin stability for formulation-dependent manufacturers.
- Specialized polymer chemist scarcity:Germany and the United States face acute shortages of technicians capable of optimizing closed-cell expansion processes for high-density grades.
- EPDM substitution in outdoor applications:Ethylene-propylene-diene monomer foams compete on UV resistance for rooftop and exterior mechanical installations.
Strategic Opportunities
- Data center liquid cooling expansion:Hyperscale facilities in Northern Virginia and Frankfurt are adopting direct-to-chip cooling architectures requiring specialized low-temperature insulation.
- Marine and transit certification:IMO SOLAS and national rail safety mandates for low-smoke, low-toxicity materials open premium positioning for certified formulations.
- India cold-chain modernization:The country's PLI scheme for food processing infrastructure is subsidizing integrated refrigeration and insulation upgrades.
Industry Challenges
- Multi-jurisdiction certification timelines:Manufacturers must sequence UL, CE marking, and country-specific fire-rating approvals, extending product launch windows.
- Legacy mechanical contractor training gaps:Installation quality for vapor-sealed joints depends on certified technician availability, which lags specification complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomeric Foam Insulation Market |
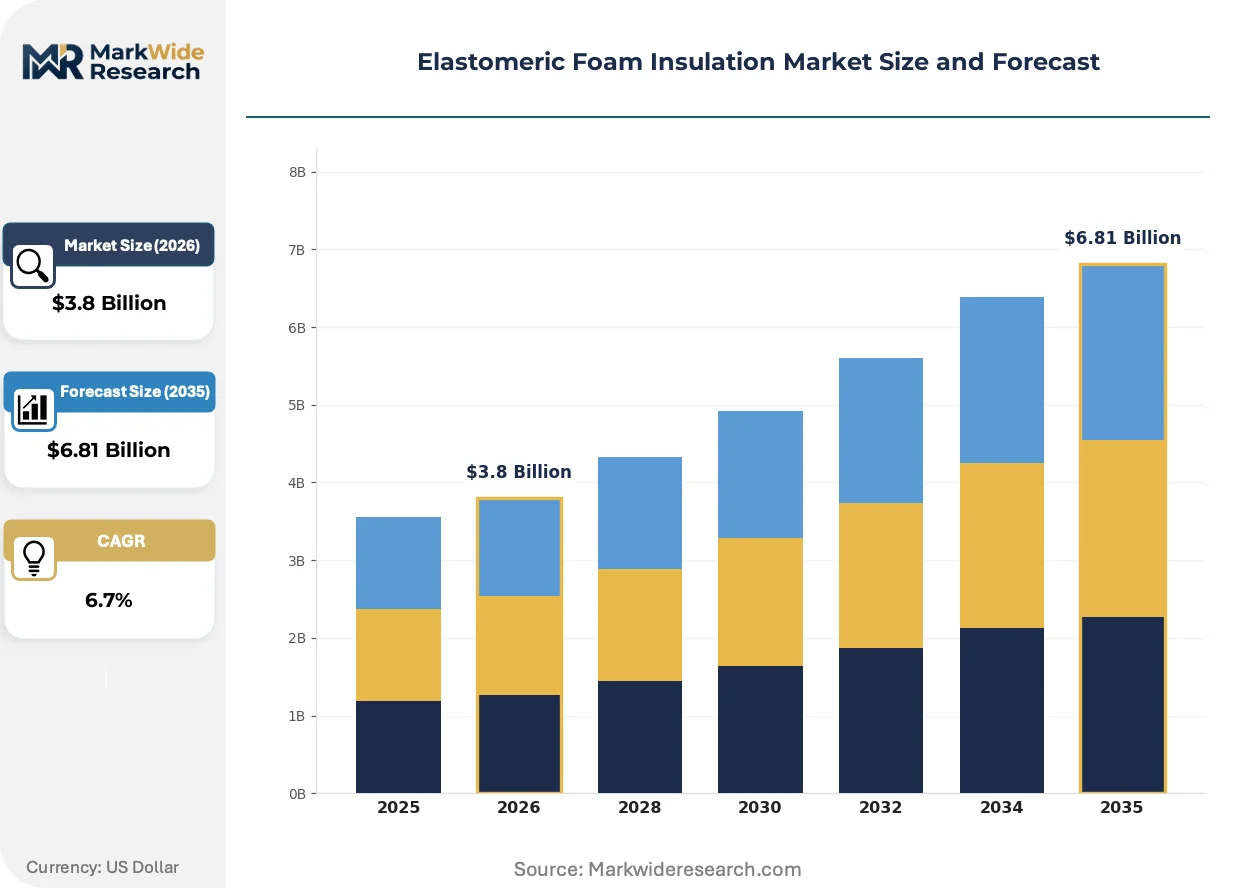
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Cell, Open Cell, Self-adhesive, Non-adhesive Application: HVAC, Plumbing, Refrigeration, Construction Installation: Residential, Commercial, Industrial, Marine Material: Nitrile Rubber, EPDM, Silicone, Others |
| Companies Covered | Dow Inc., Hira Industries LLC, Armacell International S.A., Evonik Industries AG, Huntsman Corporation, BASF SE, L'Isolante K-Flex S.p.A., Zotefoams plc, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomeric Foam Insulation Market Emerging Trajectories
Refrigerant chemistry changes and thermal performance benchmarking are forcing simultaneous material and installation practice upgrades across HVAC and refrigeration end-uses.
Water-blown foam formulations are supplanting hydrocarbon and HFC-based blowing agents in European manufacturing. HVAC OEMs in Germany and the Netherlands are specifying these grades for export equipment to preempt regulatory divergence. The transition is compressing demand for legacy formulations and rewarding early reformulators with specification lock-in.
The EPA SNAP program and state-level HFC phase-down rules are restricting high-GWP blowing agents in the United States. Equipment manufacturers must validate alternative insulation compatibility with new refrigerant chemistries. California and Washington state regulations are advancing fastest, creating a regulatory laboratory for national adoption patterns.
Integrated procurement of insulation with mechanical equipment is consolidating vendor relationships. Large commercial contractors in Texas and Florida are bundling specification and installation through single-source agreements. This consolidation is most visible in healthcare and laboratory construction where performance guarantees cover complete thermal envelope systems.
Elastomeric Foam Insulation Market Segmentation
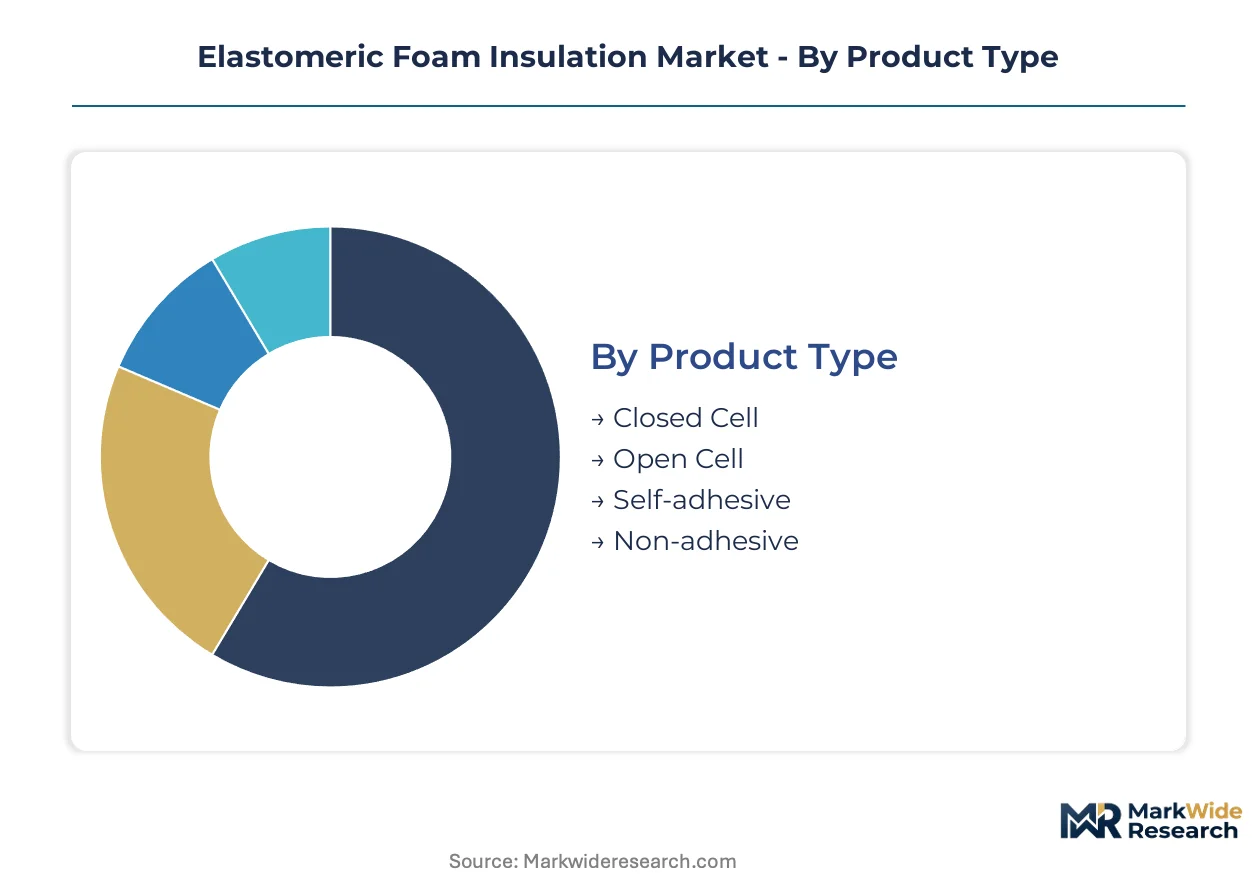
Segmentation in elastomeric foam insulation reveals where technical specifications diverge from price competition. Material chemistry and installation environment determine margin structure across each category.
Product Type:
Closed-cell formulations face mounting pressure from water-blown alternatives in European manufacturing, while open-cell grades compete against fiberglass in cost-sensitive residential markets.
- Closed Cell:Nitrile rubber-based closed-cell structures deliver moisture resistance and thermal conductivity values below 0.040 W/m·K. HVAC contractors in Germany and the United States specify these grades for chilled-water piping as ASHRAE 90.1 codes tighten thermal bridging requirements.
- Open Cell:Lower-density expanded rubber permits vapor permeability for specific wall-cavity applications. Demand concentrates in residential construction across Spain and Italy where cost thresholds override performance premiums.
- Self-adhesive:Factory-applied pressure-sensitive backing accelerates installation in confined mechanical spaces. Preferred by maintenance contractors in Texas and Florida for retrofit refrigeration line sets.
- Non-adhesive:Standard tubes and sheets require separate vapor-barrier sealing. Dominates bulk procurement for industrial pipe insulation in China where labor costs favor manual application.
Closed Cell retains volume leadership; Self-adhesive holds the steepest expansion curve.
Application:
Cost tiers separate specification-driven commercial segments from price-sensitive residential markets, with certification requirements widening the gap.
- HVAC:Chilled-water and ductwork insulation accounts for the largest installed base. Replacement cycles in the United States accelerate as building energy codes mandate lower thermal conductivity values for mechanical systems.
- Plumbing:Potable water and drainage line insulation faces substitution from polyethylene foam in residential markets. Commercial specifications in California retain elastomeric grades for freeze protection.
- Refrigeration:Low-temperature cold-chain applications demand closed-cell grades compatible with evolving refrigerant chemistries. EU F-Gas Regulation phase-downs force simultaneous equipment and insulation upgrades.
- Construction:Wall and roof assemblies represent a marginal share where elastomeric competes against mineral wool and PIR boards on cost per R-value.
HVAC commands the largest specification volume; Refrigeration climbs fastest on regulatory-driven replacement.
Installation:
Customer type determines procurement channel, with industrial buyers consolidating vendors and marine operators demanding certified specialty grades.
- Residential:Single-family and multifamily construction drives volume through distributor channels. Price sensitivity favors thinner gauges and open-cell alternatives in India and Southeast Asia.
- Commercial:Office, retail, and healthcare facilities specify closed-cell nitrile rubber for mechanical rooms and risers. Integrated procurement with HVAC equipment is consolidating vendor relationships in Texas.
- Industrial:Process piping and tank insulation requires high-density grades with fire-rating certifications. Petrochemical facilities in Louisiana and Rotterdam specify premium formulations.
- Marine:IMO SOLAS low-smoke, low-toxicity mandates create a certified niche. Shipyards in South Korea and Germany pay premiums for certified EPDM and silicone formulations.
Commercial installation dominates procurement value; Marine commands the highest margin per square meter.
Material:
Supply concentration favors integrated producers with captive rubber precursor access, while specialty grades depend on scarce polymer chemistry expertise.
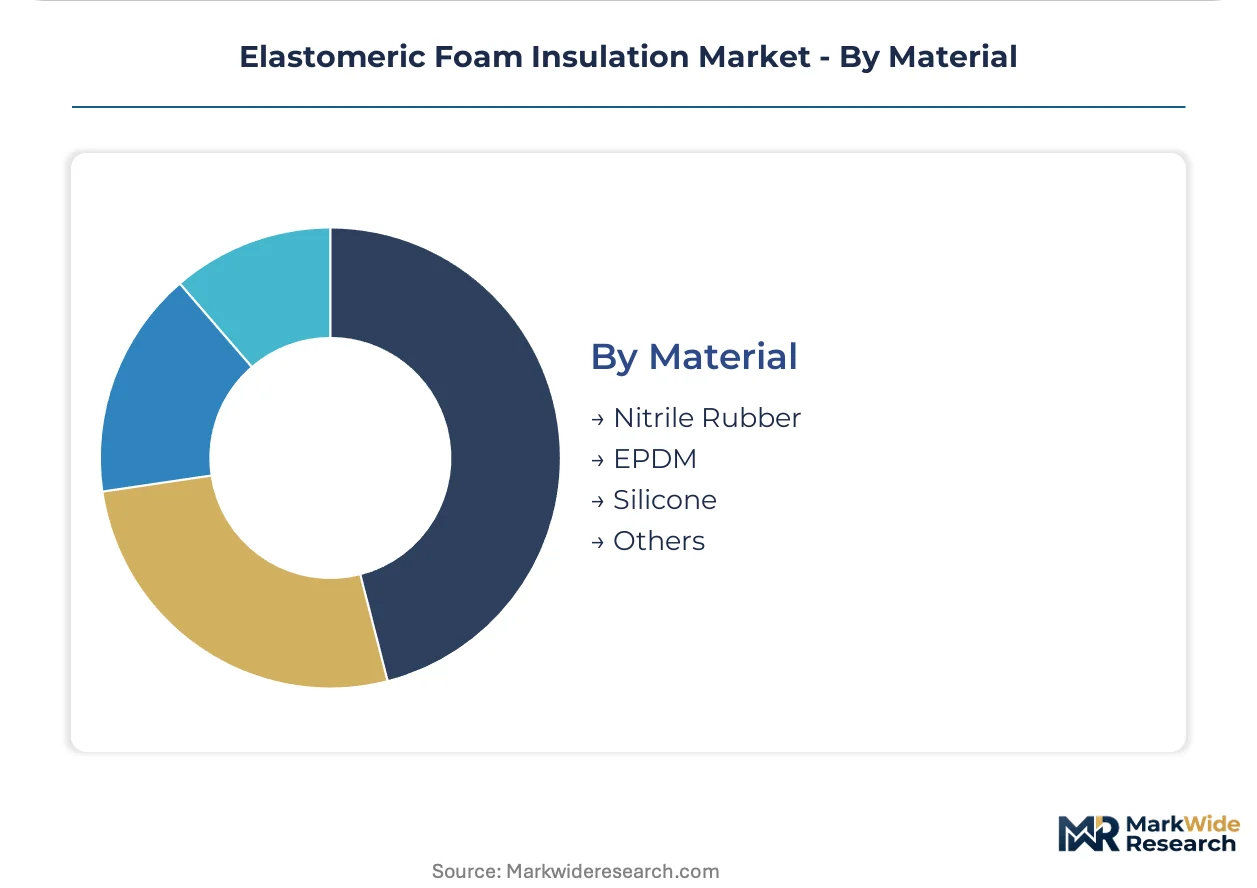
- Nitrile Rubber:Acrylonitrile-butadiene copolymer dominates volume through superior oil resistance and flexibility. Dow Inc. and Armacell leverage integrated supply chains to serve HVAC OEMs in Germany and the United States.
- EPDM:Ethylene-propylene-diene monomer foams capture outdoor and UV-exposed applications. Rooftop mechanical installations in Arizona and Australia specify EPDM for weathering resistance.
- Silicone:Extreme temperature range (-60°C to 200°C) serves aerospace and specialty industrial applications. Limited producers concentrate in Japan and Switzerland.
- Others:Chloroprene and blended formulations occupy niche positions where specific chemical resistance or fire performance is required.
Nitrile Rubber maintains volume dominance; EPDM gains share fastest on outdoor application expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA SNAP program enforcement and state-level HFC phase-down rules in the United States are compressing equipment replacement timelines and reshaping insulation procurement patterns across major demand centers.
United States
Data center liquid cooling expansion in Northern Virginia and hyperscale facility construction in Dallas-Fort Worth are driving specification of low-temperature closed-cell grades. California and Washington state regulations on high-GWP blowing agents are advancing fastest, creating regulatory precedents for national adoption. HVAC contractors in Texas and Florida are consolidating procurement through single-source agreements covering mechanical equipment and insulation systems.
Germany
Industrial construction in the Rhine-Ruhr region and pharmaceutical logistics hub development around Frankfurt are sustaining demand for high-performance thermal barriers. EU F-Gas Regulation phase-down schedules are forcing simultaneous refrigeration equipment and insulation upgrades. Armacell leverages its European manufacturing footprint to serve HVAC OEMs with consistent lead times for water-blown formulations.
China
Cold-chain infrastructure investment for pharmaceutical and food logistics networks is creating concentrated demand in automated warehousing and last-mile distribution corridors. The country's dual carbon goals are tightening building energy performance standards for mechanical systems. Industrial construction in the Yangtze River Delta is specifying closed-cell nitrile rubber for chilled-water piping as code compliance tightens.
India
The PLI scheme for food processing infrastructure is subsidizing integrated refrigeration and insulation upgrades across processing clusters. Price sensitivity in residential construction favors thinner gauges and open-cell alternatives in distributor channels. Maharashtra and Gujarat industrial zones are seeing concentrated cold-chain modernization activity.
South Korea
Shipyard activity around Busan-Ulsan is generating demand for IMO SOLAS-certified low-smoke, low-toxicity formulations for marine applications. Domestic HVAC OEMs are specifying closed-cell grades for export equipment to preempt regulatory divergence in target markets. Daegu-Gyeongbuk manufacturing corridors are serving as fabrication centers for certified specialty grades.
Elastomeric Foam Insulation Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the elastomeric foam insulation market. The vendor base clusters around integrated chemical producers with captive rubber precursor supply and specialized foam fabricators with formulation expertise. Three archetypes dominate: multinational chemical conglomerates with backward integration into nitrile rubber feedstocks, mid-cap insulation specialists with certified manufacturing for regulated applications, and regional fabricators competing on price in cost-sensitive construction markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players seeking to lock in specification relationships with HVAC OEMs and cold-chain operators.
Among integrated chemical producers, Dow Inc. and BASF SE exemplify the archetype of multinational conglomerates with upstream control over polymer precursors. Armacell International S.A. and L'Isolante K-Flex S.p.A. occupy positions within the specialist fabricator tier, with geographic naming indicating European base and S.p.A. suffix denoting Italian corporate structure. These named entities anchor the competitive landscape without constraining the full range of participants active across formulation, fabrication, and distribution functions.
| Leading Market Players |
|---|
| Dow Inc. |
| Hira Industries LLC |
| Armacell International S.A. |
| Evonik Industries AG |
| Huntsman Corporation |
| BASF SE |
| L'Isolante K-Flex S.p.A. |
| Zotefoams plc |
| Covestro AG |
| Others |
Supply Flow & Price Mechanics
Water-blown foam formulations displacing hydrocarbon-based blowing agents in European manufacturing are simultaneously redrawing supply geography toward Germany and the Netherlands while compressing margin premiums for legacy formulation holders. This chemistry transition rewards producers with captive precursor access and punishes formulation-dependent competitors facing acrylonitrile cost volatility.
Pricing Analysis
Price spreads between German-manufactured water-blown grades and Asian-produced hydrocarbon-based alternatives span certification tiers rather than raw performance metrics. Three-tier pricing structure across IMO SOLAS-certified marine grades, REACH-compliant commercial formulations, and economy open-cell residential products anchors market segmentation. Pricing pressure stems from EPDM substitution in rooftop HVAC installations where UV resistance commands premiums. Cold-chain operators in China exhibit lowest price sensitivity due to regulatory compliance mandates, while residential distributors in India and Southeast Asia drive volume through thin-gauge economy positioning.
Supply Chain Analysis
Acrylonitrile monomer availability through Rotterdam and Houston petrochemical corridors underwrites nitrile rubber precursor supply for integrated producers. Manufacturing concentrates in Germany, the United States, and China where HVAC OEM clusters anchor demand. Raw material dependencies center on butadiene feedstocks, blowing agent chemicals, and specialized polymer additives. Tariff exposure on Chinese-manufactured foam exports to North American markets creates margin vulnerability for non-integrated fabricators. Distribution runs through mechanical contractor networks in Texas and Florida, OEM direct procurement in Germany, and distributor channels for residential retrofit across India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elastomeric foam insulation sits in early-cycle expansion as data center liquid cooling adoption and cold-chain infrastructure investment outpace mature HVAC replacement rates. Regulatory phase-down schedules for high-GWP refrigerants and blowing agents are compressing equipment upgrade timelines and opening specification windows for reformulated grades.
For Market Incumbents: Consolidate specification relationships with HVAC OEMs through captive supply of water-blown formulations and backward integration into nitrile rubber precursors. Armacell's European manufacturing footprint and Dow's petrochemical integration exemplify defensive positioning against EPDM substitution in outdoor applications. Capacity additions in the Yangtze River Delta and Rhine-Ruhr corridor would preempt emerging competitor scale. For New Entrants and Emerging Players: Differentiate on IMO SOLAS marine certification where South Korean and German shipyards pay scarcity premiums for low-smoke, low-toxicity formulations. India's PLI-subsidized cold-chain modernization offers the most penetrable geography for integrated refrigeration-insulation bundles. Target data center liquid cooling specifications in Northern Virginia and Frankfurt through direct engineering engagement with hyperscale facility developers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap European fabricators holding REACH-compliant formulation libraries but lacking global distribution reach. Five-to-ten year viability hinges on water-blown chemistry transition completion and cold-chain penetration in India and Southeast Asia. Acquisition targets should demonstrate certified manufacturing for marine or transit applications with underutilized capacity in Germany or South Korea. The signal to watch is EPA SNAP enforcement acceleration in additional US states beyond California and Washington.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Blown Formulation Transition | REACH compliance in Germany and Netherlands locks in specification advantages for early reformulators. |
| Marine Certification Investment | IMO SOLAS compliance opens premium positioning in South Korean and German shipyard procurement. |
| Data Center Channel Development | Direct engineering relationships with Northern Virginia hyperscalers capture liquid cooling insulation demand. |
| India Cold-Chain Integration | PLI scheme alignment subsidizes bundled refrigeration-insulation offerings in Maharashtra processing zones. |
| Backward Integration into Precursors | Captive acrylonitrile supply insulates margin stability from petrochemical feedstock volatility. |
Methodological Framework
A spread of perspectives from HVAC procurement directors, cold-chain logistics operators, marine classification surveyors, polymer chemists at formulation houses, and mechanical contractor estimators converged on the working assumptions around water-blown chemistry adoption timelines and regulatory phase-down impacts. Secondary validation drew from EU F-Gas Regulation implementation reports, EPA SNAP program dockets, ASHRAE 90.1 code revision documentation, and customs trade data for nitrile rubber precursor flows. Bottom-up segment sizing across product types, applications, and installation categories triangulated against top-down construction spending and HVAC equipment shipment data.
Segmentation dimensions modeled include closed-cell versus open-cell formulations, HVAC versus refrigeration versus marine applications, residential versus commercial versus industrial installation types, and nitrile rubber versus EPDM versus silicone material chemistry. CAGRs were derived from regression analysis of historical specification volumes against building energy code adoption curves and refrigerant phase-down schedules. Industry-specific forecast inputs incorporated cold-chain infrastructure investment pipelines in China and India, data center liquid cooling capex disclosures from hyperscale operators, and shipyard order backlogs for IMO SOLAS-certified vessels.
Material uncertainties — acrylonitrile price volatility, multi-jurisdiction certification timeline extensions, and EPDM substitution acceleration in UV-exposed applications — sit outside the modeled envelope and could compress growth trajectories or margin structures. Practitioners should keep alternative scenarios live as EPA SNAP state-level adoption patterns and EU F-Gas Regulation enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Global Elastomeric Coating Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
Europe Single-Ply Membrane Market