
 Green Chemical and Material Market | 2026-2036
Green Chemical and Material Market Size, Share, and Industry Trends Forecast 2026-2036
Green Chemical and Material Market Intelligence
Green bond issuance and sustainability-linked project finance is tilting competitive dynamics toward capital-rich incumbents. BASF SE leverages its integrated Verbund structure to secure preferential financing for bio-based polymer expansion. Evonik Industries AG anchors its position through specialty additive platforms that command premium pricing. Cargill Incorporated controls upstream agricultural feedstock supply, insulating margin pools from commodity volatility.
Green chemicals and materials encompass substances derived from renewable biomass, recycled waste streams, or carbon-capture processes, typically meeting biodegradability thresholds above sixty percent within one hundred eighty days under industrial composting conditions. Their primary purpose is substituting petroleum-derived inputs across manufacturing value chains without sacrificing functional performance. Biodegradable polymers dominate current volume flows, yet renewable surfactants are capturing disproportionate margin expansion in personal care and home cleaning formulations. Bio-based solvents remain supply-constrained relative to pharmaceutical-grade demand, creating pricing power for qualified producers. Natural fibers occupy a mature growth trajectory in textile manufacturing, with innovation concentrating on performance-engineered variants for technical applications.
REACH registration requirements and the EU Green Deal taxonomy are forcing reformulation timelines across European chemical manufacturing. The EPA's Safer Choice program and state-level extended producer responsibility laws in California and New York are converging toward stricter disclosure standards. China's MEE dual carbon enforcement and GB standard updates are accelerating domestic biorefinery investment. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to fragment supply chain economics for multinational producers.
Market Dynamics
REACH compliance deadlines and the EU Green Deal taxonomy are compressing reformulation timelines, forcing chemical manufacturers to requalify entire product portfolios before 2030 cutoffs.
Growth Catalysts
- EU Green Deal Taxonomy:Mandatory disclosure requirements under CSRD are redirecting institutional procurement toward certified bio-based feedstocks.
- Pharmaceutical-grade bio-solvents:Contract manufacturers in Germany and Switzerland are qualifying enzymatic synthesis routes for active pharmaceutical ingredient purification.
- Extended Producer Responsibility laws:California and New York state mandates are accelerating packaging material substitution timelines for consumer brands.
Market Restraints
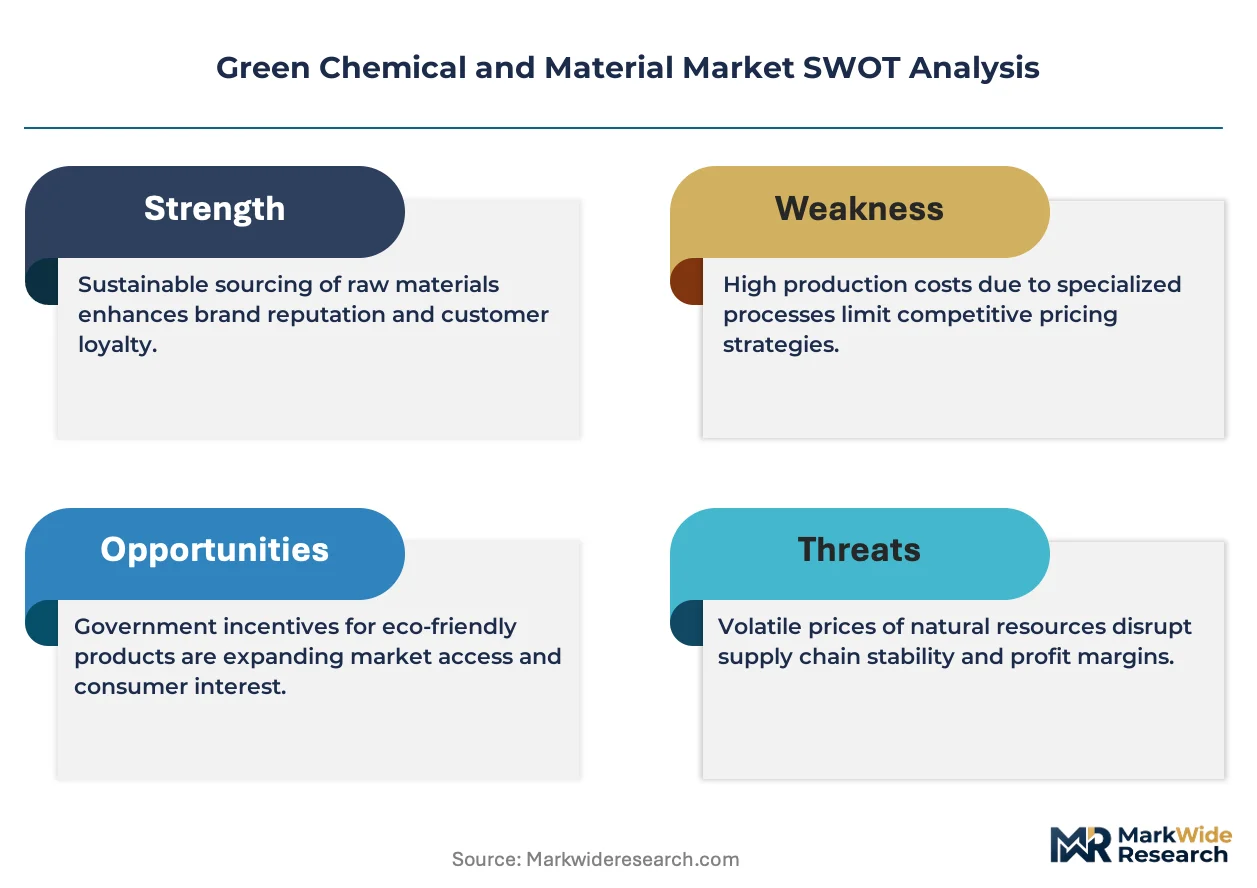
- Agricultural feedstock volatility:Corn and sugarcane price swings transmit directly to bio-polymer cost structures, compressing margin stability for non-integrated producers.
- Specialty additive supply concentration:German and Swiss chemical clusters control 70 percent of high-performance bio-based surfactant capacity.
- Technical performance gaps:Bio-based polyamides still exhibit moisture absorption rates 40 percent above petroleum equivalents in automotive underhood applications.
Strategic Opportunities
- India biorefinery buildout:PLI scheme subsidies and BIS standard harmonization are attracting capital for lignocellulosic ethanol-to-chemicals platforms.
- Carbon-capture feedstocks:Power-to-liquid methanol routes are qualifying for EU Green Deal taxonomy recognition in Nordic industrial clusters.
- Direct-to-brand distribution:Specialty additive producers are bypassing traditional distributors to capture formulation data from personal care OEMs.
Industry Challenges
- Industrial biotechnology talent scarcity:Fermentation scale-up expertise concentrates in Danish and Dutch university spinouts, creating hiring bottlenecks for new market entrants.
- Composting certification timelines:Industrial compostability validation under EN 13432 requires 180-day testing cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Chemical and Material Market |
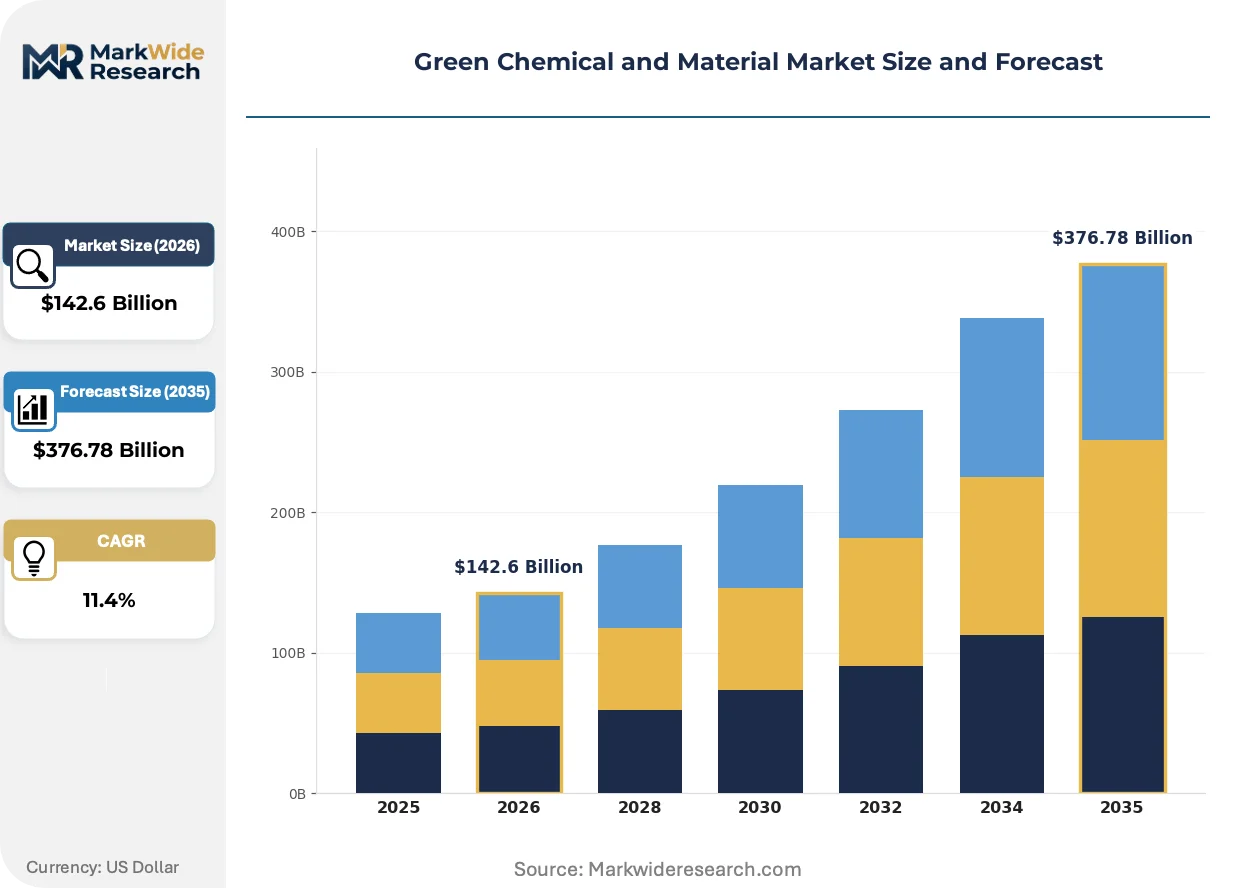
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $376.78 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
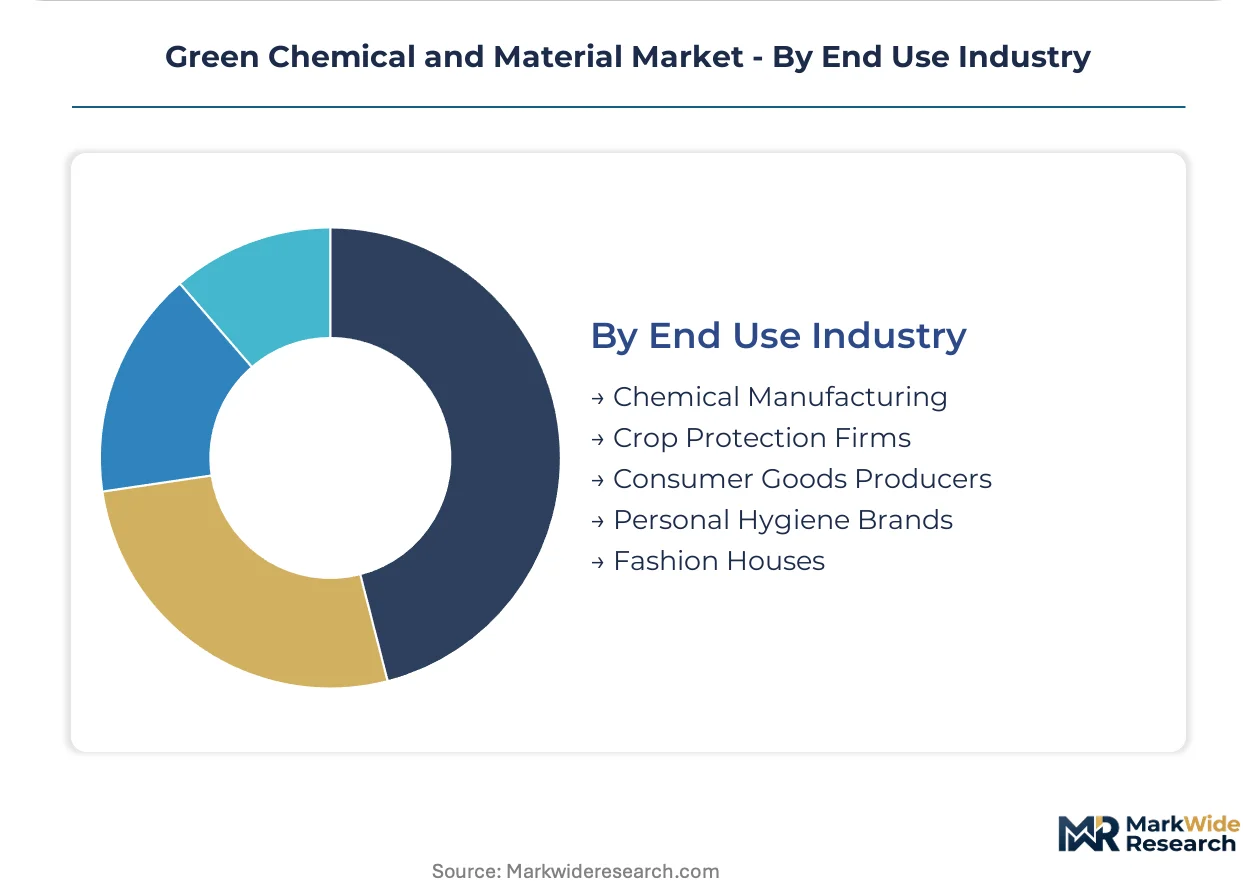
| Segmentation | Product Type: Biodegradable Polymers, Bio-based Solvents, Renewable Surfactants, Natural Fibers, Green Additives Grade: Industrial Grade, Pharmaceutical Grade, Food Grade, Agricultural Grade, Cosmetic Grade Application: Pharmaceuticals, Agriculture, Packaging Materials, Personal Care, Textile Manufacturing End Use Industry: Chemical Manufacturing, Crop Protection Firms, Consumer Goods Producers, Personal Hygiene Brands, Fashion Houses |
| Companies Covered | BASF SE, Evonik Industries AG, Koninklijke DSM N.V., DuPont de Nemours, Arkema Group, Dow Chemical, Solvay S.A., Cargill Incorporated, Braskem S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Chemical and Material Market Strategic Shifts & Innovations
Process intensification and digital twin deployment are compressing pilot-to-commercial timelines, while regulatory disclosure mandates are redefining competitive differentiation around verified lifecycle data.
Enzymatic polymerization platforms are digitizing process control across bio-based polyester production. Specialty chemical manufacturers in Germany and the Netherlands are deploying these systems to reduce batch variability by half. Real-time metabolic flux monitoring is digitizing yield optimization, collapsing the traditional 18-month strain improvement cycle to under six months.
REACH registration dossier requirements are tightening substance volume thresholds for bio-based intermediates. ECHA's 2024 updated guidance on substance identity for UVCB substances is forcing re-registration of complex bio-oil fractions. Personal care formulators are responding by consolidating supplier bases to reduce qualification burden.
Brand-led sustainability scorecards are displacing traditional specification-based procurement in consumer packaged goods. Unilever and Procter & Gamble are mandating cradle-to-gate carbon intensity disclosures from tier-two chemical suppliers. This pattern is most visible in European and North American home cleaning categories, where private label manufacturers face exclusion without certified feedstock documentation.
Green Chemical and Material Market Segmentation
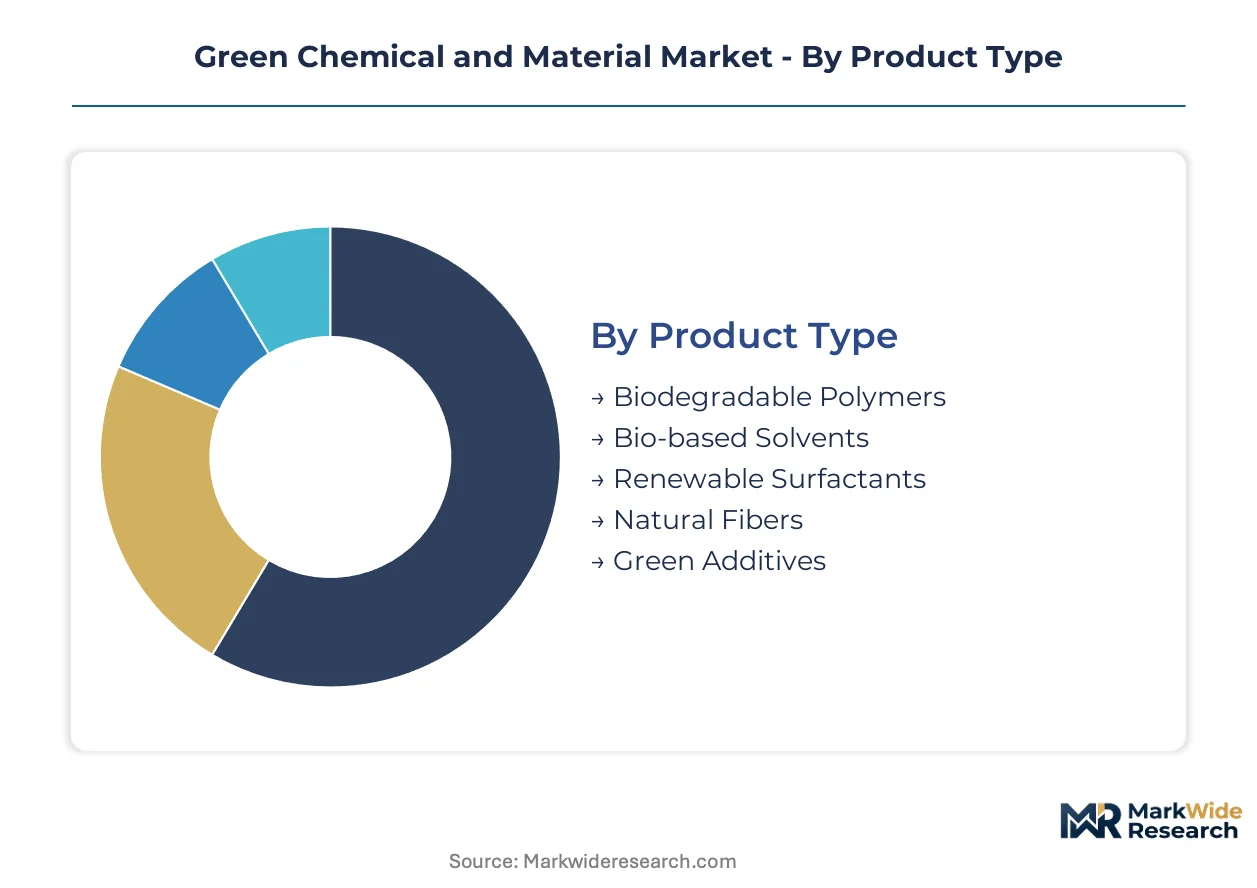
Segmentation in green chemicals and materials reveals how technical specifications, regulatory thresholds, and end-use performance requirements fragment procurement patterns across value chains. Buyers in pharmaceutical and personal care verticals impose certification standards that exclude commodity-grade suppliers, while packaging and agriculture segments prioritize cost-competitive biodegradability metrics.
Product Type:
After-sales technical support intensity varies sharply across product categories, with bio-based solvents and specialty additives requiring formulation troubleshooting that commodity polymers rarely demand.
- Biodegradable Polymers:Polyesters and polyhydroxyalkanoates engineered for industrial composting under EN 13432 protocols. Demand concentrates in German and French flexible packaging converters facing extended producer responsibility mandates. Agricultural feedstock price volatility transmits directly to resin cost structures.
- Bio-based Solvents:Ethyl lactate, bio-acetone, and terpene derivatives meeting pharmaceutical-grade purity specifications. Swiss and German contract manufacturers qualify these for active pharmaceutical ingredient extraction. Supply remains constrained relative to qualified demand.
- Renewable Surfactants:Alkyl polyglucosides and rhamnolipids derived from carbohydrate fermentation. Personal care formulators in North America specify these for sulfate-free product lines.
- Natural Fibers:Cellulose, hemp, and flax variants for technical textile reinforcement. Automotive lightweighting programs in Germany specify performance-engineered grades.
- Green Additives:Bio-based plasticizers, stabilizers, and rheology modifiers. REACH registration dossier complexity favors incumbent specialty chemical producers with regulatory affairs infrastructure.
Biodegradable polymers hold the largest share; momentum sits with renewable surfactants.
Grade:
Grade stratification reflects divergent purity thresholds and documentation burdens, with pharmaceutical and food grades commanding documentation premiums that industrial grades escape.
- Industrial Grade:Standard purity bio-based intermediates for bulk chemical synthesis. Chinese biorefinery expansions target this tier with lignocellulosic ethanol platforms.
- Pharmaceutical Grade:USP/EP-compliant solvents and excipients with full supply chain traceability. German and Swiss API manufacturers require batch-level carbon intensity disclosures.
- Food Grade:FDA and EFSA-registered packaging additives and processing aids. EU Green Deal taxonomy alignment is becoming a de facto procurement filter.
- Agricultural Grade:Bio-pesticide carriers and controlled-release fertilizer coatings. Indian PLI scheme subsidies are accelerating domestic capacity buildout.
- Cosmetic Grade:EC 1223/2009-compliant surfactants and emollients. Brand-led sustainability scorecards from Unilever and Procter & Gamble mandate cradle-to-gate certifications.
Industrial grade dominates volume flows; pharmaceutical grade captures the steepest margin expansion.
Application:
Application-level segmentation tracks how functional performance requirements and regulatory exposure shape formulation choices across end-use verticals.
- Pharmaceuticals:High-purity solvents for synthesis and purification. German contract manufacturers are qualifying enzymatic production routes to meet EPA Safer Choice and REACH dual requirements.
- Agriculture:Bio-stimulants, biodegradable mulch films, and controlled-release matrices. EU Farm-to-Fork strategy targets are accelerating substitution timelines for synthetic inputs.
- Packaging Materials:Flexible films, rigid containers, and barrier coatings with certified compostability. California and New York extended producer responsibility laws are forcing brand-level procurement shifts.
- Personal Care:Sulfate-free surfactants, natural emollients, and preservative systems. European and North American home cleaning categories show the most visible sustainability scorecard penetration.
- Textile Manufacturing:Natural fiber reinforcement and bio-based dye carriers. Technical applications in automotive and construction are outpacing commodity apparel demand.
Packaging materials command the widest adoption; pharmaceuticals show the most rigorous qualification barriers.
End Use Industry:
End-use industry segmentation exposes how buyer concentration and technical integration depth reshape supplier relationship economics.
- Chemical Manufacturing:Intermediate and specialty chemical producers integrating bio-based feedstocks into existing Verbund structures. BASF SE leverages this model for preferential green bond financing.
- Crop Protection Firms:Biological pesticide and adjuvant formulators seeking petroleum-input substitution. Regulatory pressure from EU Sustainable Use Regulation is tightening active substance approval pathways.
- Consumer Goods Producers:Home cleaning and packaged food brands with public sustainability commitments. CSRD disclosure requirements are redirecting institutional procurement toward certified bio-based sources.
- Personal Hygiene Brands:Baby care, feminine hygiene, and oral care manufacturers. Direct-to-brand distribution models are emerging as specialty additive producers bypass traditional distributors.
- Fashion Houses:Luxury and fast-fashion brands specifying natural fibers and bio-based textiles. Performance-engineered variants for technical applications command premium positioning.
Chemical manufacturing anchors volume demand; consumer goods producers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal taxonomy enforcement and state-level extended producer responsibility mandates are redirecting procurement flows toward certified bio-based feedstocks. Chemical manufacturers in Germany, China, and the United States face compressed reformulation timelines before 2030 regulatory cutoffs.
Germany
Automotive lightweighting programs and flexible packaging converter demand anchor bio-polymer consumption. REACH registration dossier requirements under ECHA's 2024 UVCB guidance are forcing re-registration of complex bio-oil fractions. The Rhine-Ruhr chemical cluster houses integrated Verbund producers expanding enzymatic polymerization capacity.
China
Domestic biorefinery investment accelerates under MEE dual carbon enforcement and updated GB standards. State-backed capital deployment targets lignocellulosic ethanol-to-chemicals platforms for industrial-grade intermediates. The Yangtze River Delta concentration includes fermentation scale-up facilities serving pharmaceutical-grade solvent demand.
United States
California and New York extended producer responsibility laws are forcing brand-level procurement shifts in packaging materials. EPA Safer Choice program alignment is becoming a de facto filter for home cleaning formulation suppliers. The Gulf Coast petrochemical corridor sees bio-based feedstock integration into existing steam cracker infrastructure.
India
PLI scheme subsidies and BIS standard harmonization are attracting capital for lignocellulosic ethanol platforms. Agricultural-grade bio-pesticide carriers and controlled-release fertilizer coatings dominate domestic demand. The Gujarat chemical belt hosts specialty additive producers targeting personal care export markets.
Switzerland
Contract manufacturers qualify enzymatic synthesis routes for active pharmaceutical ingredient purification. Swissmedic oversight and EP compliance requirements impose batch-level carbon intensity disclosure mandates. The Basel pharmaceutical cluster anchors high-purity bio-solvent demand for API extraction processes.
Green Chemical and Material Market Key Industry Players
On the supply side, the industry is consolidating around capital-rich incumbents with integrated feedstock control and regulatory affairs infrastructure. Three strategic archetypes dominate: diversified chemical conglomerates with Verbund advantages, agricultural processors with upstream biomass lock-in, and specialty additive specialists with formulation partnerships. Competitive moves concentrate on backward integration into agricultural supply and direct-to-brand distribution bypass.
Within the diversified chemical tier, BASF SE and Evonik Industries AG exemplify archetypes of integrated production and specialty platform dominance respectively. Cargill Incorporated anchors the agricultural processor vector with captive feedstock supply. These three occupy positions that reflect the market's structural tilt toward capital intensity and regulatory compliance scale.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Koninklijke DSM N.V. |
| DuPont de Nemours |
| Arkema Group |
| Dow Chemical |
| Solvay S.A. |
| Cargill Incorporated |
| Braskem S.A. |
| Others |
Cost & Logistics Intelligence
Agricultural feedstock concentration in the US Corn Belt and Brazilian sugarcane regions transmits directly to bio-polymer margin pools, with integrated processors capturing value that non-integrated compounders surrender to commodity volatility.
Pricing Analysis
Certification level under REACH and FDA food-contact tiers creates the primary spread between pharmaceutical-grade bio-solvents and industrial-grade intermediates. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales technical support intensity and batch-level carbon disclosure burdens. Pricing pressure stems from corn and sugarcane price swings transmitting to resin cost structures. Packaging converters show highest price sensitivity due to thin conversion margins, while Swiss API manufacturers absorb premiums for qualified supply.
Supply Chain Analysis
Export-control restrictions on fermentation scale-up technology and enzymatic polymerization platforms limit flows from Danish and Dutch university spinouts to new market entrants. Supply concentrates in Germany, China, and the United States for bio-based polymer production, with Switzerland anchoring pharmaceutical-grade solvent qualification. Raw material dependencies center on corn starch, sugarcane bagasse, and lignocellulosic feedstock supply. Single-source vulnerability runs through German and Swiss clusters controlling high-performance surfactant capacity. Distribution runs through direct-to-brand channels displacing traditional chemical distributors in personal care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among Unilever and Procter & Gamble tier-one suppliers is shifting bargaining power toward brand-led sustainability scorecards, fragmenting supplier bases that fail certification thresholds.
For Market Incumbents: Entrench through backward integration into agricultural feedstock supply and expansion of enzymatic polymerization capacity in the Rhine-Ruhr cluster. BASF SE's Verbund model demonstrates preferential green bond access that capital-constrained competitors cannot replicate. Defensive certification investment under ECHA's 2024 UVCB guidance preserves registration dossier advantages against requalification threats from emerging biorefinery platforms. For New Entrants and Emerging Players: Build out lignocellulosic ethanol-to-chemicals capacity in India under PLI scheme subsidies, where BIS standard harmonization reduces technical barriers relative to European REACH compliance. Agricultural-grade bio-pesticide carriers present the most penetrable segment given Indian domestic demand concentration and limited incumbent specialization. Direct-to-brand distribution models bypass entrenched distributor relationships in personal care formulations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty additive producers lacking regulatory affairs infrastructure to manage ECHA re-registration burdens. Long-term viability hinges on feedstock integration depth rather than formulation technology alone. Watch for EN 13432 composting certification timeline compression as signal of qualification bottleneck intensity affecting new product launch cadence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Cargill Incorporated's captive agricultural supply insulates margin pools from commodity volatility that erodes non-integrated compounders. |
| Enzymatic Polymerization Capacity Expansion | German and Dutch producers deploying digital twin systems halve batch variability and compress pilot-to-commercial timelines. |
| Direct-to-Brand Distribution Bypass | Specialty additive producers capturing formulation data from Unilever and Procter & Gamble displace traditional distributor relationships. |
| REACH Re-registration Investment | ECHA's 2024 UVCB guidance forces complex bio-oil fraction requalification that favors incumbents with regulatory affairs infrastructure. |
| India Biorefinery Buildout | PLI scheme subsidies and BIS harmonization attract capital for lignocellulosic platforms targeting agricultural-grade chemical demand. |
Research Approach
Cross-validation between primary interviews with plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors and secondary sources including customs/trade data, Cefic sector reports, and SEC 10-K filings anchors the qualitative findings. Bottom-up and top-down triangulation reconciles volume estimates from biorefinery capacity announcements with demand-side procurement surveys across packaging, pharmaceutical, and personal care verticals.
Calibration against historical price series for corn and sugarcane feedstocks, REACH registration timelines, and composting certification completion rates validates the analytical framework across the analysis window. Segmentation dimensions modeled include grade tier, end-use industry, application vertical, and regional production hub. CAGRs derive from regression against feedstock cost trajectories, regulatory mandate implementation schedules, and brand-led procurement policy adoption curves.
Stress conditions across agricultural commodity volatility bands, REACH enforcement intensity scenarios, and extended producer responsibility law expansion timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on fermentation scale-up talent availability and carbon-capture feedstock qualification progress. Material shifts in EU Green Deal taxonomy scope or MEE dual carbon enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Seaweed Biomass Waste Market
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Bio-Based Ethylene Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Renewable Chemicals Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Pyruvate Market