
 Silver Nanowires Market | 2026-2036
Silver Nanowires Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Nanowires Market Intelligence
ISO/TS 80004 nanotechnology terminology standards is reorganizing competitive entry in silver nanowires, forcing suppliers to document dimensional consistency and surface chemistry before qualifying for electronics procurement lists. C3Nano leverages its wet chemical synthesis platform to supply roll-to-roll compatible inks for flexible display makers. Cambrios Technologies Corporation anchors North American demand through vapor deposition partnerships with touch sensor integrators. Guangzhou Hongwu Material Technology Co., Ltd. dominates wet chemical output volumes for Asian conductive film manufacturers.
Silver nanowires are elongated metallic structures with diameters below 100 nanometers and aspect ratios exceeding 100:1, typically synthesized via polyol reduction or template-assisted growth to achieve percolation networks at low optical haze. They function as transparent conductors in optoelectronic stacks where indium tin oxide fails under mechanical strain. Wet chemical methods lead production economics for consumer electronics scale, while vapor deposition commands premium positioning in aerospace components requiring atomic-level thickness control. Chemical vapor deposition represents the fastest-growing technology segment as solar cell manufacturers seek conformal coating uniformity on textured silicon surfaces.
EPA oversees nanoscale silver registration under the Toxic Substances Control Act, creating pre-market notification burdens that filter out uncapitalized entrants. REACH substance evaluation in Europe mandates full life-cycle toxicity dossiers for nanowire formulations above 100 kilograms annual tonnage. China's GB standards for nanomaterials labeling, administered by SAMR, impose mandatory disclosure of aspect ratio distributions on import declarations. Stakeholders must track how dual carbon goals in Beijing reshape energy storage procurement criteria for conductive additives before committing capacity expansion plans.
Market Dynamics
ISO/TS 80004 nanotechnology terminology standards is forcing dimensional documentation requirements that filter uncapitalized suppliers from electronics procurement lists. Wet chemical synthesis platforms face qualification pressure as vapor deposition methods capture aerospace conformal coating contracts.
Growth Catalysts
- OLED panel integration:South Korean display foundries are embedding silver nanowire films into flexible substrate stacks. This creates pull-through demand for roll-to-roll compatible conductive inks.
- REACH substance evaluation:European material purity thresholds for nanoscale silver imports are tightening competitive entry. Compliant suppliers gain preferential positioning in EU electronics supply chains.
- Polyol reduction synthesis:Wet chemical methods achieve percolation networks at low optical haze for consumer electronics scale. Production economics favor this route over template-assisted growth for touchscreen volumes.
Market Restraints
- Indium tin oxide substitution resistance:Established ITO supply chains and sputtering infrastructure create switching friction for display manufacturers. Capital depreciation schedules lock in legacy transparent conductor choices.
- South Korean supply concentration:Display panel foundry demand clusters in a single geography. Geographic demand pooling exposes pricing power asymmetries and logistics vulnerability.
- EPA TSCA pre-market notification:Nanoscale silver registration burdens filter out undercapitalized entrants. Compliance costs create structural barriers below certain revenue thresholds.
Strategic Opportunities
- Solar cell textured silicon coating:Chemical vapor deposition methods offer conformal uniformity on non-planar photovoltaic surfaces. This application segment remains underpenetrated relative to display markets.
- China dual carbon goals:Beijing's energy storage procurement criteria are reshaping conductive additive specifications. Domestic battery manufacturers face mandate pressure to qualify nanowire-enhanced electrodes.
- Flexible display substrate convergence:Silver nanowire-PDMS composite integration with micro-LED transfer printing creates new stack architecture possibilities. Hybrid material platforms open device form factor innovation.
Industry Challenges
- Aspect ratio distribution characterization:SAMR-mandated GB standards disclosure requirements demand precision metrology capabilities. Laboratories must certify batch-to-batch geometric consistency for import clearance.
- Surface chemistry reproducibility:Polyol reduction batch variability affects percolation threshold and optical haze. Process control standardization across multi-site manufacturing remains unresolved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Nanowires Market |
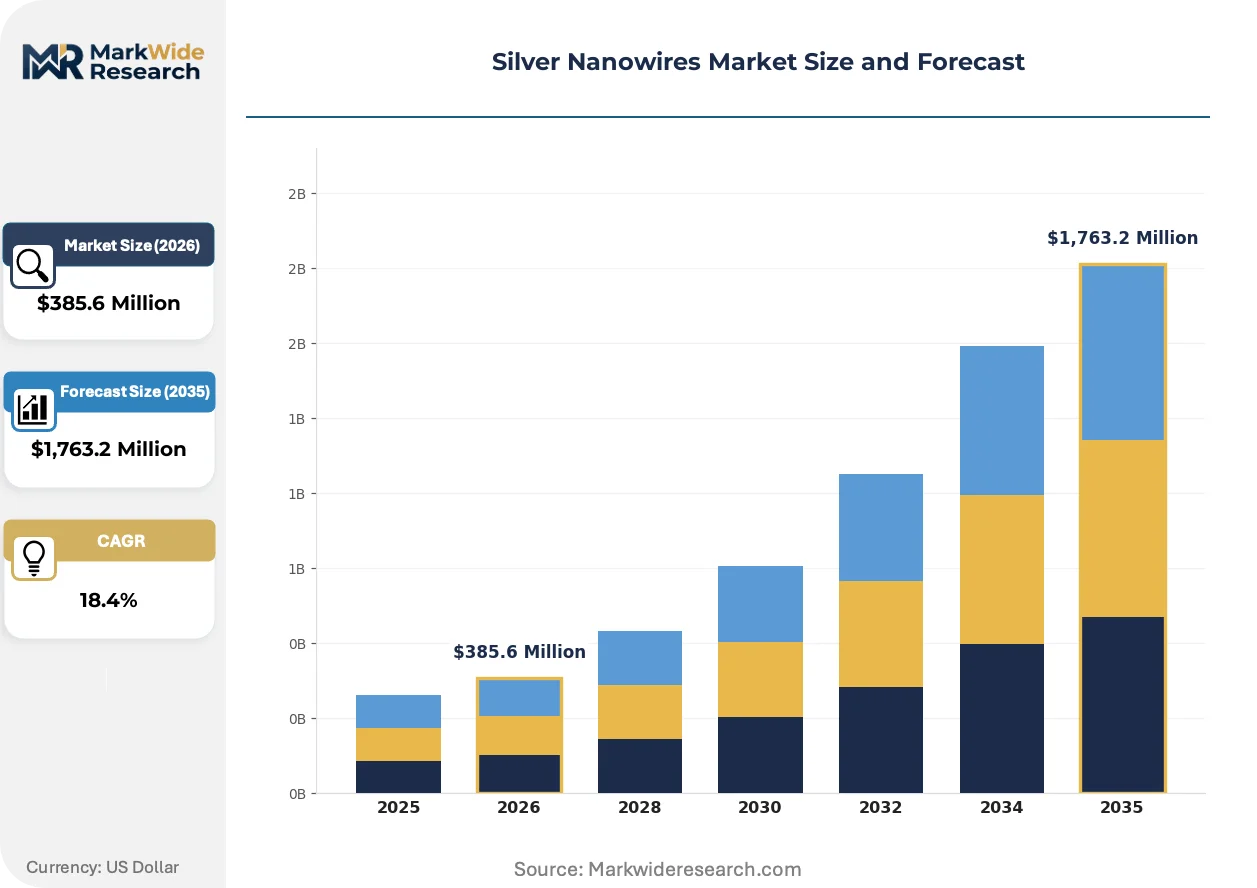
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,763.2 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sintered Nanowires, Electrospun Nanowires, Wet Chemical, Template-Assisted, Others Technology: Spray Coating, Spin Coating, Inkjet Printing, Vapor Deposition, Chemical Vapor Deposition Application: Touchscreen Displays, Wearable Electronics, Thin Film Heaters, Solar Cells, Conductive Films End User Industry: Consumer Electronics, Optical Devices Manufacturing, Energy Storage, Aerospace Components, Textile Manufacturing |
| Companies Covered | Novarials Corporation, C3Nano, DuPont de Nemours, Inc., Nanopyxis, Blue Nano, TPK Holding, Cambrios Technologies Corporation, Guangzhou Hongwu Material Technology Co., Ltd., ACS Material, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Nanowires Market Strategic Shifts & Innovations
Wet chemical synthesis platforms are compressing production timelines while regulatory documentation requirements are extending qualification cycles. These opposing forces are reshaping supplier competitive positioning.
Template-assisted growth methods are miniaturizing diameter control below 50 nanometers for aerospace electromagnetic shielding applications. Satellite component manufacturers in the United States are adopting these structures for atomic-level thickness specifications. The technology is miniaturizing feature precision that vapor deposition previously monopolized, opening mid-tier supplier participation in defense-adjacent contracts.
ECHA substance evaluation protocols under REACH are mandating full life-cycle toxicity dossiers for nanowire formulations above 100 kilograms annual tonnage. European electronics assemblers now require upstream documentation of surface ligand chemistry and dissolution kinetics. German automotive touch sensor integrators are responding by consolidating supplier bases to those with established registration dossiers.
Flexible display procurement is consolidating around specification bundles that combine optical transmittance, sheet resistance, and mechanical bend cycle thresholds. South Korean panel foundries are unbundling traditional ITO sputtering contracts into separate nanowire ink and coating equipment vendor relationships. This pattern is most visible in Gyeonggi-do cluster procurement where multi-source qualification is replacing single-supplier ITO dependence.
Silver Nanowires Market Segmentation
Silver nanowire suppliers navigate divergent qualification requirements across display, energy, and aerospace verticals. Channel strategy shifts dramatically between wet chemical bulk supply and vapor deposition precision contracting.
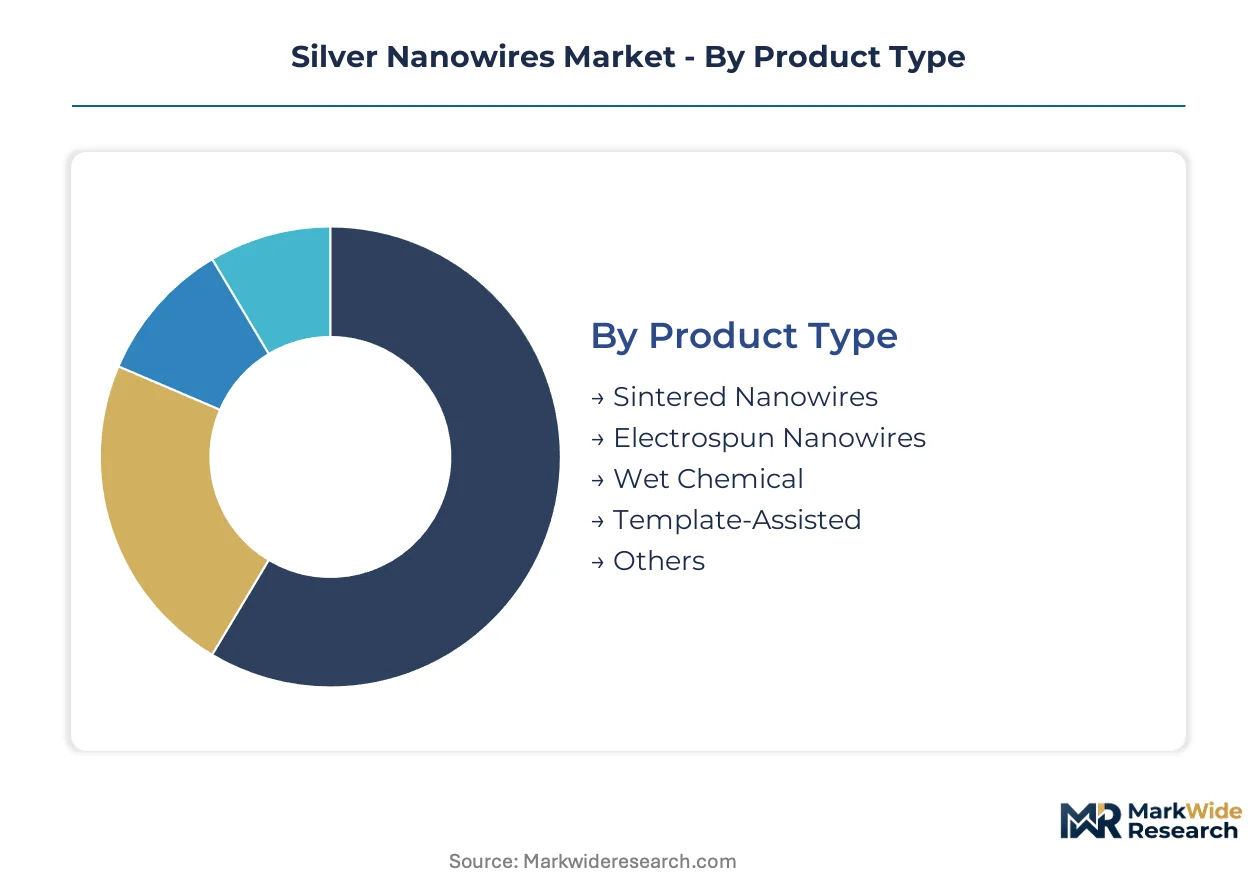
Product Type:
Wet chemical synthesis flows through roll-to-roll coating houses serving display makers, while template-assisted growth routes through aerospace prime contractors demanding atomic-level certification.
- Wet Chemical:Polyol reduction achieves percolation networks below 100 nanometers diameter with aspect ratios exceeding 100:1. South Korean OLED foundries in Gyeonggi-do cluster pull this material through multi-source ink qualification programs, displacing legacy ITO sputtering contracts.
- Template-Assisted:Porous membrane templating delivers sub-50 nanometer diameter control for electromagnetic shielding specifications. United States satellite component manufacturers specify these structures for conformal coating on non-planar antenna substrates, with vapor deposition suppliers capturing premium positioning.
- Sintered Nanowires:Thermal consolidation creates fused junction networks for textile-integrated heating elements.
- Electrospun Nanowires:Electric field-driven spinning produces non-woven mats for filtration membrane substrates.
- Others:Emerging seed-mediated growth variants for specialized optical coating applications.
By volume, Wet Chemical leads. By growth pace, Template-Assisted is ahead.
Technology:
Application cost tiers separate high-throughput coating from precision deposition, with solar cell manufacturers driving adoption at the premium end.
- Chemical Vapor Deposition:Conformal coating uniformity on textured silicon photovoltaic surfaces achieves atomic-level thickness control. Solar cell manufacturers in China seek this technology for passivated contact architectures under dual carbon procurement mandates.
- Vapor Deposition:Physical vapor methods command aerospace electromagnetic shielding contracts requiring traceable thickness documentation. German automotive touch sensor integrators specify these coatings for dashboard human-machine interfaces.
- Spray Coating:Aerosol deposition enables rapid area coverage for large-format display substrates.
- Spin Coating:Centrifugal spreading delivers uniform thin films for laboratory-scale device prototyping.
- Inkjet Printing:Drop-on-demand patterning supports custom electrode geometries for wearable form factors.
By installed base, Spray Coating dominates. By expansion trajectory, Chemical Vapor Deposition climbs the fastest.
Application:
Customer maturity separates qualified display supply chains from emerging energy storage adoption.
- Touchscreen Displays:Silver nanowire-PDMS composite stacks replace ITO on flexible substrates for foldable smartphone architectures. South Korean panel foundries unbundle traditional sputtering contracts into separate ink and equipment vendor relationships.
- Solar Cells:Textured silicon coating demands conformal deposition uniformity that chemical vapor methods uniquely provide. Chinese photovoltaic manufacturers face procurement pressure to qualify nanowire-enhanced electrodes.
- Wearable Electronics:Stretchable conductor requirements for fitness tracker form factors.
- Thin Film Heaters:Transparent conductive heating for automotive defrosting applications.
- Conductive Films:General-purpose transparent electrode substrates for emerging optoelectronic devices.
By revenue concentration, Touchscreen Displays leads. By qualification momentum, Solar Cells is gaining share fastest.
End User Industry:
Supply concentration in consumer electronics contrasts with fragmented qualification across industrial verticals.
- Consumer Electronics:Display and wearable device manufacturers concentrate procurement in South Korea and China. ISO/TS 80004 dimensional documentation requirements filter uncapitalized suppliers from electronics procurement lists.
- Energy Storage:Battery electrode additive specifications reshape under Beijing's dual carbon goals. Domestic Chinese manufacturers face mandate pressure to qualify conductive nanowire formulations.
- Optical Devices Manufacturing:Precision coating requirements for camera and sensor windows.
- Aerospace Components:Satellite electromagnetic shielding with atomic-level thickness specifications.
- Textile Manufacturing:Wearable heating and sensing integration for smart apparel.
By procurement scale, Consumer Electronics leads. By policy tailwinds, Energy Storage shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel manufacturers concentrate procurement in three economies, with chemical synthesis suppliers following foundry location decisions. Regulatory divergence across EPA, REACH, and SAMR jurisdictions filters market entry by documentation capability.
United States
EPA TSCA pre-market notification requirements for nanoscale silver create structural barriers for uncapitalized entrants. Satellite component manufacturers in California and Arizona specify template-assisted nanowires for electromagnetic shielding on non-planar antenna substrates. Vapor deposition suppliers capture premium aerospace contracts requiring atomic-level thickness documentation.
South Korea
OLED panel foundries in the Gyeonggi-do cluster drive pull-through demand for roll-to-roll compatible conductive inks. MFDS nanomaterial safety guidelines align with ISO/TS 80004 dimensional documentation standards for electronics procurement qualification. Samsung and LG Display operations in Paju and Tangjeong unbundle traditional ITO sputtering into separate ink and equipment vendor relationships.
China
Dual carbon procurement mandates reshape battery electrode additive specifications for domestic energy storage manufacturers. SAMR-administered GB standards impose mandatory aspect ratio distribution disclosure on nanomaterial import declarations. Photovoltaic producers in Jiangsu and Zhejiang provinces seek chemical vapor deposition methods for conformal coating on textured silicon surfaces.
Germany
ECHA REACH substance evaluation mandates full life-cycle toxicity dossiers for nanowire formulations above 100 kilograms annual tonnage. Automotive touch sensor integrators specify vapor deposition coatings for dashboard human-machine interfaces. Bavarian electronics assemblers consolidate supplier bases to those with established registration dossiers and surface ligand chemistry documentation.
Japan
METI industrial nanotechnology roadmaps prioritize transparent conductor development for flexible display applications. JIS standards for nanomaterial characterization support ISO/TS 80004 alignment in electronics supply chains. Precision coating houses in the Kansai region supply optical device manufacturers with sheet resistance and mechanical bend cycle certification.
Silver Nanowires Market Key Industry Players
Player mix skews toward wet chemical synthesis specialists and vapor deposition precision contractors. Three tiers structure participation: multinational chemical conglomerates with nanomaterial divisions, dedicated nanowire synthesis firms, and regional coating service providers. Consolidation pressure favors suppliers with simultaneous ISO/TS 80004 documentation capability and multi-site manufacturing scale. Strategic moves center on backward integration into polyol precursor supply and geographic co-location with display foundry clusters.
Within the wet chemical synthesis tier, C3Nano and Guangzhou Hongwu Material Technology Co., Ltd. exemplify roll-to-roll ink supply positioning for flexible display makers. Cambrios Technologies Corporation occupies a distinct position on the vapor deposition vector, anchoring North American demand through touch sensor integration partnerships. DuPont de Nemours, Inc. represents the diversified chemical conglomerate archetype, leveraging existing electronics materials distribution infrastructure across multiple transparent conductor technologies.
| Leading Market Players |
|---|
| Novarials Corporation |
| C3Nano |
| DuPont de Nemours, Inc. |
| Nanopyxis |
| Blue Nano |
| TPK Holding |
| Cambrios Technologies Corporation |
| Guangzhou Hongwu Material Technology Co., Ltd. |
| ACS Material, LLC |
| Others |
Cost & Logistics Intelligence
Indium tin oxide displacement by silver nanowire formulations simultaneously redraws procurement geography toward South Korean display clusters and compresses pricing premiums previously anchored to sputtering equipment depreciation schedules. This substitution dynamic concentrates buyer power among OLED foundries while fragmenting supplier tiers between wet chemical bulk providers and vapor deposition precision contractors.
Pricing Analysis
Cost-plus contracts with silver nitrate indexation dominate procurement between wet chemical suppliers and roll-to-roll coating houses serving Gyeonggi-do display foundries. Price differentiation rests on ISO/TS 80004 dimensional documentation tier and vapor deposition certification for aerospace applications. Cost compression in wet chemical synthesis is intensifying because polyol reduction batch standardization remains unresolved across multi-site manufacturing. Display panel manufacturers exhibit highest price sensitivity, while satellite component integrators tolerate premium positioning for atomic-level thickness traceability.
Supply Chain Analysis
China and South Korea anchor wet chemical nanowire output for consumer electronics scale, with the United States capturing vapor deposition precision for aerospace and defense-adjacent contracts. Silver nitrate precursor supply draws from established precious metals refining corridors, while polyol reduction reagents and templating membranes feed from specialty chemical distributors. Single-source vulnerability concentrates in South Korean display foundry demand pooling, exposing logistics disruption risk from regional shipping chokepoints. Distribution runs through qualified ink formulation houses co-located with roll-to-roll coating equipment vendors near panel manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision metrology capabilities for aspect ratio distribution certification represent the binding constraint separating qualified suppliers from procurement list exclusions. Documented surface ligand chemistry and dissolution kinetics dossiers constitute scarce assets that consolidation pressure will increasingly concentrate among capitalized incumbents.
For Market Incumbents: Consolidate supplier bases through backward integration into polyol precursor supply and captive metrology laboratory certification. C3Nano and Cambrios Technologies Corporation demonstrate defensible positioning through co-location with Gyeonggi-do foundry clusters and vapor deposition partnerships with touch sensor integrators respectively. Threat from template-assisted growth miniaturization below 50 nanometers demands R&D investment in diameter control precision to retain aerospace contract access. For New Entrants and Emerging Players: Solar cell textured silicon coating services represent the most penetrable white-space where chemical vapor deposition methods remain underqualified relative to display market saturation. Chinese photovoltaic manufacturers under dual carbon procurement mandates face mandate pressure to qualify nanowire-enhanced electrodes, creating entry opportunity for conformal coating specialists. Go-to-market positioning should emphasize atomic-level thickness uniformity documentation rather than commodity ink volume competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wet chemical synthesis platforms lacking ISO/TS 80004 documentation capability for electronics procurement qualification. Long-term viability across the projection horizon favors suppliers with simultaneous multi-site manufacturing scale and established REACH registration dossiers. Signal to watch is ECHA substance evaluation protocol expansion tightening tonnage thresholds for nanowire formulation imports into European electronics supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Precursor Supply | C3Nano secures reagent cost stability and batch consistency for roll-to-roll ink production. |
| ISO/TS 80004 Metrology Laboratory Certification | Guangzhou Hongwu qualifies for Samsung and LG Display procurement lists through dimensional documentation. |
| Vapor Deposition Partnership with Touch Sensor Integrators | Cambrios Technologies anchors North American aerospace electromagnetic shielding contract flow. |
| REACH Registration Dossier Investment | DuPont consolidates German automotive touch sensor supply through ECHA-compliant surface chemistry documentation. |
| Geographic Co-location with Gyeonggi-do Foundry Cluster | TPK Holding reduces logistics vulnerability from South Korean demand concentration through proximity positioning. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs trade records, and SAMR-administered GB standards documentation for nanomaterial import declarations. Primary interviews engaged nanowire synthesis plant managers, procurement leads at South Korean display panel OEMs, distribution channel partners supplying roll-to-roll coating houses, and technical R&D directors at vapor deposition equipment vendors. Bottom-up volume modeling from qualified supplier capacity statements triangulates against top-down demand aggregation from OLED foundry procurement disclosures.
Segmentation dimensions modeled span synthesis method, deposition technology, application vertical, and end-user industry across the analysis window. CAGRs derive from weighted average of capacity expansion announcements, foundry capital expenditure trajectories, and regulatory compliance cost absorption curves. Industry-specific forecast inputs include MFDS nanomaterial safety guideline alignment timelines and Beijing dual carbon procurement mandate implementation pacing for energy storage electrode specifications.
Forecasts assume regulatory continuity in EPA TSCA pre-market notification requirements, ECHA REACH substance evaluation protocols, and SAMR GB standards enforcement; material policy shifts would require re-modeling of supplier qualification timelines and import clearance documentation burdens. Recalibration cycles align with material shifts in display foundry unbundling patterns and photovoltaic manufacturer nanowire electrode adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Superconducting Materials Market
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
US Graphene Market
Advanced Materials
Corundum Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Curable Materials Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
Global Graphene Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market