
 Global Conductive Inks Market | 2026-2036
Global Conductive Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Conductive Inks Market Intelligence
A shift from single-source supplier agreements to multi-sourcing strategies by large consumer electronics manufacturers is broadening the competitive landscape. DuPont de Nemours, Inc. leverages its extensive material science portfolio to serve high-volume clients in the printed electronics space. Henkel AG & Co. KGaA differentiates through integrated adhesive and thermal management properties in its conductive ink products. Meanwhile, specialists such as Creative Materials Inc. cater to niche, high-performance applications requiring custom formulations.
Conductive inks are specialized materials that contain conductive particles, like silver or carbon, suspended in a polymer binder for deposition. They are formulated for printing circuits onto various substrates, enabling the creation of flexible and lightweight electronic components. Silver-based inks dominate in terms of performance and market value, while the carbon-based segment offers a cost-effective alternative for applications like RFID tags. Screen printing remains a prevalent technology for mass production, but inkjet printing is gaining traction for prototyping and customized manufacturing runs.
The European Union's RoHS directive restricts hazardous substances in electronics, influencing the formulation of inks to use lead-free and halogen-free materials. In the United States, EPA regulations on volatile organic compounds (VOCs) affect solvent-based ink manufacturing and application processes. Material selection will increasingly balance performance requirements against a complex and diverging set of international environmental compliance standards for electronic components.
Market Dynamics
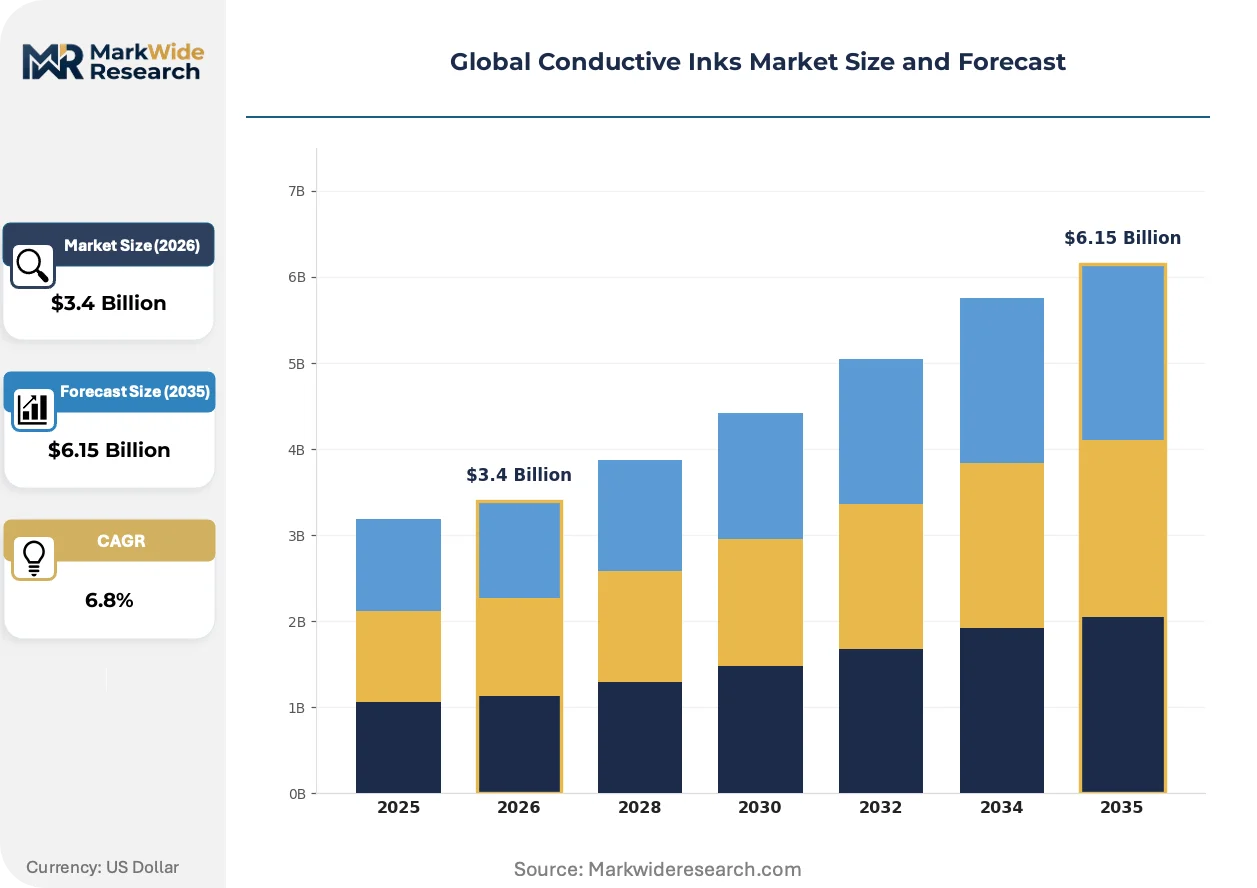
The primary force shaping the market is the need to balance performance against cost, driven by the expansion of printed electronics into both high-value wearables and cost-sensitive applications like RFID tags, forcing formulation diversification.
Growth Catalysts
- Wearable Devices:Growth in flexible electronics for wearables demands advanced inks compatible with non-rigid substrates, driving formulation innovation and volume.
- EU's RoHS Directive:This regulation mandates lead-free materials in electronics, creating a strong preference for compliant, advanced ink formulations.
- Carbon Ink Viability:Cost-effective carbon inks enable high-volume applications like RFID tags, which are too price-sensitive for silver-based alternatives.
Market Restraints
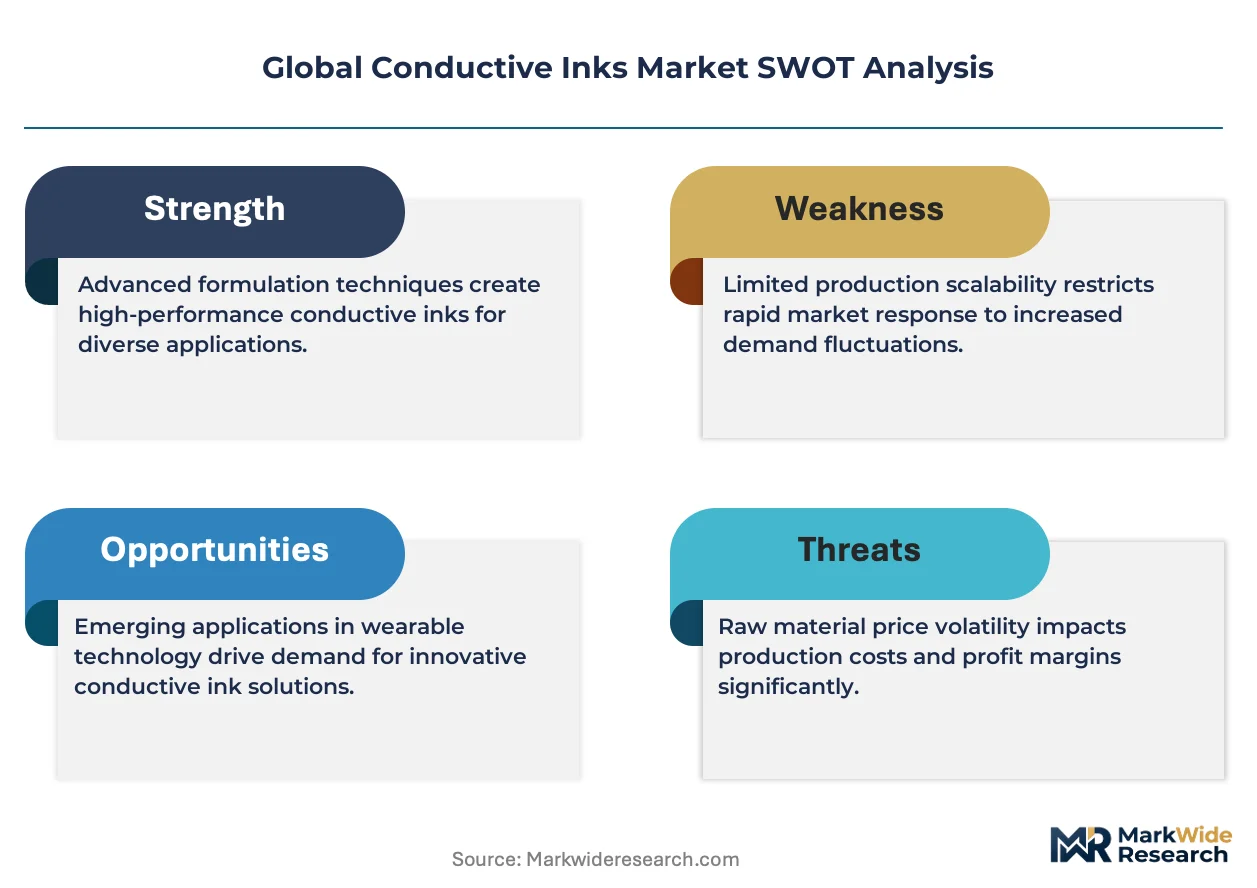
- Silver Price Volatility:As a primary raw material, fluctuating silver commodity prices create cost instability for manufacturers of high-performance inks.
- Performance Trade-offs:Cheaper carbon-based inks have lower conductivity compared to silver, limiting their use in high-performance electronic applications.
- Substrate Compatibility:Ensuring reliable adhesion and electrical performance on diverse substrates, particularly new flexible polymers, remains a persistent technical challenge.
Strategic Opportunities
- Inkjet Printing Technology:Adoption of inkjet for prototyping and custom manufacturing allows for on-demand, low-volume production, creating new service-based business models.
- Biomedical Applications:The need for disposable diagnostic sensors and wearable health monitors creates a high-value market for biocompatible conductive inks.
- Stretchable Formulations:Developing inks for highly elastic substrates opens opportunities in advanced wearables and soft robotics that require conformable electronic circuits.
Industry Challenges
- Diverging Regulations:Formulators must navigate a complex set of environmental rules, such as the EU's RoHS directive and the US EPA's limits on volatile organic compounds.
- Process Control:Maintaining consistent line width, thickness, and resistivity during high-speed screen printing for mass production remains a significant operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Conductive Inks Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver-Based, Carbon-Based, Copper-Based, Graphene-Based, Polymer-Based Technology: Screen Printing, Inkjet Printing, Gravure Printing, Flexography, Aerosol Jet Printing Application: Printed Electronics, RFID Tags, Touch Panels, Solar Cells, Wearable Devices End User: Consumer Electronics Manufacturers, Aerospace Integrators, Defense Contractors, Telecommunications Vendors, Textile Producers |
| Companies Covered | DuPont de Nemours, Inc., Henkel AG & Co. KGaA, Sun Chemical Corporation, Heraeus Holding GmbH, NovaCentrix, PPG Industries, Inc., Johnson Matthey Plc, Creative Materials Inc., Vorbeck Materials Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Conductive Inks Market Strategic Shifts & Innovations
Formulation science is adapting to new manufacturing realities and stricter environmental oversight. The evolution of conductive inks is now tied to the adoption of novel deposition techniques and the global push for greener electronics manufacturing processes.
Inkjet printing enables the precise, digital deposition of conductive materials without masks or screens. Prototyping labs and specialty electronics manufacturers are adopting this technology for rapid-turnaround and customized jobs. This capability is decentralizing circuit fabrication from high-volume factories to smaller, agile design-and-build operations.
The European Union’s REACH regulation imposes stringent requirements on the chemical substances used in manufacturing. This directly impacts conductive ink formulations, mandating extensive safety data and registration for solvents, binders, and additives. Ink producers targeting the EU must invest in compliance and reformulate products to phase out substances of very high concern.
A clear shift toward multi-sourcing strategies is underway among large consumer electronics manufacturers to reduce supply chain risk. This move away from single-supplier agreements for critical materials like conductive inks introduces greater competition among formulators. This pattern is most visible within the high-volume smartphone assembly clusters located in China and Vietnam.
Global Conductive Inks Market Segmentation
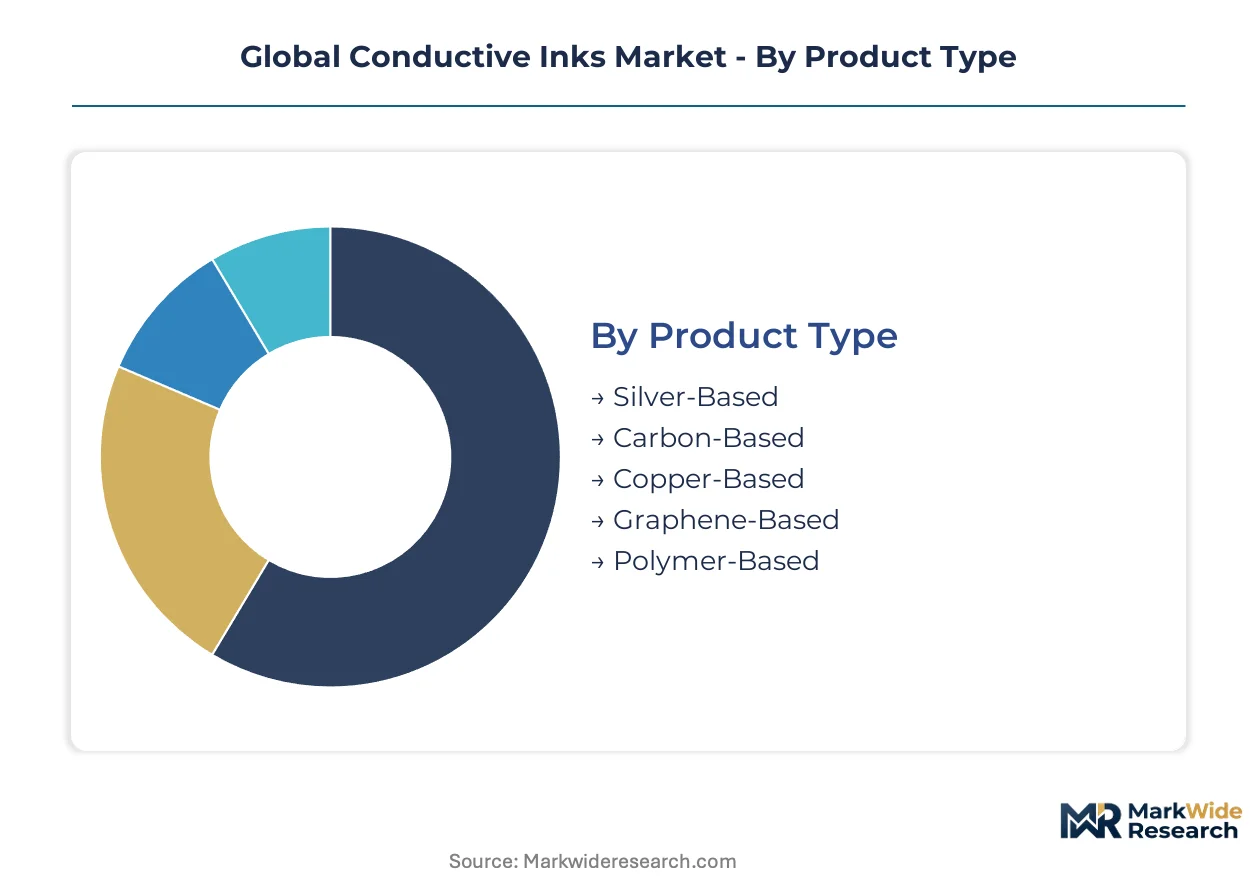
Conductive inks demonstrate functional versatility across diverse electronic applications. Segmentation analysis delineates the distinct material compositions, manufacturing techniques, target applications, and end-user profiles that define this specialized market. Understanding these segments reveals where value concentrates and where innovation drives future expansion.
Product Type:
The market for conductive inks exhibits a clear division between high-performance, premium materials and cost-effective, high-volume alternatives.
- Silver-Based:These inks utilize silver particles suspended in a polymer binder, offering superior electrical conductivity and thermal stability. Demand concentrates in high-performance flexible electronics for applications in South Korea and Japan, where miniaturization and reliability are critical.
- Carbon-Based:Comprising carbon nanotubes or graphite flakes, these inks provide a cost-effective alternative with adequate conductivity for less demanding applications. High-volume production for RFID tags in China drives significant material consumption due to price sensitivity.
- Copper-Based:Copper-based inks offer a balance of conductivity and cost, serving as an alternative to silver in certain applications.
- Graphene-Based:Leveraging graphene's unique properties, these inks provide excellent conductivity and mechanical flexibility for advanced research and niche products.
- Polymer-Based:These formulations use conductive polymers, offering inherent flexibility and transparency for specialized display and sensor applications.
Today's leader: Silver-Based. Tomorrow's challenger: Graphene-Based.
Technology:
Deposition techniques determine the precision, speed, and cost efficiency of circuit fabrication, directly influencing manufacturing scalability.
- Screen Printing:This established method uses a mesh screen to transfer ink onto a substrate, enabling high-speed, mass production of circuits. It remains prevalent in electronics manufacturing clusters in China for cost-efficient, large-volume circuit boards.
- Inkjet Printing:A digital, non-contact method, inkjet printing precisely deposits ink droplets, allowing for rapid prototyping and customized, low-volume manufacturing runs. This technology gains traction in Germany and the United States for advanced sensor development.
- Gravure Printing:Gravure printing utilizes an engraved cylinder for high-speed, roll-to-roll production of fine lines and patterns on flexible substrates.
- Flexography:This rotary printing technique employs a flexible relief plate, suitable for high-volume printing on various flexible materials like films and foils.
- Aerosol Jet Printing:Aerosol jet printing deposits fine aerosolized ink droplets with high resolution, ideal for 3D structures and non-planar surfaces in specialized applications.
Screen Printing dominates current production volumes, while Inkjet Printing is expanding most quickly for new applications.
Application:
End-use applications dictate the specific performance requirements and material properties for conductive inks, from flexibility to conductivity thresholds.
- Wearable Devices:Conductive inks enable the creation of flexible and conformable circuits for smartwatches, fitness trackers, and smart textiles. This application drives innovation in stretchable and biocompatible ink formulations in the United States and Europe.
- RFID Tags:These inks form the antennas and circuitry for radio-frequency identification tags, crucial for inventory management and logistics. The expansion of supply chain tracking in China and India creates substantial demand for cost-effective carbon inks.
- Printed Electronics:This broad category encompasses various electronic components fabricated using printing techniques, including sensors and flexible displays.
- Touch Panels:Conductive inks are essential for creating transparent electrodes and interconnects in touch-sensitive interfaces for consumer electronics.
- Solar Cells:Inks are used to form conductive grids and electrodes in photovoltaic devices, enhancing efficiency and reducing manufacturing costs.
Wearable Devices currently command significant innovation, with RFID Tags driving substantial volume demand.
End User:
The diverse range of end-user industries reflects the broad utility of conductive inks, each with unique procurement patterns and product specifications.
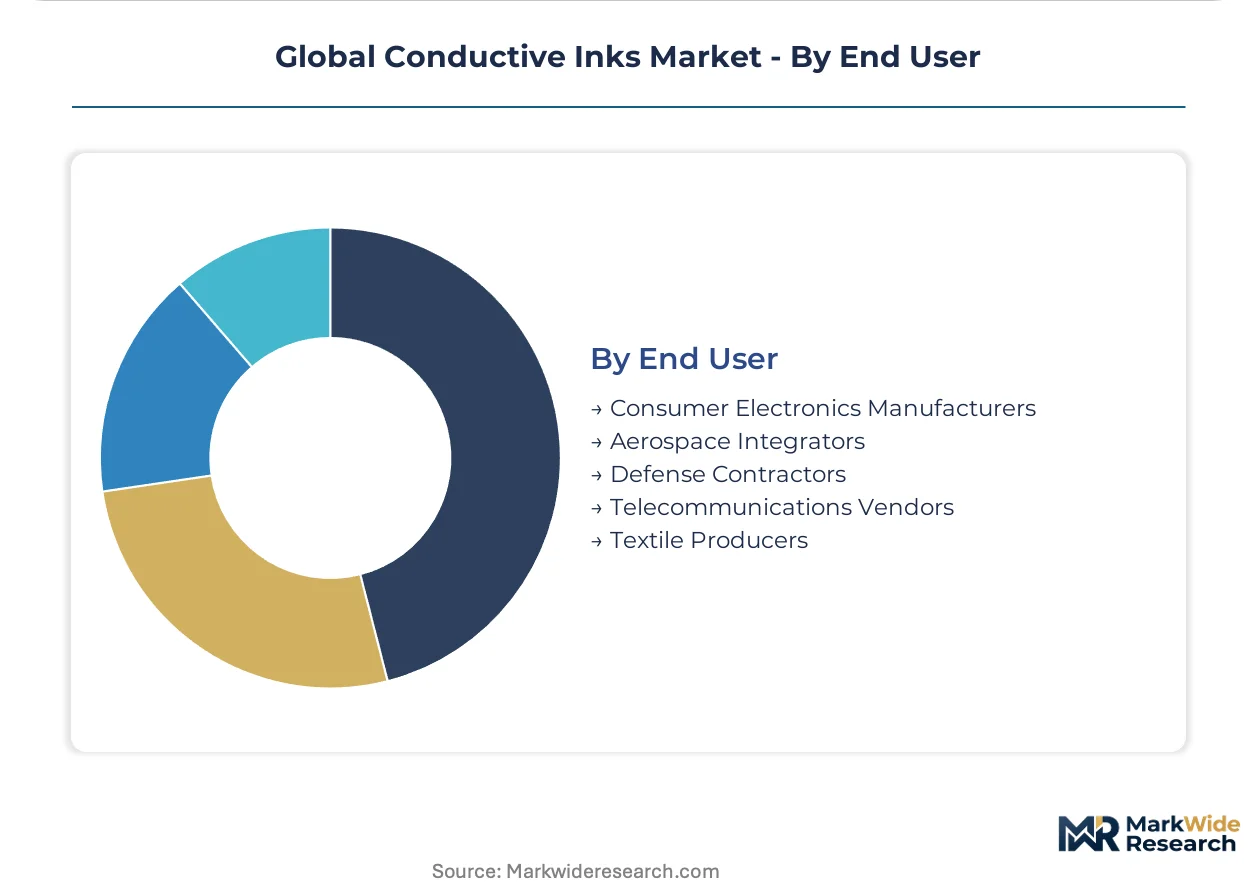
- Consumer Electronics Manufacturers:These manufacturers integrate conductive inks into smartphones, tablets, and various smart home devices, demanding high performance and cost efficiency. Large assembly operations in Vietnam and Mexico drive significant procurement volumes.
- Aerospace Integrators:Companies in the aerospace sector use conductive inks for lightweight sensors, flexible heaters, and EMI shielding in aircraft and spacecraft. Precision and reliability are paramount for these high-value components in France and the United States.
- Defense Contractors:The defense industry utilizes conductive inks for specialized sensors, flexible antennas, and secure electronic systems in military hardware.
- Telecommunications Vendors:These companies apply conductive inks in components for 5G infrastructure, IoT devices, and advanced communication systems.
- Textile Producers:Textile manufacturers incorporate conductive inks into smart fabrics for health monitoring, interactive displays, and heating elements in garments.
Consumer Electronics Manufacturers represent the largest purchasing segment, with Aerospace Integrators requiring the most specialized formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global conductive inks market faces a complex regulatory environment, prompting manufacturers to strategically locate production. Diverging environmental standards across regions influence formulation choices and manufacturing processes. This creates a dynamic where production shifts to optimize compliance costs and market access.
China
China's vast consumer electronics manufacturing base drives significant demand for cost-effective carbon inks. The country's GB standards influence material selection for electronic components. Production in Shenzhen and the Yangtze River Delta concentrates on high-volume assembly and RFID tag fabrication.
United States
United States demand for conductive inks stems from innovation in wearable devices and advanced sensor development. EPA regulations on volatile organic compounds shape solvent-based ink manufacturing. Silicon Valley and Boston serve as hubs for prototyping and specialized inkjet printing applications.
Germany
German market expansion is tied to advanced sensor development and precision automotive electronics. European Union REACH regulations mandate extensive safety data for chemical substances in inks. Munich and Stuttgart feature strong clusters for advanced manufacturing and specialized inkjet technology.
South Korea
South Korea's leadership in flexible displays and high-performance flexible electronics fuels silver-based ink demand. The nation's K-REACH regulations govern chemical substance registration and use. Seoul and Gyeonggi Province house key R&D centers and manufacturing facilities for advanced electronic components.
Vietnam
Vietnam's growing role in global consumer electronics assembly creates substantial volume demand for conductive inks. The country's national technical regulations guide material compliance for exported goods. Bắc Ninh and Ho Chi Minh City are key centers for electronics manufacturing operations.
Global Conductive Inks Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche, high-performance applications, creating a dynamic market structure. The landscape exhibits a tiered configuration, where a few dominant material science conglomerates operate alongside numerous specialized formulators. Strategic archetypes include diversified chemical giants offering broad portfolios, dedicated ink specialists focusing on specific chemistries, and innovative startup ventures targeting advanced materials. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and mitigate supply chain risks.
The competitive landscape features a blend of large, diversified chemical companies and specialized material science firms. DuPont de Nemours, Inc., a US-based corporation, exemplifies the diversified giant, leveraging its extensive material science portfolio to serve high-volume clients in the printed electronics space. German-based Henkel AG & Co. KGaA differentiates its offerings through integrated adhesive and thermal management properties within its conductive ink products. Additionally, specialists such as Creative Materials Inc., also US-based, cater to niche, high-performance applications that demand custom formulations and specialized material properties.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Henkel AG & Co. KGaA |
| Sun Chemical Corporation |
| Heraeus Holding GmbH |
| NovaCentrix |
| PPG Industries, Inc. |
| Johnson Matthey Plc |
| Creative Materials Inc. |
| Vorbeck Materials Corporation |
| Others |
Cost & Logistics Intelligence
Silver commodity prices, influenced by global industrial demand and speculative trading, cascade through the conductive inks supply chain, directly impacting the cost structure for high-performance formulations. This volatility necessitates strategic procurement by ink manufacturers and influences the final pricing tiers offered to electronics assemblers.
Pricing Analysis
Input cost fluctuations directly influence conductive ink pricing, particularly for silver-based products where raw material costs represent a significant component. Pricing stratifies across premium, standard, and economy tiers, driven by conductivity performance and customization level. Price differentiation also occurs based on certification level, such as compliance with specific EU RoHS standards. Pricing softness stems from the expansion of cost-sensitive applications like RFID tags, forcing manufacturers to optimize formulations. Consumer electronics manufacturers assembling RFID tags are the most price-sensitive segment, while aerospace integrators prioritize performance over cost.
Supply Chain Analysis
Large consumer electronics manufacturers increasingly mandate multi-sourcing strategies for critical materials like conductive inks, reducing reliance on single suppliers. Geographic supply concentration for conductive ink manufacturing centers in China and South Korea, where extensive electronics assembly operations exist. The supply chain depends on consistent access to silver, carbon, and specialized polymer binders. Commodity price volatility for silver creates a structural supply chain risk for high-performance ink producers. Distribution runs through direct sales channels to major OEMs, complemented by specialized distributors serving niche applications and smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conductive inks market presents a geographic-arbitrage opportunity, where lower manufacturing costs in China contrast with stringent environmental compliance requirements in the European Union.
For Market Incumbents: Deepen material science R&D into lead-free and halogen-free formulations to counter evolving EU RoHS directives. Expand manufacturing capacity in strategic regions like Vietnam to leverage cost efficiencies for high-volume consumer electronics production. Invest in advanced inkjet printing technologies to serve prototyping and customized manufacturing segments. Formulate next-generation inks compatible with novel flexible and stretchable substrates, anticipating future wearable device needs. Secure long-term supply agreements for critical raw materials like silver to mitigate commodity price volatility.
For New Entrants and Emerging Players: Begin with specialized inkjet printing applications in Germany, targeting advanced sensor development and custom manufacturing runs. Focus on graphene-based and polymer-based inks for niche, high-performance applications requiring unique mechanical and electrical properties. The biomedical applications segment, particularly disposable diagnostic sensors, represents a highly penetrable market due to its specific biocompatibility requirements. Develop a go-to-market strategy centered on rapid prototyping services and technical support for specialized R&D labs in the United States.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized formulators possessing proprietary IP in stretchable or biocompatible inks for the long term. These companies can command premium valuations due to their unique material science capabilities and market differentiation. Target acquisition candidates with established compliance records for EU REACH and RoHS regulations, reducing future regulatory burden. A signal to watch is the increasing adoption rate of inkjet printing for volume production, indicating readiness for advanced material integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Formulation Diversification | Addresses diverse performance and cost requirements across applications like wearables and RFID tags. |
| Inkjet Technology Investment | Enables precise, low-volume manufacturing and rapid prototyping for advanced electronic components. |
| Regional Compliance Hub Development | Navigates complex environmental regulations in the EU and US, ensuring market access. |
| Strategic Partnerships | Secures raw material supply and expands market reach with electronics manufacturers. |
| Graphene Ink Commercialization | Unlocks new applications requiring superior conductivity and mechanical flexibility for advanced products. |
Research Approach
Bottom-up wearable device modeling reconciled against top-down raw material supply tracking forms the analytical core of this study. Primary interviews with R&D directors, procurement leads at OEMs, material scientists, and application engineers provided critical qualitative insights. Secondary validation drew from regulatory filings (EPA, REACH), industry association reports, academic journals, and company financial disclosures. This approach ensured comprehensive data triangulation across demand-side consumption and supply-side capabilities.
Historical trendline analysis across the modeling period informed the projection of future market trajectories. The analytical framework incorporated segmentation dimensions by product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived through a proprietary algorithm, factoring in market dynamics and technological adoption curves. Global consumer electronics production volumes and silver price forecasts served as key industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts or rapid material science breakthroughs. Forecasts reflect assumptions regarding stable regulatory environments and sustained investment in printed electronics. Deviation in either global economic growth or raw material supply chain stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
Global Decorative Print Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
United States Flexographic Printing Market
Printing Inks
Security Printing Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
Global Digital Inks Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Food Grade Inks Market
Printing Inks
Ink Resins Market
Printing Inks
Inkjet Colorants Market
Printing Inks
Printing Inks Market
Printing Inks
Rapid Liquid Printing Market