
 North America Performance Elastomer Market | 2026-2036
North America Performance Elastomer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Performance Elastomer Market Insights
Specialty chemical distribution in North America is tilting toward direct mill relationships as compounders seek feedstock security. DuPont leverages its integrated silicone supply chain to serve medical and aerospace qualification programs. Dow anchors its position through Gulf Coast EPDM production that feeds automotive weatherstrip demand. BASF SE competes on thermoplastic polyurethane grades for consumer electronics overmolding.
Performance elastomers are engineered polymers exhibiting elastic recovery above 100% strain, formulated from silicone, EPDM, NBR, or SBR backbones with tailored crosslink densities for thermal stability, chemical resistance, or electrical insulation. Their primary purpose is to maintain sealing integrity, vibration damping, or flexible containment across temperature extremes and aggressive media. Silicone leads medical and aerospace segments due to biocompatibility certifications and sterilization tolerance, while EPDM dominates automotive weatherstrip and coolant hose applications where ozone and glycol resistance command premium pricing. NBR sustains share in oilfield and hydraulic segments through acrylonitrile content adjustments that balance fluid resistance with low-temperature flexibility.
FDA biocompatibility standards, EPA REACH-equivalent chemical reporting under TSCA Section 8, and FAA material flammability certifications shape product development cycles and qualification barriers for new compound introductions. The IRA domestic content provisions for clean energy manufacturing are redirecting some silicone and fluoroelastomer demand toward US-based supply. Stakeholders must monitor how evolving automotive electrification thermal management requirements and medical device re-shoring policies reshape grade specifications and regional capacity allocation.
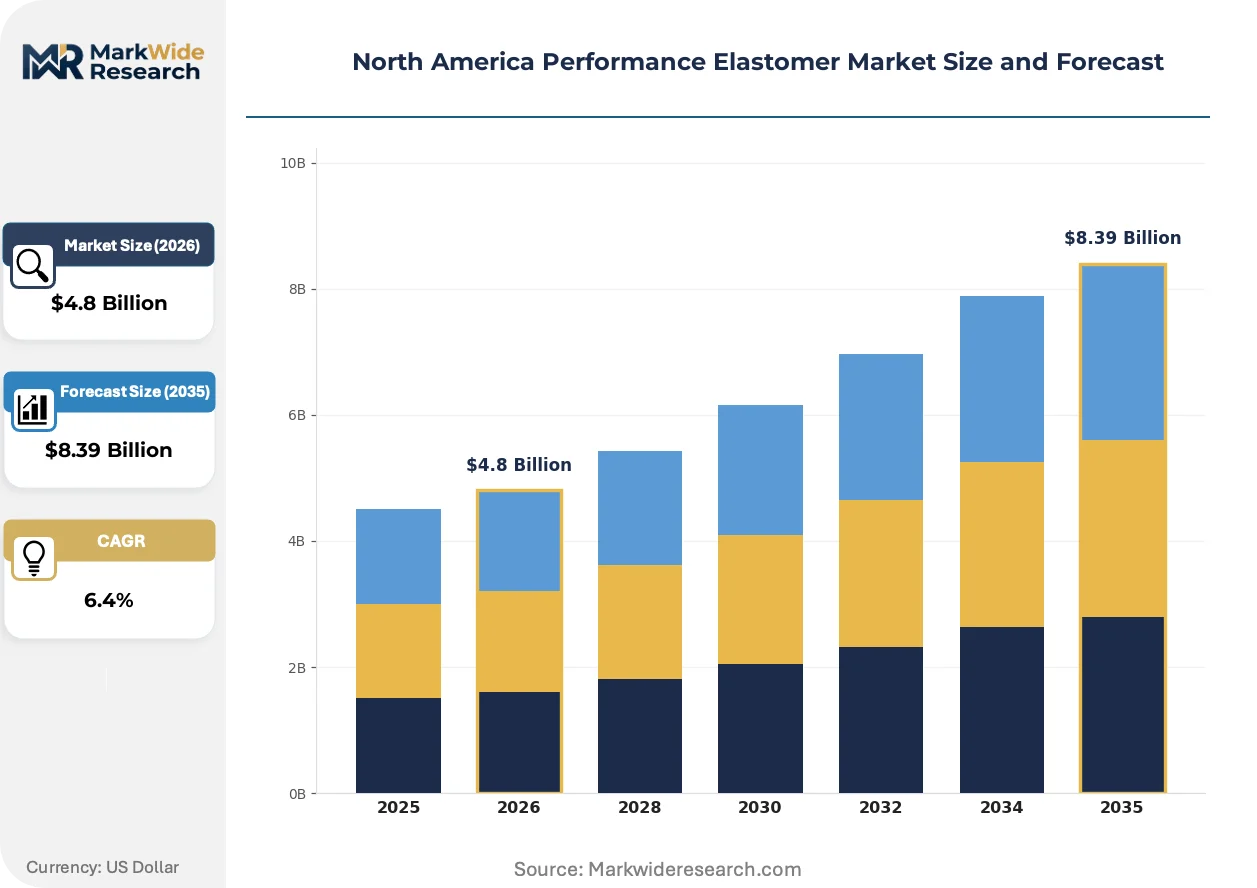
Market Dynamics
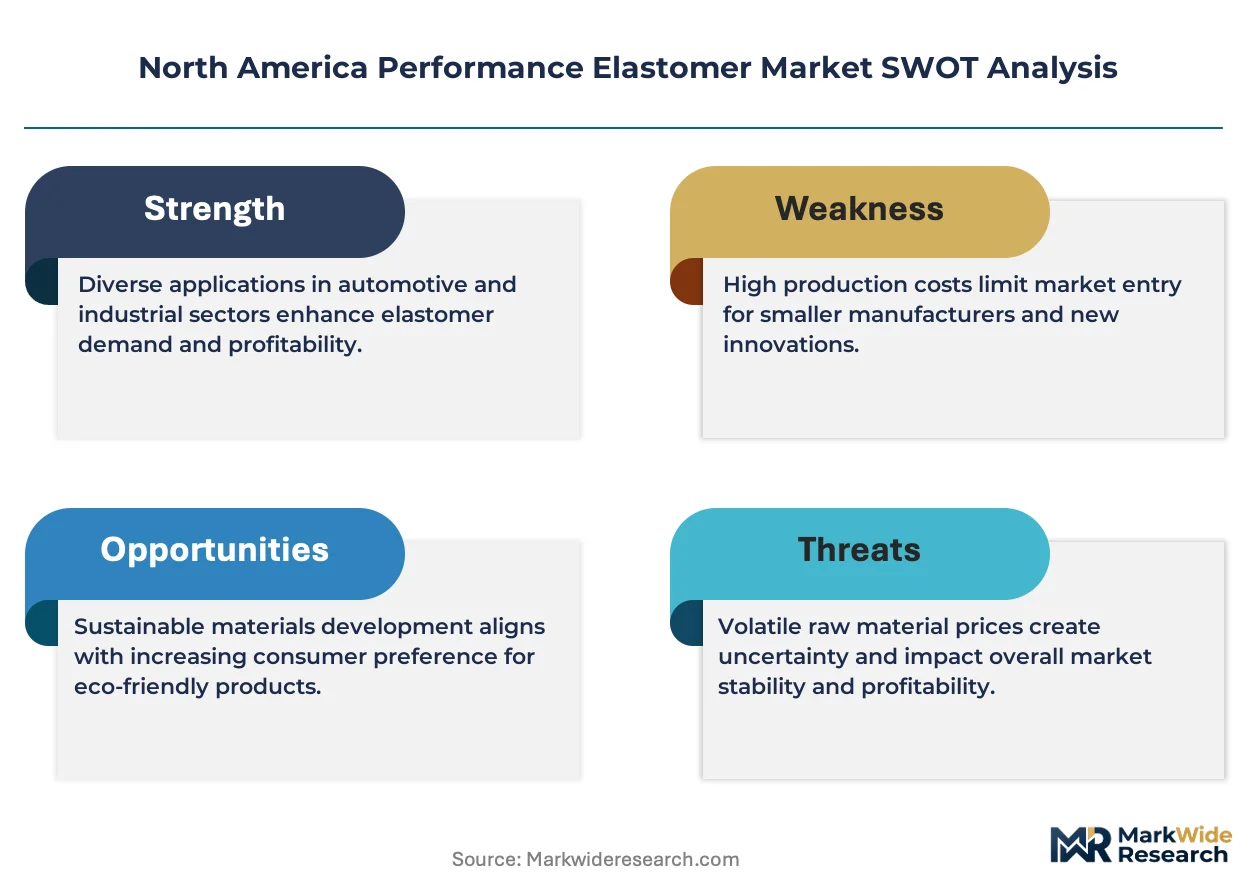
Automotive electrification is restructuring material specifications across North America, as battery thermal management systems demand elastomers rated for 150°C continuous operation that legacy EPDM formulations cannot satisfy.
Growth Catalysts
- IRA domestic content provisions:Clean energy manufacturing incentives are redirecting silicone and fluoroelastomer procurement toward US-based compounders serving solar and wind OEMs.
- Medical device re-shoring:FDA biocompatibility certifications for implantable-grade silicones are accelerating qualification programs at Gulf Coast specialty polymer facilities.
- EPA tailpipe tightening:Stricter emission rules are forcing Michigan and Ohio automotive OEMs to expand silicone seal procurement for electric powertrain sealing integrity.
Market Restraints
- Silicone monomer supply concentration:Gulf Coast petrochemical corridor dependence creates vulnerability to hurricane-related production interruptions and force majeure events.
- Specialty carbon black input volatility:Reinforcing filler costs fluctuate with oil-indexed feedstock pricing, compressing compounder margins on standard EPDM grades.
- Fluoroelastomer technical ceiling:Perfluoroelastomer cure chemistry limits low-temperature flexibility below -20°C, restricting adoption in cold-climate aerospace applications.
Strategic Opportunities
- Underpenetrated Canadian medical device cluster:Toronto-area contract manufacturers lack qualified domestic silicone compounders, creating white space for US Gulf Coast suppliers with Health Canada establishment licensing.
- Thermoplastic vulcanize convergence:Dynamic vulcanization technology enables polypropylene/EPDM alloys that replace thermoset rubber in automotive interior soft-touch components.
- Direct mill relationships:Compounders are bypassing distributors to secure feedstock allocation priority from Dow and DuPont silicone divisions.
Industry Challenges
- FAA material flammability certification timelines:Smoke density and toxicity testing for aerospace-grade silicones extends qualification cycles to 18-24 months, freezing design-in decisions.
- Formulation chemist scarcity:Gulf Coast compounding facilities compete for talent with upstream petrochemical operators offering premium compensation for peroxide cure expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Performance Elastomer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SBR, EPDM, NBR, Silicone End User: Automotive, Aerospace, Consumer Electronics, Medical Deployment: Onshore, Offshore, In-Plant, Remote Application: Seals, Hoses, Gaskets, Coatings |
| Companies Covered | DuPont, BASF SE, Dow, Covestro AG, Chemours, Evonik AG, Solvay S.A., Arlanxeo, Avient Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Performance Elastomer Market Trends and Innovations
Material science advances and regulatory stringency are converging to redefine performance thresholds, with thermal stability and biocompatibility specifications climbing faster than incumbent formulation platforms can adapt.
Self-liquid silicone rubber (LSR) injection molding with in-mold bonding to thermoplastic substrates is rendering obsolete two-component assembly of discrete gaskets and housings. Medical device OEMs in Minnesota and Massachusetts are adopting this at pilot scale for diagnostic instrument seals. The technology compresses part count and labor cost while demanding capital investment in multi-shot presses that smaller molders cannot finance.
EPA enforcement of TSCA Section 8 chemical reporting is tightening traceability requirements for imported silicone intermediates. Compounders must now document full supply chain substance identity back to monomer synthesis. This friction most affects mid-tier formulators sourcing Asian-sourced dimethylsiloxane, forcing qualification switches to domestic Dow and Wacker supply.
Buyer consolidation among Tier 1 automotive suppliers is concentrating procurement leverage. Continental and Aptiv are unbundling compound specification from molding execution, selecting elastomer grades through centralized technical committees rather than plant-level purchasing. This shift is most visible in Detroit-area weatherstrip supply, where direct mill contracts now lock in 3-year volume commitments with price collars indexed to propylene monomer.
North America Performance Elastomer Market Segmentation
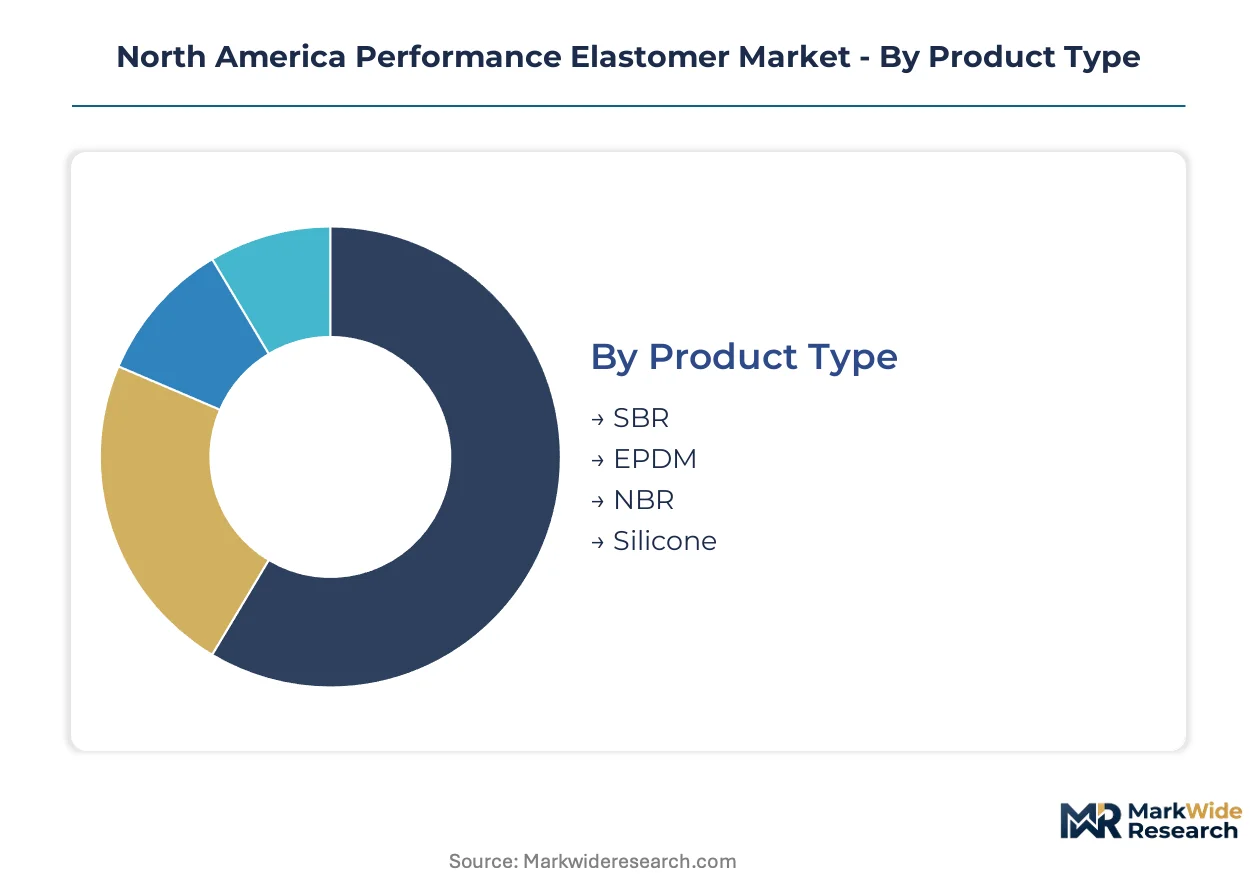
Performance elastomer procurement in North America fragments across formulation chemistry, end-use qualification tiers, and deployment logistics. Each segmentation axis carries distinct margin profiles and technical barriers that reshape supplier-customer relationships.
Product Type:
After-sales service intensity varies sharply across polymer families, with silicone demanding FDA re-qualification support and fluoroelastomer requiring field failure analysis that EPDM rarely needs.
- EPDM:Ethylene-propylene-diene terpolymer formulations deliver ozone and glycol resistance through controlled ethylidene norbornene incorporation. Automotive weatherstrip demand concentrates in Michigan and Ohio assembly plants where EPA tailpipe tightening accelerates coolant hose specifications. Gulf Coast petrochemical corridor capacity anchors supply security for this grade.
- Silicone:Polydimethylsiloxane backbones with vinyl functionalization enable platinum-catalyzed addition cure systems rated for 200°C continuous operation. Medical device re-shoring drives qualification programs at Minnesota and Massachusetts diagnostic OEMs requiring FDA biocompatibility certifications. The polymer commands premium pricing for implantable-grade lots.
- NBR:Acrylonitrile-butadiene copolymers balance fluid resistance against low-temperature flexibility through nitrile content adjustment. Oilfield hydraulic applications in Texas and Louisiana sustain demand despite volatile reinforcing filler costs.
- SBR:Styrene-butadiene emulsion and solution polymerizations serve tire and general rubber goods with lower performance thresholds. Price-sensitive applications limit service intensity compared to specialty grades.
By volume, EPDM leads. By growth pace, silicone is ahead.
End User:
Customer procurement sophistication separates aerospace qualification programs from automotive scale contracts, with medical occupying a middle ground of technical rigor and moderate volume.
- Automotive:Battery thermal management systems demand elastomers rated for 150°C continuous operation that legacy EPDM formulations cannot satisfy. Michigan and Ohio OEMs are expanding silicone seal procurement as electric powertrain architectures displace internal combustion platforms.
- Medical:Implantable-grade silicones require FDA biocompatibility certifications and sterilization tolerance validation. Minnesota and Massachusetts diagnostic instrument manufacturers are adopting liquid silicone rubber injection molding at pilot scale.
- Aerospace:FAA material flammability certifications extend qualification cycles to 18-24 months for smoke density and toxicity compliance. Cold-climate applications face perfluoroelastomer flexibility limitations below -20°C.
- Consumer Electronics:Thermoplastic polyurethane grades from BASF SE compete for overmolding applications where tactile feel and chemical resistance balance cost constraints.
Automotive commands the largest procurement volumes. Medical qualification complexity creates the steepest expansion trajectory for specialized compounders.
Deployment:
Logistics configuration determines inventory carrying costs and technical service accessibility, with remote locations imposing the highest support burden on suppliers.
- In-Plant:Direct mill relationships at Gulf Coast compounding facilities enable just-in-time feedstock allocation from Dow and DuPont silicone divisions. Automotive Tier 1 suppliers in Detroit concentrate procurement through this channel.
- Onshore:Regional distribution from Texas and Louisiana petrochemical hubs serves medical device clusters in Minnesota and Massachusetts with documented supply chain traceability under EPA TSCA Section 8.
- Offshore:Asian-sourced dimethylsiloxane intermediates face qualification switches to domestic supply as compounders document full substance identity back to monomer synthesis.
- Remote:Canadian medical device contract manufacturers in the Toronto area lack qualified domestic silicone compounders, creating white space for US Gulf Coast suppliers with Health Canada establishment licensing.
In-Plant deployment dominates automotive procurement. Remote service models are gaining share fastest among cross-border medical supply chains.
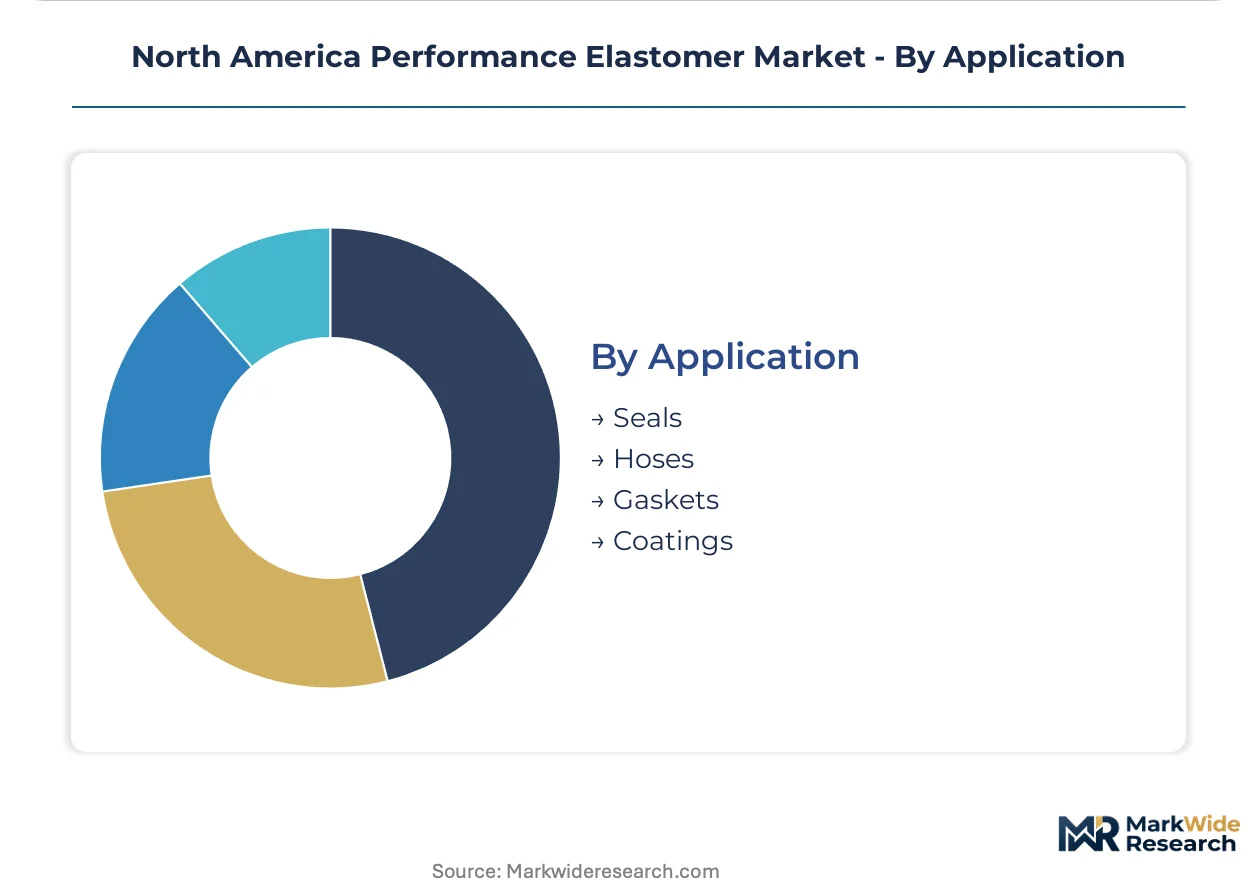
Application:
Functional performance requirements separate commodity gaskets from qualification-intensive seals and coatings, with hoses occupying an intermediate technical tier.
- Seals:Self-liquid silicone rubber injection molding with in-mold bonding to thermoplastic substrates compresses part count for diagnostic instrument applications. The technology demands capital investment in multi-shot presses that smaller molders cannot finance.
- Hoses:Coolant and turbocharger applications require EPDM formulations with specific ethylidene norbornene levels to balance heat aging against extrusion processability. EPA tailpipe tightening is accelerating specification upgrades.
- Gaskets:Static sealing applications tolerate broader formulation latitude, with SBR and standard EPDM grades competing on carbon black loading and cost.
- Coatings:Thin-film elastomeric applications for electrical insulation and chemical barrier protection require specialized dispersion technology and substrate pretreatment protocols.
Seals generate the highest value per kilogram. Hose specifications are climbing fastest as automotive thermal management requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailpipe regulations and IRA domestic content provisions anchor United States demand, while Health Canada licensing requirements and Mexico's automotive assembly expansion reshape cross-border supply configurations across the continent.
United States
Michigan and Ohio automotive OEMs are expanding silicone seal procurement for electric powertrain architectures as NHTSA and EPA rules tighten emission standards. The IRA redirects silicone and fluoroelastomer procurement toward Gulf Coast compounders serving solar and wind OEMs. Minnesota and Massachusetts diagnostic instrument manufacturers are adopting liquid silicone rubber injection molding at pilot scale for FDA biocompatibility certifications.
Canada
Toronto-area contract manufacturers lack qualified domestic silicone compounders, creating white space for US Gulf Coast suppliers with Health Canada establishment licensing. The country's medical device re-shoring policies accelerate qualification programs for implantable-grade silicones. Alberta's oilfield hydraulic applications sustain NBR demand despite volatile reinforcing filler costs from oil-indexed feedstock pricing.
Mexico
Automotive assembly expansion in Nuevo León and the Bajío Region concentrates EPDM weatherstrip demand from Detroit-area Tier 1 suppliers. The country's integration into North American clean energy supply chains positions silicone compounders for IRA-compliant solar component exports. Querétaro's aerospace cluster faces FAA material flammability certification timelines extending qualification cycles to 18-24 months.
North America Performance Elastomer Market Competitive Landscape
Integrated petrochemical majors and specialty compounders split the market through divergent feedstock control strategies. Dow anchors supply security through Gulf Coast EPDM production serving automotive weatherstrip demand. DuPont leverages integrated silicone supply chains for medical and aerospace qualification programs. BASF SE competes on thermoplastic polyurethane grades for consumer electronics overmolding. Capacity expansion and direct mill relationships represent the dominant competitive moves as compounders bypass distributors to secure allocation priority.
Among diversified chemical conglomerates, DuPont, Dow, and BASF SE exemplify the integrated-archetype position. These entities occupy positions defined by captive monomer supply and qualification-program depth rather than transactional volume scale. Their presence shapes procurement leverage as buyer consolidation among Tier 1 automotive suppliers concentrates specification authority through centralized technical committees.
| Leading Market Players |
|---|
| DuPont |
| BASF SE |
| Dow |
| Covestro AG |
| Chemours |
| Evonik AG |
| Solvay S.A. |
| Arlanxeo |
| Avient Corporation |
| Others |
Pricing and Supply Chain Analysis
The US Gulf Coast petrochemical corridor concentrates specialty polymer compounding capacity that feeds downstream pricing power to medical device and aerospace clusters. Silicone monomer supply concentration in Texas and Louisiana creates allocation leverage during force majeure events, while EPDM producers index contract collars to propylene monomer volatility.
Pricing Analysis
Geographic price spreads between Gulf Coast compounders and Canadian medical device manufacturers reflect Health Canada establishment licensing premiums and cross-border logistics costs. Three-tier pricing structure across implantable-grade, FDA-certified, and standard industrial silicones separates qualification-intensive medical lots from automotive weatherstrip volumes. Cost compression in commodity EPDM grades is intensifying because specialty carbon black input volatility tracks oil-indexed feedstock pricing. Tier 1 automotive suppliers exhibit highest price sensitivity through centralized technical committees, while implantable-grade medical buyers accept premium positioning for biocompatibility certification.
Supply Chain Analysis
Extended payment terms from Detroit-area Tier 1 automotive suppliers strain working capital for mid-tier compounders lacking supply-chain finance facilities. Production concentrates in the United States, Canada, and Mexico under USMCA rules of origin. Silicone formulations draw from dimethylsiloxane monomers, ethylidene norbornene comonomers, and reinforcing filler systems. Single-source vulnerability to hurricane-related production interruptions at Gulf Coast facilities threatens just-in-time feedstock allocation. Distribution runs through direct mill relationships that bypass traditional chemical distributors for volume priority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric powertrain thermal management requirements are accelerating silicone adoption beyond legacy EPDM specifications, positioning the market for early-cycle expansion as automotive electrification penetrates Midwest assembly plants.
For Market Incumbents: Pre-empt qualification bottlenecks by expanding Gulf Coast platinum-catalyzed silicone capacity ahead of FDA biocompatibility certification backlogs. Anchor backward integration into dimethylsiloxane monomer supply to defend margin position against Asian import traceability friction under EPA TSCA Section 8 enforcement. Lock three-year volume commitments with price collars indexed to propylene monomer before buyer consolidation among Tier 1 automotive suppliers concentrates further. For New Entrants and Emerging Players: Toronto-area contract manufacturers lacking qualified domestic silicone compounders represent the most penetrable entry point for US Gulf Coast suppliers with Health Canada establishment licensing. Thermoplastic vulcanize convergence in automotive interior soft-touch components offers a second white-space target where polypropylene/EPDM alloys displace thermoset rubber. Lead with documented supply chain substance identity back to monomer synthesis to satisfy EPA enforcement priorities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among implantable-grade silicone compounders with locked FDA qualification programs and multi-year medical device OEM contracts. Long-term viability over the next decade hinges on exposure to electrification-driven thermal management demand rather than legacy internal combustion applications. Monitor IRA domestic content provision enforcement as the inflection signal redirecting procurement toward US-based supply.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Gulf Coast platinum-catalyzed silicone additions serve battery thermal management demand from Michigan and Ohio OEMs. |
| Backward Integration | Captive dimethylsiloxane production defends margin position against EPA TSCA Section 8 traceability enforcement. |
| Long-term Supply Agreement | Three-year volume commitments with propylene-indexed collars lock automotive Tier 1 procurement before further consolidation. |
| Joint Venture | Health Canada-licensed partnerships with Toronto-area contract manufacturers capture underpenetrated medical device demand. |
| Green Manufacturing Transition | Low-carbon silicone processes align with IRA domestic content provisions for clean energy manufacturing incentives. |
Research Methodology
A standing panel of silicone compounding plant managers, automotive Tier 1 procurement directors, FDA regulatory affairs specialists, and medical device biomedical engineers provided ongoing calibration across the study. Primary interviews with Dow and DuPont technical sales teams, Gulf Coast distribution channel partners, and Minnesota diagnostic instrument OEMs combined with secondary validation from EPA enforcement disclosures, FDA 510(k) filings, ACC industry reports, and USMCA trade flow data. Bottom-up grade-volume build-ups and top-down elastomer consumption estimates triangulated market sizing.
Scenario-bracketing around IRA domestic content provision enforcement intensity and EPA tailpipe regulation tightening shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, end-use qualification tier, deployment logistics configuration, and application functional requirements. CAGRs derived from elasticity-adjusted demand curves incorporating automotive electrification penetration rates and medical device re-shoring policy implementation. Industry-specific inputs encompassed battery thermal management temperature specifications and FAA material flammability certification timeline assumptions.
Macroeconomic conditions sit as an overlay; deviation in propylene monomer pricing, hurricane frequency disrupting Gulf Coast production, or automotive assembly rate volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and qualification program success rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
High Temperature Elastomers Market