
 Elastomer Coated Fabric Market | 2026-2036
Elastomer Coated Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomer Coated Fabric Market Foresight
Germany is narrowing its specialty elastomer capacity gap through targeted investments in polyurethane and silicone coating lines serving automotive tier-one suppliers. Seaman Corporation leverages vertical integration from polymer compounding to finished roll goods, sustaining cost advantages in industrial membrane applications. Trelleborg AB anchors European supply for offshore and marine protective fabrics, competing on specification breadth across neoprene and chloroprene formulations. Continental AG dominates automotive interior contracts through in-house textile finishing operations that extend from substrate weaving to final coated product.
Elastomer coated fabric consists of woven, knitted, or nonwoven textile substrates bonded with synthetic rubber layers typically ranging from 0.1 to 2.0 millimeters in thickness, engineered to deliver tensile strength, chemical resistance, and elastic recovery for demanding environments. Polyurethane coatings lead volume owing to balanced cost-performance in industrial and consumer applications, while silicone formulations command premium positioning in high-temperature automotive and aerospace gaskets where thermal stability exceeds 200 degrees Celsius. PVC-coated variants occupy mature, price-sensitive segments such as commercial upholstery and temporary shelters, whereas neoprene grades specialize in marine and protective outerwear where oil resistance and weathering durability justify higher unit economics.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based coating operations in the United States, while REACH restrictions on isocyanates and plasticizers reshape formulation choices across European manufacturing. The EU Green Deal and associated CSRD reporting obligations are pressing coated fabric producers to document scope-three emissions and accelerate water-based or UV-curable process transitions. Stakeholders must monitor evolving chemical hazard classifications and align R&D portfolios with jurisdictions tightening pre-market notification requirements for novel polymer additives.
Market Dynamics
Automotive OEMs are consolidating interior textile procurement around silicone-coated substrates capable of withstanding sustained thermal loads above 200 degrees Celsius, compressing supplier qualification timelines and favoring vertically integrated coating operations.
Growth Catalysts
- EPA NESHAP compliance mandates:US fabric coaters are retrofitting solvent-based lines to waterborne or UV-curable systems, creating equipment upgrade demand and technical service revenue for process chemical suppliers.
- Stuttgart-Wolfsburg supplier cluster concentration:Germany's automotive tier-one density is pulling polyurethane and silicone coating capacity into Baden-Württemberg and Lower Saxony, reducing logistics costs for just-in-sequence delivery.
- Silicone elastomer thermal performance:Gasket and seating applications in electric vehicle battery enclosures require sustained heat resistance that polyurethane formulations cannot match, opening specification upgrades.
Market Restraints
- Isocyanate feedstock volatility:Polyurethane coating margins compress when MDI and TDI prices spike, forcing coaters to absorb costs or risk contract loss during annual automotive supplier negotiations.
- Chloroprene supply concentration:Neoprene-coated fabric production depends on a narrow base of polychloroprene polymer suppliers concentrated in East Asia, exposing marine and protective wear manufacturers to disruption risk.
- REACH SVHC notification thresholds:European coating formulators face escalating compliance costs as ECHA expands the candidate list of substances of very high concern, particularly for plasticizer additives in PVC-coated variants.
Strategic Opportunities
- India automotive seating localization:PLI scheme incentives for advanced chemistry cell and component manufacturing are drawing coating operations to Gujarat and Tamil Nadu to serve Maruti Suzuki and Hyundai Motor India.
- UV-curable silicone hybrid formulations:Convergence of energy-curable processing speed with silicone thermal performance enables coaters to penetrate aerospace gasket applications previously locked into compression-molded rubber.
- EU Green Deal scope-three disclosure:Coated fabric producers with verified carbon accounting can capture premium positioning in CSRD-mandated supplier selection by automotive and industrial OEMs.
Industry Challenges
- Formulation chemist scarcity:Coating operations struggle to recruit specialists capable of balancing rheology, adhesion, and regulatory compliance across polyurethane, silicone, and hybrid systems.
- Automotive qualification cycle compression:Tier-one suppliers demand coated fabric validation in 18-month windows that conflict with standard 36-month OEM material approval protocols, straining R&D bandwidth.
- Multi-jurisdiction chemical hazard alignment:Divergent EPA, ECHA, and state-level substance restrictions force coaters to maintain parallel formulation portfolios, increasing inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomer Coated Fabric Market |
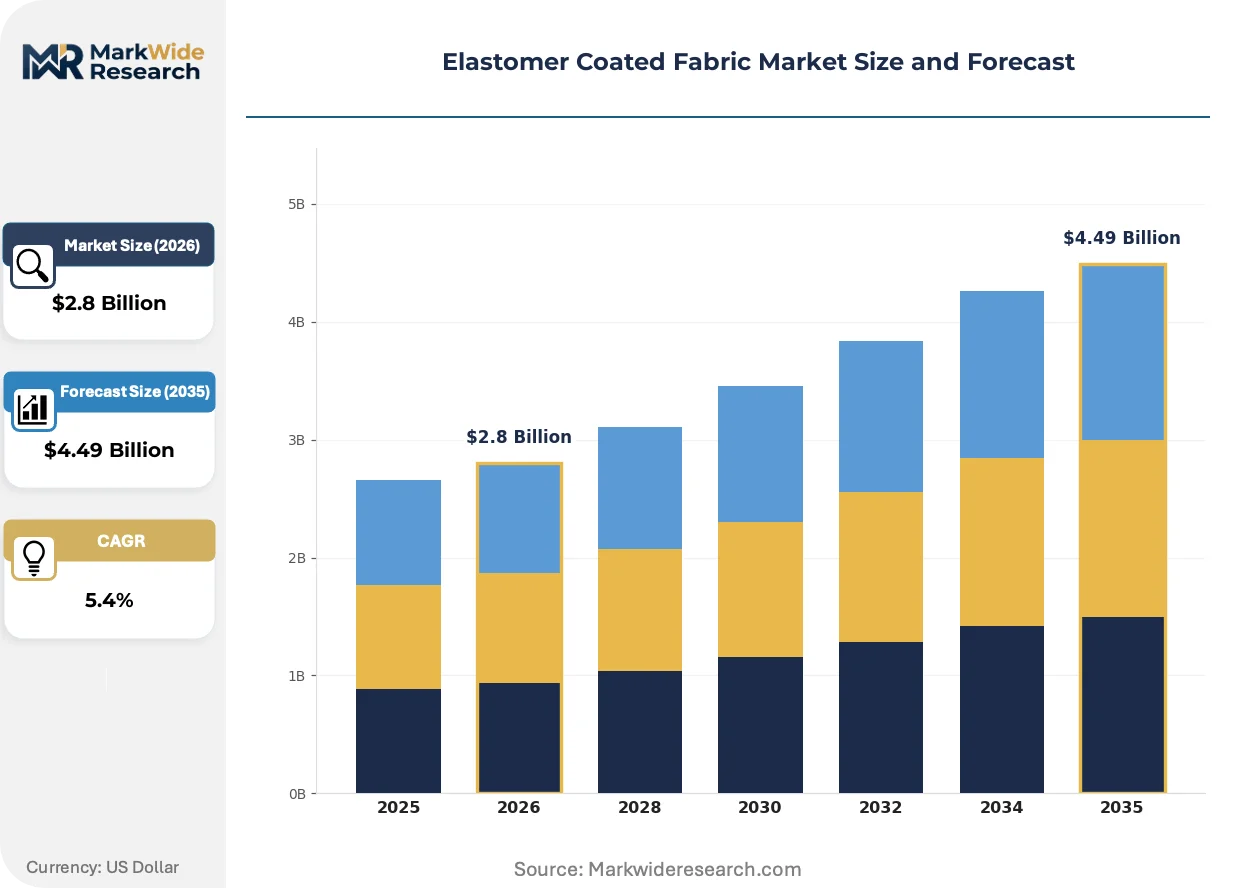
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Neoprene, PVC Application: Textiles, Automotive Interiors, Industrial Fabrics, Outerwear End User: Fashion Industry, Automotive OEMs, Industrial Manufacturers, Sports Equipment Distribution Channel: Online Retailers, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Seaman Corporation, Serge Ferrari Group, Trelleborg AB, Spradling International Inc., Sioen Industries NV, Continental AG, OMNOVA Solutions Inc., Low & Bonar, Compagnie de Saint-Gobain S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomer Coated Fabric Market Shifts & Advancements
Coating process intensification and regulatory chemistry restrictions are compressing legacy solvent-based production models while opening specification space for thermally advanced elastomer systems.
Waterborne polyurethane dispersions with blocked isocyanate crosslinkers are collapsing the performance gap between solvent-borne and low-VOC coating systems. Automotive seating suppliers in Germany and the United States are qualifying these formulations for Class A interior surfaces previously reserved for solvent-based finishes. The technology is collapsing capital allocation toward incineration and recovery equipment, redirecting investment into inline curing and inspection automation.
REACH restrictions on isocyanates and plasticizers are forcing reformulation of established polyurethane and PVC coating recipes across European manufacturing. ECHA's 2023-2025 restriction roadmap targets specific chain extenders and stabilizers common in industrial membrane applications. Marine protective fabric producers serving North Sea offshore platforms are accelerating testing of bio-based polyol alternatives to preempt authorization requirements.
Automotive OEMs are consolidating textile procurement through direct contracting with coating operations rather than merchant substrate suppliers. Tier-one seating manufacturers in Wolfsburg and Detroit are losing intermediary margin capture as Continental AG and similar integrators extend from weaving through finished roll goods. This concentration is most visible in Germany, where in-house textile finishing operations now control specification writing for interior programs.
Elastomer Coated Fabric Market Segmentation
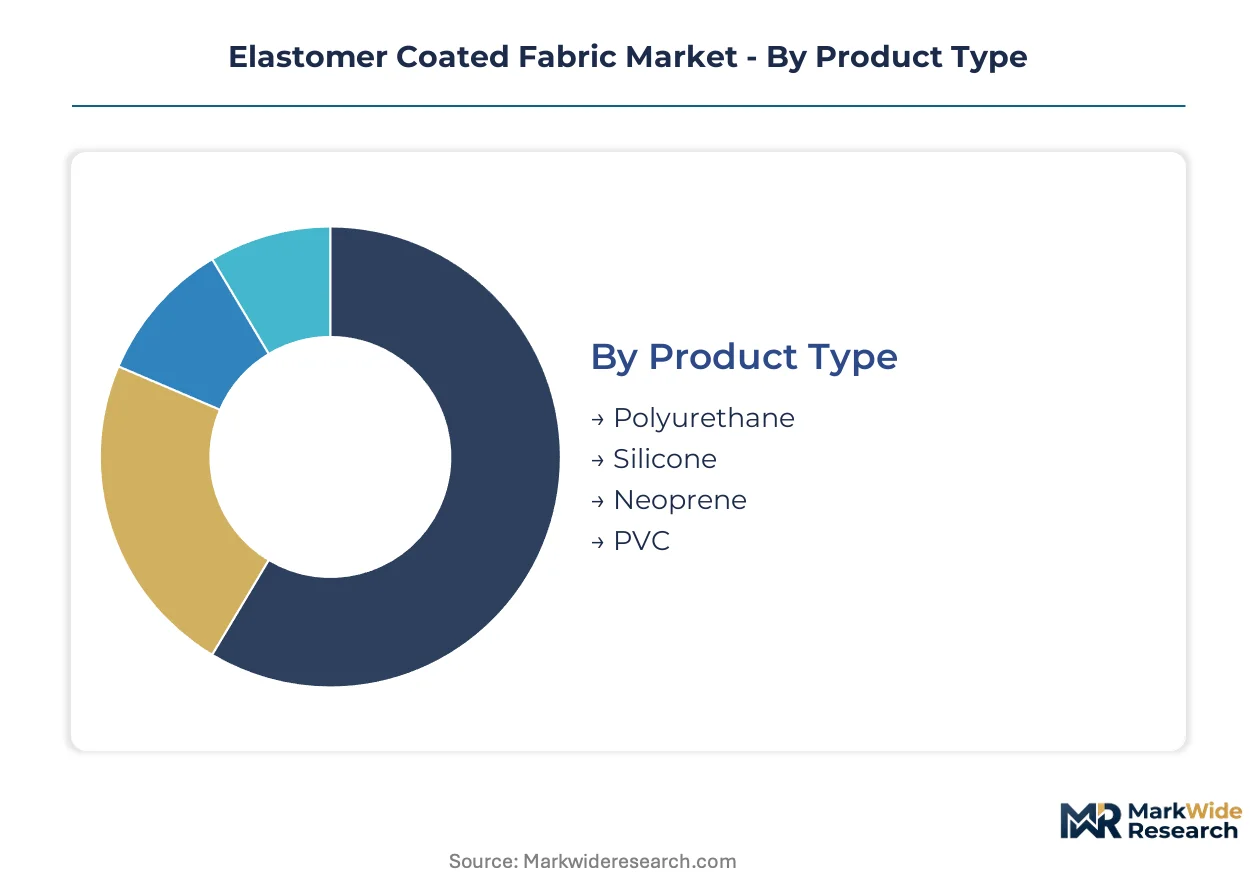
Elastomer coated fabric segmentation reflects divergent technical requirements across temperature tolerance, chemical resistance, and regulatory compliance. Coating chemistry and end-use specifications determine procurement patterns, with automotive and industrial buyers driving consolidation around vertically integrated suppliers.
Product Type:
Mature polyurethane formulations dominate volume throughput, while emerging silicone systems capture specification upgrades in thermal-critical applications.
- Polyurethane:Waterborne and solvent-borne formulations bond to woven polyester or nylon substrates, delivering tensile strength above 20 MPa for industrial membrane and seating applications. Demand concentrates in Germany's Stuttgart-Wolfsburg automotive corridor where tier-one suppliers specify polyurethane for cost-optimized interior programs subject to REACH isocyanate restrictions.
- Silicone:Heat-cured polysiloxane coatings maintain elastic recovery above 200 degrees Celsius, enabling gasket and battery enclosure applications that polyurethane cannot serve. Procurement is accelerating among electric vehicle OEMs in the United States and Germany as EPA NESHAP and REACH constraints simultaneously tighten on solvent-based alternatives.
- Neoprene:Polychloroprene formulations provide oil resistance and weathering durability for marine protective fabrics and diving equipment, though supply concentration in East Asia exposes coaters to feedstock disruption.
- PVC:Plasticized vinyl coatings occupy mature commercial upholstery and temporary shelter segments where price sensitivity overrides performance requirements, facing escalating ECHA scrutiny on phthalate additives.
Polyurethane handles the majority of throughput; silicone is the fastest mover on share.
Application:
Application segmentation tracks customer procurement authority, with automotive OEMs consolidating direct contracting power previously held by tier-one intermediaries.
- Automotive Interiors:Seating, door panels, and headliners require Class A surface finishes with fogging resistance and flame-retardant certification. Continental AG and similar integrators now control specification writing through in-house textile finishing operations spanning substrate weaving to final coated product.
- Industrial Fabrics:Membranes for tension structures, conveyor belts, and filtration systems prioritize tensile strength and chemical resistance over aesthetic properties. Seaman Corporation leverages backward integration from polymer compounding to finished roll goods in this segment.
- Textiles:Decorative and functional coated fabrics for commercial upholstery and architectural applications serve price-sensitive buyers through merchant substrate suppliers.
- Outerwear:Protective garments for marine, military, and emergency services specify neoprene or specialized polyurethane grades where weathering durability justifies premium unit economics.
Industrial fabrics anchor volume throughput; automotive interiors are climbing the fastest as OEMs consolidate procurement.
End User:
End user segmentation reveals divergent technical validation requirements, with automotive OEMs compressing supplier qualification timelines against industrial manufacturers' extended testing protocols.
- Automotive OEMs:Direct contracting with coating operations is displacing tier-one intermediary relationships, particularly in Germany where in-house textile finishing now controls interior program specifications. Battery enclosure applications are pulling silicone-coated substrates into electric vehicle platforms.
- Industrial Manufacturers:Membrane and protective fabric buyers prioritize specification breadth and lot-to-lot consistency, rewarding vertically integrated coaters with captive polymer compounding capabilities.
- Fashion Industry:Apparel and accessory brands source coated fabrics through merchant converters, with limited technical specification authority relative to automotive and industrial buyers.
- Sports Equipment:Wetsuit, drysuit, and protective gear manufacturers concentrate demand for neoprene grades, exposing them to polychloroprene supply concentration risk.
Automotive OEMs command the highest specification authority; industrial manufacturers provide the steadiest volume base.
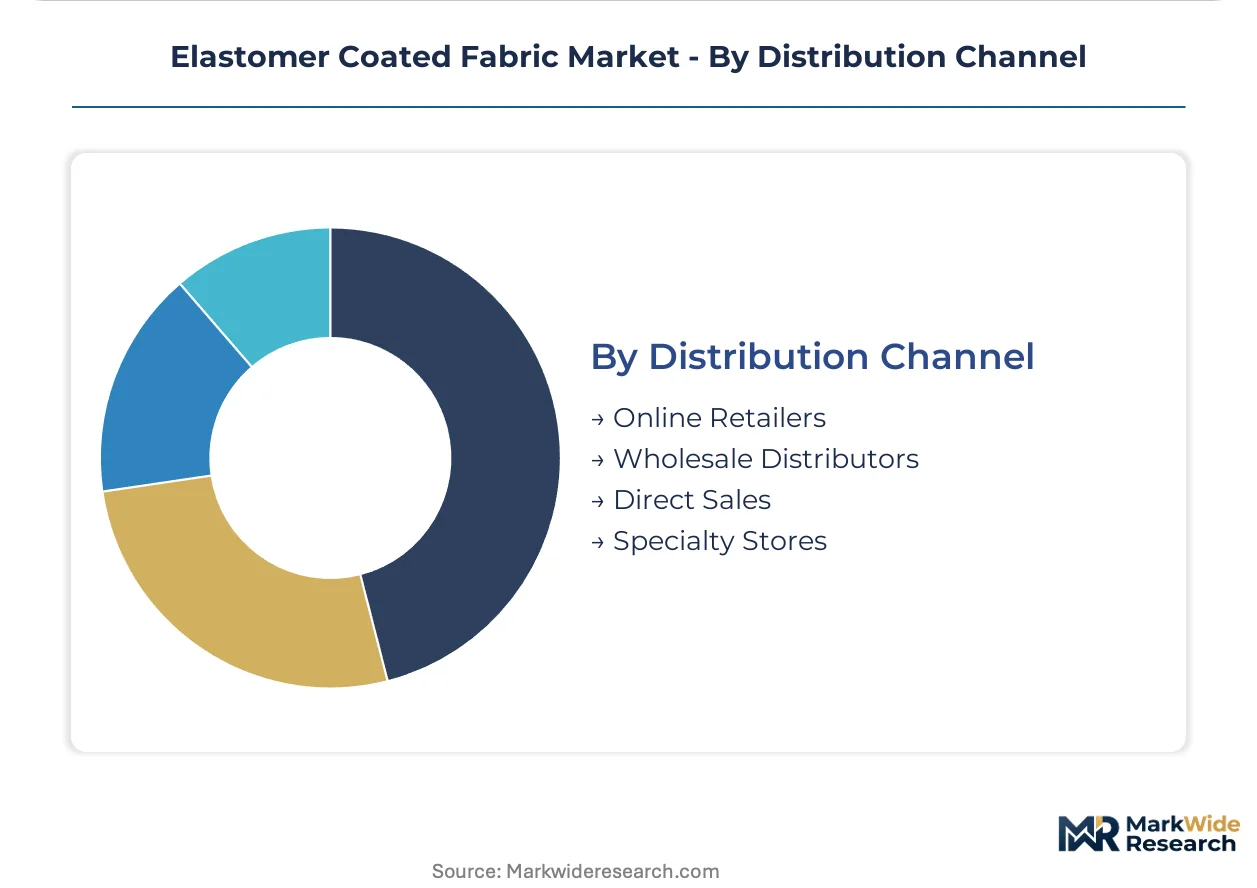
Distribution Channel:
Channel segmentation tracks order size and technical service intensity, with direct sales capturing complex automotive programs and wholesale distributors serving fragmented industrial demand.
- Direct Sales:Coating operations with in-house technical service teams contract directly with automotive OEMs and large industrial fabricators, managing 18-month qualification cycles and just-in-sequence delivery requirements. Stuttgart-Wolfsburg supplier cluster concentration enables this channel in Germany.
- Wholesale Distributors:Regional inventory positions serve small-to-mid industrial buyers and converter operations lacking volume to justify mill-direct relationships.
- Online Retailers:E-commerce penetration remains limited to standardized PVC and economy polyurethane grades for consumer and small commercial applications.
- Specialty Stores:Niche channels serve marine, outdoor, and protective equipment end users requiring application-specific technical guidance.
Direct sales captures the highest-margin throughput; wholesale distributors retain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane and silicone coating capacity clusters around automotive manufacturing corridors, with regulatory pressure on solvent-based systems redirecting investment toward waterborne and UV-curable alternatives. Germany and the United States concentrate tier-one supplier density, while India and China attract localization investments through production-linked incentives.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are consolidating direct procurement of silicone-coated textiles for electric vehicle battery enclosures and seating applications. REACH restrictions on isocyanates and plasticizers under ECHA's 2023-2025 roadmap are forcing polyurethane coaters to reformulate established recipes. The Baden-Württemberg and Lower Saxony supplier clusters now host vertically integrated operations spanning substrate weaving through finished roll goods.
United States
EPA NESHAP compliance mandates are driving retrofitting of solvent-based coating lines to waterborne or UV-curable systems across Ohio and Michigan manufacturing bases. Electric vehicle programs at Detroit-area OEMs are accelerating silicone substrate qualification for thermal management applications. The Midwest automotive corridor retains concentration of industrial membrane coaters serving conveyor belt and tension structure markets.
China
Domestic automotive brands are expanding specification authority over interior textile procurement, displacing merchant substrate suppliers in the Yangtze River Delta manufacturing belt. MEE enforcement of volatile organic compound limits is compressing legacy solvent-based production models in Jiangsu and Zhejiang provinces. Shanghai and surrounding clusters are attracting waterborne polyurethane dispersion capacity to serve local EV battery enclosure demand.
India
PLI scheme incentives for advanced chemistry cell manufacturing are drawing coating operations to Gujarat and Tamil Nadu to serve Maruti Suzuki and Hyundai Motor India seating programs. BIS certification requirements for automotive interior materials are extending supplier qualification timelines for multinational coaters entering the market. The Chennai and Ahmedabad industrial corridors are emerging as polyurethane coating hubs for localized automotive supply chains.
Japan
METI carbon neutrality roadmaps are pressing coated fabric producers to document scope-three emissions and accelerate process transitions. Automotive OEMs in the Nagoya and Tokyo metropolitan areas are consolidating textile procurement around silicone formulations capable of withstanding sustained thermal loads above 200 degrees Celsius. The Chubu and Kanto regions retain specialized neoprene capacity serving marine protective equipment manufacturers.
Elastomer Coated Fabric Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in polymer compounding and substrate weaving. The vendor base separates into three strata: multinational automotive suppliers with captive textile finishing, industrial membrane specialists with backward integration into polymer compounding, and regional coaters serving price-sensitive commercial segments. Dominant competitive moves include capacity expansion in waterborne polyurethane systems and strategic partnerships to secure polychloroprene feedstock.
Among vertically integrated industrial fabricators, Seaman Corporation exemplifies the polymer-to-roll-goods archetype, while Trelleborg AB occupies a position within marine and offshore protective fabric supply. Continental AG represents the automotive platform integrator tier, extending from substrate weaving through finished coated product to capture specification authority from tier-one seating manufacturers. These three anchors illustrate the competitive tension between upstream control and downstream system integration.
| Leading Market Players |
|---|
| Seaman Corporation |
| Serge Ferrari Group |
| Trelleborg AB |
| Spradling International Inc. |
| Sioen Industries NV |
| Continental AG |
| OMNOVA Solutions Inc. |
| Low & Bonar |
| Compagnie de Saint-Gobain S.A. |
| Others |
Supply & Pricing Matrix
Isocyanate feedstock volatility in MDI and TDI markets compresses polyurethane coating margins and forces tiered pricing separation between solvent-borne premium grades and waterborne standard formulations, while simultaneously reshaping procurement geography toward Germany's Stuttgart-Wolfsburg corridor where automotive OEMs consolidate direct supplier relationships.
Pricing Analysis
REACH restrictions on isocyanates and plasticizers dictate the pricing tier structure across European elastomer coated fabric manufacturing. Three-tier pricing structure across premium silicone grades for EV battery enclosures, standard waterborne polyurethane for automotive seating, and economy PVC variants for commercial upholstery reflects certification burden and thermal performance differentiation. Cost compression in standard polyurethane tiers is intensifying because tier-one automotive suppliers demand annual price-downs during contract renegotiations. Industrial membrane buyers exhibit lowest price sensitivity due to specification-critical applications, while commercial upholstery segments drive aggressive supplier competition.
Supply Chain Analysis
Export controls on advanced polymer additive technologies limit formulation knowledge transfer between European coaters and Asian manufacturing partners. Feedstock supply concentrates in Germany for automotive-grade polyurethane systems, the United States for silicone dispersion capacity, and East Asia for polychloroprene neoprene production. Coating operations draw from MDI/TDI isocyanate streams, polysiloxane silicone precursors, and plasticized vinyl resin inputs. Single-source vulnerability runs through East Asian polychloroprene suppliers serving marine protective fabric manufacturers. Distribution runs through direct mill relationships with automotive OEMs and wholesale distributor networks for fragmented industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM specification authority over interior textiles represents a platform-economics inflection where direct contracting with coaters displaces tier-one intermediary capture, enabled by interoperability between in-house weaving operations and finished roll-goods finishing.
For Market Incumbents: Pre-empt margin erosion from waterborne polyurethane qualification demands by securing captive isocyanate supply agreements and accelerating UV-curable silicone hybrid R&D to defend specification authority against emerging Asian coaters with cost-optimized solvent-based lines. For New Entrants and Emerging Players: Pursue India automotive seating localization under PLI scheme incentives in Gujarat and Tamil Nadu, where BIS certification barriers filter multinational competition and Hyundai Motor India procurement creates accessible white-space for regional coating operations with technical service capabilities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated polymer-to-roll-goods specialists over merchant substrate suppliers. Long-term viability across the analysis window hinges on carbon accounting verification for CSRD-mandated supplier selection. The signal to watch is automotive OEM direct contracting velocity as tier-one intermediaries lose specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Polyurethane Capacity Expansion | EPA NESHAP retrofit mandates in Ohio and Michigan create equipment upgrade demand for process chemical suppliers. |
| Silicone Formulation R&D Partnership | Electric vehicle battery enclosure specifications in Stuttgart and Wolfsburg pull thermal-resistant coating development. |
| Backward Integration into Polymer Compounding | Seaman Corporation's captive supply of industrial membrane inputs demonstrates margin defense against merchant competitors. |
| India Localization Joint Venture | PLI scheme incentives in Gujarat and Tamil Nadu enable just-in-sequence delivery to Maruti Suzuki seating programs. |
| Scope-Three Carbon Certification Program | EU Green Deal CSRD reporting obligations reward verified carbon accounting with premium supplier positioning. |
Research Methodology
The analysis maps silicone, polyurethane, neoprene, and PVC coating sub-sectors, each validated through primary interviews with automotive tier-one procurement directors, industrial membrane specification engineers, coating plant operations managers, and marine protective fabric technical buyers, combined with secondary triangulation against EPA NESHAP compliance filings, ECHA SVHC candidate list updates, SEC 10-K disclosures from publicly traded coating operations, and automotive production registration databases, employing bottom-up capacity modeling and top-down demand segmentation reconciliation.
Forecast assumptions held regulatory trajectory fixed at ECHA's 2023-2025 restriction roadmap and EPA NESHAP enforcement intensity, while varying electric vehicle adoption curves and automotive interior content per vehicle across the projection horizon. Segmentation dimensions modeled include coating chemistry type, end-use application, OEM procurement tier, and regional manufacturing cluster concentration. CAGRs derive from installed capacity utilization trends and qualification cycle compression effects, with specific inputs from REACH authorization timelines and PLI scheme incentive disbursement patterns.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, isocyanate feedstock pricing, or currency volatility in East Asian polychloroprene supply markets would shift the trajectory. Forecasts reflect these anchored assumptions without claiming predictive certainty. Material shifts in EPA or ECHA regulatory enforcement intensity, or breakthrough UV-curable silicone hybrid adoption rates, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Global Elastomeric Coating Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Stretchable Conductive Material Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market