
 LAMEA 3D Graphene Market | 2026-2036
LAMEA 3D Graphene Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA 3D Graphene Market Insights
Layer-by-layer assembly and chemical vapor deposition integration is tilting manufacturing economics toward scalable 3D architectures. CVD Equipment Corporation leverages its reactor expertise to anchor North American-to-LAMEA technology transfer. Nano Dimension specializes in additive manufacturing platforms that embed graphene conductors directly into functional parts. American Elements sustains raw material supply chains spanning rare earth precursors to finished graphene oxide dispersions.
LAMEA 3D Graphene comprises carbon allotropes arranged in three-dimensional porous or networked scaffolds, typically exhibiting specific surface areas exceeding 500 square meters per gram and electrical conductivity surpassing 1000 siemens per meter, engineered for structural reinforcement, thermal management, and electrochemical interfaces. Reduced graphene oxide dominates current volume shipments due to mature reduction protocols and cost-efficient aqueous processing. Energy storage applications capture expanding margin pools as supercapacitor and solid-state battery developers specify 3D graphene current collectors. Composite materials remain the foundational revenue base across aerospace and automotive tier-one suppliers.
Brazil's ANVISA and South Africa's Department of Trade, Industry and Competition impose evolving nanomaterial safety protocols that shape product registration timelines and import documentation burdens. Saudi Arabia's SFDA and the UAE's MOHAP are constructing healthcare-grade graphene approval pathways for biomedical sensor applications. Stakeholders must monitor how LAMEA regulatory divergence affects cross-border formulation standardization and clinical trial portability.
Market Dynamics
Layer-by-layer assembly and chemical vapor deposition integration are compressing unit economics for scalable 3D architectures, while Brazil's ANVISA and South Africa's Department of Trade, Industry and Competition impose evolving nanomaterial safety protocols that reshape product registration timelines across the region.
Growth Catalysts
- Energy storage specification:Supercapacitor and solid-state battery developers in São Paulo's industrial corridor are mandating 3D graphene current collectors for next-generation electrochemical interfaces.
- South African research funding:The Department of Science and Innovation has accelerated capital deployment into advanced materials research, stimulating localized production capacity for reduced graphene oxide.
- Aerospace composite procurement:Tier-one suppliers across Latin America are expanding orders for structural reinforcement materials incorporating 3D graphene scaffolds.
Market Restraints
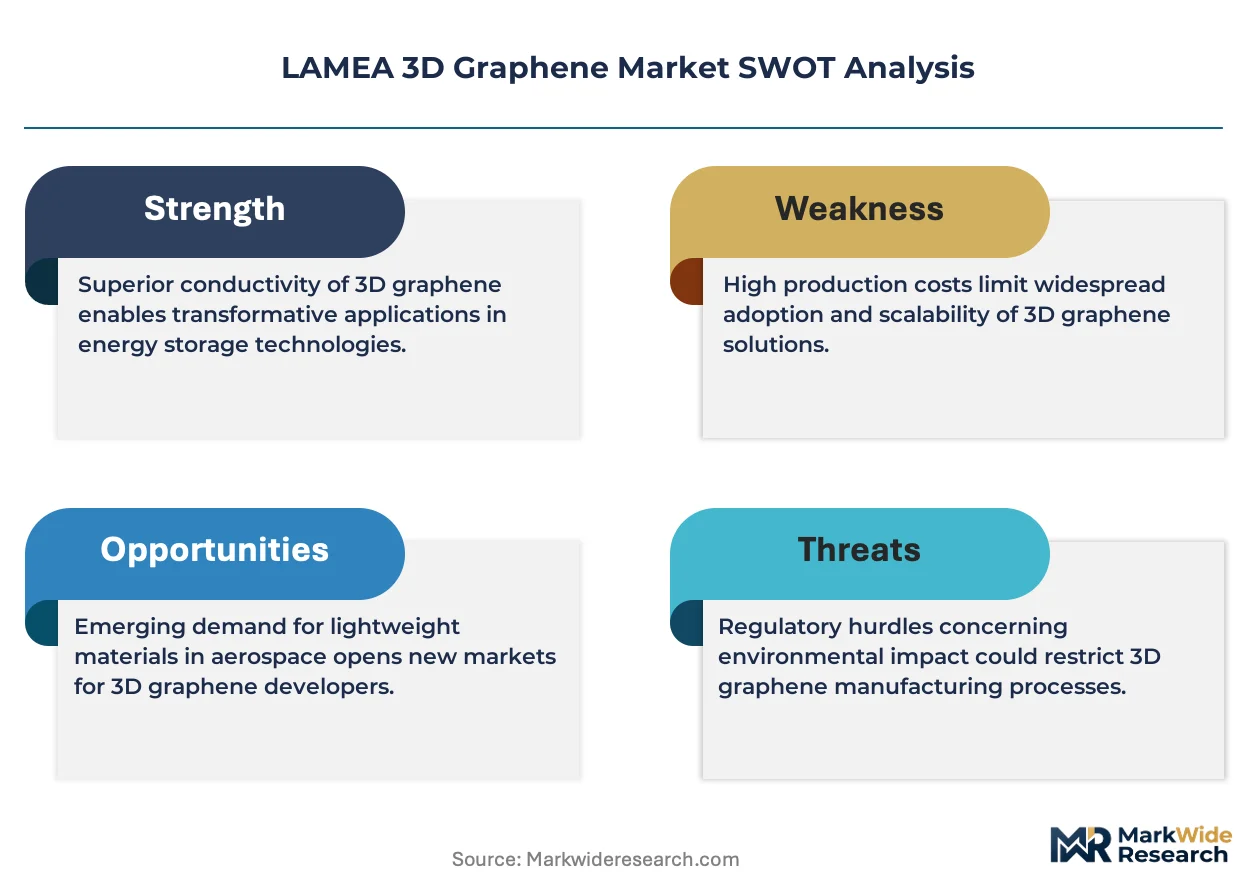
- Input cost volatility:Fluctuations in rare earth precursor prices destabilize graphene oxide dispersion economics for aqueous processing facilities.
- Regulatory friction:Divergent nanomaterial safety protocols between ANVISA and South Africa's Department of Trade, Industry and Competition fragment cross-border formulation standardization.
- Technical limitation:Specific surface area consistency below 500 square meters per gram in batch-produced reduced graphene oxide restricts high-performance applications.
Strategic Opportunities
- Saudi biomedical pathway:The SFDA is constructing healthcare-grade graphene approval frameworks for sensor applications, opening regulated medical device channels.
- UAE regulatory alignment:MOHAP's emerging nanomaterial standards create early-mover positioning for clinical trial portability across Gulf markets.
- Technology convergence:Additive manufacturing platforms embedding graphene conductors directly into functional parts enable part-consolidation in Brazil's electronics clusters.
Industry Challenges
- Certification timeline compression:ANVISA's evolving documentation burdens extend product registration cycles, straining working capital for import-dependent formulators.
- Capex intensity for CVD reactors:Capital equipment requirements for chemical vapor deposition integration exceed mid-tier producer balance sheet capacity.
- Standardization delays:Absence of harmonized LAMEA test protocols for electrical conductivity measurement complicates buyer qualification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA 3D Graphene Market |
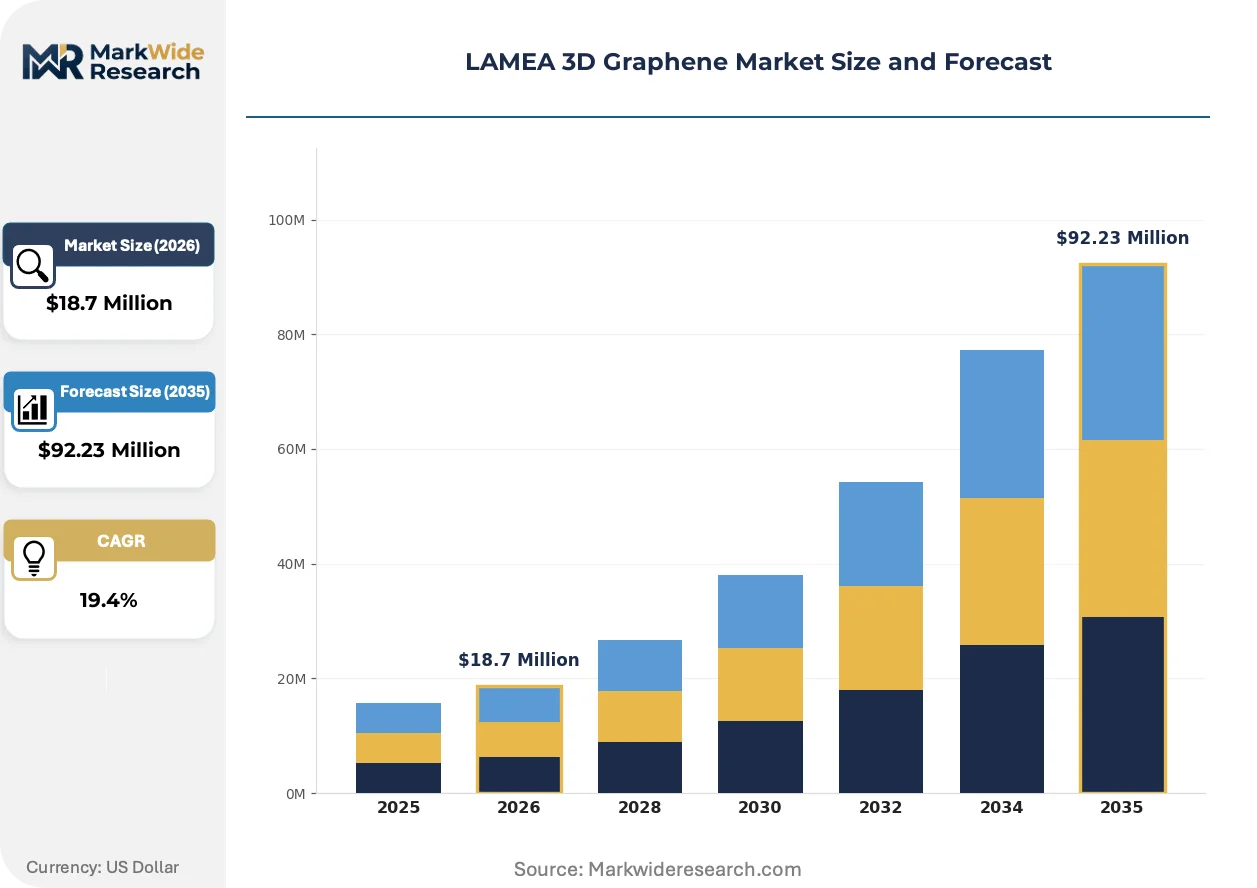
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $92.23 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
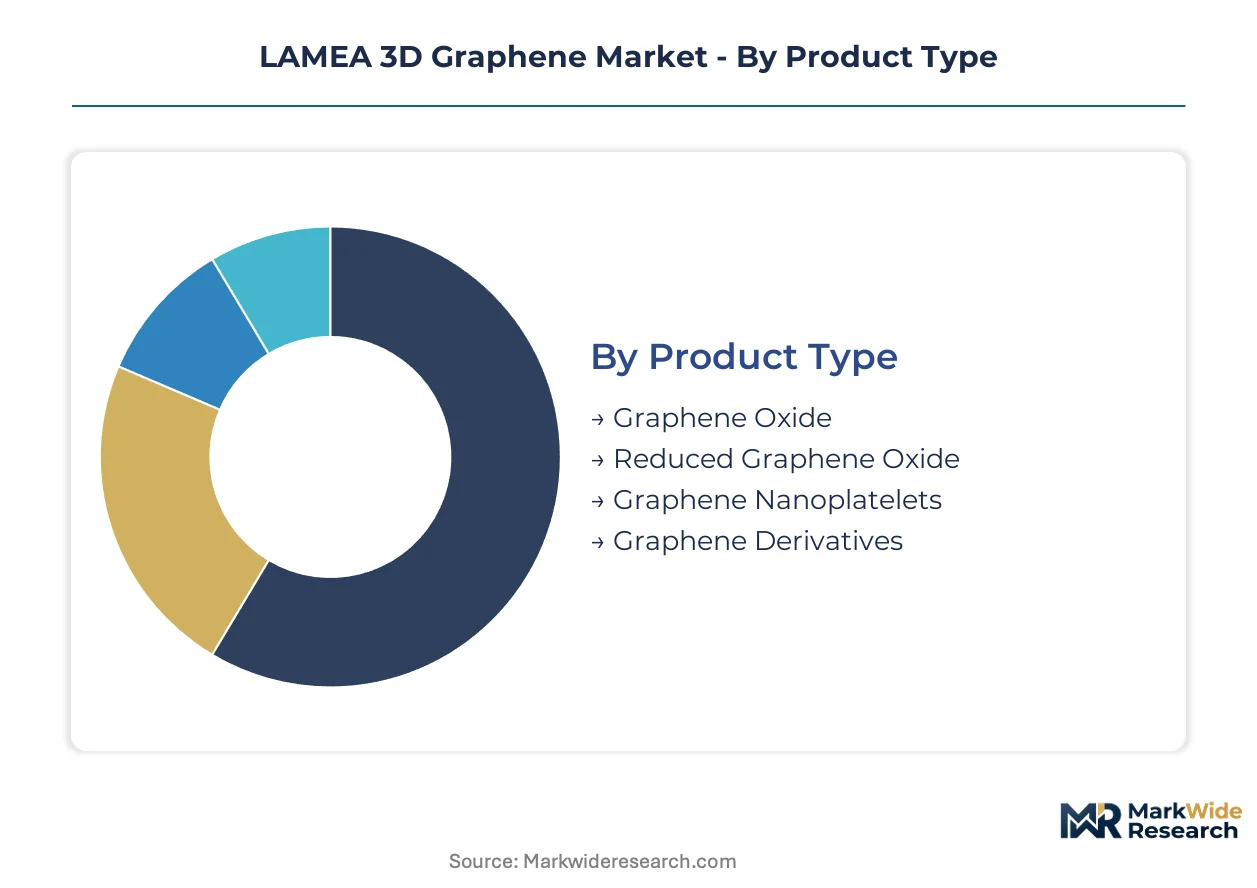
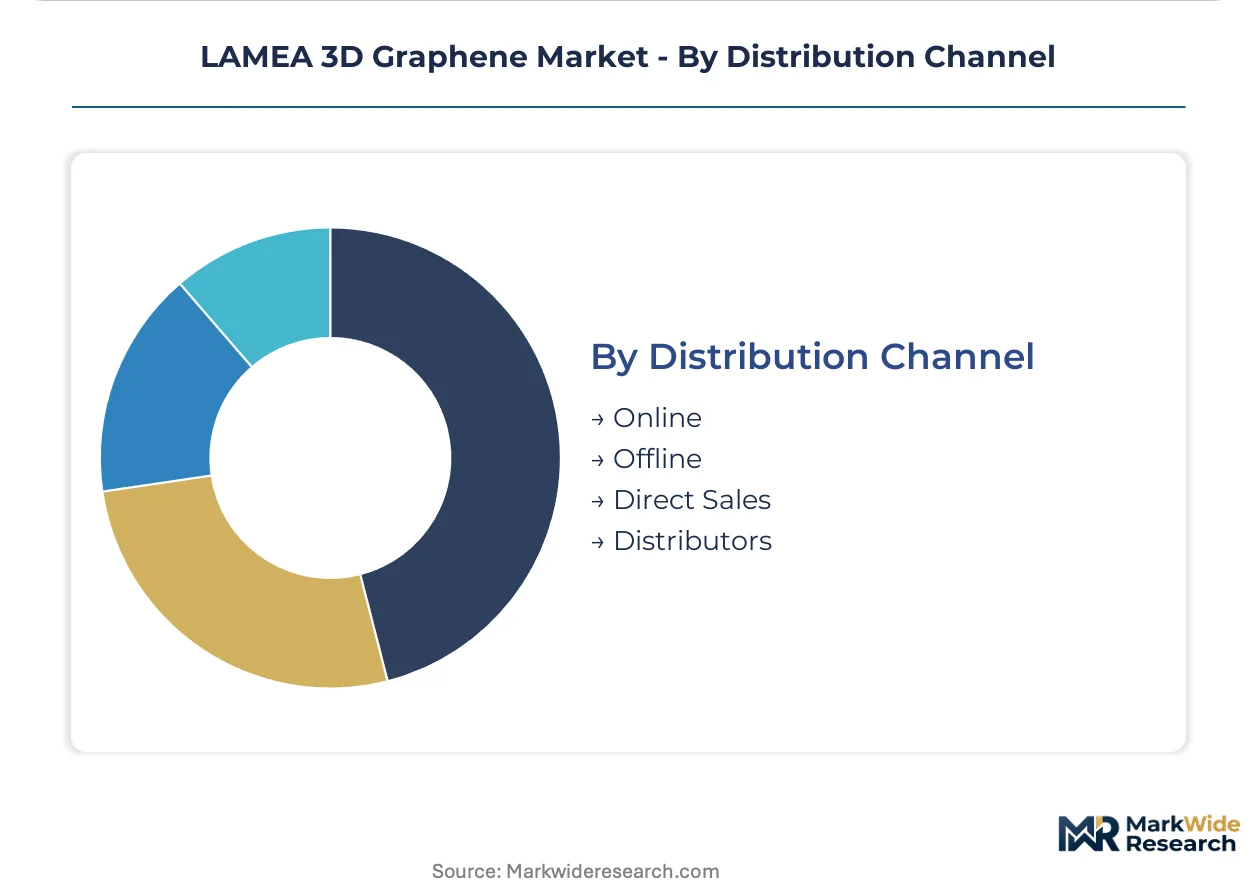
| Segmentation | Product Type: Graphene Oxide, Reduced Graphene Oxide, Graphene Nanoplatelets, Graphene Derivatives End User: Aerospace, Electronics, Energy, Healthcare Application: Composite Materials, Conductive Coatings, Energy Storage, Sensors Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | NANOCHEMAZONE, CVD Equipment Corporation, American Elements, Lyten, Inc., Graphex Group, Integrated Graphene Ltd., Nano Dimension, G6 Materials Corp., ACS Material, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA 3D Graphene Market Trends and Innovations
Chemical vapor deposition integration is virtualizing traditional manufacturing boundaries, while regulatory divergence across Brazil, South Africa, and Gulf states is fragmenting compliance architectures. Demand-side specification behavior is compressing supplier qualification cycles.
Chemical vapor deposition reactor technology is virtualizing the boundary between raw material processing and finished component fabrication. Aerospace tier-one suppliers in São Paulo and Dubai are adopting CVD-integrated graphene reinforcement at pilot scale. This convergence is virtualizing the historical separation between materials suppliers and composite manufacturers, compressing value chain margins at intermediate processing stages.
South Africa's Department of Science and Innovation funding mandates now require local content thresholds for advanced materials research grants. This industrial policy is redirecting foreign direct investment toward joint-venture structures with domestic universities. Reduced graphene oxide producers are responding by licensing aqueous reduction protocols to Johannesburg-based manufacturing partners rather than exporting finished dispersions.
Buyer concentration in Brazil's energy storage cluster is compressing supplier switching cycles from annual to quarterly review periods. São Paulo-based supercapacitor developers are unbundling after-sales technical service from material supply contracts, creating standalone consulting revenue streams. This behavioral shift is most visible in the electronics corridor where procurement teams now specify electrical conductivity thresholds exceeding 1000 siemens per meter as baseline qualification criteria.
LAMEA 3D Graphene Market Segmentation
Product architecture, end-use specification, and route-to-market configuration each create distinct margin pools and qualification barriers across the LAMEA 3D graphene value chain. Buyers in São Paulo's electronics corridor and Dubai's aerospace clusters segment procurement by conductivity thresholds and regulatory compliance tier rather than commodity pricing alone.
Product Type:
Mature reduction protocols anchor volume economics at the base of the product pyramid, while CVD-integrated architectures command premium positioning at the apex.
- Reduced Graphene Oxide:Aqueous processing protocols yield specific surface areas exceeding 500 square meters per gram with electrical conductivity surpassing 1000 siemens per meter. South Africa's Department of Science and Innovation funding mandates now require local content thresholds, redirecting foreign direct investment toward Johannesburg-based manufacturing partners rather than finished dispersion imports.
- Graphene Oxide:Precursor material for downstream reduction, processed through mature oxidation-intercalation-exfoliation sequences. Brazil's ANVISA evolving nanomaterial safety protocols extend product registration cycles for import-dependent formulators in São Paulo's industrial corridor, straining working capital.
- Graphene Nanoplatelets:Exfoliated graphite structures with platelet morphology serving composite reinforcement applications.
- Graphene Derivatives:Functionalized variants including nitrogen-doped and fluorinated architectures for specialized electrochemical interfaces.
Reduced Graphene Oxide handles the majority of throughput; Graphene Derivatives is expanding most quickly on share.
End User:
Application pull concentrates in capital-intensive sectors where structural reinforcement and thermal management specifications justify material premiums.
- Energy:Supercapacitor and solid-state battery developers mandate 3D graphene current collectors for next-generation electrochemical interfaces. São Paulo-based procurement teams unbundle after-sales technical service from material supply contracts, creating standalone consulting revenue streams with quarterly rather than annual supplier review cycles.
- Aerospace:Tier-one suppliers across Latin America expand orders for composite materials incorporating 3D graphene scaffolds for structural reinforcement. CVD-integrated graphene reinforcement pilots are operational in São Paulo and Dubai, virtualizing the historical separation between materials suppliers and composite manufacturers.
- Electronics:High-conductivity derivatives for next-generation components in Brazil's São Paulo industrial corridor.
- Healthcare:Saudi Arabia's SFDA and UAE's MOHAP construct healthcare-grade graphene approval pathways for biomedical sensor applications.
Energy captures the steepest expansion trajectory; Aerospace retains the deepest contract tenure and technical service attachment.
Application:
Functional specification separates commodity coating applications from architecturally complex scaffold integrations.
- Energy Storage:3D porous architectures engineered for supercapacitor electrodes and solid-state battery current collectors. Buyer concentration in São Paulo compresses supplier switching cycles, with electrical conductivity thresholds exceeding 1000 siemens per meter now baseline qualification criteria.
- Composite Materials:Structural reinforcement matrices for aerospace and automotive tier-one suppliers. Layer-by-layer assembly and chemical vapor deposition integration compress unit economics while enabling scalable 3D architectures.
- Conductive Coatings:Surface-applied formulations for electromagnetic shielding and thermal dissipation.
- Sensors:Biomedical and industrial detection platforms requiring high surface-area electrochemical interfaces.
Energy Storage is climbing the fastest on specification intensity; Composite Materials maintains the broadest cross-sector qualification.
Distribution Channel:
Channel configuration reflects buyer scale, technical support requirements, and regulatory documentation burdens.
- Direct Sales:Large-volume contracts with tier-one aerospace and energy storage developers requiring embedded technical service. ANVISA's evolving documentation burdens favor direct relationships where regulatory compliance expertise can be co-developed.
- Distributors:Regional inventory positioning for mid-tier electronics and healthcare formulators across Brazil and South Africa. Fragmented nanomaterial safety protocols between ANVISA and South Africa's Department of Trade, Industry and Competition complicate cross-border formulation standardization.
- Online:Catalog-based procurement for research-grade materials and standardized dispersions.
- Offline:Traditional trade relationships serving legacy industrial accounts with established qualification histories.
Direct Sales commands the highest service attachment margin; Distributors is gaining share fastest through regional regulatory navigation capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for 3D graphene precursors shapes competitive positioning across Latin America, Middle East, and Africa. Export-oriented producers in South Africa and Brazil are redirecting foreign direct investment toward localized reduction facilities. Cross-border formulation standardization remains fragmented by divergent nanomaterial safety protocols.
Brazil
São Paulo's industrial corridor concentrates demand from supercapacitor developers and electronics manufacturers specifying electrical conductivity thresholds exceeding 1000 siemens per meter. ANVISA's evolving nanomaterial safety protocols extend product registration cycles, straining working capital for import-dependent formulators. The city's energy storage cluster now unbundles after-sales technical service from material supply contracts.
South Africa
Johannesburg-based manufacturing partnerships are absorbing licensed aqueous reduction protocols from foreign graphene oxide producers. The Department of Science and Innovation mandates local content thresholds for advanced materials research grants, redirecting capital deployment toward domestic production capacity. Specific surface area consistency in batch-produced reduced graphene oxide remains a technical limitation for high-performance applications.
Saudi Arabia
SFDA is constructing healthcare-grade graphene approval frameworks for biomedical sensor applications, opening regulated medical device channels. Domestic aerospace tier-one suppliers are piloting CVD-integrated graphene reinforcement for structural composite applications. Riyadh's research institutions are attracting joint-venture structures with international materials specialists.
United Arab Emirates
MOHAP's emerging nanomaterial standards create early-mover positioning for clinical trial portability across Gulf markets. Dubai's aerospace clusters are operationalizing CVD-integrated graphene reinforcement pilots, virtualizing the historical separation between materials suppliers and composite manufacturers. The emirate's procurement teams specify 3D graphene scaffolds for next-generation thermal management systems.
Israel
Specialized electrochemical interface developers are sourcing graphene derivatives for sensor platforms targeting industrial detection applications. The national innovation authority channels capital toward additive manufacturing platforms embedding graphene conductors directly into functional parts. Tel Aviv's electronics corridor exhibits compressed supplier switching cycles from annual to quarterly review periods.
LAMEA 3D Graphene Market Competitive Landscape
On the supply side, the industry is bifurcated between aqueous processing specialists and CVD-integrated platform operators. Mid-tier producers face balance sheet constraints for capital equipment requirements, while research-grade suppliers compete on technical service attachment rather than commodity pricing. Two strategic archetypes dominate: licensed protocol operators leveraging local content mandates, and reactor-technology holders facilitating North American-to-LAMEA transfer. Capacity expansion and technology licensing represent the dominant competitive vectors.
Among North American technology holders, CVD Equipment Corporation and American Elements exemplify distinct positioning archetypes. CVD Equipment Corporation occupies a reactor-technology anchor position, while American Elements sustains raw material supply chain spanning rare earth precursors to finished dispersions. Nano Dimension represents the additive manufacturing convergence vector, embedding graphene conductors directly into functional parts. These three entities collectively illustrate the technology-transfer and manufacturing-integration pathways reshaping supplier qualification across São Paulo, Johannesburg, and Dubai industrial clusters.
| Leading Market Players |
|---|
| NANOCHEMAZONE |
| CVD Equipment Corporation |
| American Elements |
| Lyten, Inc. |
| Graphex Group |
| Integrated Graphene Ltd. |
| Nano Dimension |
| G6 Materials Corp. |
| ACS Material |
| Others |
Pricing and Supply Chain Analysis
The São Paulo-Dubai air freight corridor carries rare earth precursors and finished graphene oxide dispersions at rates that compress margins for aqueous processing facilities while amplifying price premiums for CVD-integrated architectures. This logistics chokepoint concentrates supply-side bargaining power among reactor-technology holders and fragments downstream price differentiation across import-dependent formulators.
Pricing Analysis
Current-generation CVD-integrated graphene scaffolds command substantial premiums over prior-generation reduced graphene oxide volumes, while next-generation additive-manufactured conductors sit at price discovery. Three-tier pricing structure across premium, standard, and economy levels separates certification-grade biomedical materials from industrial composite grades and research-grade dispersions. Cost compression in standard-grade reduced graphene oxide intensifies because South African local content mandates redirect foreign investment toward licensed Johannesburg production. Energy storage developers in São Paulo exhibit lowest price sensitivity due to unbundled technical service contracts, while mid-tier electronics formulators face acute margin pressure from ANVISA registration burdens.
Supply Chain Analysis
Upstream feedstock for graphene oxide precursors draws from graphite mining concentrates in China, Mozambique, and Madagascar, with rare earth catalysts sourced from Chinese separation facilities and Australian heavy mineral sands. Aqueous processing equipment and CVD reactor components hinge on German, Japanese, and South Korean precision manufacturing. Single-source vulnerability concentrates in Chinese graphite supply, where export license volatility disrupts precursor economics for Brazilian and South African reduction facilities. Distribution runs through direct sales channels for tier-one aerospace and energy accounts, with regional distributors navigating fragmented ANVISA and South African Department of Trade, Industry and Competition documentation requirements for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LAMEA 3D graphene represents high-growth materials disruption, with chemical vapor deposition integration and divergent nanomaterial safety protocols across Brazil, South Africa, and Gulf states creating simultaneous technology and regulatory inflection points.
For Market Incumbents: Build certification moats around healthcare-grade graphene pathways before SFDA and MOHAP frameworks mature. Anchor defensive positioning through backward integration into Johannesburg-based aqueous reduction capacity to satisfy South African Department of Science and Innovation local content thresholds. Deepen technical service attachment for São Paulo energy storage clusters where quarterly supplier reviews compress switching costs. For New Entrants and Emerging Players: Pursue additive manufacturing convergence for electronics corridor applications in São Paulo and Tel Aviv where CVD capex barriers exclude mid-tier competitors. Target biomedical sensor segments in Saudi Arabia and UAE where regulatory pathways remain under construction and first-mover certification yields multi-year exclusivity. Lead go-to-market through joint-venture structures with domestic universities to access South African research funding mandates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors reactor-technology holders and licensed protocol operators over commodity dispersion suppliers. Long-term viability rests on regulatory navigation capabilities across fragmented LAMEA safety frameworks rather than scale economics alone. Signal to watch: harmonization initiatives between ANVISA and Gulf state regulators that would compress qualification timelines and shift competitive advantage toward standardized product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing to Local Partners | South African local content mandates redirect FDI toward Johannesburg manufacturing joint ventures. |
| Healthcare-Grade Certification Investment | SFDA and MOHAP pathway construction opens regulated medical device channels in Gulf markets. |
| Direct Sales Channel Expansion | ANVISA documentation burdens favor embedded compliance expertise for São Paulo energy clusters. |
| Additive Manufacturing Platform Development | Nano Dimension convergence enables part-consolidation in Brazil's electronics corridor. |
| CVD Reactor Capacity Buildout | Chemical vapor deposition integration virtualizes boundaries between materials and composite manufacturers. |
Research Methodology
The analysis maps reduced graphene oxide, CVD-integrated scaffolds, and additive-manufactured conductors, each validated through primary interviews with graphene plant managers, aerospace tier-one procurement leads, energy storage R&D directors, and regulatory affairs specialists at ANVISA and SFDA, combined with secondary triangulation against customs trade data, SEC filings from North American technology holders, and advanced materials research grant disclosures from South Africa's Department of Science and Innovation. Bottom-up volume builds from facility-level capacity and utilization rates cross-check against top-down demand aggregation from end-use specification behavior.
Assumption sets held regulatory divergence and technology substitution rates as variable inputs while fixing geographic production cost structures and freight rate baselines across the analysis window. Segmentation dimensions modeled include product architecture tier, end-use industry, application functional specification, and route-to-market configuration. CAGRs derive from logistic diffusion curves fitted to buyer specification intensity data, with supercapacitor and solid-state battery demand trajectories serving as primary volume drivers.
Macroeconomic conditions sit as an overlay; deviation in rare earth precursor prices, air freight rates, or LAMEA currency volatility would shift the trajectory. Forecasts reflect documented assumptions about CVD equipment cost decline curves and regulatory harmonization timelines. Cross-checking against aerospace composite procurement databases and hospital medical device approval registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
3D Printing Powder Market
3D Printing Materials
3D Printing PLA Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market