
 Saudi Arabia Plastic Packaging Films Market | 2026-2036
Saudi Arabia Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Plastic Packaging Films Market Insights
Buyer concentration among Saudi food processors and dairy cooperatives is hardening as scale requirements for automated packaging lines favor suppliers with dedicated technical service teams. Napco National leverages integrated blown film extrusion and printing capabilities to anchor long-term contracts with domestic dairy leaders. Takween Advanced Industries competes through specialized multilayer barrier films for pharmaceutical blister packs. Arabian Plastic Industrial Company Limited (APICO) sustains regional distribution advantages across the GCC via its Jeddah manufacturing complex.
Saudi Arabia plastic packaging films comprise thermoplastic polymer sheets typically ranging from 12 to 150 microns in thickness, manufactured through cast or blown extrusion processes, designed to protect, contain, and preserve goods across supply chains. Stretch films dominate industrial palletization due to load-stability requirements at Saudi logistics hubs handling petrochemical exports. Flexible films capture expanding share in retail-ready food packaging as domestic supermarkets adopt modified-atmosphere formats. Polyethylene grades, particularly linear low-density formulations, lead material consumption given their cost-performance balance for high-volume bread and frozen food applications.
SFDA governs food-contact compliance while SASO mandates quality marks for imported film rolls, with both agencies intensifying post-market surveillance that raises barriers for uncertified traders. The EU Green Deal's extraterritorial influence is pressuring Saudi exporters to document recyclability credentials for European-bound packaged goods. Stakeholders must monitor how the Kingdom's domestic recycling infrastructure investments reshape virgin resin pricing and post-consumer content mandates.
Market Dynamics
SFDA's tightened food-contact material rules are compressing supplier timelines and forcing converters to rebuild certification portfolios, while Riyadh's industrial corridor concentrates demand among automated packaging lines that exclude smaller film traders.
Growth Catalysts
- Quick-service restaurant expansion:Domestic fast-food chains are scaling centralized commissary operations that demand high-throughput flexible packaging, pulling multilayer film volumes into Riyadh and Jeddah production zones.
- Modified-atmosphere packaging adoption:Saudi supermarket operators are retrofitting deli and produce sections with gas-flush systems that require EVOH-barrier films previously absent from local converter portfolios.
- GCC export channel maturation:Jeddah's Red Sea port infrastructure is shortening lead times to Egyptian and East African markets, enabling Saudi film converters to displace European suppliers in regional dairy packaging tenders.
Market Restraints
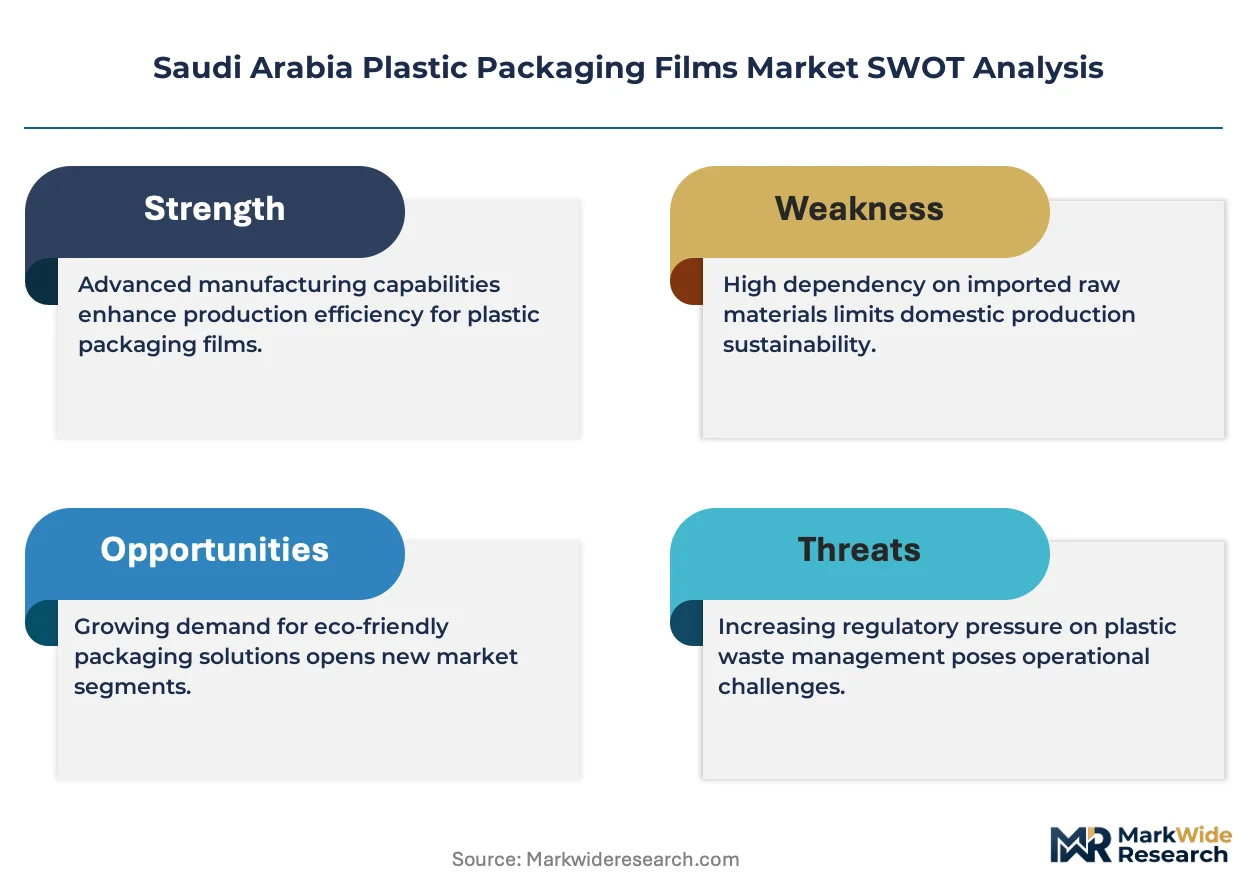
- Ethylene feedstock concentration:SABIC and its joint-venture partners control over 90% of domestic polyethylene resin supply, exposing converters to single-source pricing volatility and allocation constraints during cracker maintenance cycles.
- SFDA compliance timeline compression:The 2024 updated food-contact regulations shortened migration testing windows from 180 to 90 days, forcing importers to hold larger safety stocks or risk customs detention at Jeddah Islamic Port.
- Paper-fiber substitution in premium retail:European retailers sourcing Saudi packaged dates and nuts are mandating fiber-based primary packaging for shelf-ready displays, eroding high-margin film applications in export-oriented processing.
Strategic Opportunities
- Tabuk and Northern Borders underpenetration:The Kingdom's northwestern agricultural expansion around Al-Jawf date farms lacks localized film converting capacity, creating white space for blown-film operations serving on-farm packing stations.
- Post-consumer recycled content mandates:Saudi Investment Recycling Company's projected 2030 targets for 35% recycled plastic in packaging will reward early movers with captive mechanical recycling streams and preferential government procurement access.
- Digital printing convergence:Integration of HP Indigo and Xeikon systems with cast extrusion lines is enabling run-length flexibility down to 500 kilograms, opening short-shelf-life dairy and fresh juice segments previously closed to rotogravure-dominated suppliers.
Industry Challenges
- Blown-film technician scarcity:The Kingdom's technical and vocational training pipeline produces fewer than 200 certified extrusion operators annually, forcing converters to poach talent from petrochemical maintenance divisions at 40% wage premiums.
- Legacy ERP integration with traceability mandates:SFDA's batch-level serialization requirements are crashing against decades-old MRP systems at mid-tier Jeddah converters, requiring 18-24 month SAP or Oracle implementations that delay compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Plastic Packaging Films Market |
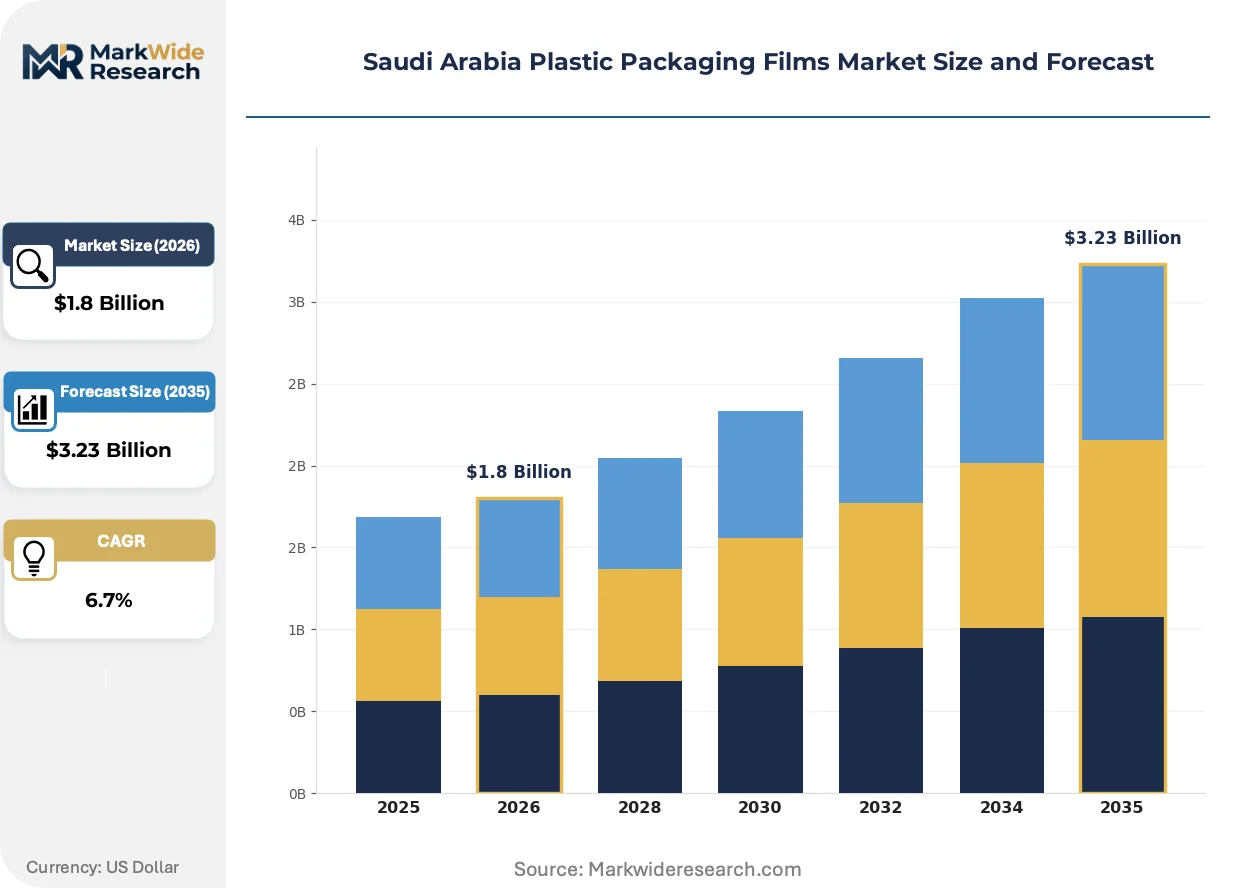
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Stretch Films, Shrink Films, Rigid Films, Flexible Films Material: Polyethylene, Polypropylene, Polyvinyl Chloride, BOPET Application: Food Packaging, Industrial Packaging, Medical Packaging, Retail Packaging End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics |
| Companies Covered | 3P Gulf Group, Arabian Plastic Industrial Company Limited (APICO), Napco National, Takween Advanced Industries, Rowad Global Packaging Company Ltd, ENPI Group, Falcon Pack, Interplast (Harwal Group of Companies), Obeikan Investment Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Plastic Packaging Films Market Trends and Innovations
Automation and regulatory digitization are compressing traditional supplier hierarchies, while downstream buyers reconfigure procurement around circularity credentials rather than unit cost alone.
Multilayer coextrusion with inline thickness gauging is automating quality control previously handled by offline laboratory technicians, allowing Riyadh-based dairy film suppliers to guarantee ±3% gauge tolerance in real time. Large processors including Almarai and Nadec are specifying these systems for new line approvals, effectively disqualifying converters without metrology integration. The technology is automating away the sampling-based inspection protocols that once protected smaller regional suppliers.
SFDA's electronic submission platform for food-contact notifications is hardening documentary requirements for substance migration data, forcing non-Saudi resin distributors to retain Kingdom-registered toxicology consultants. The industrial consequence is a 60-day average extension in new product registration timelines, compressing first-mover advantage windows for imported specialty films. Pharmaceutical blister pack converters are most affected, as Takween and similar specialists must now pre-submit complete additive inventories before quoting GCC tenders.
Centralized procurement consolidation among Saudi supermarket chains is displacing fragmented film purchasing through independent converters, with Carrefour Saudi and Tamimi Markets now mandating direct supplier relationships for private-label packaging. The segment being disrupted is the traditional distributor-converter middle layer that handled specification translation and small-lot aggregation. This pattern is most visible in Riyadh's retail consolidation, where three buying groups now control over 70% of flexible food packaging specifications.
Saudi Arabia Plastic Packaging Films Market Segmentation
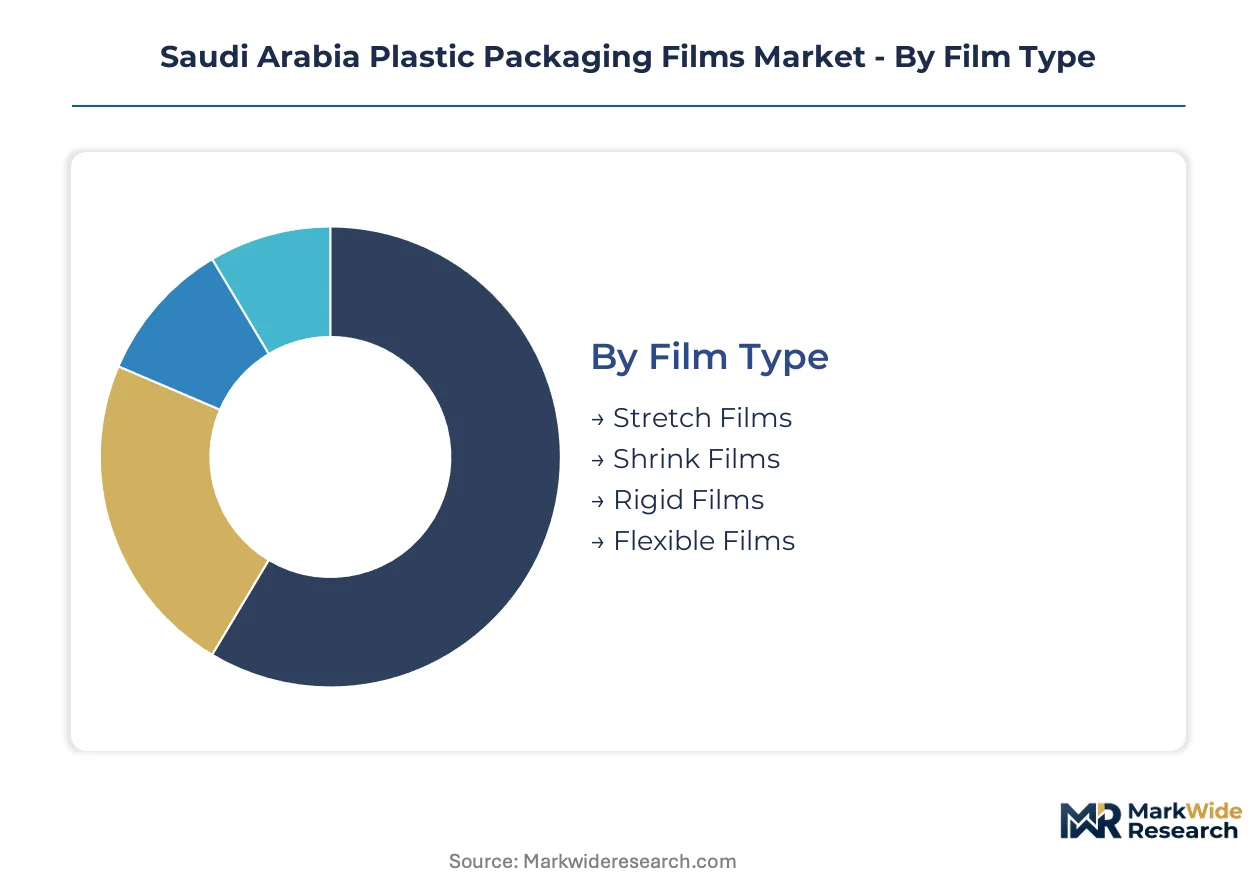
Film converters across Saudi Arabia configure production lines around thickness tolerances and barrier specifications that diverge sharply between dairy commissaries and petrochemical palletization. The segmentation structure reveals how Riyadh's industrial corridor concentrates high-volume polyethylene capacity while Jeddah's port-adjacent plants serve pharmaceutical export formats demanding multilayer precision.
Film Type:
Standardization dominates high-throughput stretch and shrink formats, while flexible films demand customized coextrusion recipes for modified-atmosphere compatibility.
- Stretch Films:Linear low-density polyethylene formulations engineered for 200-300% elongation secure pallet loads at Jubail petrochemical export terminals. Demand concentrates at Saudi Aramco-affiliated logistics hubs where automated wrapping lines specify 23-micron minimum gauges for load stability during Red Sea transit.
- Flexible Films:Multilayer structures incorporating EVOH or PA barriers enable gas-flush packaging for Almarai dairy and Nadec juice portfolios. Conversion capacity is concentrating in Riyadh's Second Industrial City where inline printing and metallization serve retail-ready formats.
- Shrink Films:Cross-linked polyolefin grades provide printed sleeve applications for bottled water and beverage multipacks.
- Rigid Films:Thermoformable APET and CPET sheets serve pharmaceutical blister packs and prepared meal trays.
Most installed capacity flows through stretch films serving industrial logistics. Expansion is steepest in flexible films as supermarket chains retrofit deli cases with modified-atmosphere systems.
Material:
Cost-performance positioning separates commodity polyethylene volumes from specialty barrier resins commanding technical service premiums.
- Polyethylene:LLDPE and LDPE grades absorb over 60% of domestic resin throughput, blown into bread bags, frozen food pouches, and industrial stretch formats. SABIC's Yanbu and Jubail crackers supply feedstock, though converters face allocation constraints during maintenance turnarounds.
- BOPET:Biaxially oriented polyethylene terephthalate delivers dimensional stability and optical clarity for pharmaceutical blister lidding and high-barrier snack lamination. Takween Advanced Industries anchors domestic BOPET metallization capacity for GCC pharmaceutical exports.
- Polypropylene:Cast and oriented PP films serve label stocks, tape backings, and retort pouch applications.
- Polyvinyl Chloride:Plasticized and rigid PVC formulations persist in medical device blister packs and shrink sleeve segments despite sustainability headwinds.
Polyethylene commands the heaviest extruder utilization across the Kingdom. BOPET is climbing the fastest as pharmaceutical serialization mandates tighten barrier specifications.
Application:
Regulatory intensity separates food-contact compliance burdens from industrial formats governed primarily by mechanical performance.
- Food Packaging:SFDA-mandated migration testing and substance notifications apply to all film layers contacting dairy, meat, and baked goods. Centralized commissaries for Maestro Pizza and Herfy Food Services are pulling high-clarity LLDPE and barrier coextrusions into Riyadh production zones.
- Medical Packaging:Sterile barrier systems for syringe and IV bag formats require ISO 11607 validation and SFDA facility licensing. Jeddah's King Abdullah Economic City clusters medical device assembly with adjacent film converting for GCC hospital supply chains.
- Industrial Packaging:Stretch and shrink formats for palletized petrochemical exports prioritize load containment over regulatory documentation.
- Retail Packaging:Printed carrier bags and merchandise overwrap serve hypermarket and mall distribution, facing paper substitution pressure from European retail sourcing criteria.
Food packaging absorbs the greatest extrusion tonnage. Medical packaging is expanding most quickly as domestic pharmaceutical manufacturing deepens backward integration into primary packaging.
End User:
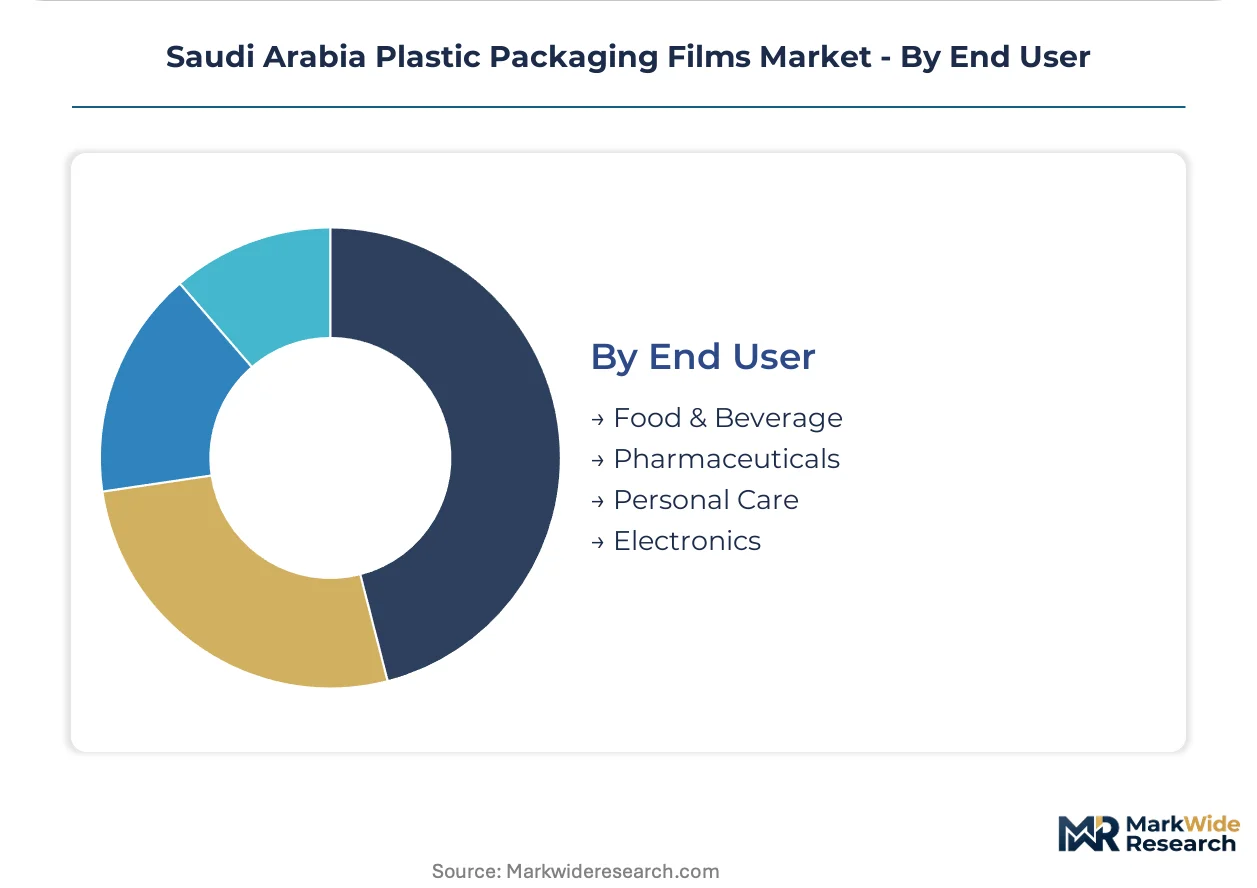
Procurement scale separates national dairy and pharmaceutical leaders from fragmented personal care and electronics assemblers.
- Food & Beverage:Almarai, Nadec, and Al Safi Danone specify multilayer barrier films with dedicated technical service agreements, consolidating supplier relationships around three Riyadh-based converters with inline laboratory capabilities.
- Pharmaceuticals:SPIMACO and Jamjoom Pharma drive demand for cold-form aluminum-PVC laminates and high-barrier blister foils, with SFDA's updated medical device regulations extending validation timelines for imported film structures.
- Personal Care:Shampoo sachets and cosmetic pouches consume printed flexible films through fragmented brand-owner networks.
- Electronics:Antistatic and moisture-barrier formats serve semiconductor and component packaging for re-export manufacturing.
Food and beverage accounts for the dominant share of committed extrusion capacity. Pharmaceuticals is gaining share fastest as localization policies expand domestic drug manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified blown-film technicians concentrate in Riyadh's Second Industrial City and Jeddah's manufacturing zones, creating geographic skill premiums that shape converter location decisions across the Kingdom.
Riyadh
Almarai and Nadec dairy commissaries anchor demand for multilayer barrier films with inline printing capabilities. SFDA's centralized food-contact notification processing operates from Riyadh, shortening approval timelines for local converters. The Second Industrial City clusters blown-film extrusion capacity serving automated packaging lines at Maestro Pizza and Herfy Food Services centralized kitchens.
Jeddah
Red Sea port infrastructure pulls export-oriented pharmaceutical blister pack production toward King Abdullah Economic City. SASO quality mark enforcement at Jeddah Islamic Port filters uncertified imported film rolls before inland distribution. APICO's manufacturing complex anchors GCC export channel logistics, displacing European suppliers in Egyptian and East African dairy packaging tenders.
Eastern Province
Jubail petrochemical export terminals generate concentrated stretch film demand for palletized load stabilization during Red Sea transit. SABIC's Yanbu and Jubail crackers supply polyethylene feedstock, though maintenance turnarounds expose converters to allocation volatility. Saudi Aramco-affiliated logistics hubs specify 23-micron minimum gauges for automated wrapping lines handling bulk chemical exports.
Tabuk and Northern Borders
Al-Jawf date farm expansion creates underpenetrated demand for on-farm packing station film supply. The northwestern agricultural belt lacks localized blown-film converting capacity, forcing processors to source from Riyadh-based suppliers with 800-kilometer distribution spans. White space exists for dedicated film operations serving harvest-season packaging peaks without inter-regional freight costs.
Saudi Arabia Plastic Packaging Films Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. National champions with integrated extrusion-printing capabilities anchor long-term dairy and food service contracts through dedicated technical service teams. Mid-tier regional distributors retain GCC export channel advantages via port-adjacent manufacturing positions. Fragmented import-dependent traders face margin compression from SFDA compliance timeline compression and centralized supermarket procurement consolidation. Dominant competitive moves include backward integration into captive resin sourcing and strategic partnerships with automated packaging line OEMs for specification lock-in.
Among Riyadh-based integrated converters, Napco National exemplifies the national champion archetype through combined blown film extrusion and printing infrastructure. Takween Advanced Industries occupies a specialized position serving pharmaceutical barrier film requirements with multilayer coextrusion capabilities. APICO anchors the regional distributor tier through Jeddah manufacturing positioning that supports GCC export logistics. These three company structures represent the competitive spectrum from diversified integration through technical specialization to geographic channel control.
| Leading Market Players |
|---|
| 3P Gulf Group |
| Arabian Plastic Industrial Company Limited (APICO) |
| Napco National |
| Takween Advanced Industries |
| Rowad Global Packaging Company Ltd |
| ENPI Group |
| Falcon Pack |
| Interplast (Harwal Group of Companies) |
| Obeikan Investment Group |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between SFDA-validated barrier films and commodity polyethylene grades manifests in both pricing spreads and supply chain configurations across the Kingdom. Premium converters with inline laboratory capabilities command technical service premiums from Almarai and Nadec, while uncertified traders face margin compression from centralized supermarket procurement consolidation.
Pricing Analysis
Capacity additions in Riyadh's Second Industrial City are reshaping price floors for multilayer flexible films as automated packaging line specifications harden. Three-tier pricing structure across premium barrier, standard coextrusion, and commodity stretch grades separates converters with dedicated technical teams from import-dependent distributors. Pricing pressure stems from SABIC's ethylene allocation constraints during cracker maintenance cycles. National dairy processors exhibit lowest price sensitivity due to specification lock-in, while fragmented personal care sachet assemblers drive commodity tier competition.
Supply Chain Analysis
Regional distribution centers in Jeddah's King Abdullah Economic City anchor hub-and-spoke patterns serving GCC export channels. Domestic supply concentrates in Saudi Arabia with resin feedstock from SABIC's Yanbu and Jubail crackers, though Korean and German specialty barrier resin suppliers retain pharmaceutical-grade positions. Raw material dependencies rest on linear low-density polyethylene, EVOH barrier resins, and metallized BOPET substrates. Single-source vulnerability to SABIC maintenance turnarounds creates allocation risk. Distribution runs through converter-direct relationships with supermarket buying groups and dairy commissaries, displacing traditional distributor middle layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia plastic packaging films market represents a late-cycle quality story as downstream buyers reconfigure procurement around circularity credentials and SFDA compliance rather than unit cost alone. Modified-atmosphere packaging adoption across supermarket deli and produce sections is pulling premium barrier specifications into converter portfolios previously dominated by commodity formats.
For Market Incumbents: Deploy captive mechanical recycling streams to secure preferential access under Saudi Investment Recycling Company's projected targets. SFDA's shortened migration testing windows threaten importers with customs detention, creating defensive moats for domestic converters with pre-approved additive inventories. Backward integration into resin sourcing buffers SABIC allocation volatility. Technical service team expansion locks in long-term dairy contracts against emerging competitors.
For New Entrants and Emerging Players: Automated packaging line OEMs represent the most accessible channel partner type for specification lock-in at Maestro Pizza and Herfy Food Services commissaries. Tabuk and Northern Borders agricultural expansion around Al-Jawf date farms offers underpenetrated white space lacking localized blown-film capacity. Digital printing convergence with cast extrusion lines enables short-run flexibility for fresh juice segments previously closed to rotogravure-dominated suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier Jeddah converters face 18-24 month ERP implementation delays against SFDA batch-level serialization mandates. Long-term viability favors vertically integrated specialists with laboratory capabilities and GCC export channel control. Acquisition targets include regional distributors with port-adjacent manufacturing positions and captive resin relationships. The signal to watch is Saudi Investment Recycling Company's mechanical recycling infrastructure deployment pace as a trigger for post-consumer content mandate enforcement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | SABIC allocation constraints during cracker maintenance expose converters to single-source pricing volatility. |
| SFDA Certification Portfolio Rebuild | Shortened 90-day migration testing windows disqualify uncertified importers from dairy and pharmaceutical tenders. |
| Digital Printing System Integration | HP Indigo and Xeikon convergence with cast extrusion opens short-shelf-life segments below 500-kilogram run lengths. |
| Captive Mechanical Recycling Investment | Saudi Investment Recycling Company's 35% recycled content targets reward early movers with government procurement preference. |
| Technical Service Team Expansion | Almarai and Nadec specification requirements for inline laboratory capabilities automate away smaller regional competitors. |
Research Methodology
Multiple input streams — primary interviews with blown-film extrusion operators and SFDA regulatory consultants, secondary validation through SASO quality mark databases and SABIC resin allocation disclosures, and customs records from Jeddah Islamic Port — were reconciled through bottom-up and top-down triangulation. Plant managers at Riyadh's Second Industrial City converters, procurement leads at centralized dairy commissaries, distribution channel partners serving GCC export routes, and technical R&D directors at barrier film specialists provided operational data. Trade publications, SEC filings from listed petrochemical parents, and Saudi Food and Drug Authority notification registers supplied secondary context.
Historical capacity utilization patterns were cross-referenced against panel input from extrusion equipment OEMs and resin distributors to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include film type, material grade tier, application regulatory intensity, and end-user procurement scale. CAGRs were derived from elasticity-adjusted demand curves incorporating quick-service restaurant expansion rates and supermarket modified-atmosphere retrofit timelines. Forecast inputs included blown-film technician pipeline constraints and digital printing adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SABIC cracker maintenance scheduling, EU Green Deal extraterritorial enforcement on recyclability documentation, and paper-fiber substitution mandates from European retail sourcing criteria. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Heat Seal Coating Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market