
 Frisket Masking Film Market | 2026-2036
Frisket Masking Film Market Size, Share, and Industry Trends Forecast 2026-2036
Frisket Masking Film Market Foresight
Buyer concentration among vehicle customizers and printing studios is hardening as mid-sized shops consolidate purchasing through distributor networks and direct manufacturer agreements. 3M leverages its adhesive technology leadership to sustain premium positioning across pressure-sensitive product lines. PPG Industries anchors its masking film portfolio through backward integration into coating chemistry, while Axalta Coating Systems differentiates by specializing in automotive-grade formulations that resist solvent bleed-through during multi-stage paint processes.
Frisket masking film comprises low-tack, flexible polymer sheets—typically cellulose acetate or polyethylene with calibrated adhesive coatings between 0.5 and 2.0 mil thickness—engineered for clean-edge paint separation without substrate damage or residue transfer. The technology dimension shows pressure-sensitive adhesive systems dominating volume while water-based adhesive platforms capture expanding share among environmentally certified print shops; matte film leads product type demand in screen printing applications where light diffusion prevents edge halos, whereas specialty coated films command the strongest margin pools in precision model making and prototype finishing.
EPA regulations on volatile organic compound emissions from solvent-based adhesives are reshaping formulation priorities, while REACH compliance in Europe restricts certain phthalate plasticizers used in legacy masking films. OSHA workplace exposure standards further constrain solvent-heavy application methods in US manufacturing plants and construction sites. Stakeholders must monitor adhesive chemistry transitions and regional certification requirements to align product portfolios with tightening chemical safety mandates.
Market Dynamics
Water-based adhesive chemistry is displacing solvent-based formulations as EPA volatile organic compound limits and REACH phthalate restrictions harden compliance thresholds across automotive and graphics applications.
Growth Catalysts
- Automotive Customization Surge:Vehicle personalizers in the United States and Germany are expanding precision masking operations to support multi-stage paint processes and vinyl wrap preparation.
- REACH Chemical Compliance:European print shops are accelerating adoption of certified low-VOC masking films to meet ECHA substance restrictions and maintain Green Seal certification status.
- Water-Based Adhesive Platforms:Pressure-sensitive adhesive systems formulated without aromatic solvents are capturing share among environmentally certified model makers and prototype finishers.
Market Restraints
- Petrochemical Feedstock Volatility:Polyethylene and cellulose acetate resin costs fluctuate with crude oil derivatives, compressing margin stability for film converters.
- Specialty Coating Concentration:Calibrated adhesive coating capability clusters among a limited set of chemical processors in the United States and Germany, creating supply bottleneck risk.
- Digital Masking Substitution:Laser-cut vinyl stencils and direct-to-substrate inkjet systems are displacing manual frisket application in low-volume signage and hobbyist segments.
Strategic Opportunities
- India Industrial Graphics Expansion:Screen printing clusters in Mumbai and Chennai present underpenetrated demand for matte-film products serving textile and packaging decorators.
- OSHA Workplace Mandates:Tightening OSHA permissible exposure limits for solvent vapors in US manufacturing plants is creating certified-product preference tailwinds.
- E-Commerce Channel Development:Direct-to-studio distribution via specialized coatings marketplaces is compressing distributor markups and expanding reach to remote customizers.
Industry Challenges
- Adhesive Formulation Expertise Gap:Shortage of polymer chemists experienced in low-tack, residue-free coating design is constraining new product development cycles.
- Multi-Jurisdiction Certification Burden:Simultaneous EPA, REACH, and Green Seal compliance testing extends product launch timelines and elevates qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frisket Masking Film Market |
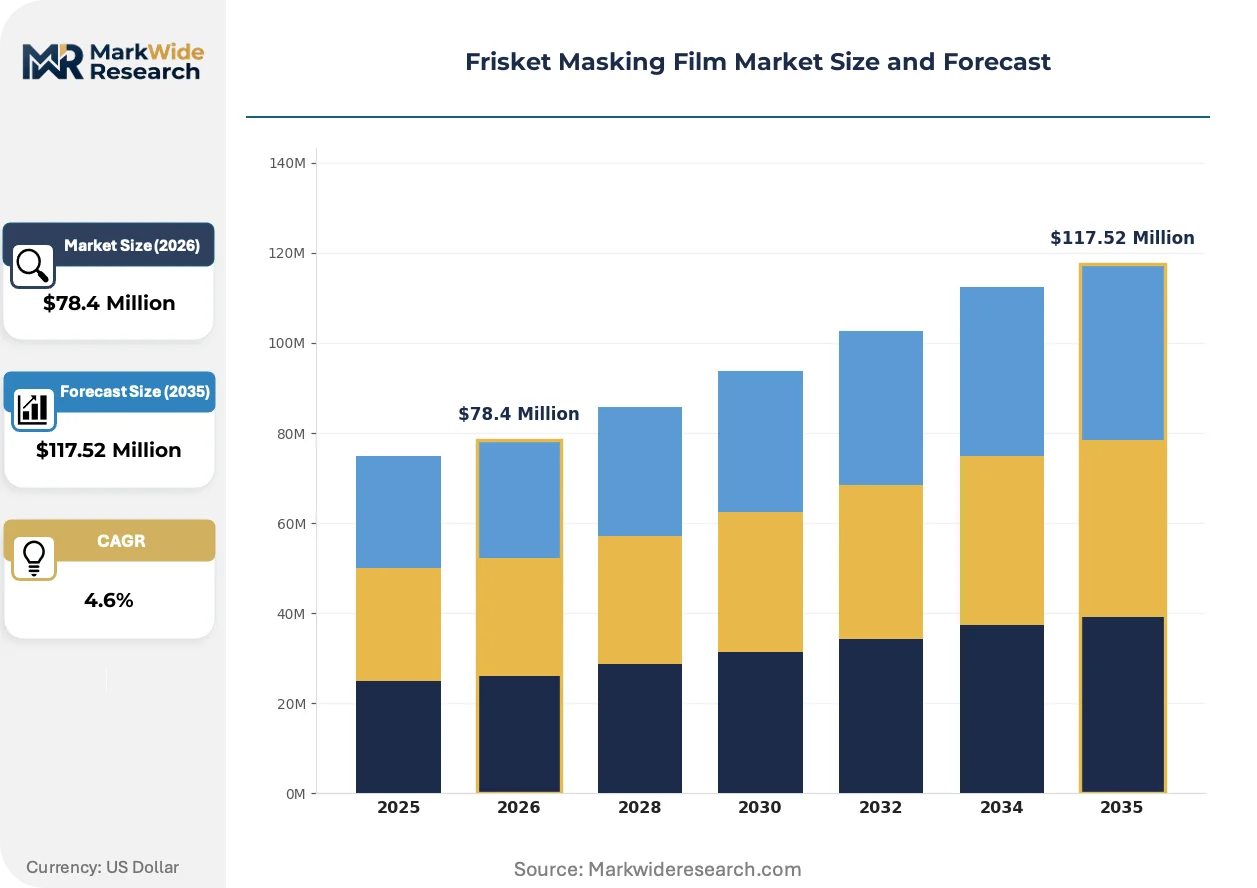
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $117.52 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matte Film, Glossy Film, Ultra-Thin Film, Specialty Coated Film, Clear Film Technology: Pressure-Sensitive Adhesive, Solvent-Based Adhesive, Water-Based Adhesive, Heat-Activated Adhesive, UV Resistant Technology Application: Screen Printing, Automotive Crafting, Architectural Painting, Industrial Coating, Model Making End User: Printing Studios, Vehicle Customizers, Construction Contractors, Manufacturing Plants, Hobbyists |
| Companies Covered | 3M, PPG Industries, Axalta Coating Systems, Sherwin-Williams, BASF, Nippon Paint, AkzoNobel, RPM International, Jotun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frisket Masking Film Market Shifts & Advancements
Formulation chemistry and application methodology are undergoing parallel transformation as environmental mandates tighten and end-users demand cleaner separation performance across diverse substrates.
Water-based pressure-sensitive adhesive technology is converging with nanostructured release coating systems to enable sub-mil thickness films that maintain clean-edge performance on curved automotive panels. Customizers in California and Texas are piloting these platforms for complex airbrush work. The structural consequence is compression of solvent-based product margins as certified shops consolidate purchasing around compliant alternatives.
EPA volatile organic compound emission standards for industrial adhesives are forcing reformulation of legacy masking film lines ahead of 2025 compliance deadlines. Coating manufacturers are investing in aqueous polymer dispersion capacity to replace aromatic solvent carriers. Automotive refinish shops in Michigan and Ohio are experiencing the steepest product transition costs as they retool spray booth ventilation and inventory systems.
Buyer concentration among mid-sized vehicle customizers is consolidating procurement through specialized distributor networks and direct manufacturer agreements. Independent print studios are ceding purchasing autonomy to regional buying cooperatives that negotiate volume terms and technical support packages. This pattern is most visible in the southeastern United States, where Atlanta and Charlotte-based customizers have formed purchasing alliances.
Frisket Masking Film Market Segmentation
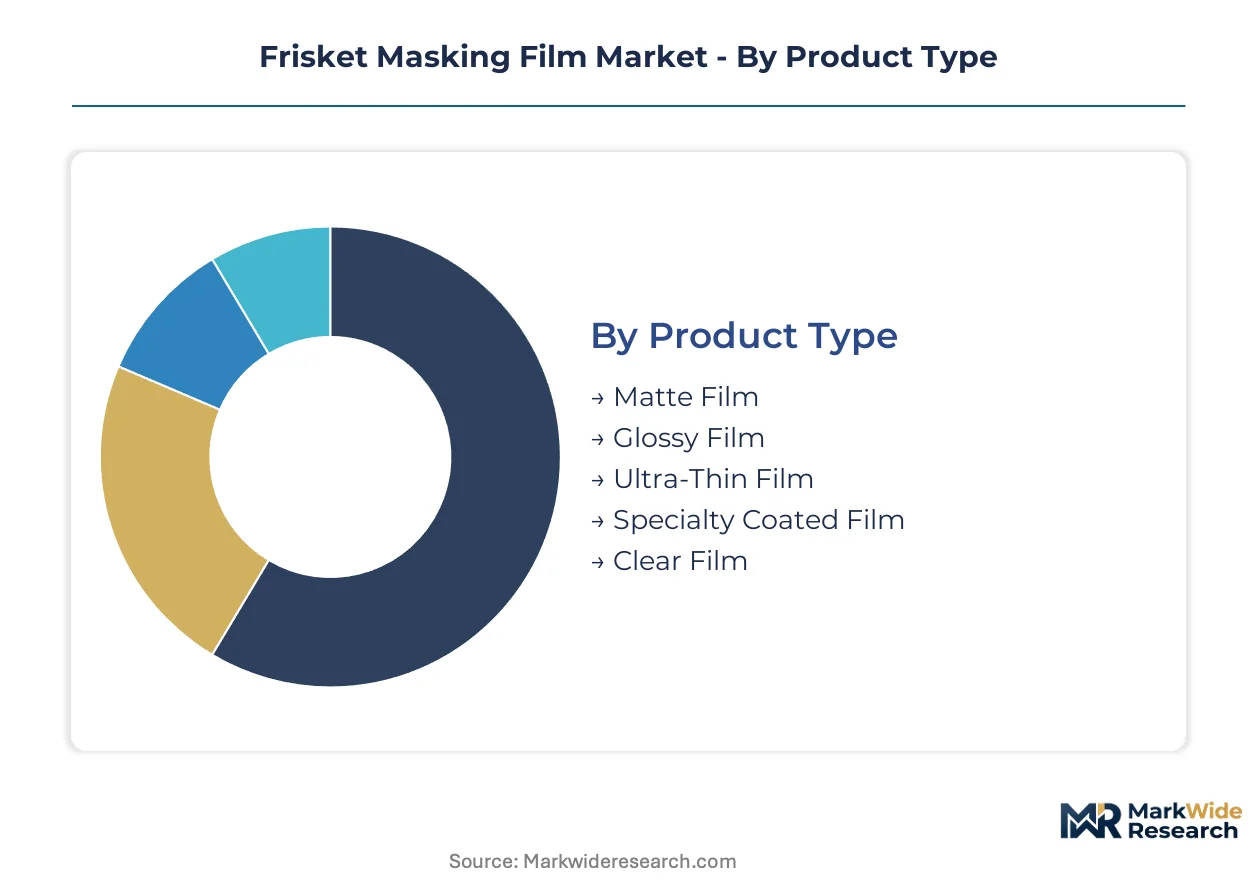
Frisket masking film segmentation reflects divergent performance requirements across precision graphics, automotive refinishing, and industrial coating workflows. Product thickness, adhesive chemistry, and surface finish properties determine suitability for curved substrates, multi-stage paint processes, and clean-edge separation demands.
Product Type:
Customization intensity spans from commodity clear films to engineered specialty coatings, with formulation complexity driving margin stratification across the five product tiers.
- Matte Film:Engineered with light-diffusing surface texture to prevent edge halos in photographic screen printing applications. Demand concentrates among textile decorators in Mumbai and Chennai screen printing clusters, where EPA-aligned shops are phasing out solvent-heavy alternatives.
- Specialty Coated Film:Calibrated sub-mil thickness constructions with nanostructured release layers for prototype finishing and precision model making. German automotive customizers in Stuttgart and Munich specify these formulations for complex airbrush work on curved panels, paying premium margins for residue-free performance.
- Glossy Film:High-clarity cellulose acetate constructions favored by architectural painters for decorative finishing where surface sheen must be preserved.
- Ultra-Thin Film:Substrate-conforming polyethylene sheets below 0.5 mil thickness for intricate vinyl wrap preparation in Texas and California vehicle shops.
- Clear Film:Standard transparency constructions serving hobbyist and educational markets with basic masking requirements.
Leading the category by volume: Matte Film. Growing fastest: Specialty Coated Film.
Technology:
Adhesive chemistry investment correlates directly with regulatory compliance burden, separating certified aqueous platforms from legacy solvent systems facing EPA and REACH phase-out timelines.
- Pressure-Sensitive Adhesive:Dominant volume platform utilizing calibrated tack levels between 0.5 and 2.0 oz/in for clean removal without substrate damage. US automotive refinish shops in Michigan and Ohio are retooling spray booth systems to accommodate water-based PSA variants ahead of compliance deadlines.
- Water-Based Adhesive:Aqueous polymer dispersion systems capturing share among Green Seal-certified print studios. European screen printers in Germany and France are consolidating procurement around REACH-compliant water-based platforms to maintain ECHA certification status.
- Solvent-Based Adhesive:Legacy aromatic solvent carriers facing margin compression as OSHA permissible exposure limits tighten in US manufacturing plants.
- Heat-Activated Adhesive:Thermal bonding systems for industrial coating applications requiring elevated temperature resistance.
- UV Resistant Technology:Stabilized formulations for outdoor architectural painting and extended exposure construction applications.
Volume leader: Pressure-Sensitive Adhesive. Steepest expansion trajectory: Water-Based Adhesive.
Application:
End-use sophistication ranges from manual hobbyist application to automated multi-stage industrial coating, with substrate type and process automation determining film specification requirements.
- Screen Printing:Precision stencil separation demanding matte-finish light diffusion for photographic reproduction quality. Indian textile decorators in Ahmedabad and Surat are expanding capacity for export-oriented garment printing.
- Automotive Crafting:Multi-stage paint masking and vinyl wrap preparation requiring conformability to compound curves. German vehicle customizers specify ultra-thin specialty coated films for complex airbrush detailing.
- Architectural Painting:Decorative masking for interior and exterior finishing where surface protection and clean edge definition are paramount.
- Industrial Coating:High-volume manufacturing plant applications with automated application systems and heat-resistant requirements.
- Model Making:Prototype finishing and precision hobby work demanding sub-mil thickness and residue-free removal characteristics.
Revenue concentration: Screen Printing. Gaining share fastest: Automotive Crafting.
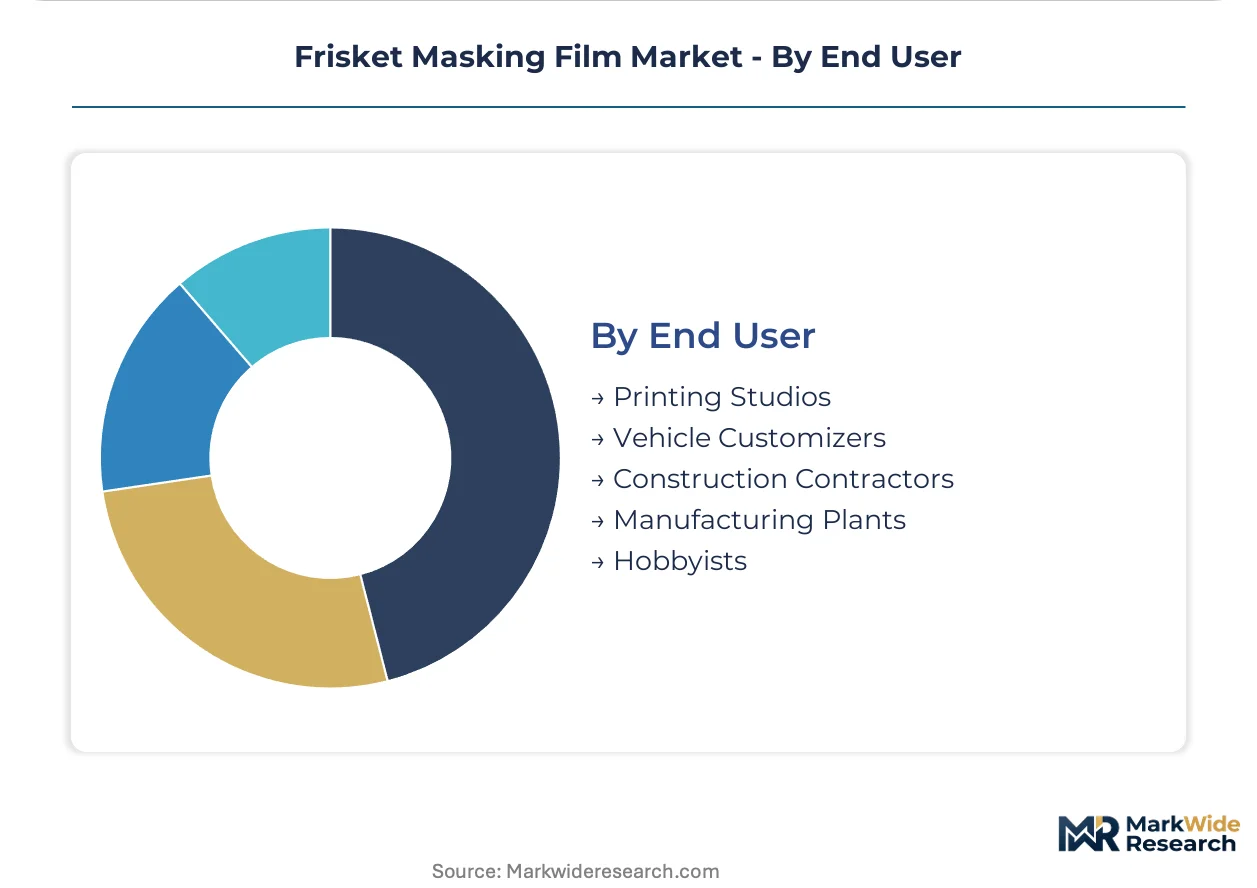
End User:
Buyer scale and procurement sophistication create distinct channel requirements, from distributor-mediated construction contractors to direct-manufacturer agreements with consolidated vehicle customizer alliances.
- Vehicle Customizers:Mid-sized automotive personalization shops consolidating purchasing through Atlanta and Charlotte-based buying cooperatives. These southeastern US alliances negotiate volume terms and technical support packages directly with adhesive coating manufacturers.
- Printing Studios:Screen printing and graphics operations ranging from independent studios to regional decorators. German and French print shops are accelerating certified low-VOC film adoption to maintain Green Seal and ECHA compliance status.
- Construction Contractors:Project-based architectural painting contractors procuring through distributor networks with seasonal demand patterns.
- Manufacturing Plants:Industrial coating operations subject to OSHA workplace exposure mandates driving certified-product preference.
- Hobbyists:Individual consumers and educational institutions purchasing through e-commerce marketplaces with compressed distributor markups.
Procurement volume leader: Vehicle Customizers. Expanding most quickly: Printing Studios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vehicle customizers in the United States and Germany drive the largest consumption volumes for precision masking films, while regulatory divergence across EPA, REACH, and emerging Asian standards is fragmenting formulation requirements by geography.
United States
Automotive refinish shops in Michigan and Ohio are retooling spray booth ventilation systems to accommodate water-based adhesive variants ahead of EPA volatile organic compound compliance deadlines. OSHA permissible exposure limits for solvent vapors are tightening certified-product preferences in manufacturing plants across the industrial Midwest. Atlanta and Charlotte-based vehicle customizer alliances now negotiate volume terms directly with adhesive coating manufacturers, bypassing traditional distributor networks.
Germany
Stuttgart and Munich automotive customizers specify ultra-thin specialty coated films for complex airbrush detailing on curved panels, paying premium margins for residue-free performance. ECHA substance restrictions under REACH are accelerating certified low-VOC film adoption among print shops seeking to maintain Green Seal certification status. German chemical processors dominate calibrated adhesive coating capability clusters, creating supply concentration risk for European converters.
India
Screen printing clusters in Mumbai, Chennai, Ahmedabad, and Surat present underpenetrated demand for matte-film products serving textile and packaging decorators. The country's national environmental regulator is aligning industrial chemical standards with international VOC limits, pressuring legacy solvent-based operations. Indian textile decorators are expanding capacity for export-oriented garment printing, driving precision stencil separation requirements.
China
Industrial graphics expansion in the Yangtze River Delta and Pearl River Delta regions is creating demand for conformable masking films in automotive refinishing applications. The Ministry of Ecology and Environment is enforcing stricter emissions standards on adhesive formulation plants in coastal manufacturing zones. Chinese film converters are investing in aqueous polymer dispersion capacity to replace aromatic solvent carriers ahead of dual carbon policy timelines.
Japan
Precision model making and prototype finishing workshops in the Kanto and Kansai regions require sub-mil thickness films with nanostructured release layers. METI industrial standards are pushing coating manufacturers toward low-residue adhesive platforms for electronics and automotive supplier networks. Tokyo-area specialty film distributors are consolidating procurement for hobbyist and professional segments through direct manufacturer agreements.
Frisket Masking Film Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue water-based formulation certification and e-commerce channel development. The vendor base stratifies across adhesive technology leadership, coating chemistry integration, and automotive-grade specialization. Three archetypes dominate: diversified materials conglomerates with captive adhesive R&D, coating specialists with backward integration into polymer chemistry, and regional converters serving distributor-mediated construction and hobbyist channels. Competitive moves center on aqueous formulation capacity expansion and direct-to-studio distribution partnerships that compress intermediary markups.
Among diversified materials conglomerates, 3M and BASF occupy positions exemplifying adhesive technology leadership and polymer chemistry integration respectively. PPG Industries anchors the coating specialist tier through in-house production of resin systems. These three companies represent the dominant competitive archetypes: technology-driven premium positioning, upstream control over raw material supply, and specialized automotive-grade formulation expertise.
| Leading Market Players |
|---|
| 3M |
| PPG Industries |
| Axalta Coating Systems |
| Sherwin-Williams |
| BASF |
| Nippon Paint |
| AkzoNobel |
| RPM International |
| Jotun |
| Others |
Supply & Pricing Matrix
Polyethylene and cellulose acetate resin costs, tethered to crude oil derivative indices, cascade through three pricing tiers as calibrated adhesive coating capability concentrates among United States and German chemical processors. Vehicle customizer alliances in Atlanta and Charlotte negotiate volume terms that compress distributor markups, while EPA compliance investments elevate water-based formulation premiums.
Pricing Analysis
Volume concentrates in matte and clear film commodity tiers where margin compression runs deepest, while specialty coated films command premium-mid-economy pricing differentiation based on nanostructured release layer performance. Price differentiation hinges on REACH and Green Seal certification status plus volume scale procurement. Pricing pressure stems from petrochemical feedstock volatility squeezing converter margins. Hobbyists and educational buyers exhibit highest price sensitivity; German automotive customizers show least.
Supply Chain Analysis
Reverse-logistics flows for adhesive coating calibration equipment and expired solvent-based inventory create secondary market activity in Michigan and Ohio refinish corridors. Raw material supply clusters in the United States, Germany, and China, drawing from polyethylene resin, cellulose acetate, and aqueous polymer dispersion inputs. Single-source vulnerability concentrates in calibrated coating capability among limited chemical processors. Distribution runs through specialized coatings marketplaces and regional buying cooperatives serving vehicle customizers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adhesive formulation expertise scarcity props pricing power across compliant product tiers, as polymer chemists experienced in low-tack, residue-free coating design remain concentrated among legacy coating manufacturers.
For Market Incumbents: Hedge against digital masking substitution by deepening backward integration into aqueous polymer dispersion capacity and securing direct-to-studio distribution partnerships. Laser-cut vinyl stencils threaten low-volume signage segments; defend through certification investment and technical support bundling with Atlanta and Charlotte buying cooperatives. For New Entrants and Emerging Players: Specialized coatings marketplaces offer channel access with compressed intermediary markups, enabling penetration of underexploited Indian screen printing clusters in Mumbai and Chennai. White-space targets include matte-film textile decorators and REACH-compliant print shops seeking Green Seal alternatives; pursue e-commerce channel development with direct manufacturer agreements. For Investors and Strategic Acquirers: OSHA workplace exposure mandate tightening is the leading indicator that certified-product preference tailwinds will strengthen water-based adhesive platform valuations. Long-term viability centers on aqueous formulation capacity and nanostructured release layer expertise; monitor EPA volatile organic compound enforcement actions as inflection signal for solvent-based asset obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Formulation Capacity Expansion | EPA compliance deadlines in Michigan and Ohio force coating chemistry transitions ahead of enforcement. |
| Direct-to-Studio Distribution Partnership | Atlanta and Charlotte customizer alliances bypass distributor markups through manufacturer volume agreements. |
| REACH Certification Investment | ECHA substance restrictions elevate Green Seal status among German and French print shop procurement criteria. |
| Specialty Coating R&D Partnership | Nanostructured release layer development targets Stuttgart and Munich complex airbrush detailing applications. |
| Indian Market Channel Development | Mumbai and Chennai screen printing clusters present underpenetrated matte-film demand for textile decorators. |
Research Methodology
Multi-period observation of EPA enforcement patterns, REACH certification adoption curves, and vehicle customizer procurement consolidation anchored the trend analysis, supplemented by interviews with adhesive coating plant managers, automotive refinish shop owners, screen printing studio operators, and specialized coatings marketplace platform managers. Secondary validation drew from EPA regulatory filings, ECHA substance restriction updates, customs trade data for polyethylene and cellulose acetate imports, and SEC disclosures from diversified materials conglomerates. Bottom-up demand modeling triangulated against top-down supply capacity assessments across the analysis window.
Segment-weighting across product type, adhesive technology, application workflow, and end-user procurement scale informed volume and value projections throughout the forecast period. CAGRs derived from calibrated adhesive coating capacity expansion timelines, automotive customization intensity indices, and regulatory compliance cost pass-through elasticity. Industry-specific inputs included spray booth retooling expenditure patterns and Green Seal certification velocity among European print shops.
Caveats apply where EPA enforcement acceleration, REACH substance list expansion, or digital masking technology cost reduction could materially shift the outlook. Forecasts reflect assumptions regarding aqueous polymer dispersion capacity buildout and customizer alliance procurement consolidation. Practitioners should monitor OSHA permissible exposure limit revisions and Indian national environmental regulator alignment with international VOC standards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Insulation Film Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Hydrocolloid Coating Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
Barrier Foil Market
Packaging Barrier Films
Global Micro-Perforated Films Market