
 Intermediate Bulk Container Liner Market | 2026-2036
Intermediate Bulk Container Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Intermediate Bulk Container Liner Market Analytics
Buyer concentration among multinational chemical processors is decoupling from traditional regional distributor networks. Greif Inc. leverages its integrated container-liner manufacturing footprint to serve bulk chemical clients directly. Scholle IPN anchors its position through advanced aseptic filling technology for food-grade applications. Sealed Air competes via proprietary barrier film formulations that extend product shelf stability during ocean transit.
An intermediate bulk container liner is a flexible polymer insert designed to fit inside rigid IBC totes or bulk boxes, typically manufactured from multi-layer polyethylene or polypropylene films through extrusion and heat-sealing processes, creating a contamination barrier between the container wall and the transported substance. Polyethylene liners dominate current volume due to cost-efficient extrusion and broad chemical compatibility, while polypropylene variants capture premium margin pools in high-temperature pharmaceutical applications. Custom liners represent the fastest-growing packaging type as specialty chemical and pharmaceutical shippers demand dimensional adaptations for unique container geometries and filling protocols.
FDA food-contact regulations and EU REACH chemical safety standards govern polymer composition, migration limits, and recyclability documentation for liners sold into regulated supply chains. These frameworks compel manufacturers to maintain batch-level traceability and third-party certification, effectively raising barriers for uncertified regional suppliers. Stakeholders must monitor evolving extended producer responsibility mandates in Europe and North America that will soon require documented liner recovery or recycling pathways.
Market Dynamics
Buyer consolidation among multinational chemical processors is restructuring distribution economics, forcing liner manufacturers to bypass traditional regional distributors and establish direct fulfillment relationships with bulk chemical shippers.
Growth Catalysts
- ECHA REACH chemical safety standards:Stricter migration limit testing for polymer-based liners is compelling shippers to upgrade from commodity-grade to certified barrier films, accelerating replacement cycles in European chemical logistics.
- Pharmaceutical temperature excursions:Cold-chain biologics shipping is expanding demand for multi-layer insulation liners that maintain thermal stability across extended ocean transit routes.
- Germany's Rhine industrial corridor:Concentrated bulk chemical production along this waterway cluster is generating sustained liner procurement volumes for hazardous material containment applications.
Market Restraints
- Polyethylene resin volatility:Feedstock cost swings for LLDPE and HDPE grades compress manufacturer margins and complicate long-term contract pricing with chemical processors.
- Single-source extrusion equipment:Dependence on German and Italian machinery suppliers for multi-layer co-extrusion lines creates 18-24 month capacity expansion lead times.
- Film thickness limitations:Current heat-sealing technology cannot reliably produce sub-80-micron barrier films for oxygen-sensitive pharmaceutical applications without compromising seam integrity.
Strategic Opportunities
- India specialty chemical exports:Rapid capacity additions at Gujarat and Maharashtra chemical parks are creating first-mover advantages for liner suppliers establishing local technical service presence.
- EU Green Deal extended producer responsibility:Upcoming mandates for documented liner recovery pathways will reward manufacturers with established mechanical recycling partnerships.
- RFID-barrier film convergence:Integration of track-and-trace sensors with polymer liners enables real-time contamination monitoring for high-value pharmaceutical shipments.
Industry Challenges
- Multi-layer film recycling complexity:Separation of incompatible polymer layers in post-use liners requires specialized infrastructure that remains underdeveloped across most European markets.
- FDA food-contact notification timelines:120-day pre-market review periods for new polymer formulations delay product launches and tie up R&D capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intermediate Bulk Container Liner Market |
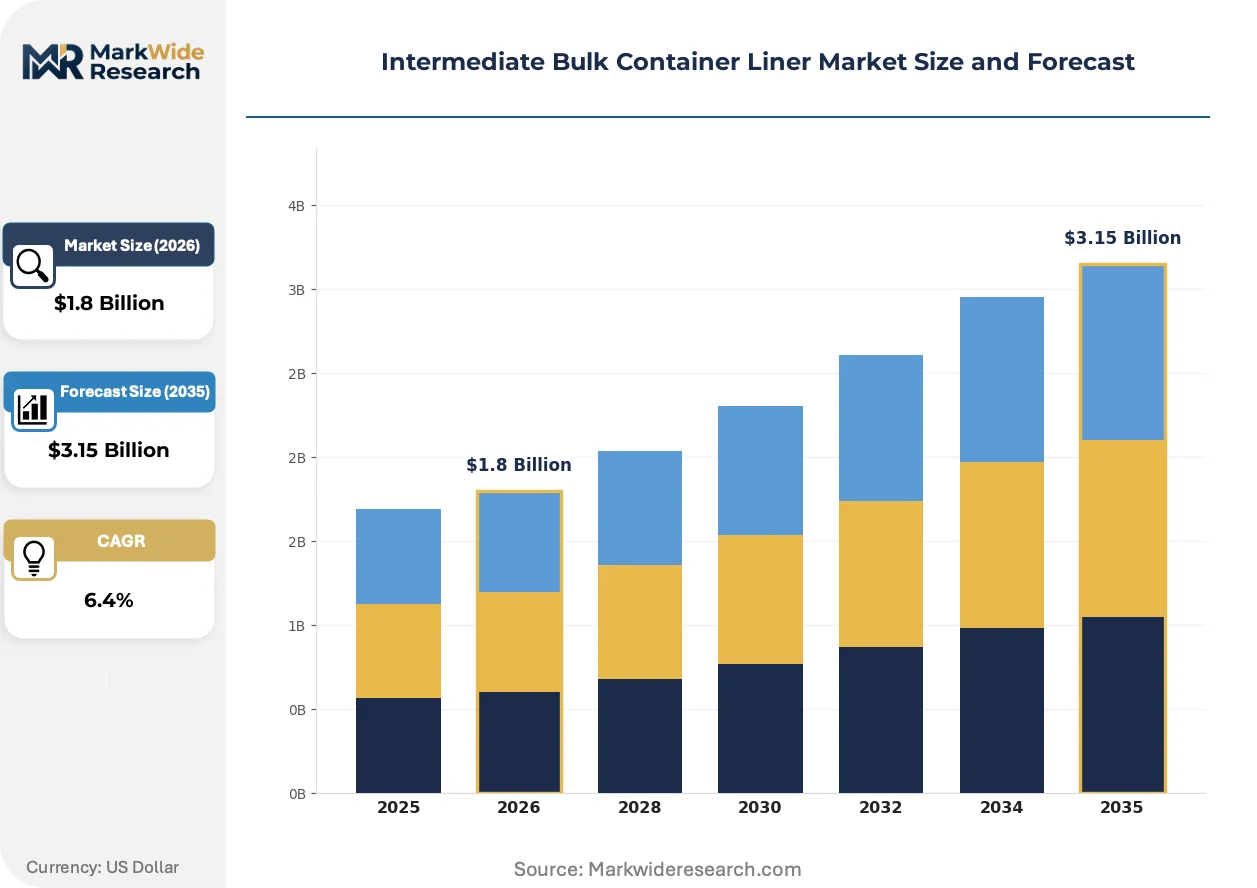
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, PVC, Other End Use Industry: Chemical, Food & Beverage, Pharmaceutical, Agriculture Packaging Type: Standard Liners, Custom Liners, Bag Liners, Other Geographical Application: Bulk Transport, Storage Solutions, Export Packaging, Others |
| Companies Covered | Amcor plc, CDF Corporation, Berry Global Inc., Bulk Lift International LLC, Arena Products Inc., Greif Inc., Sealed Air, Scholle IPN, Snyder Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intermediate Bulk Container Liner Market Evolving Landscape
Active barrier technologies and smart packaging integration are redefining performance benchmarks, while regulatory pressure on circularity is forcing material science innovation ahead of traditional cost-driven competition.
Ethylene vinyl alcohol copolymer is expanding into oxygen-sensitive pharmaceutical and nutraceutical applications where shelf-life extension justifies material cost premiums. Biologics manufacturers in Switzerland and Germany are adopting EVOH-lined IBC systems for temperature-controlled distribution of monoclonal antibodies. This barrier technology is expanding into standard chemical logistics as shippers seek to reduce oxidative degradation of specialty intermediates during multi-modal transport.
EU REACH SVHC candidate list expansion is tightening disclosure requirements for polymer additives used in food-contact and pharmaceutical liners. Manufacturers must now maintain comprehensive substance dossiers tracing plasticizers, stabilizers, and slip agents through complex supply chains. Small and mid-sized European compounders face disproportionate compliance burdens relative to integrated resin producers with captive additive formulation capabilities.
Direct procurement from liner manufacturers is displacing traditional packaging distributor intermediaries among large chemical processors seeking technical customization and volume pricing leverage. BASF, Dow, and Covestro operations in Germany's Ludwigshafen and Dormagen clusters now negotiate annual frame contracts with specified performance metrics rather than spot purchasing through regional wholesalers. This channel compression concentrates pricing power with manufacturers capable of delivering application engineering support alongside commodity film supply.
Intermediate Bulk Container Liner Market Segmentation
Material specification, end-use contamination tolerance, and dimensional adaptability determine liner procurement decisions across chemical, food, and pharmaceutical supply chains. Segmentation reveals where premium barrier technologies command margin versus commodity extrusion volumes.
Material Type:
Polymer selection hinges on chemical compatibility matrices, temperature thresholds, and regulatory migration limits for the contained substance.
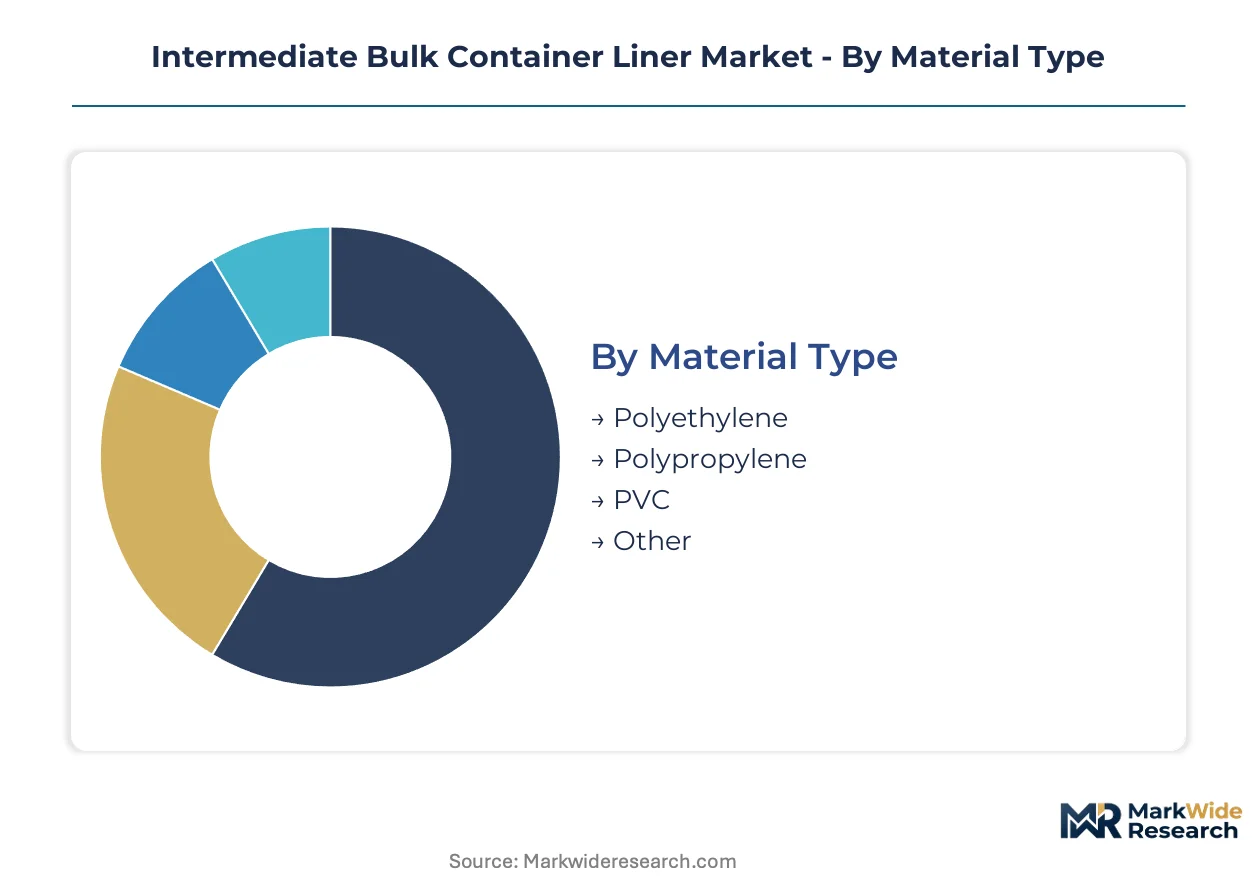
- Polyethylene:Multi-layer LLDPE and HDPE films dominate current production through cost-efficient co-extrusion and broad chemical resistance. German bulk chemical shippers along the Rhine corridor specify polyethylene liners for standard hazardous material containment where oxygen barrier performance remains secondary.
- Polypropylene:Higher melting point and dimensional stability capture premium applications in pharmaceutical autoclave sterilization protocols. Swiss biologics manufacturers specify biaxially oriented polypropylene for temperature-excursion-sensitive monoclonal antibody distribution.
- PVC:Plasticized formulations serve niche chemical resistance applications where specific solvent compatibility requirements exclude polyolefin alternatives.
- Other:Ethylene vinyl alcohol copolymer and nylon barrier layers address oxygen-sensitive nutraceutical and active pharmaceutical ingredient transport.
Polyethylene leads on scale; polypropylene leads on momentum.
End Use Industry:
Regulatory stringency and contamination consequence severity stratify liner performance requirements and certification burdens.
- Chemical:ECHA REACH compliance mandates batch-level traceability for polymer additives and migration testing documentation. Hazardous material classification drives multi-layer barrier specifications for flammable and corrosive substance containment.
- Food & Beverage:FDA food-contact notification and EU food-grade certification require substantiated purity claims for polymer formulations. Aseptic filling protocols in dairy and beverage applications demand validated sterile barrier performance.
- Pharmaceutical:Cold-chain biologics distribution is expanding multi-layer insulation liner adoption for temperature stability across extended ocean transit routes.
- Agriculture:Fertilizer and crop protection chemical logistics favor cost-optimized polyethylene formulations with basic chemical resistance.
Chemical applications anchor procurement volume; pharmaceutical applications command the steepest expansion trajectory.
Packaging Type:
Dimensional standardization versus customization defines manufacturing economics and customer relationship intensity.
- Standard Liners:Off-the-shelf dimensions serve high-volume chemical and agricultural applications with predictable container geometries and rapid replenishment cycles.
- Custom Liners:Application-specific dimensional adaptations and filling protocol integration capture specialty chemical and pharmaceutical shippers seeking container geometry optimization and reduced residual product loss.
- Bag Liners:Flexible intermediate bulk container inserts serve powder and granular material handling where rigid IBC compatibility is not required.
- Other:Collapsible liner systems and disposable totes address niche export packaging and single-use contamination control requirements.
Standard liners dominate shipment counts; custom liners are gaining share fastest.
Geographical Application:
Transport mode and duration dictate barrier performance specifications and durability requirements.
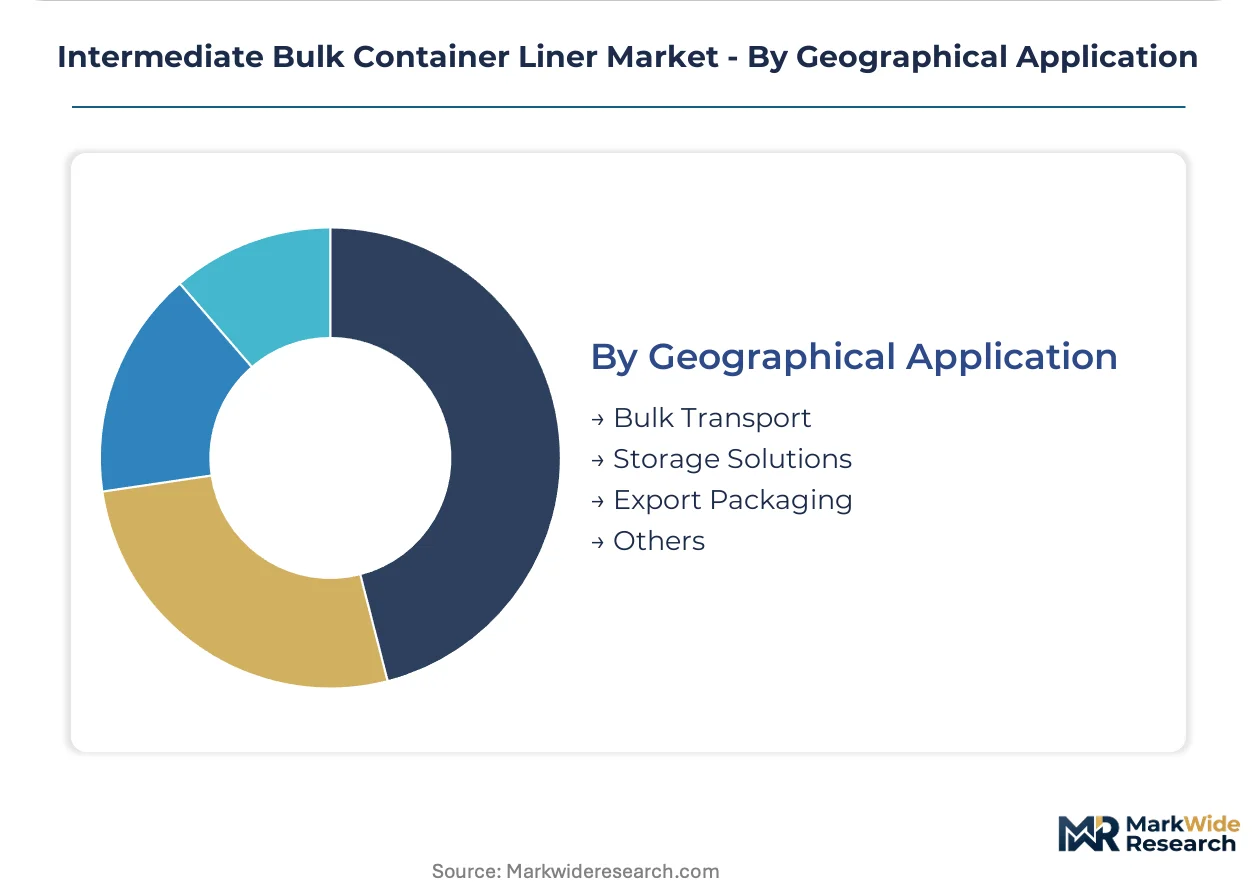
- Bulk Transport:Multi-modal chemical logistics through Germany's industrial corridor generate sustained demand for puncture-resistant multi-layer constructions.
- Storage Solutions:Extended warehouse residence times require UV-stabilized formulations and anti-static properties for sensitive pharmaceutical intermediates.
- Export Packaging:Ocean transit durations exceeding thirty days drive adoption of enhanced moisture and oxygen barrier specifications for oxidation-prone specialty chemicals.
- Others:Railcar and flexitank liner applications serve bulk liquid transport modes outside standard IBC formats.
Bulk transport anchors installed base; export packaging shows the strongest growth impulse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine corridor commands chemical logistics volume that outstrips individual markets in Asia-Pacific, while the United States and China pursue divergent regulatory paths on polymer migration standards. India and Switzerland anchor pharmaceutical-grade demand through distinct supply chain configurations.
Germany
BASF, Covestro, and Dow operations along the Ludwigshafen-Dormagen corridor generate sustained procurement of multi-layer barrier liners for hazardous material containment. ECHA REACH SVHC disclosure mandates compel shippers to maintain batch-level additive traceability through complex supply chains. The Rhine industrial cluster concentrates Europe's highest liner consumption intensity for bulk chemical logistics.
United States
FDA food-contact notification requirements for new polymer formulations create 120-day pre-market review delays that tie up R&D capital. EPA hazardous waste regulations intersect with DOT shipping standards to mandate certified barrier films for flammable substance transport. Texas Gulf Coast petrochemical complexes and Louisiana chemical corridors drive standard polyethylene liner volume for agricultural and industrial chemical distribution.
China
GB standards for food-contact materials and MIIT industrial packaging regulations govern domestic liner specifications with increasing stringency. Yangtze River Delta chemical parks and Shandong Peninsula specialty chemical zones are expanding capacity faster than local liner suppliers can qualify barrier film formulations. NMPA pharmaceutical packaging standards are tightening migration limits for biologics distribution.
India
Gujarat and Maharashtra chemical parks are adding specialty chemical capacity that outpaces domestic liner technical service presence. BIS certification requirements for food-contact polymers create compliance bottlenecks for imported barrier films. Mumbai-Pune industrial corridor and Vadodara-Ankleshwar chemical zones are generating first-mover opportunities for suppliers establishing local application engineering support.
Switzerland
Swissmedic pharmaceutical packaging regulations and cold-chain biologics distribution requirements drive premium polypropylene and EVOH barrier adoption. Basel biotech cluster and Zurich pharmaceutical corridor specify temperature-excursion-resistant liners for monoclonal antibody ocean transit. The country's precision manufacturing culture extends to validated sterile barrier performance for aseptic filling protocols.
Intermediate Bulk Container Liner Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Integrated packaging conglomerates leverage resin compounding and extrusion capabilities to serve bulk chemical clients through direct fulfillment relationships. Pure-play liner manufacturers anchor positions through application engineering and dimensional customization for pharmaceutical shippers. The dominant competitive moves are backward integration into polymer compounding and geographic expansion through technical service presence in high-growth chemical corridors.
Among US-based packaging conglomerates, Berry Global Inc. and Sealed Air occupy positions exemplifying integrated barrier film and protective packaging capabilities. Greif Inc. represents the industrial packaging specialist archetype with captive container-liner manufacturing coordination. Scholle IPN anchors the aseptic filling technology tier for food-grade and pharmaceutical applications.
| Leading Market Players |
|---|
| Amcor plc |
| CDF Corporation |
| Berry Global Inc. |
| Bulk Lift International LLC |
| Arena Products Inc. |
| Greif Inc. |
| Sealed Air |
| Scholle IPN |
| Snyder Industries Inc. |
| Others |
Value Network & Pricing Analysis
Multi-layer co-extrusion technology adoption in Germany and Italy is simultaneously compressing per-unit production costs and concentrating barrier film supply among equipment-capable manufacturers, reshaping how chemical processors negotiate annual frame contracts.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard polyethylene liners while European ECHA REACH certification premiums sustain margin pools for pharmaceutical-grade films. Three-tier pricing structure across certified barrier, standard industrial, and economy agricultural tiers reflects migration limit compliance burdens and volume scale. Cost compression in the economy tier is intensifying because resin volatility and distributor disintermediation squeeze legacy suppliers. Agricultural shippers exhibit the highest price sensitivity; Swiss biologics manufacturers accept steep premiums for validated sterile barrier performance.
Supply Chain Analysis
Dual-sourcing mandates from BASF, Dow, and Covestro operations compel liner manufacturers to maintain qualified secondary extrusion partnerships despite geographic concentration. Supply concentrates in Germany, Italy, and China, with German machinery builders anchoring multi-layer co-extrusion equipment supply. Raw material dependencies rest on LLDPE and HDPE resin grades, EVOH barrier layers, and polypropylene homopolymer. Single-source vulnerability in German-Italian extrusion equipment creates 18-24 month capacity expansion bottlenecks. Distribution runs through direct fulfillment relationships with multinational chemical processors, bypassing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as pharmaceutical cold-chain biologics demand shifts specifications toward temperature-excursion-resistant multi-layer insulation liners.
For Market Incumbents: Extend barrier film formulation capabilities into EVOH and polypropylene insulation layers to capture pharmaceutical premium pools. Deepen backward integration into polymer compounding to defend margin position against resin volatility. Qualify secondary extrusion partnerships in India to offset European equipment lead time risks. For New Entrants and Emerging Players: EU Green Deal extended producer responsibility mandates in Europe open a window for mechanical recycling partnerships that incumbent integrated producers lack. Target Gujarat and Maharashtra chemical parks with local technical service presence to exploit first-mover gaps in India's specialty chemical export expansion. Lead with application engineering support rather than commodity film pricing to differentiate from established distributors. For Investors and Strategic Acquirers: Roll-up economics work for regional pure-play liner manufacturers with established pharmaceutical certification and captive extrusion capacity because buyer consolidation among chemical processors concentrates procurement with technically capable suppliers. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Watch FDA food-contact notification backlogs as a signal for R&D capital efficiency inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin formulation reduces ECHA REACH additive traceability compliance costs for pharmaceutical clients. |
| Geographic Expansion through Technical Service Presence | Local application engineering in Gujarat chemical parks captures specialty chemical export growth ahead of incumbent distributors. |
| Mechanical Recycling Partnership Development | Documented liner recovery pathways secure EU Green Deal extended producer responsibility compliance advantages. |
| RFID-Barrier Film Convergence Investment | Real-time contamination monitoring integration commands premium positioning for high-value monoclonal antibody shipments. |
| Long-term Supply Agreement Structuring | Annual frame contracts with BASF, Covestro, and Dow operations reduce spot pricing exposure and secure volume commitments. |
Research Methodology
Bottom-up chemical and pharmaceutical end-use modeling reconciled against top-down extrusion capacity and resin consumption tracking forms the analytical core of this study. Primary interviews with plant managers at Rhine corridor chemical processors, procurement leads at Swiss biologics manufacturers, distribution channel partners in India, and technical R&D directors at barrier film compounders were cross-validated against secondary sources including ECHA REACH substance dossiers, FDA food-contact notification databases, German chemical industry association reports, and customs trade data for polyethylene and polypropylene film shipments.
Input-output matrices map resin grade consumption through extrusion equipment utilization to end-use segment demand across the projection horizon. Segmentation dimensions modeled include material type, end-use industry, packaging format, and regional production hub. CAGRs were derived from elasticity-adjusted volume projections tied to chemical capacity expansion announcements and pharmaceutical cold-chain infrastructure investments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EVOH supply disruption or accelerated EU extended producer responsibility mandate implementation. Deviation in FDA food-contact notification review timelines would shift the outlook materially for new polymer formulation launches.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Oblong Jar Market
Containers
USA and Canada Packer Bottle Market
Containers
Foam Containers Market
Containers
Club Store Packaging Tray Market
Containers
Modular Container Market
Containers
Canning Jars Market
Containers
Pocket Containers Market
Containers
Stack and Nest Containers Market
Containers
Americas Container Technology Market
Containers
Wooden Crates Market
Containers
Car Lube Container Market
Containers
Belgium Container Glass Market
Containers
Injection Molding Containers Market
Containers
APAC Container Technology Market
Containers
Containerboard Market
Containers
Essential Oil Containers Market