
 Specialty Plastic Films Market | 2026-2036
Specialty Plastic Films Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Plastic Films Market Intelligence
The proliferation of multi-layer co-extrusion technology is fragmenting the traditional value chain by enabling customized barrier and performance properties in a single film. Toray Industries Inc. leverages its material science expertise in high-performance polyester films for electronics. Berry Global Inc. competes on manufacturing scale and broad-portfolio offerings for the packaging sector. Covestro AG differentiates through its focus on advanced polyurethane and polycarbonate-based films for automotive and medical applications.
Specialty plastic films are engineered polymers, often with complex multi-layer structures, designed for specific performance characteristics beyond commodity applications. These films provide tailored properties such as high tensile strength, specific gas permeability, UV resistance, or thermal stability. While polyester films command a premium in high-end electronics and industrial applications, polyethylene variants lead in volume for flexible packaging. The construction application segment shows consistent demand for durable, weather-resistant films.
Food-contact safety standards set by the US FDA and the European Food Safety Authority (EFSA) govern material selection for packaging films. In parallel, China's GB standards and the EU's REACH regulations impose strict chemical composition and substance registration requirements on manufacturers. Navigating the divergent global regulations on recyclability and plastic waste will be a defining strategic challenge for film producers.
Market Dynamics
The specialty plastic films market is shaped by a fundamental tension between the demand for higher-performance, complex multi-layer structures in sectors like healthcare and electronics, and intensifying regulatory pressure for material simplification to meet circular economy objectives.
Growth Catalysts
- Healthcare Sector Demand:The need for advanced sterile packaging for medical devices and pharmaceuticals, which require high-barrier and puncture-resistant films, stimulates market expansion.
- Co-extrusion Technology:The proliferation of multi-layer co-extrusion technology enables the production of films with customized barrier, sealant, and mechanical properties in a single, efficient process.
- Indian Manufacturing Expansion:Government support and investment in India are expanding domestic capacity for high-performance films, aiming to serve both a large internal market and global export demand.
Market Restraints
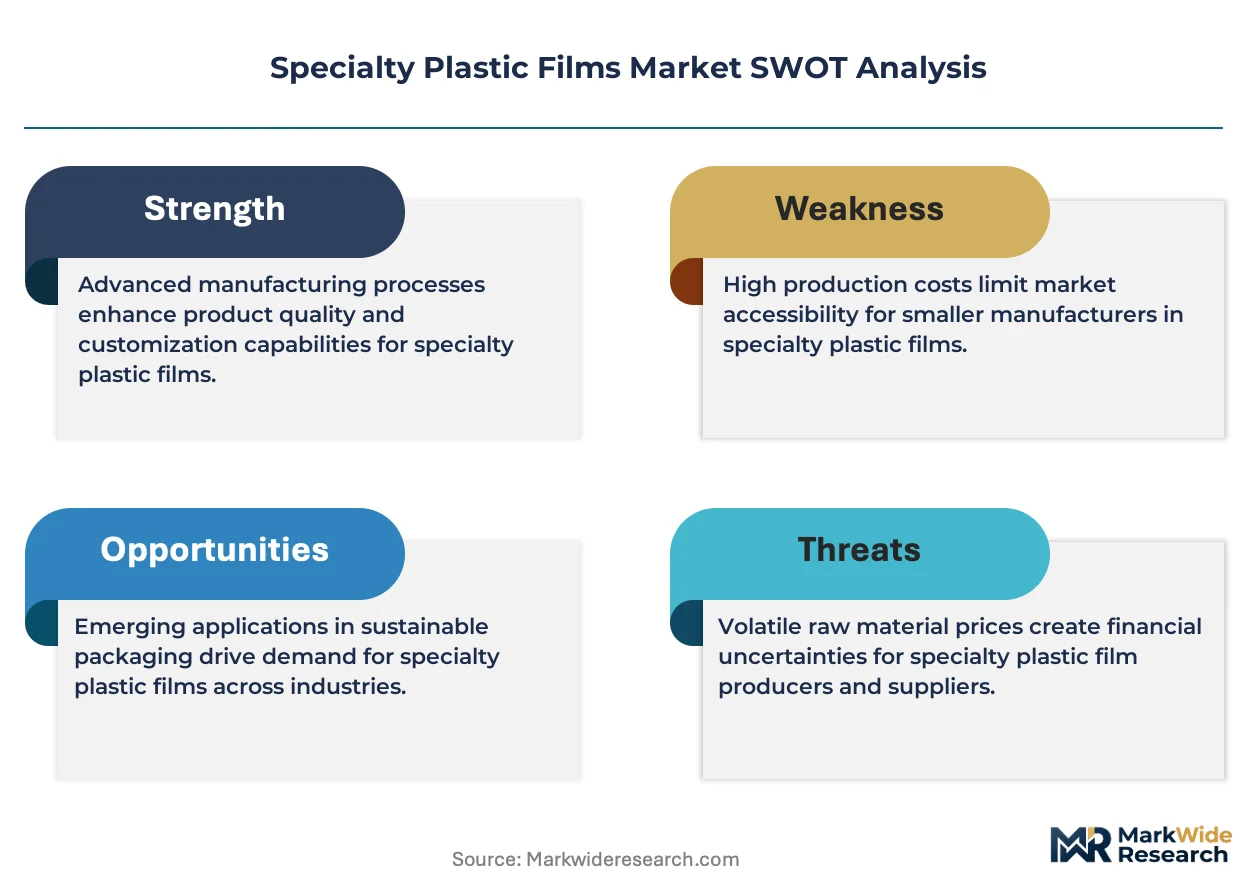
- Feedstock Price Volatility:The market's cost structure is directly exposed to fluctuations in the price of petrochemical feedstocks like ethylene and propylene, which can compress manufacturer margins.
- Regulatory Fragmentation:Divergent global regulations on recyclability, such as the stringent mandates in the EU versus different standards in North America, create complexity in product design for global producers.
- Substitution from Bio-Plastics:In less demanding packaging applications, bio-based and compostable polymers are presenting a viable substitution threat, appealing to sustainability-focused consumer brands.
Strategic Opportunities
- Mono-Material Film Development:Creating high-barrier, single-polymer films (e.g., all-polyethylene) that are fully recyclable presents a significant opportunity to meet sustainability mandates without sacrificing performance.
- Films for Flexible Electronics:The emergence of foldable displays, flexible sensors, and wearable electronics creates a new, high-value application segment for optically clear and durable polyester films.
- Expansion in Southeast Asia:Rapid growth in the food processing and consumer packaged goods sectors across Southeast Asian nations provides a key geographic growth vector for packaging film suppliers.
Industry Challenges
- Chemical Compliance Burden:Film manufacturers must navigate the complex and costly substance registration processes of multiple regulatory frameworks, such as the EU's REACH and China's GB standards.
- High Capital Intensity:The acquisition and maintenance of advanced co-extrusion lines and the cleanroom environments required for medical and electronics-grade films demand significant capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Plastic Films Market |
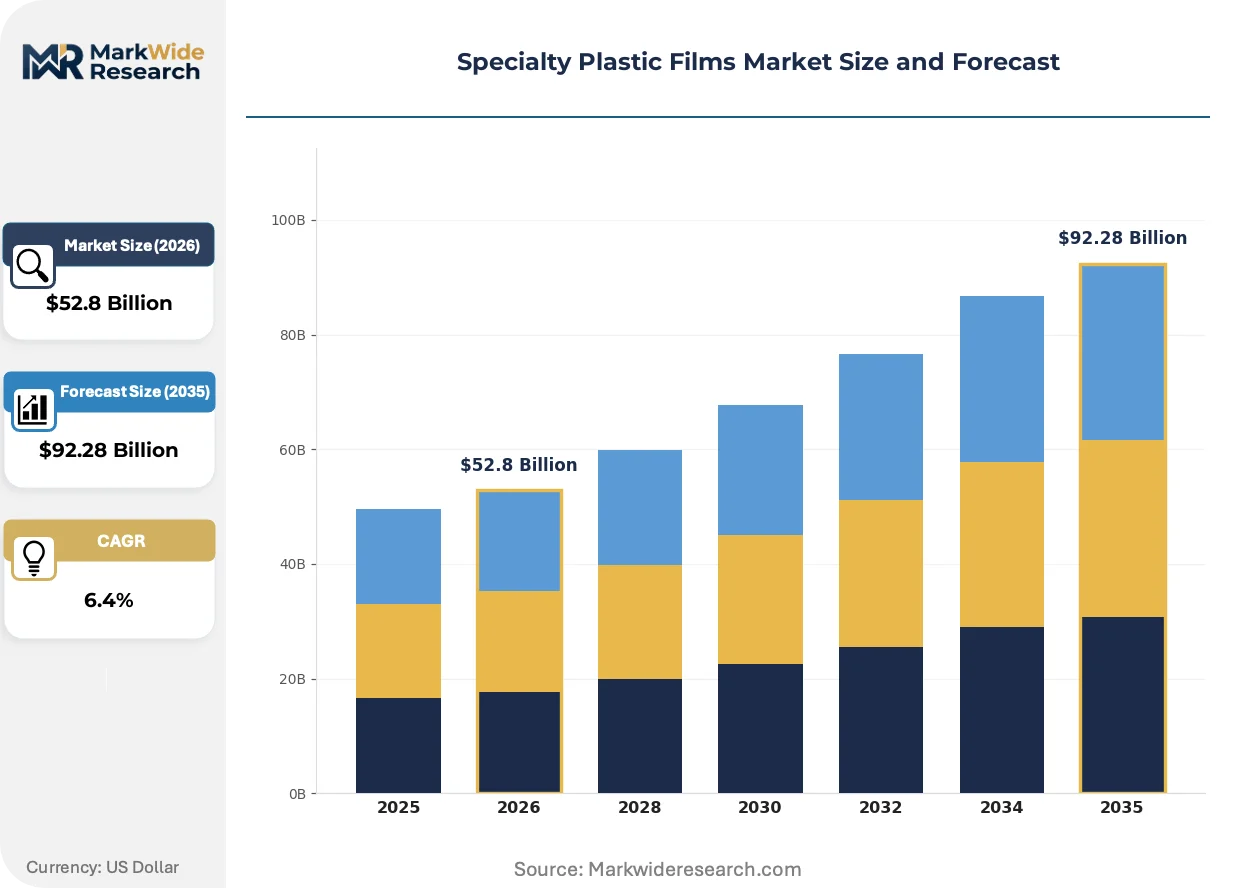
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester Application: Packaging, Agriculture, Electronics, Construction End User: Food & Beverage, Healthcare, Automotive, Consumer Goods Thickness: Below 50 Microns, 50-100 Microns, 100-200 Microns, Above 200 Microns |
| Companies Covered | 3M, Covestro AG, Evonik Industries AG, Toray Industries Inc., Honeywell International Inc., SABIC, Dupont Teijin Films U.S. Limited Partnership, Berry Global Inc., Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Plastic Films Market Strategic Shifts & Innovations
Material science innovation is converging with regulatory pressures to redefine product viability. This dynamic forces producers to balance advanced functional properties with end-of-life considerations, particularly concerning recyclability and chemical composition compliance across global markets.
Advanced barrier coating technology provides specific gas and moisture protection. Food and medical packaging converters are the primary adopters, seeking to extend shelf life and ensure product integrity. The market is migrating from difficult-to-recycle multi-material laminates toward mono-material substrates enhanced with ultra-thin functional coatings, simplifying the recycling stream.
The European Union's Circular Economy Action Plan imposes strict targets for plastic packaging recyclability and mandates minimum levels of recycled content. This policy directly impacts film producers supplying the European market, forcing investment in redesigning products for easier recycling. The packaging segment is most affected, with companies exploring chemical recycling to meet content requirements.
Buyer evaluation criteria are evolving beyond simple unit cost. Procurement decisions in the consumer packaged goods sector increasingly factor in total lifecycle costs, including potential fees under Extended Producer Responsibility (EPR) schemes. This shift is most pronounced in Europe, where mature EPR frameworks incentivize the use of easily recyclable film structures.
Specialty Plastic Films Market Segmentation
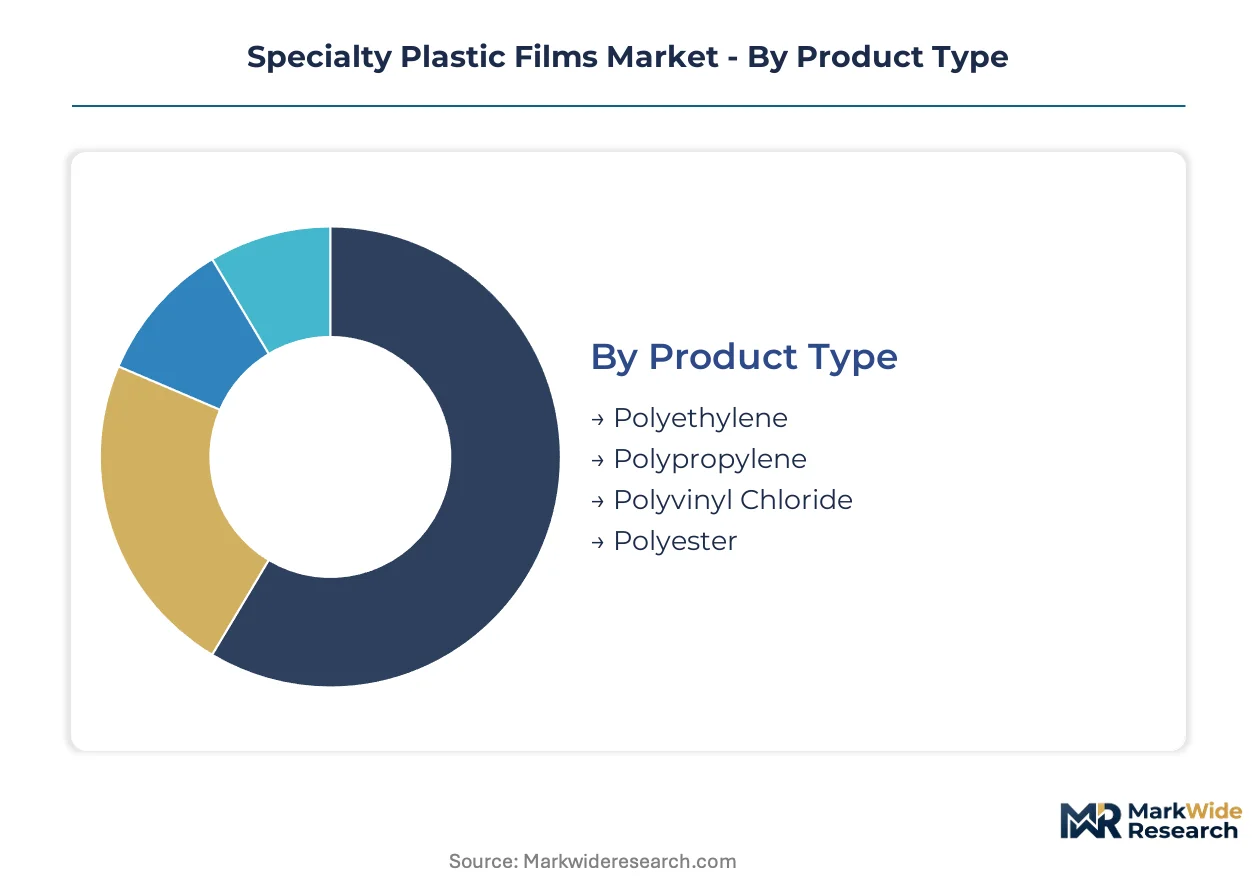
Specialty plastic films serve diverse functions across industries, demanding precise material specifications. Understanding these segments reveals the specific material science and performance demands driving market evolution. This granular view helps producers align product development with distinct application needs.
Product Type:
Product type segmentation highlights the varying material lifecycles, from high-volume, shorter-use films to durable, long-lasting industrial components.
- Polyester:These films, often based on PET, exhibit high tensile strength, excellent thermal stability, and superior optical clarity. Demand is concentrating in high-end electronics, such as flexible displays and capacitors, where precise material properties are critical.
- Polyethylene:Polyethylene films, including LDPE, LLDPE, and HDPE, offer flexibility, good moisture barrier, and heat-sealability. Their demand is concentrated in the packaging sector, particularly for food and consumer goods, due to cost-effectiveness and versatility.
- Polypropylene:Polypropylene films provide high stiffness, clarity, and good barrier properties, often used in flexible packaging and labels.
- Polyvinyl Chloride:PVC films offer excellent clarity, chemical resistance, and printability, finding use in shrink wraps and medical packaging.
Polyethylene anchors the volume base while Polyester gains share at the steepest rate.
Application:
The application segments delineate where specialty plastic films provide critical functional performance beyond commodity materials.
- Packaging:Films in this segment provide barrier protection, extend shelf life, and ensure product integrity for various goods. This application sees significant demand in food & beverage and pharmaceutical industries globally, driven by consumer safety and convenience needs.
- Electronics:These films offer properties like optical clarity, dielectric strength, and thermal resistance, essential for components. Demand from the electronics sector is concentrating in Asia, particularly for flexible displays and advanced circuitry, where precision is paramount.
- Construction:Construction films provide weather resistance, insulation, and protective barriers for building materials and infrastructure projects.
- Agriculture:Agricultural films enhance crop yield, control moisture, and protect produce, used in greenhouses and mulching applications.
The packaging application drives significant market value, while electronics applications push material science innovation.
End User:
End-user segmentation reveals the distinct procurement criteria and regulatory compliance needs across different industries.
- Healthcare:This segment demands films with high barrier properties, sterility, and puncture resistance for medical devices and pharmaceutical packaging. Demand from the healthcare sector is consistently strong across North America and Europe, driven by stringent regulatory standards like those from the US FDA and EMA.
- Food & Beverage:Films for food and beverage applications focus on extending shelf life, preventing contamination, and ensuring product freshness. The segment's demand is concentrating in emerging economies, particularly in Southeast Asia, where processing and packaging infrastructure is expanding rapidly.
- Consumer Goods:Consumer goods utilize films for protective packaging, branding, and tamper-evident seals for various household products.
- Automotive:Automotive applications require films for interior components, protective wraps, and functional laminates, offering durability and aesthetic appeal.
Healthcare end users impose the most stringent regulatory requirements, influencing film design and material selection across the industry.
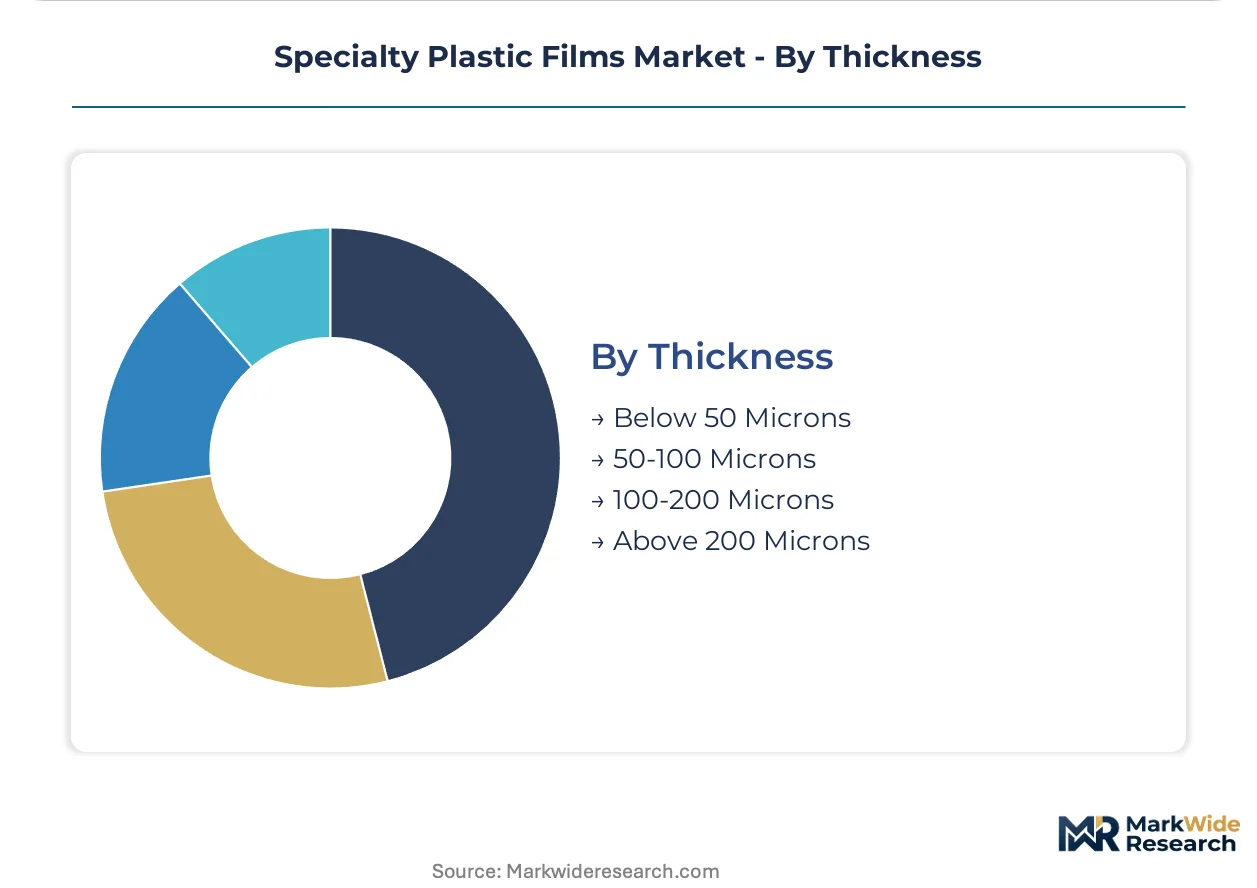
Thickness:
Thickness segmentation often correlates with the performance-to-cost ratio, with ultra-thin films enabling advanced functionalities and thicker films providing robust protection.
- Below 50 Microns:These ultra-thin films are critical for lightweighting, flexible electronics, and high-barrier coatings where minimal material usage is vital. Demand for these films is increasing in specialized applications such as foldable displays and advanced medical patches, particularly in East Asian manufacturing hubs.
- 50-100 Microns:This thickness range represents a balance of strength, flexibility, and cost-effectiveness, making it suitable for a wide array of flexible packaging. The segment sees broad demand across consumer packaged goods, driven by the need for efficient material use without compromising protection.
- 100-200 Microns:Films in this range offer enhanced durability and barrier properties, commonly used for industrial packaging and some construction applications.
- Above 200 Microns:Thicker films provide maximum protection and rigidity, essential for heavy-duty industrial applications and durable construction membranes.
Innovation in film thickness is pushing towards thinner, higher-performing materials to meet sustainability goals and advanced application requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty plastic films see significant trade flows, with Asian manufacturing hubs exporting high-performance materials to global markets. This dynamic supports diverse applications, from advanced electronics to sterile medical packaging. The interplay of regional demand and specialized production shapes investment priorities across continents.
United States
The United States healthcare sector drives demand for advanced sterile packaging films, alongside the electronics industry requiring specialized materials for flexible displays. US FDA standards rigorously govern material selection for medical device packaging, ensuring product safety and efficacy. Silicon Valley and Boston areas host significant R&D and manufacturing for high-tech applications, leveraging these advanced films.
Germany
Germany's automotive industry and high-end industrial packaging sectors exhibit consistent demand for durable and functional specialty films. The EU's REACH regulations and Circular Economy Action Plan significantly influence material composition and recyclability requirements for film producers. Chemical parks in Ludwigshafen and Leverkusen remain central to polymer innovation and advanced film production.
China
China's expansive electronics manufacturing base and vast consumer goods packaging market propel substantial demand for specialty plastic films. China's GB standards impose strict requirements for food contact materials and chemical substance registration, influencing product development. The Yangtze River Delta and Pearl River Delta regions serve as major production and consumption hubs for these specialized films.
India
India's rapidly expanding food & beverage packaging and pharmaceutical sectors generate considerable demand for specialty films. The PLI (Production Linked Incentive) scheme actively encourages domestic manufacturing of high-performance materials, stimulating local production. Gujarat and Maharashtra are emerging as key centers for film production and processing capabilities.
Japan
Japanese industries, particularly advanced electronics components and high-performance industrial sectors, require films with precise functional characteristics. JIS (Japanese Industrial Standards) ensure rigorous material quality and performance in critical applications, maintaining high industry benchmarks. The Tokyo and Osaka regions continue to host significant R&D centers and specialized film manufacturers.
Specialty Plastic Films Market Key Industry Players
On the supply side, the industry is characterized by a fragmented competitive landscape, featuring a mix of integrated material science giants and numerous specialized niche producers. Three strategic archetypes dominate: integrated polymer manufacturers, scale-focused packaging solution providers, and application-specific innovators. Competitive moves include consistent capacity expansion and strategic portfolio diversification to meet evolving market needs.
Within the integrated material science tier, Toray Industries Inc. represents expertise in high-performance polyester films for electronics and industrial uses. Berry Global Inc. exemplifies scale-driven offerings, providing a broad portfolio for the packaging sector. Covestro AG anchors the advanced polyurethane and polycarbonate-based film segment, catering to automotive and medical applications.
| Leading Market Players |
|---|
| 3M |
| Covestro AG |
| Evonik Industries AG |
| Toray Industries Inc. |
| Honeywell International Inc. |
| SABIC |
| Dupont Teijin Films U.S. Limited Partnership |
| Berry Global Inc. |
| Amcor Plc |
| Others |
Cost & Logistics Intelligence
Commodity volatility in petrochemical feedstocks determines both pricing tier spreads and supply chain shape for specialty plastic films. This fluctuation directly impacts material costs, influencing manufacturer margins and product differentiation strategies.
Pricing Analysis
The technology-generation pricing gap between advanced multi-layer films and simpler mono-material structures creates distinct market tiers. The dominant pricing model is contract-based long-term offtake, particularly for high-volume packaging applications. Price differentiation stems from certification level, such as US FDA approval for medical films, and the degree of customization required for specialized electronics. Pricing softness reflects intense competition in standard packaging films, while healthcare end-users exhibit the lowest price sensitivity due to stringent performance and regulatory needs.
Supply Chain Analysis
Export-control regimes, particularly those impacting advanced materials for electronics, limit the global flow of high-performance films. Supply concentrates in Asia, with China and Japan serving as major production hubs. The industry relies heavily on petrochemical feedstocks like ethylene and propylene. Regulatory fragmentation poses a significant structural risk, with distribution running through specialized converters and direct sales to large OEM customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty plastic films market presents a significant service-attach opportunity. Technical support and material customization consulting, a recurring revenue layer, expands faster than the base film material sales.
For Market Incumbents:Harden intellectual property protections around advanced barrier coating technologies to counter emerging entrant threats. Invest in localized capacity expansion in India, leveraging the PLI scheme, to mitigate feedstock price volatility and strengthen regional supply. Deepen vertical integration into specialized polymer compounding to control material quality and reduce reliance on external suppliers. This protects against substitution from bio-plastics in less demanding applications.
For New Entrants and Emerging Players:Pursue mono-material film development for high-barrier packaging, targeting the European market to meet circular economy mandates. Focus on flexible electronics applications, particularly foldable displays, as a high-value white-space target. The packaging segment in Southeast Asia offers the most penetrable geography due to expanding food processing infrastructure. A direct-to-converter sales model emphasizing custom material science solutions provides a strong go-to-market angle.
For Investors and Strategic Acquirers:The EU's Circular Economy Action Plan reshapes the acquisition landscape, favoring companies with proven recyclability solutions. Long-term viability over the next 5-10 years hinges on sustainable product portfolios and advanced recycling technologies. Target specialized material science innovators developing mono-material high-barrier films or chemical recycling capabilities. The signal to watch is the adoption rate of Extended Producer Responsibility (EPR) schemes globally, indicating future market direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Film Portfolio Expansion | Meets stringent EU recyclability mandates, appeals to sustainability-focused consumer brands, and simplifies end-of-life processing. |
| Investment in Chemical Recycling Infrastructure | Enables compliance with recycled content targets and provides a closed-loop solution for complex multi-layer films. |
| Capacity Expansion in Southeast Asia | Capitalizes on rapid growth in food processing and consumer packaged goods sectors across the region. |
| R&D in Flexible Electronics Films | Addresses the high-value demand for optically clear and durable films in emerging display technologies. |
| Strategic Partnerships with Medical Device OEMs | Secures long-term contracts and aligns product development with advanced sterile packaging requirements for healthcare. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, procurement leads, and regulatory affairs specialists, then refined. This involved combining insights from interviews with secondary validation. Secondary sources included company filings, industry association reports, and regulatory body publications. Bottom-up market sizing and top-down validation ensured robust data triangulation.
Demand-supply balance analysis formed the core of the forecast framework across the analysis window. The model integrated segmentation across product type, application, end-user, film thickness, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends, projected technology adoption, and expert consensus. Key forecast inputs included petrochemical feedstock price projections.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or industrial production would shift the trajectory. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Material shifts in major trade policies or the pace of circular economy implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Europe Luxury Packaging Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market