
 Copper Coated Films Market | 2026-2036
Copper Coated Films Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Coated Films Market Outlook
Modular substrate configurations are restructuring how electronics buyers specify copper coated films, shifting from monolithic laminates toward stackable, thickness-graded layers that reduce waste. 3M Company leverages its adhesive-coating expertise to dominate high-tack bonding applications for flexible circuits. DuPont de Nemours anchors the premium polymer substrate segment with proprietary Kapton-compatible formulations. Nitto Denko specializes in ultra-thin roll-to-roll coatings for display interconnects.
Copper coated films consist of thin metallic copper layers deposited onto flexible or rigid substrates through sputtering, electroplating, or chemical vapor deposition, typically achieving thicknesses between 0.1 and 35 micrometers to provide electrical conductivity, electromagnetic shielding, or thermal management. The polymer substrate category leads volume shipments due to its dominance in flexible electronics, while the composite substrate segment records the fastest expansion as aerospace and satellite manufacturers seek weight-reduction without sacrificing shielding effectiveness. Electronics applications command the largest value share, though automotive demand is accelerating fastest as EV power electronics require higher thermal dissipation from compact form factors.
EPA standards govern volatile organic compound emissions from solvent-based coating processes in the United States, while REACH restrictions in Europe limit hexavalent chromium in anti-corrosion pretreatments. Japan's METI enforces JIS standards for electromagnetic compatibility in consumer electronics, directly influencing copper layer thickness specifications for films exported to Japanese OEMs. Stakeholders must monitor how evolving battery-electric vehicle thermal management requirements in multiple jurisdictions reshape copper thickness and substrate flexibility specifications ahead of platform redesign cycles.
Market Dynamics
Substrate miniaturization in flexible electronics is compressing copper layer thickness specifications while multiplying functional requirements, forcing manufacturers to reconcile thermal dissipation demands with roll-to-roll processing constraints.
Growth Catalysts
- EV Power Electronics:Battery-electric vehicle inverters and DC-DC converters require higher thermal conductivity from compact form factors, pulling copper coated films into automotive thermal management stacks.
- REACH Compliance Deadlines:European hexavalent chromium restrictions are accelerating substitution toward copper-based anti-corrosion pretreatments in electromagnetic shielding applications.
- Seoul-Suwon Semiconductor Corridor:South Korean advanced packaging facilities are expanding orders for ultra-thin polymer substrates as chiplet architectures proliferate.
Market Restraints
- Copper Price Volatility:London Metal Exchange copper futures expose film manufacturers to input cost swings that contract structures cannot fully hedge.
- Sputtering Equipment Concentration:Roll-to-roll vacuum deposition systems concentrate among Japanese and German capital equipment suppliers, creating procurement bottlenecks.
- Polyimide Substrate Sourcing:Kapton-compatible polymer supply chains anchor to limited DuPont production sites, constraining qualified alternative sourcing.
Strategic Opportunities
- Satellite Constellation Deployment:Low-earth orbit satellite manufacturers seek weight-reduction in electromagnetic shielding without sacrificing effectiveness, opening composite substrate applications.
- Japan METI JIS Standards:Electromagnetic compatibility mandates for consumer electronics create specification pull for copper layer thicknesses in films exported to Japanese OEMs.
- Roll-to-Roll Laser Patterning:Direct laser structuring of copper traces without photolithography masks is converging with additive manufacturing workflows for prototyping.
Industry Challenges
- Thin-Film Metallurgist Talent:Sputtering process optimization and adhesion chemistry expertise concentrates among aging specialists in Japan and Germany.
- EPA VOC Compliance Timelines:Solvent-based coating process retrofits require capital deployment ahead of emission standard phase-ins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Coated Films Market |
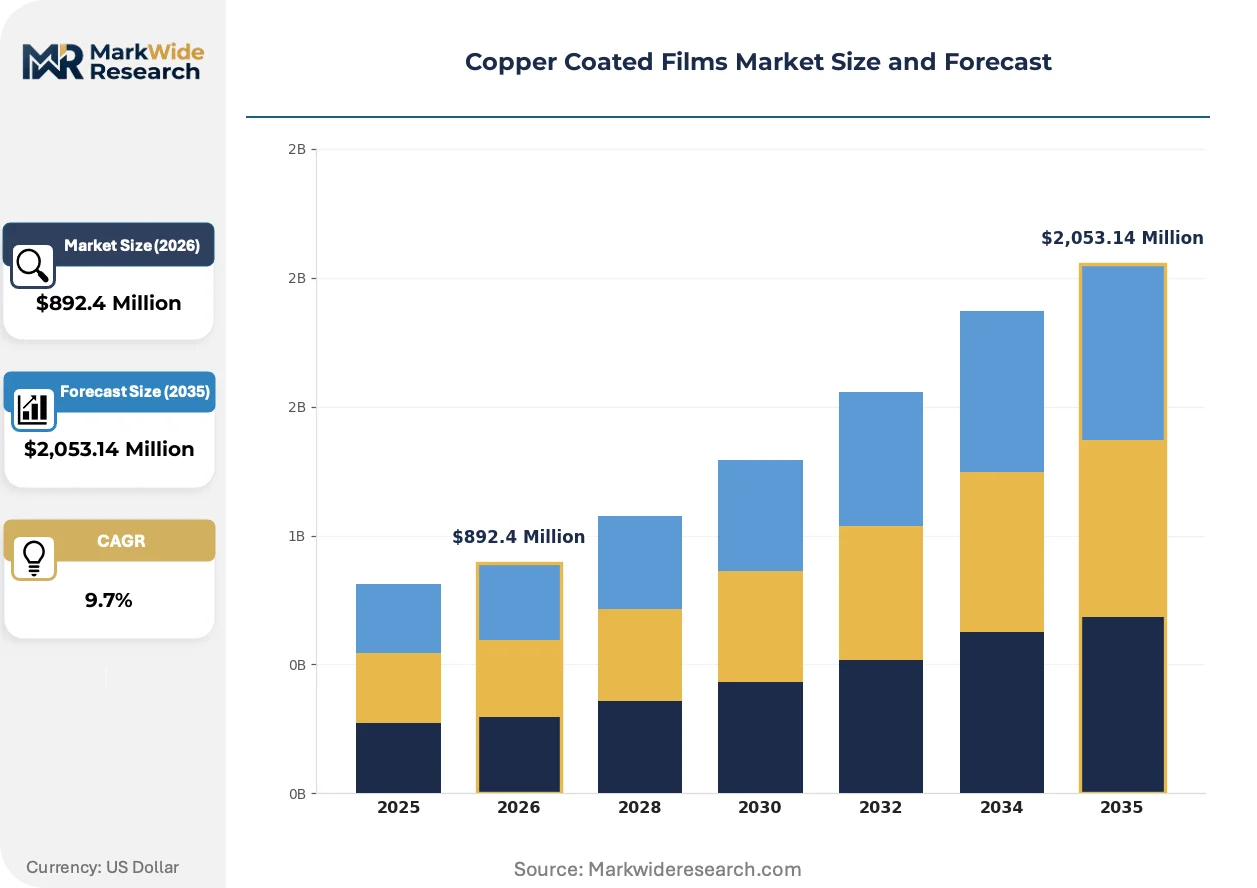
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $2,053.14 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
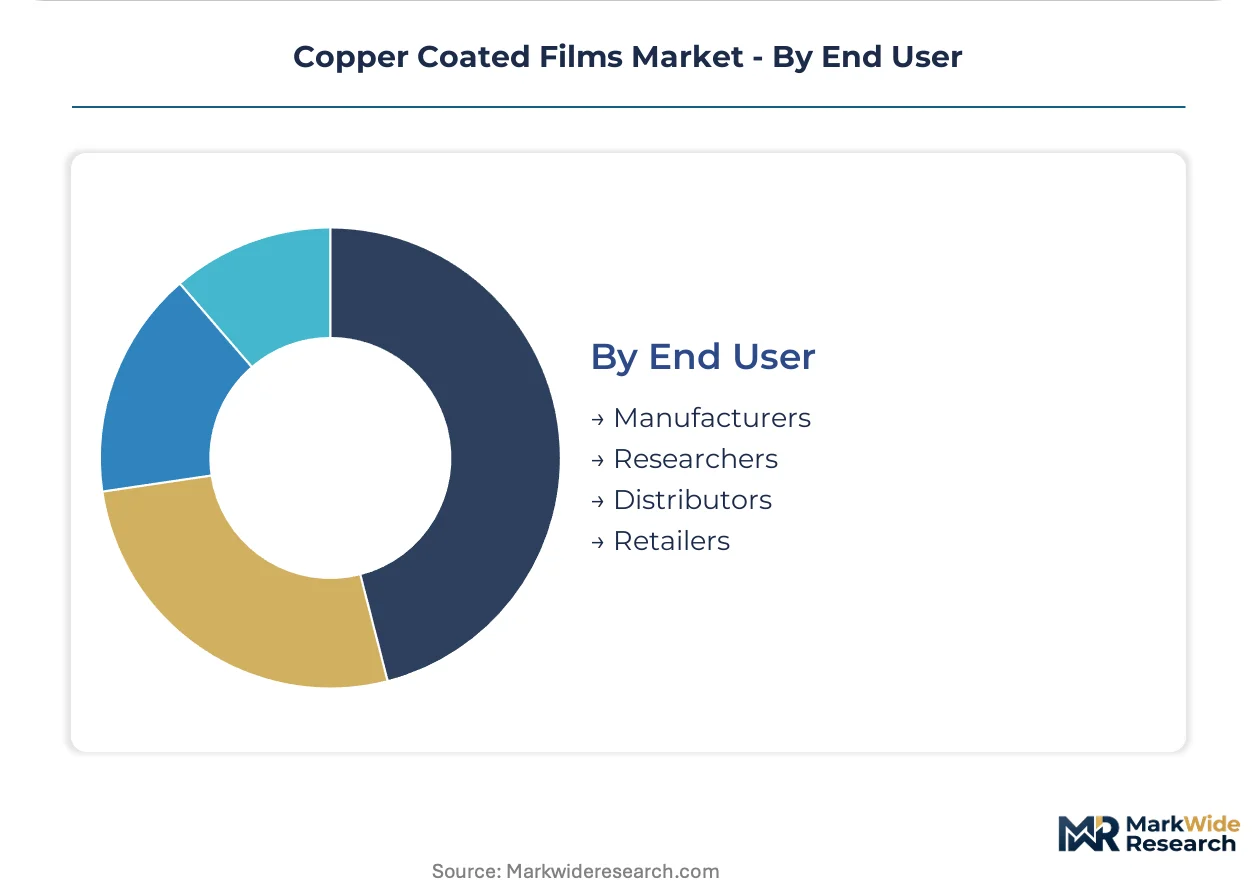
| Segmentation | Product Type: Polymer, Aluminum, Composite, Glass Application: Electronics, Automotive, Packaging, Medical Form: Rolls, Sheets, Coatings, Laminates End User: Manufacturers, Researchers, Distributors, Retailers |
| Companies Covered | 3M Company, DuPont de Nemours, AGC Inc., Avery Dennison Corporation, Dunmore, Toray Industries, Nitto Denko, Lintec Corporation, Remtec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Coated Films Market Strategic Shifts
Stackable substrate architectures are displacing monolithic laminates across electronics manufacturing, with thickness-graded layers enabling waste reduction and design flexibility. This structural shift reconfigures how buyers specify copper coated films and how suppliers organize production.
Roll-to-roll sputtering with in-situ thickness monitoring is modularizing how manufacturers configure deposition lines. Display interconnect producers in South Korea are adopting reconfigurable coating sections that swap between 0.1 and 5 micrometer targets without line shutdowns. This flexibility is compressing minimum order quantities and enabling just-in-time thickness customization previously reserved for batch processes.
EPA volatile organic compound standards for solvent-based coating processes are tightening emission thresholds in the United States. Electronics manufacturers with captive coating operations face retrofit deadlines that favor aqueous or UV-curable alternatives. Flexible circuit producers in Michigan and Texas are accelerating capital planning to maintain compliance without disrupting automotive customer qualification cycles.
Specification consolidation among tier-one electronics assemblers is compressing supplier qualification timelines. Buyers in the semiconductor packaging segment now demand simultaneous substrate, adhesive, and copper layer certification rather than sequential validation. This pattern concentrates procurement among vertically integrated film suppliers with in-house polymer casting and metallization capabilities, most visible in procurement patterns around Seoul and Shenzhen.
Copper Coated Films Market Segmentation
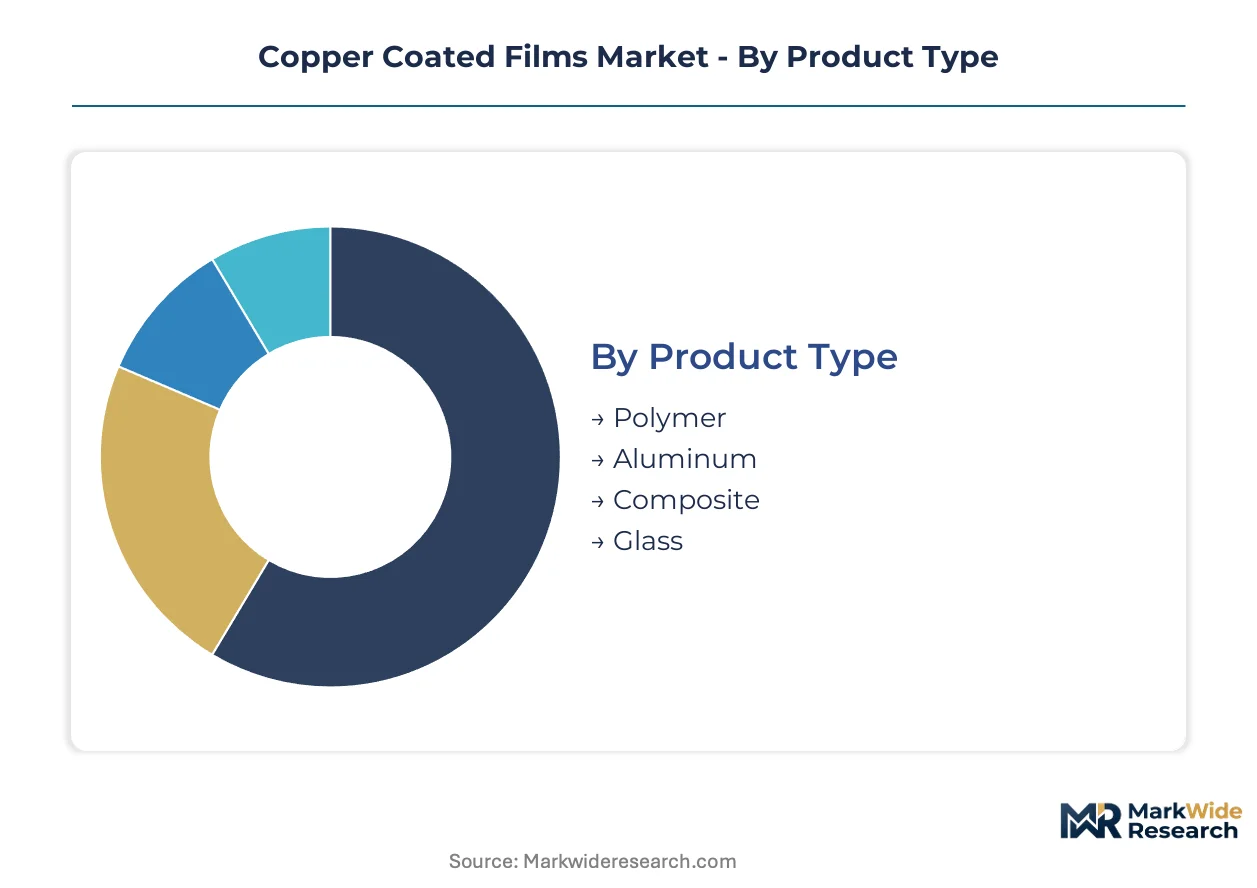
Copper coated film specifications diverge sharply across end-use requirements, with substrate flexibility, thermal conductivity, and electromagnetic shielding effectiveness driving incompatible technical priorities. Buyers in automotive thermal management demand fundamentally different copper thickness and adhesion profiles than satellite manufacturers seeking weight reduction.
Product Type:
Polymer substrate supply chains anchor to limited qualified production sites, constraining how quickly film manufacturers can pivot between material specifications.
- Polymer:Flexible polyimide and polyester substrates dominate flexible printed circuit applications, with Kapton-compatible formulations commanding premium positioning. Seoul-Suwon semiconductor packaging facilities are expanding orders for ultra-thin polymer variants as chiplet architectures proliferate, though DuPont production site concentration limits alternative sourcing.
- Composite:Multi-layer substrates combining polymer cores with ceramic or metallic interlayers achieve weight reduction without sacrificing shielding effectiveness. Low-earth orbit satellite manufacturers are driving specification pull for composite formulations, with aerospace contractors in Germany and Japan qualifying new suppliers for constellation deployment programs.
- Aluminum:Aluminum-copper hybrid substrates serve cost-sensitive electromagnetic interference shielding where thermal dissipation requirements remain moderate.
- Glass:Rigid glass substrates with sputtered copper layers anchor display interconnect and high-frequency applications requiring dimensional stability.
Today's leader: Polymer. Tomorrow's challenger: Composite.
Application:
Automotive thermal management applications are climbing the fastest as battery-electric vehicle power electronics reshape copper thickness specifications.
- Electronics:Flexible circuits, display interconnects, and semiconductor packaging consume the largest volume share, with roll-to-roll processing optimized for thicknesses between 0.1 and 35 micrometers. South Korean display manufacturers are adopting reconfigurable coating sections that swap deposition targets without line shutdowns, compressing minimum order quantities for just-in-time customization.
- Automotive:EV inverters and DC-DC converters require higher thermal conductivity from compact form factors, pulling copper coated films into power module substrates and battery thermal management stacks. Michigan and Texas flexible circuit producers are accelerating capital planning to maintain EPA volatile organic compound compliance without disrupting automotive customer qualification cycles.
- Packaging:Anti-corrosion and electromagnetic shielding films protect sensitive electronics during transit, with REACH hexavalent chromium restrictions accelerating copper-based pretreatment substitution.
- Medical:Biocompatible copper coatings for antimicrobial surfaces and diagnostic device interconnects face extended qualification timelines from FDA and EMA.
Electronics commands current volume. Automotive traces the steepest expansion trajectory.
Form:
Roll-to-roll processing configurations determine achievable thickness tolerances and minimum order economics across form factor categories.
- Rolls:Continuous wound formats enable high-throughput sputtering and electroplating with in-situ thickness monitoring, dominating flexible electronics production. Display interconnect manufacturers in South Korea and Japan configure modular deposition lines with reconfigurable coating sections.
- Sheets:Rigid formats suit batch processing for aerospace and medical applications requiring precise dimensional control and lot traceability.
- Coatings:Direct liquid or vapor-deposited copper layers applied to customer-supplied substrates serve specialty electromagnetic shielding and thermal management retrofit applications.
- Laminates:Pre-bonded copper-substrate-adhesive stacks compress buyer qualification timelines by consolidating multi-layer certification, concentrating procurement among vertically integrated suppliers.
Rolls dominate throughput. Laminates consolidate procurement power.
End User:
Manufacturer procurement patterns are compressing supplier qualification timelines from sequential to simultaneous substrate-adhesive-copper layer certification.
- Manufacturers:Captive flexible circuit producers and electronics assemblers specify copper coated films directly, with tier-one semiconductor packaging buyers demanding in-house polymer casting and metallization capabilities. Procurement concentrates around Seoul and Shenzhen among qualified integrated suppliers.
- Researchers:Academic and national laboratory users drive prototyping volumes for additive manufacturing integration and laser patterning process development, with smaller lot sizes and extended technical support requirements.
- Distributors:Technical distributors serve mid-tier electronics manufacturers with stocked standard thicknesses, though specification consolidation among large buyers is compressing their addressable market.
- Retailers:Limited direct retail presence exists, confined to hobbyist electronics and small-scale repair applications with minimal technical specification requirements.
Manufacturers control specification power. Researchers shape next-generation process adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper coated film manufacturing originated in post-war Japan and the United States, where sputtering techniques developed for aerospace applications migrated into consumer electronics. Production expertise subsequently dispersed to South Korea and Germany as flexible circuit demand multiplied across automotive and display sectors.
United States
EPA volatile organic compound standards are forcing coating process retrofits in Michigan and Texas flexible circuit facilities. The agency's emission threshold tightening favors aqueous and UV-curable alternatives over solvent-based deposition. Automotive thermal management stacks for EV power electronics concentrate procurement authority with tier-one assemblers in Detroit and Austin corridors.
Germany
Aerospace contractors in Bavaria and Baden-Württemberg are qualifying composite substrate suppliers for low-earth orbit satellite constellation programs. REACH hexavalent chromium restrictions accelerate copper-based anti-corrosion pretreatment substitution across electromagnetic shielding applications. Stuttgart and Munich industrial clusters anchor European qualification timelines for satellite-grade film specifications.
South Korea
Seoul-Suwon semiconductor packaging facilities are expanding orders for ultra-thin polymer substrates as chiplet architectures proliferate. The country's national technology regulator enforces electromagnetic compatibility standards that directly influence copper layer thickness specifications for domestic OEM exports. Display interconnect manufacturers in Gyeonggi Province configure modular deposition lines with reconfigurable coating sections for just-in-time thickness customization.
Japan
METI JIS standards for electromagnetic compatibility in consumer electronics create specification pull for copper layer thicknesses in films exported to domestic OEMs. Roll-to-roll vacuum deposition equipment concentrates among capital equipment suppliers in Nagoya and Osaka industrial corridors. Sputtering process optimization expertise concentrates among aging specialists in Chubu and Kansai regions.
China
Shenzhen and Dongguan electronics assemblers are compressing supplier qualification timelines from sequential to simultaneous substrate-adhesive-copper layer certification. The country's Ministry of Industry and Information Technology governs GB standards for flexible circuit applications. Pearl River Delta procurement patterns concentrate among vertically integrated film suppliers with in-house polymer casting and metallization capabilities.
Copper Coated Films Market Competitive Environment
Premium-margin players sit above commodity-margin players across substrate formulation and metallization precision capabilities. The market structures into three tiers: vertically integrated polymer-metallization houses, specialized coating service providers, and captive electronics manufacturer operations. Strategic archetypes include adhesive-coating specialists leveraging polymer expertise, sputtering equipment operators with roll-to-roll scale, and materials science conglomerates with captive substrate supply. Competitive moves concentrate on backward integration into polymer casting and geographic expansion toward Seoul-Suwon and Shenzhen demand clusters.
Within the adhesive-coating specialist tier, 3M Company and Avery Dennison Corporation represent North American positioning anchored in bonding chemistry expertise. DuPont de Nemours occupies a position exemplifying premium polymer substrate supply with proprietary formulation control. Among East Asian fabricators, Nitto Denko and Toray Industries sit within the precision coating archetype, with Japanese corporate structures supporting roll-to-roll scale operations. These five entities illustrate how competitive positioning diverges across substrate control, coating precision, and adhesive integration vectors.
| Leading Market Players |
|---|
| 3M Company |
| DuPont de Nemours |
| AGC Inc. |
| Avery Dennison Corporation |
| Dunmore |
| Toray Industries |
| Nitto Denko |
| Lintec Corporation |
| Remtec Inc. |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange copper futures volatility cascades through copper coated film supply chains into three-tier pricing structures across premium, standard, and economy levels. Polymer substrate concentration at DuPont production sites amplifies cost pass-through for Kapton-compatible formulations, while REACH-compliant anti-corrosion pretreatments command certification premiums from European automotive buyers.
Pricing Analysis
Contract-based long-term offtake arrangements with quarterly price adjustment clauses dominate procurement between tier-one electronics assemblers and qualified film suppliers. Price differentiation hinges on ISO-certified polymer casting capabilities and JIS-compliant electromagnetic compatibility testing. Cost compression in standard-grade polymer substrates is intensifying because South Korean display manufacturers are consolidating orders around vertically integrated suppliers with in-house metallization. Automotive thermal management buyers exhibit lowest price sensitivity due to qualification lock-in, while commodity electromagnetic shielding distributors face highest margin pressure.
Supply Chain Analysis
Dual-sourcing mandates from tier-one semiconductor packaging buyers require simultaneous qualification of polymer substrate and copper metallization suppliers across Japan, South Korea, and Germany. Raw material flows draw from Chilean copper concentrate, DuPont polyimide resin, and Japanese sputtering target manufacturers. Single-source vulnerability concentrates in roll-to-roll vacuum deposition equipment from Nagoya and Osaka capital equipment suppliers. Distribution runs through direct mill relationships for high-volume electronics assemblers and technical distributors for mid-tier flexible circuit producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copper coated films represent a margin-expansion trajectory as substrate miniaturization compresses qualified supplier pools and EV thermal management specifications shift toward premium composite formulations.
For Market Incumbents: Hedge copper price exposure through LME futures layering and long-term concentrate offtakes with Chilean mining houses. Deepen backward integration into polymer casting to defend against DuPont supply concentration, while accelerating EPA-compliant aqueous coating retrofits ahead of Michigan and Texas facility deadlines. Certification investment in simultaneous substrate-adhesive-copper layer validation compresses competitor qualification timelines. For New Entrants and Emerging Players: Technical distributors serving mid-tier automotive suppliers in the Detroit corridor offer lowest barrier-to-entry channel access. White-space targets include composite substrate qualification for German aerospace constellation programs and laser-patterning service bureaus for additive manufacturing prototyping. Position around REACH-compliant copper pretreatment substitution as hexavalent chromium restrictions tighten. For Investors and Strategic Acquirers: Asymmetric upside sits with precision coating specialists possessing modular roll-to-roll deposition lines and in-situ thickness monitoring capabilities. Five-to-ten year viability favors suppliers with demonstrated Seoul-Suwon and Shenzhen qualification history. Watch for inflection in battery-electric vehicle platform redesign cycles triggering copper thickness specification resets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Casting | In-house Kapton-compatible substrate production secures supply continuity for automotive qualification cycles. |
| Modular Roll-to-Roll Deposition Line Expansion | Reconfigurable coating sections enable just-in-time thickness customization for South Korean display manufacturers. |
| REACH-Compliant Pretreatment Certification | Copper-based anti-corrosion validation opens European electromagnetic shielding substitution opportunities. |
| Laser Patterning Service Bureau Launch | Maskless copper trace structuring converges with additive manufacturing prototyping demand from research institutions. |
| Composite Substrate Aerospace Qualification | Weight-reduction specifications for low-earth orbit satellites drive specification pull from Bavaria contractors. |
Study Parameters
Bottom-up flexible electronics and automotive thermal management modeling reconciled against top-down sputtering equipment and polymer substrate supply tracking forms the analytical core of this study. Primary interviews with flexible circuit procurement directors, polymer casting plant managers, sputtering process engineers, and automotive platform thermal architects combined with secondary validation from EPA emission filings, METI JIS standard publications, REACH restriction updates, and SEC 10-K disclosures from listed materials suppliers. Triangulation across these sources calibrated volume and value estimates.
Historical trendline analysis of polymer substrate shipments and copper layer thickness specifications established baseline growth patterns across the projection horizon. Segmentation modeling incorporated substrate type, application end-use, form factor, and regional regulatory cluster dimensions. CAGRs derived from elasticity analysis against EV power electronics content per vehicle, chiplet architecture proliferation rates, and satellite constellation deployment schedules. Industry-specific forecast inputs included LME copper price scenarios and sputtering equipment lead time assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery-electric vehicle platform redesign timing, REACH enforcement stringency evolution, and DuPont polymer supply expansion decisions. Deviation in Seoul-Suwon semiconductor packaging capital expenditure cycles would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Bonding Films Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
North America Barrier Films Market