
 Global Rigid Paper Containers Market | 2026-2036
Global Rigid Paper Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rigid Paper Containers Market Intelligence
Buyer concentration among food and beverage multinationals is hardening as private-label entrants fragment the mid-market. International Paper leverages its integrated pulp-to-box network across North American mills to serve this consolidated tier. Smurfit Kappa competes through European corrugated and solid board expertise, while Huhtamäki Oyj specializes in molded fiber and formed paper solutions for quick-service restaurant chains.
Rigid paper containers are structural packaging products fabricated from paperboard substrates exceeding 200 gsm, formed through die-cutting, scoring, folding, and adhesive bonding to create load-bearing enclosures with defined geometric stability. Their primary purpose is to protect, transport, and display consumer goods while substituting plastic and metal alternatives. Folding cartons dominate volume due to flat-pack shipping efficiency and high-speed filling line compatibility, whereas set-up boxes command premium margin pools in luxury goods and cosmetics. Composite containers are gaining fastest in dry food and nutritional supplements where barrier-coated paperboard replaces composite cans with metal ends.
The EU Green Deal and F-Gas Regulation indirectly accelerate paper container demand by constraining plastic film and foam alternatives, while FDA food contact substance notifications govern barrier coatings in US applications. India's BIS packaging standards and China's GB/T paperboard specifications shape import compliance and local sourcing decisions for multinational converters. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific recycling certification requirements as gatekeepers to retail shelf access.
Market Dynamics
The rigid paper container sector is reconfiguring around EU Green Deal packaging mandates that eliminate single-use plastics, forcing converters to absorb stranded plastic capacity into paperboard barrier-coating lines while food brands accelerate specification changes.
Growth Catalysts
- EU Green Deal packaging mandates:Brussels' phased plastic bans in food service and fresh produce categories redirect volume toward fiber-based alternatives with aqueous barrier coatings.
- India's domestic paperboard capacity expansion:BIS-compliant converting lines in Gujarat and Maharashtra reduce import dependency for multinational food brands operating in South Asia.
- Quick-service restaurant chains:Molded fiber clamshells and formed paper bowls replace expanded polystyrene in drive-thru and delivery formats across North American and European markets.
Market Restraints
- Pulp price volatility:Northern bleached softwood kraft supply interruptions in Scandinavia and Canada compress converter margins during contract renegotiations with consumer packaged goods buyers.
- Barrier coating technical limitations:Current aqueous and extruded polyethylene alternatives fail to match aluminum-laminated structures for oxygen-sensitive nutritional supplements and infant formula.
- China's GB/T paperboard specifications:Import compliance complexity for foreign converters delays market entry despite domestic demand for premium folding cartons in cosmetics and electronics.
Strategic Opportunities
- Brazil's underpenetrated nutritional supplement segment:ANVISA-aligned barrier-coated paperboard tubes and composite cans displace plastic jars in protein powder and vitamin categories.
- Extended producer responsibility frameworks:Germany's VerpackG and France's AGEC law create preferential shelf access for fiber-based packaging with certified recyclability credentials.
- Digital printing convergence with paperboard forming:Short-run variable data enables mass customization for regional food brands without cylinder engraving lead times.
Industry Challenges
- Barrier coating food contact notification timelines:FDA FCN submissions for novel aqueous coatings require 120-day review cycles that delay product launches.
- High-speed filling line integration:Paperboard rigidity tolerances differ from plastic and metal legacy formats, necessitating capital-intensive line modification at dairy and beverage co-packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rigid Paper Containers Market |
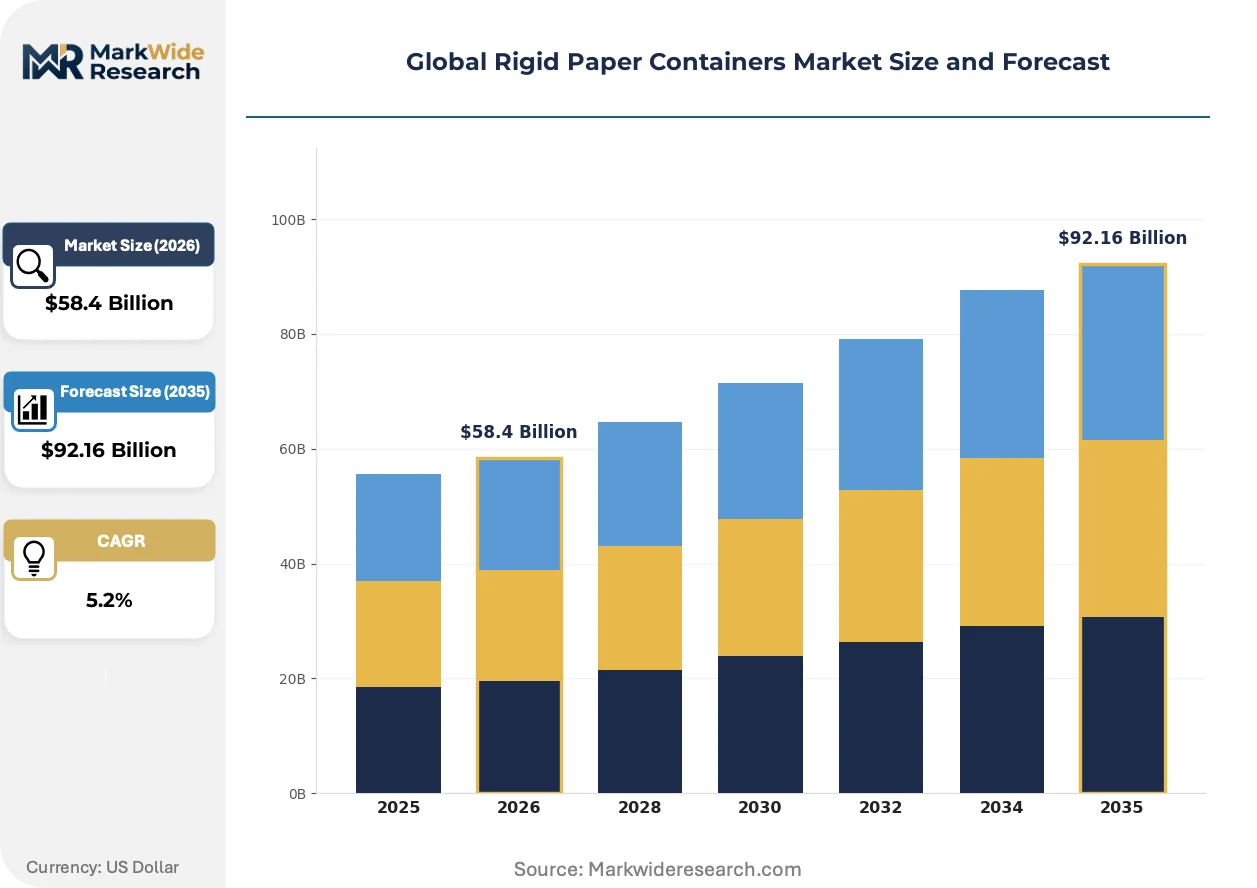
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $92.16 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Cartridge Boxes, Folding Cartons, Set-up Boxes, Composite Containers End Use Industry: Food & Beverage, Cosmetics & Personal Care, Electronics, Pharmaceuticals, Luxury Goods Material: Kraft Paper, Coated Paperboard, Specialty Paper, Laminated Paper, Recycled Paper Distribution Channel: Direct Sales, Retail Chains, Online Platforms, Wholesalers, Packaging Distributors |
| Companies Covered | International Paper, WestRock, Smurfit Kappa, Mondi Group, DS Smith, Sonoco Products Company, Amcor plc, Stora Enso, Huhtamäki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rigid Paper Containers Market Strategic Shifts & Innovations
Active barrier technologies and forming process automation are compressing the performance gap between paperboard and conventional plastic or metal packaging, while regulatory pressure accelerates specification turnover in food and beverage categories.
Water-based polymer barrier coatings are absorbing moisture and grease protection functions previously served by polyethylene extrusion or aluminum lamination. Dairy and prepared meal brands in Germany and France are adopting these coatings at pilot scale for refrigerated distribution. The technology is absorbing margin pressure from oil-based film substrates as pulp pricing stabilizes relative to petrochemical feedstocks.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) in food contact materials entered force across EU member states in early 2023. This regulatory shift eliminates oil-and-grease-resistant fluorochemical treatments from folding cartons and molded fiber products. Nordic and Benelux markets are responding fastest, with converters qualifying silicone and clay-based alternatives for fast-food packaging applications.
Brand procurement teams are consolidating specification authority at headquarters level while delegating volume allocation to regional manufacturing networks. This centralization pattern compresses the supplier base for multinational food and beverage accounts. The shift is most visible in North American and Western European markets where sustainability scorecards now determine contract renewal eligibility.
Global Rigid Paper Containers Market Segmentation
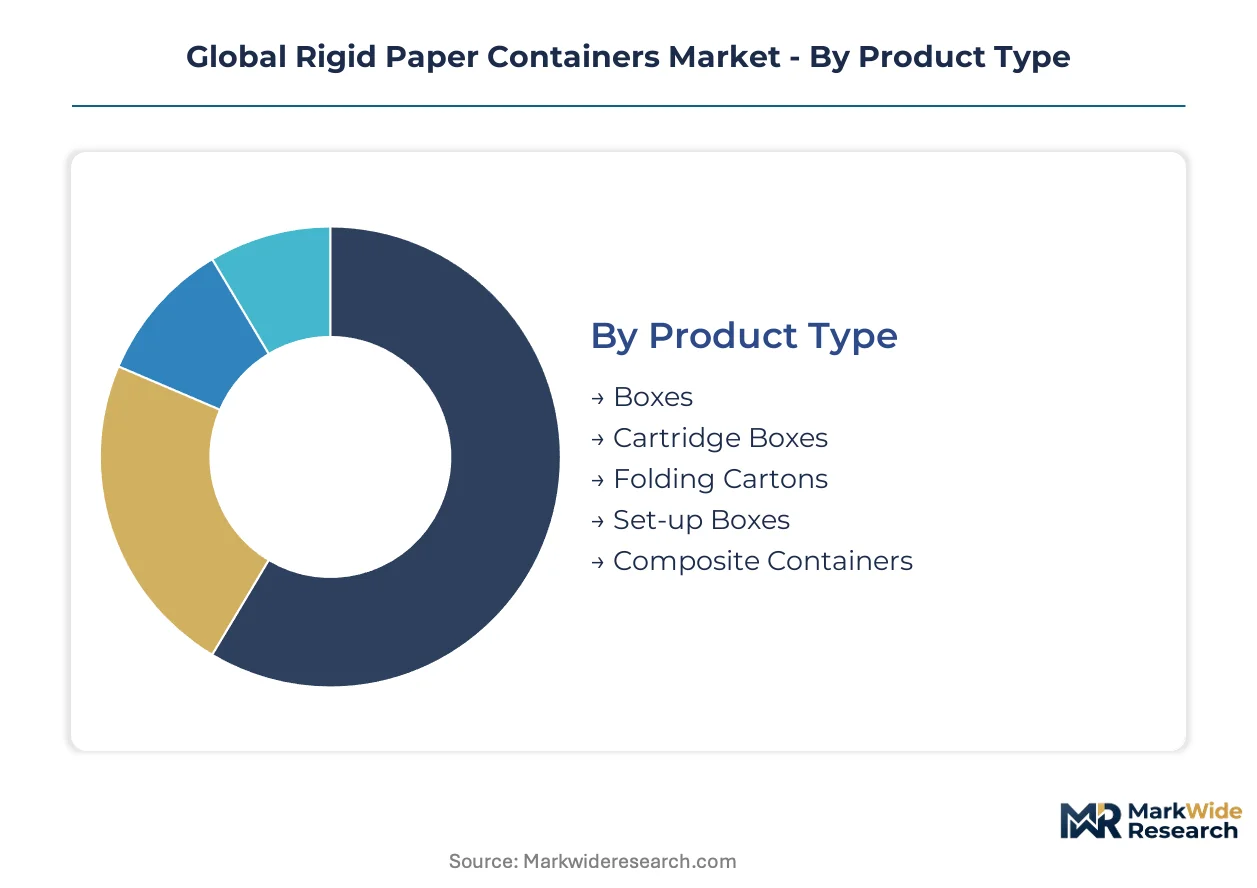
Converters configure production assets around substrate thickness, barrier performance, and forming complexity. Specification differentiation determines which segments absorb capital investment versus operating as overflow capacity.
Product Type:
Structural geometry dictates machinery requirements and shipping economics.
- Folding Cartons:Manufactured from flat paperboard blanks that crease and lock without adhesive, enabling pallet-efficient shipment to filling plants. German dairy and prepared meal brands specify aqueous barrier coatings for refrigerated distribution. Flat-pack economics dominate volume allocation.
- Composite Containers:Spiral-wound paperboard bodies with metal or plastic ends, offering rigidity for dry powders and granular products. Brazil's ANVISA-aligned nutritional supplement brands displace plastic jars with barrier-coated paperboard tubes. Barrier coating technical limitations constrain oxygen-sensitive applications.
- Boxes:General-purpose rigid enclosures for non-food industrial and retail applications.
- Cartridge Boxes:Precision-formed containers for ammunition and specialized industrial components.
- Set-up Boxes:Pre-assembled rigid structures with premium finishing for gift and display purposes.
Folding cartons lead on scale; composite containers lead on momentum.
End Use Industry:
Regulatory pressure and shelf-life requirements segment demand by compliance intensity.
- Food & Beverage:Dairy, prepared meals, and dry goods drive barrier-coated folding carton specifications. EU Green Deal mandates redirect quick-service restaurant chains toward molded fiber clamshells and formed paper bowls.
- Cosmetics & Personal Care:Premium set-up boxes and rigid folding cartons with metallic substrates and soft-touch coatings. REACH PFAS restrictions eliminate fluorochemical oil resistance, forcing silicone and clay-based alternative qualification.
- Electronics:Anti-static coatings and structural rigidity for device protection.
- Pharmaceuticals:Child-resistant and senior-friendly compliance structures for OTC packaging.
- Luxury Goods:Hand-finished set-up boxes with specialty paper wrapping and magnetic closures.
Food and beverage leads on scale; cosmetics and personal care leads on momentum.
Material:
Substrate selection balances structural integrity, printability, and regulatory compliance.
- Coated Paperboard:Clay-coated or polyethylene-extruded surfaces provide moisture resistance and high-fidelity print reproduction. India's BIS-compliant converting lines in Gujarat and Maharashtra scale domestic coated board capacity for multinational food brands.
- Kraft Paper:Unbleached virgin or recycled fiber delivers tear resistance and sustainability credentials for corrugated and rigid applications. Nordic markets prioritize certified recyclable fiber under extended producer responsibility frameworks.
- Specialty Paper:Textured, metallic, or translucent substrates for premium cosmetic and luxury applications.
- Laminated Paper:Multi-layer structures combining paperboard with aluminum or polymer films for barrier performance.
- Recycled Paper:Post-consumer fiber content for sustainability-mandated procurement specifications.
Coated paperboard leads on scale; kraft paper leads on momentum.
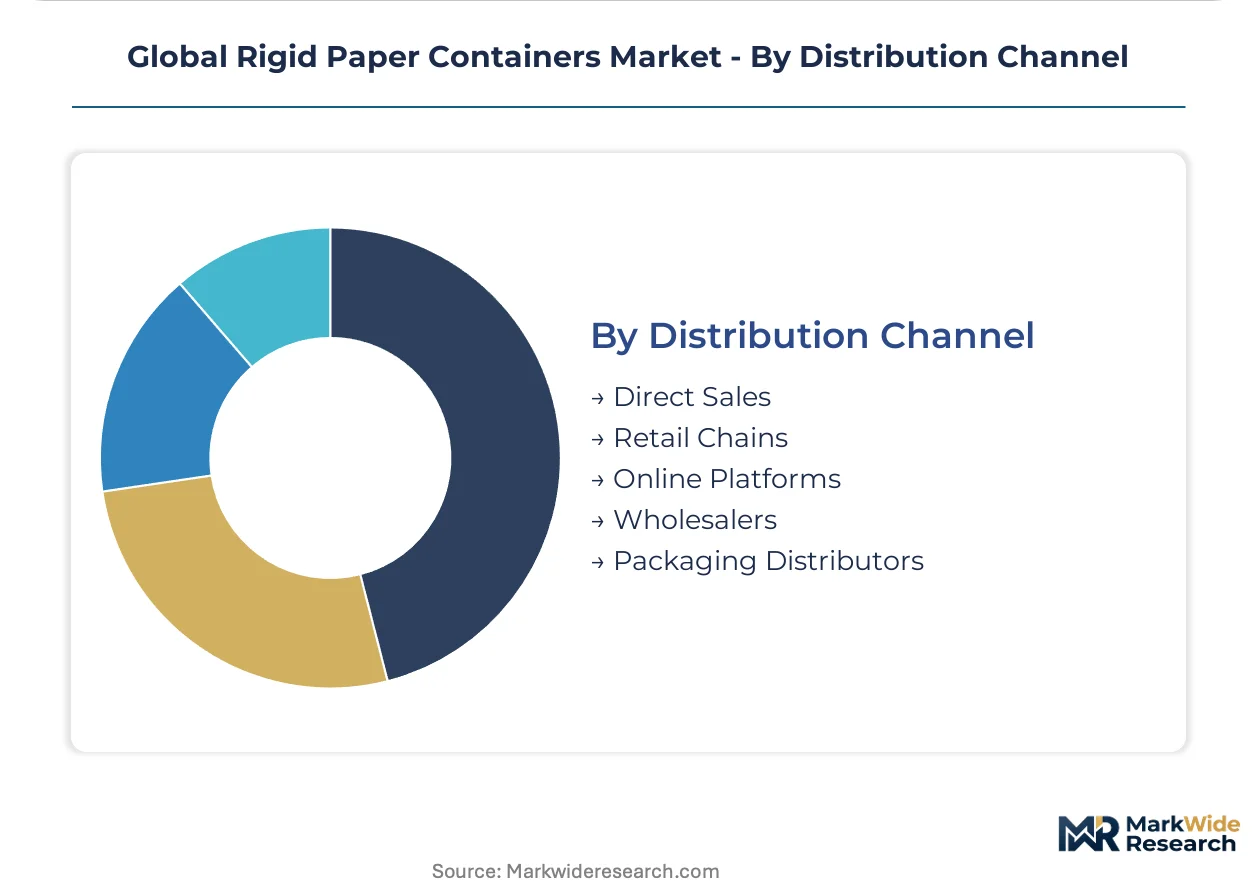
Distribution Channel:
Channel structure reflects buyer scale and specification complexity.
- Direct Sales:Converter-to-brand relationships for high-volume food and beverage accounts with customized barrier specifications. Procurement centralization at headquarters level compresses supplier bases for multinational accounts.
- Packaging Distributors:Inventory and technical service for mid-market converters lacking specification engineering resources. Regional manufacturing networks delegate volume allocation while retaining centralized authority.
- Retail Chains:Private-label packaging procurement through centralized buying offices.
- Online Platforms:E-commerce channels for standardized stock sizes and short-lead-time replenishment.
- Wholesalers:Bulk aggregation for smaller converters and regional food brands.
Direct sales leads on scale; packaging distributors leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany converts more barrier-coated folding carton volume than Brazil, yet India's domestic mill expansion is compressing import dependency faster than either European or Latin American sourcing shifts.
Germany
Dairy and prepared meal brands specify aqueous barrier coatings for refrigerated distribution at pilot scale. VerpackG extended producer responsibility frameworks create preferential shelf access for certified recyclable fiber packaging. Converting clusters in Baden-Württemberg and North Rhine-Westphalia absorb stranded plastic capacity into paperboard barrier-coating lines.
India
Multinational food brands scale domestic sourcing as BIS-compliant converting lines reduce import dependency. BIS packaging standards govern paperboard substrate specifications and barrier coating compliance. Gujarat and Maharashtra paperboard mills expand coated board capacity to serve South Asian manufacturing networks.
Brazil
ANVISA-aligned nutritional supplement brands displace plastic jars with barrier-coated paperboard tubes and composite cans. ANVISA regulates food contact materials and nutritional packaging safety standards. São Paulo and Rio Grande do Sul converting clusters scale spiral-wound composite container output for protein powder and vitamin categories.
United States
Quick-service restaurant chains adopt molded fiber clamshells and formed paper bowls across drive-thru and delivery formats. FDA food contact substance notifications govern barrier coating approvals with 120-day review cycles. Midwest dairy co-packers modify high-speed filling lines to accommodate paperboard rigidity tolerances.
China
Premium folding carton demand in cosmetics and electronics encounters import compliance complexity under GB/T paperboard specifications. GB/T standards shape substrate thickness and structural performance requirements. Yangtze River Delta converters develop local barrier coating capabilities to displace aluminum-laminated imports.
Global Rigid Paper Containers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across substrate grades and barrier performance tiers. The supplier base compresses around multinational food and beverage accounts as procurement centralization at headquarters level consolidates specification authority. Three archetypes dominate: integrated pulp-to-box operators with captive fiber supply, European corrugated and solid board specialists, and molded fiber formers serving quick-service restaurant chains. Competitive moves concentrate on backward integration into pulp assets and geographic expansion of barrier-coating line capacity.
Among North American integrated operators, International Paper and WestRock occupy positions defined by mill network scale and pulp-to-box vertical control. Smurfit Kova anchors the European specialist tier with corrugated and solid board expertise spanning continental converting assets. These three exemplify how fiber integration depth and regional regulatory alignment determine contract eligibility for consolidated multinational accounts.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Smurfit Kappa |
| Mondi Group |
| DS Smith |
| Sonoco Products Company |
| Amcor plc |
| Stora Enso |
| Huhtamäki Oyj |
| Others |
Cost & Logistics Intelligence
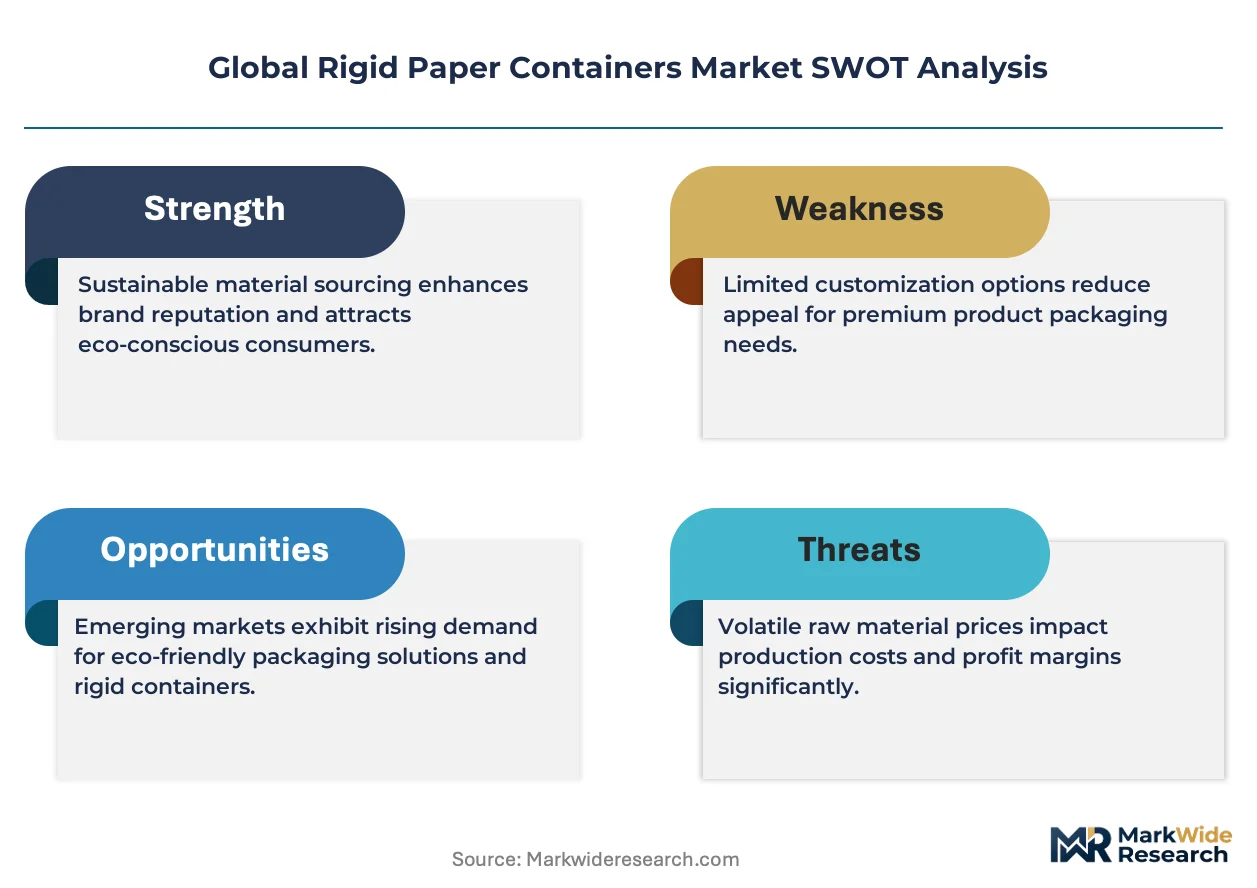
EU Green Deal packaging mandates gate qualified supply access and premium-tier pricing eligibility as converters absorb stranded plastic capacity into aqueous barrier-coating lines. Food and beverage multinationals now tie contract renewals to certified recyclability credentials, compressing the supplier base toward integrated operators with captive fiber supply.
Pricing Analysis
Capacity additions in India are reshaping price floors for coated paperboard across South Asian manufacturing networks. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified recyclable fiber from BIS-compliant domestic board and uncertified commodity grades. Cost compression in the standard tier is intensifying because Gujarat and Maharashtra mills expand output faster than brand specification upgrades. Private-label entrants exhibit highest price sensitivity; multinational accounts with centralized procurement show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, India, and Brazil anchor hub-and-spoke patterns for barrier-coated folding cartons and composite containers. Raw material supply draws from Scandinavian northern bleached softwood kraft, Canadian pulp exports, and domestic Indian hardwood fiber. Single-source vulnerability concentrates in aqueous barrier coating chemistry qualified for FDA food contact notifications. Distribution runs through converter-direct relationships for multinational accounts and packaging distributors for mid-market overflow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rigid paper container market reads as a late-cycle quality story where specification authority consolidates around aqueous barrier performance and certified recyclability credentials. Quick-service restaurant chains and nutritional supplement brands drive demand-shift toward premium molded fiber and composite formats.
For Market Incumbents: Extend aqueous barrier-coating line capacity in Germany and India to capture specification upgrades from dairy and prepared meal brands. Absorb stranded plastic capacity through equipment retrofits rather than greenfield investment. Defend against molded fiber specialists by qualifying silicone and clay-based oil-resistance coatings under REACH PFAS restrictions. For New Entrants and Emerging Players: The price-point gap between premium EU-certified and economy domestic board creates entry space for mid-tier converters with BIS or ANVISA alignment. Brazil's nutritional supplement segment offers the most penetrable white space for barrier-coated paperboard tubes displacing plastic jars. Lead with short-run digital printing capabilities to serve regional food brands without cylinder engraving lead times. For Investors and Strategic Acquirers: Valuations sit cheapest among European corrugated specialists lacking aqueous barrier-coating assets. Long-term viability hinges on backward integration into pulp supply and geographic expansion of certified recyclable fiber capacity. Watch FDA food contact substance notification approval timelines as the inflection indicator for novel coating chemistry adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Assets | Captive fiber supply insulates International Paper and WestRock from Nordic kraft price volatility. |
| Aqueous Barrier-Coating Line Expansion | Smurfit Kappa and Mondi Group qualify coatings for EU dairy refrigerated distribution mandates. |
| Digital Printing Convergence | Short-run variable data enables Huhtamäki Oyj to serve quick-service restaurant chain regional customization. |
| Certified Recyclability Credential Investment | Germany's VerpackG and France's AGEC law create preferential shelf access for compliant fiber packaging. |
| Geographic Manufacturing Footprint Expansion | Gujarat and Maharashtra converting clusters reduce import dependency for multinational food brands in India. |
Research Approach
Coverage spans Germany, India, Brazil, the United States, and China, with primary inputs from each market cluster. The analysis combines interviews with converter plant managers, brand procurement leads at multinational food and beverage companies, aqueous coating R&D directors, and regulatory affairs specialists with secondary validation from FDA food contact substance notification databases, EU ECHA REACH restriction filings, BIS packaging standard specifications, and customs trade data for paperboard substrate flows. Bottom-up mill capacity estimates triangulate against top-down brand procurement spend allocations.
Segmentation granularity models product type at the forming-technology level, end-use industry at the regulatory-compliance intensity tier, material at the barrier-performance grade, and distribution channel at the buyer-scale archetype. Value projections across the analysis window derive from unit volume forecasts multiplied by pricing stratification across premium-certified, standard-compliant, and economy-commodity tiers. CAGRs incorporate pulp price elasticity coefficients and barrier-coating adoption curves for oxygen-sensitive applications.
The model assumes a particular technology adoption path for aqueous polymer barrier coatings; alternative pathways for extruded polyethylene or aluminum lamination retention would alter the outlook for composite container displacement of plastic jars. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
US Rigid Thermoform Plastic Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market