
 Oxygen Barrier Films and Coatings for Dry Food Market | 2026-2036
Oxygen Barrier Films and Coatings for Dry Food Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Barrier Films and Coatings for Dry Food Market Analysis
Capital-intensity divergence between metallization specialists and commodity film converters is collapsing as coextrusion technology democratizes barrier performance. Amcor plc leverages its global converting footprint to integrate ethylene vinyl alcohol laminations at scale. Mondi Group anchors its position through kraft-paper barrier hybrids that satisfy retailer sustainability mandates. Sealed Air Corporation differentiates via vacuum skin lidding systems that extend oxygen protection for premium snack segments.
Oxygen barrier films and coatings for dry food are multilayer polymeric structures, typically incorporating ethylene vinyl alcohol copolymers or aluminum oxide vapor-deposited layers at thicknesses below 100 nanometers, engineered to maintain oxygen transmission rates below 1 cc/m²/day. These structures prevent lipid oxidation and vitamin degradation in shelf-stable packaged goods. Polyethylene dominates volume in standard snack bags where cost minimization outweighs premium barrier demands. Nylon occupies the fastest-growing tier in retortable instant meal pouches requiring thermal stability alongside oxygen resistance. PET sustains margin concentration in lidding applications for single-serve cereal trays where optical clarity and printability command price premiums.
FDA food contact substance notifications govern ethylene vinyl alcohol migration limits in US distribution, while EU REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of legacy grease-resistant barrier coatings. EFSA evaluates novel barrier polymers under updated food contact material guidelines that extend review timelines. Japan's Ministry of Health, Labour and Welfare maintains positive list requirements for food-contact layers that complicate import qualification. Stakeholders must monitor evolving substance restrictions across FDA, EFSA, and Asian regulators while pre-qualifying next-generation bio-based barrier chemistries ahead of compliance deadlines.
Market Dynamics
Coextrusion technology is collapsing the historical performance gap between commodity converters and metallization specialists, redistributing competitive advantage toward scale-efficient laminators capable of integrating ethylene vinyl alcohol barriers at throughput rates previously reserved for premium suppliers.
Growth Catalysts
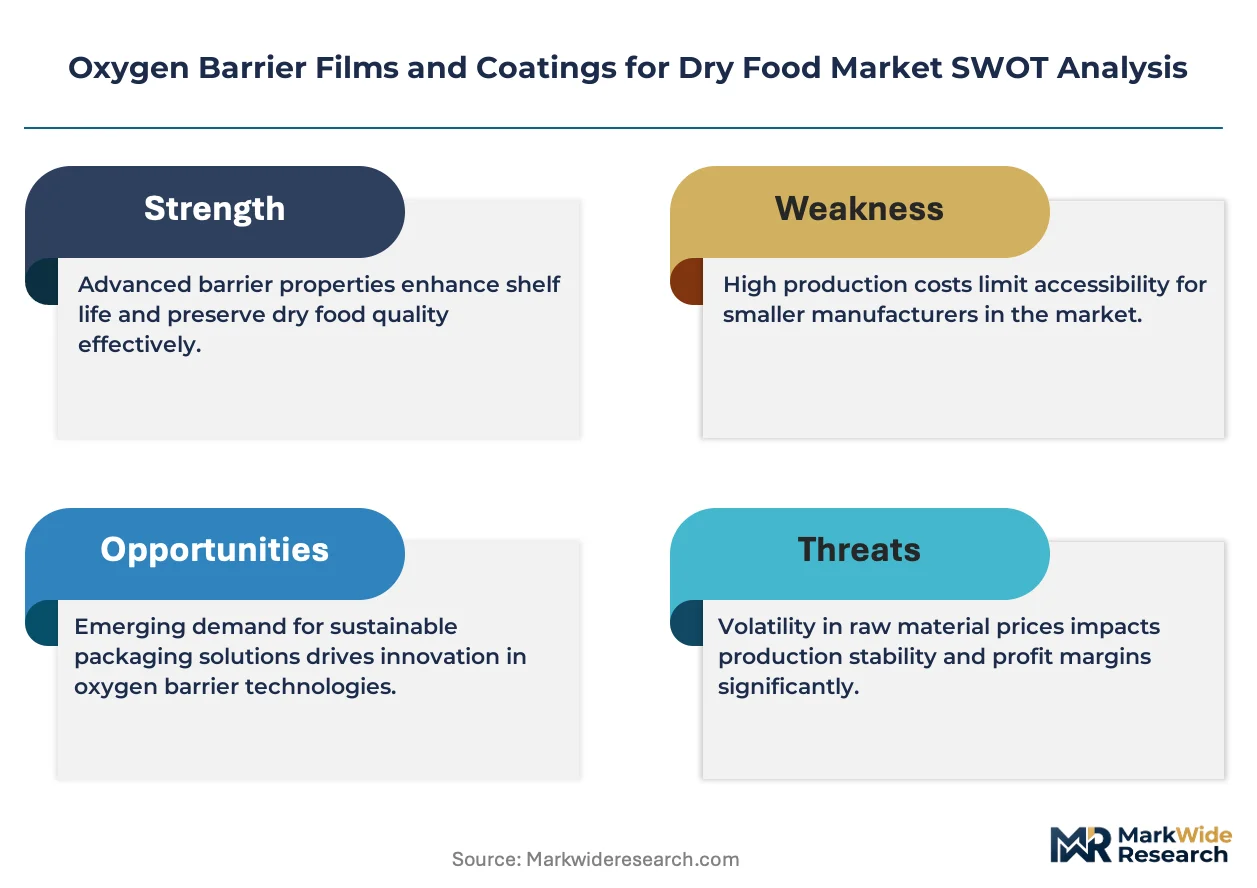
- EU Packaging and Packaging Waste Regulation:Revisions mandating extended producer responsibility are compelling snack manufacturers to adopt high-barrier pouches that eliminate preservatives while maintaining shelf stability.
- Centralized German retail distribution:Private-label expansion favors standardized barrier specifications that reduce SKU complexity and enable volume-based procurement consolidation.
- Ethylene vinyl alcohol copolymer lamination:Advances in multilayer coextrusion are extending oxygen transmission performance below 1 cc/m²/day at thicknesses that preserve material economics.
Market Restraints
- Aluminum oxide vapor deposition capacity:Vacuum metallization equipment requires capital intensity that concentrates supply among a limited base of specialized converters.
- Per- and polyfluoroalkyl substance restrictions:EU REACH limitations on legacy grease-resistant barrier coatings are forcing unplanned reformulation cycles before qualification timelines complete.
- Polyethylene feedstock volatility:Standard snack bag producers face margin compression when resin costs fluctuate against fixed-price retail contracts.
Strategic Opportunities
- Retortable instant meal pouches:Nylon-based oxygen barriers with thermal stability represent an underpenetrated application segment demanding coextrusion expertise.
- Kraft-paper barrier hybrids:Retailer sustainability mandates in Western Europe are creating specification windows for fiber-based structures with vapor-deposited oxide layers.
- Vacuum skin lidding systems:Premium snack segments require oxygen protection combined with optical clarity that PET lidding films deliver at price premiums.
Industry Challenges
- EFSA migration limit compliance:Extended review timelines for novel barrier polymers under updated food contact material guidelines delay product launches.
- Multilayer structure recyclability:Sorting infrastructure limitations complicate end-of-life processing for ethylene vinyl alcohol laminations in circular economy frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Barrier Films and Coatings for Dry Food Market |
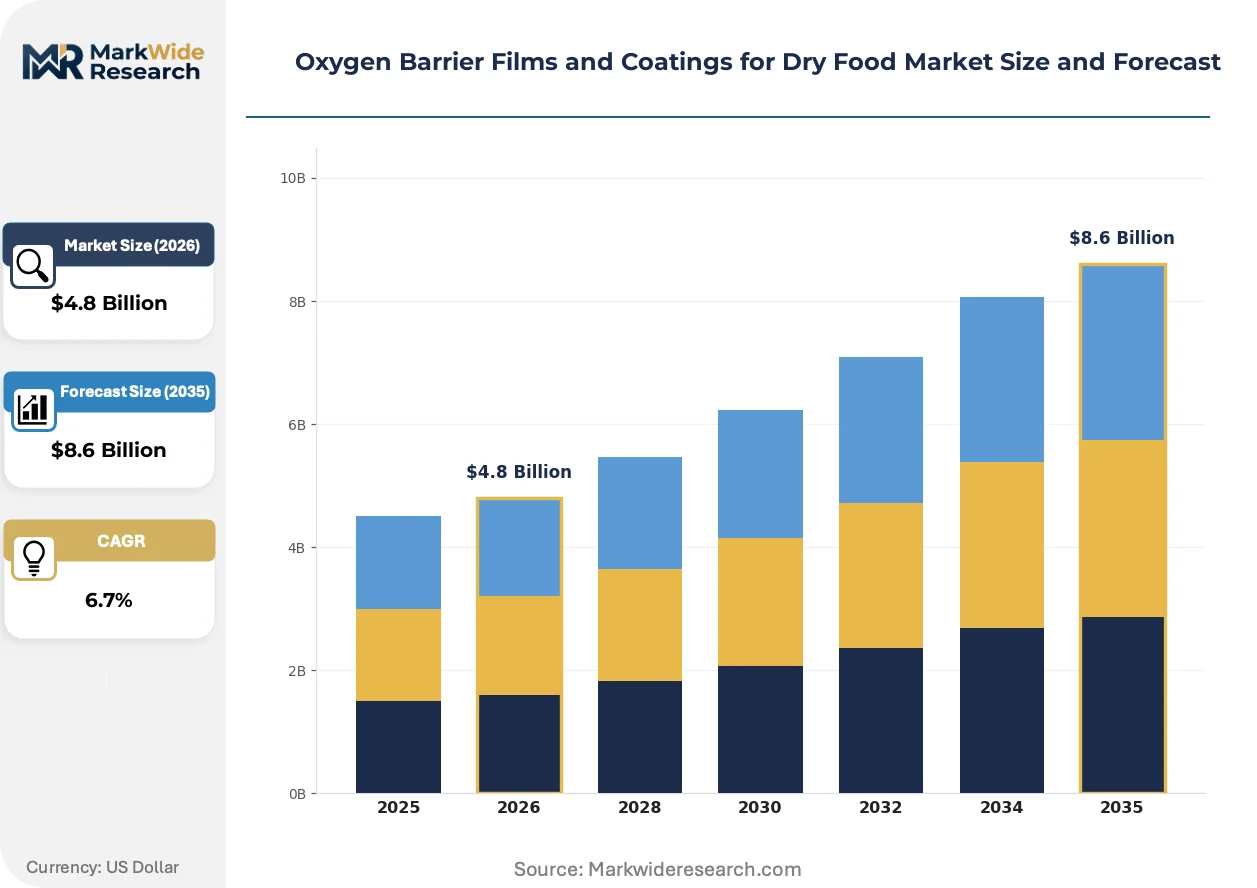
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, PET End Use Industry: Snacks, Cereals, Instant Meals, Pet Food Application: Pouches, Bags, Wrappings, Lidding Thickness: 50 µm, 100 µm, 150 µm, 200 µm |
| Companies Covered | Amcor plc, Mondi Group, Sealed Air Corporation, Toppan Inc., Toray Industries Inc., Mitsubishi Chemical Group Corporation, Avery Dennison Corporation, Berry Global Group Inc., DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Barrier Films and Coatings for Dry Food Market Emerging Trajectories
Barrier performance democratization is compressing the premium-commodity divide while regulatory substance restrictions and retailer sustainability specifications are rewriting material selection criteria across dry food packaging value chains.
Atomic layer deposition of aluminum oxide at sub-100 nanometer thicknesses is displacing conventional metallized polyethylene terephthalate in lidding applications where optical clarity and barrier precision converge. Premium cereal tray manufacturers are adopting these coatings to maintain printability while satisfying oxygen transmission specifications. The displacement is compressing incumbent vapor deposition equipment utilization rates among legacy suppliers.
EFSA updated food contact material guidelines are extending substance evaluation timelines for ethylene vinyl alcohol copolymers and novel bio-based barrier chemistries. European dry food importers face qualification delays that disrupt supply chain planning cycles. Multilayer converters are responding by pre-submitting notification packages ahead of formulation finalization.
Private-label procurement consolidation is compressing supplier qualification cycles as German centralized retailers standardize barrier specifications across snack and cereal portfolios. Volume commitments are replacing spot purchasing in polyethylene and nylon film categories. This concentration is most visible in Rhine-Ruhr distribution corridors serving discount retail networks.
Oxygen Barrier Films and Coatings for Dry Food Market Segmentation
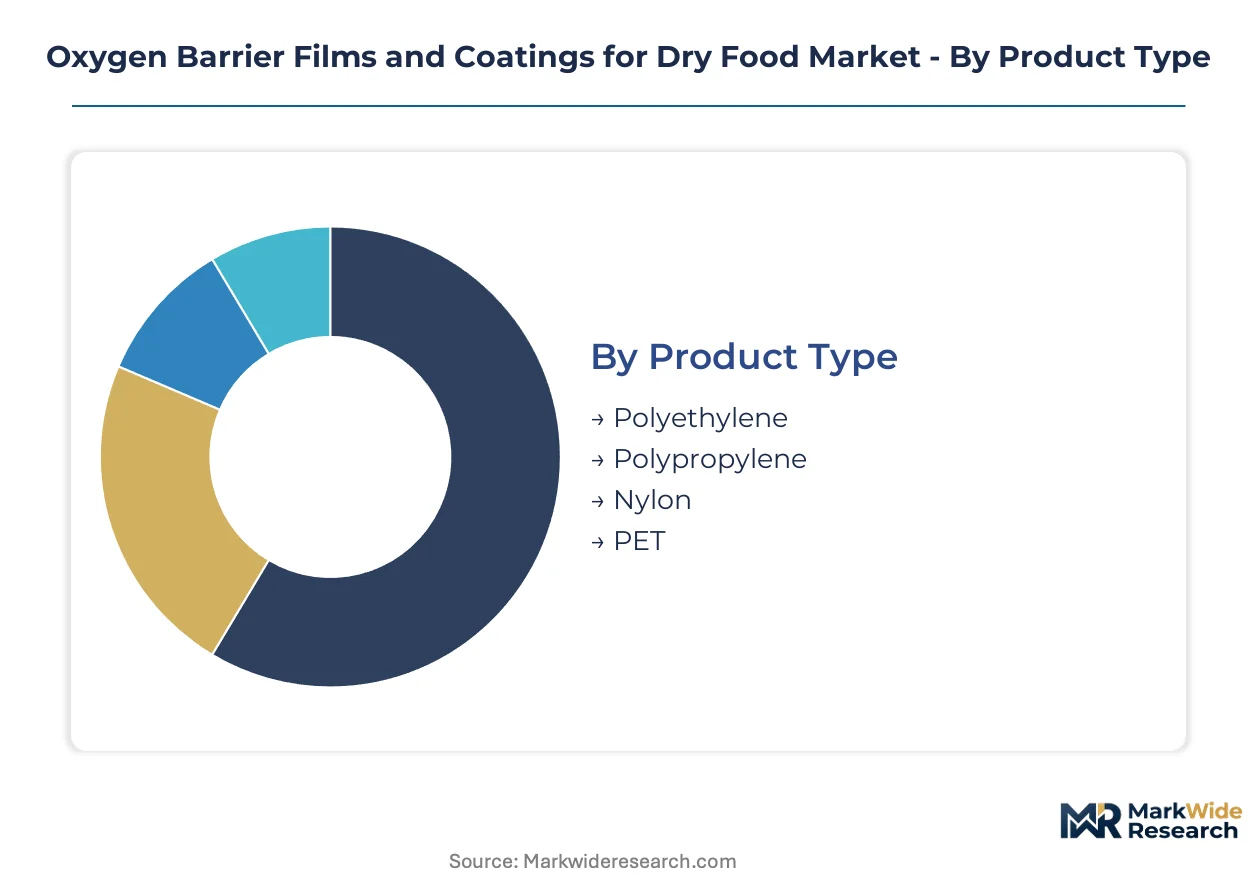
Segmentation in oxygen barrier films reveals how material selection, end-use requirements, and packaging formats intersect to determine technical specifications and procurement economics. Channel flows differ sharply between commodity snack converters seeking cost-optimized polyethylene and premium cereal manufacturers demanding optical-grade PET lidding.
Product Type:
Channel distribution varies by resin chemistry: polyethylene and polypropylene dominate high-volume snack bag supply chains to discount retailers, while nylon and PET concentrate in specialized laminators serving premium private-label programs.
- Polyethylene:Linear low-density formulations with ethylene vinyl alcohol coextrusion achieve oxygen transmission rates below 1 cc/m²/day at sub-100 micron gauges. German discount retail networks standardize on these specifications for private-label snack portfolios where cost minimization outweighs premium barrier demands.
- Nylon:Biaxially oriented polyamide structures deliver thermal stability essential for retortable instant meal pouches requiring oxygen resistance through sterilization cycles. Demand is concentrating in Japanese convenience food supply chains where shelf-stable prepared meals command premium positioning.
- Polypropylene:Cast and oriented films provide moisture barrier synergy with moderate oxygen protection for dry cereal inner liners. BOPP metallization lines serve European co-packing facilities.
- PET:Optical clarity and printability sustain margin concentration in lidding applications for single-serve cereal trays. Vapor-deposited aluminum oxide variants displace conventional metallization in premium segments.
Polyethylene dominates installed base. Nylon is where expansion concentrates.
End Use Industry:
Application-driven specification tiers separate preservative-free shelf-life extension in snacks from vitamin degradation prevention in fortified cereals.
- Snacks:High-barrier pouches eliminate synthetic preservatives while maintaining 9-12 month shelf stability for potato chips and extruded products. EU Packaging and Packaging Waste Regulation revisions are compelling adoption across Rhine-Ruhr distribution corridors.
- Cereals:Vitamin A and E degradation prevention requires oxygen transmission rates sustained below 0.5 cc/m²/day through distribution cycles. Fortified product lines in US Midwest manufacturing clusters drive specification stringency.
- Instant Meals:Retort compatibility demands thermal stability alongside oxygen barrier performance. Asian convenience food processors represent emerging specification influence.
- Pet Food:Fat oxidation prevention in premium kibble and treat segments sustains niche barrier requirements. North American specialty pet food co-packers specify multilayer structures.
Snacks command volume leadership. Cereals exhibit steepest expansion trajectory.
Application:
Format selection determines barrier layer placement: pouches integrate coextruded walls, lidding demands single-surface coating precision, bags balance throughput economics with seal integrity.
- Pouches:Stand-up and flat pouch geometries incorporate ethylene vinyl alcohol laminations at 3-5 layer counts. German centralized retail procurement is consolidating specifications across private-label snack and cereal portfolios.
- Bags:Vertical form-fill-seal compatibility drives polyethylene-dominant structures with metallized film windows. High-speed converting lines in Benelux packaging clusters favor standardized barrier grades.
- Wrappings:Flow-wrap applications for bakery and confectionery items require heat-sealable barrier layers with twist retention. Southern European specialty food processors sustain regional specification diversity.
- Lidding:PET and oriented polyamide films with aluminum oxide vapor deposition deliver optical clarity for tray visibility. Premium snack segments in Japanese retail channels specify vacuum skin lidding systems.
Bags hold production volume leadership. Pouches are gaining share fastest.
Thickness:
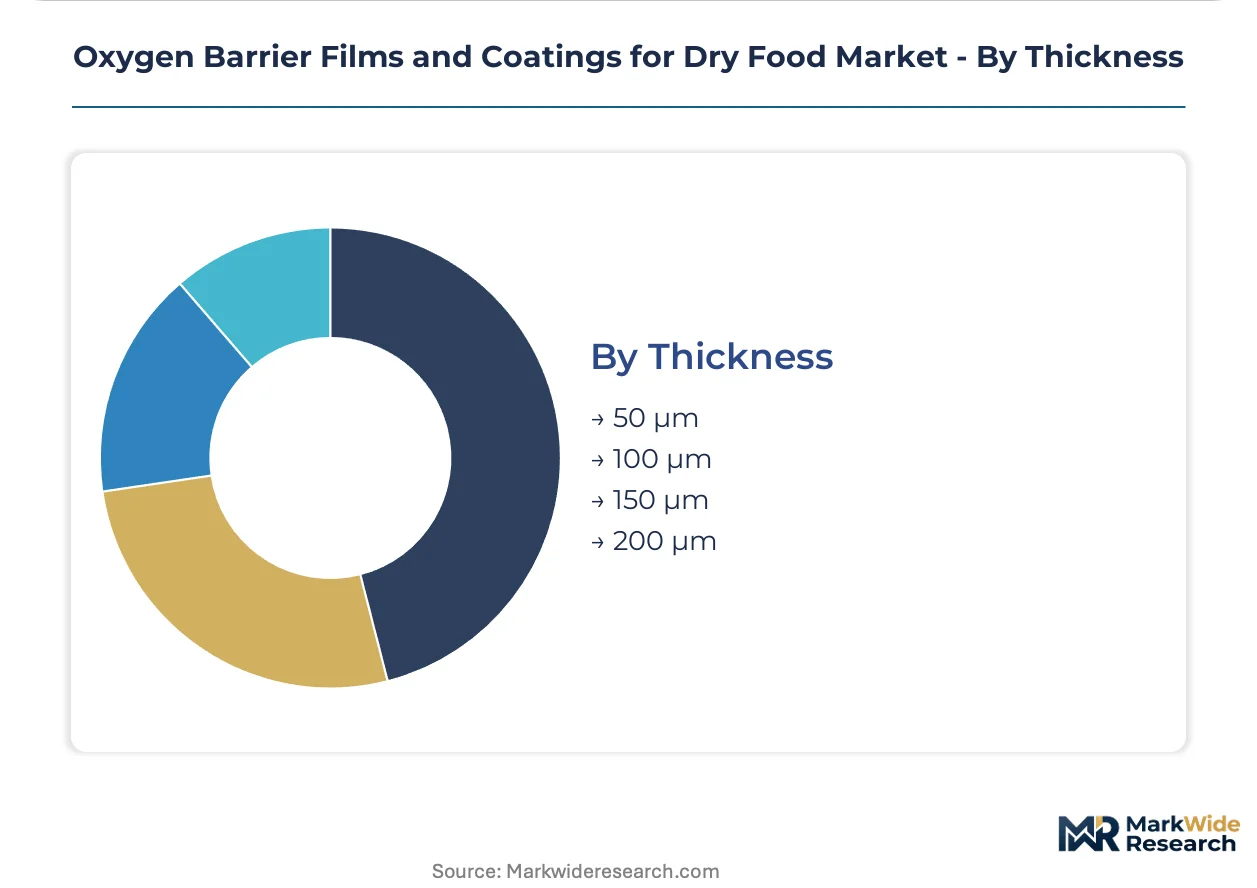
Gauge selection reflects the tension between material economics and barrier performance: thinner specifications reduce resin consumption but demand more precise layer distribution.
- 50 µm:Ultra-thin coextrusions with concentrated ethylene vinyl alcohol core layers achieve barrier performance at material minima. Japanese precision converting technology enables specification adoption.
- 100 µm:Standard snack bag gauges balance throughput efficiency with seal integrity across high-speed form-fill-seal operations. German discount retail supply chains standardize on this specification tier.
- 150 µm:Intermediate gauges serve retortable applications where thermal stress demands structural robustness. Asian instant meal processors specify this range.
- 200 µm:Heavy-gauge structures support vacuum skin lidding and deep-draw thermoforming for premium protein and cheese applications. North American specialty food packaging sustains limited demand.
100 µm commands mainstream volume. 50 µm represents the frontier of material reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity as centralized retail procurement consolidates specifications, while snack converters in India face acute cost pressure where polyethylene dominates and barrier premiums erode margins.
Germany
Private-label expansion across Aldi and Lidl networks drives specification standardization for high-barrier pouches. EFSA migration limits and EU Packaging and Packaging Waste Regulation revisions enforce compliance rigor for multilayer structures. The Rhine-Ruhr corridor concentrates converting capacity serving discount retail distribution.
United States
Fortified cereal manufacturers in the Midwest demand oxygen transmission rates below 0.5 cc/m²/day to prevent vitamin degradation. FDA food contact substance notifications govern ethylene vinyl alcohol migration limits in interstate commerce. Chicago-area packaging clusters specialize in retort-compatible barrier laminations for instant meal processors.
Japan
Convenience food processors specify thermal-stable nylon barriers for shelf-stable prepared meals commanding premium positioning. METI and the Ministry of Health, Labour and Welfare maintain positive list requirements for food-contact layers complicating import qualification. The Kanto region around Tokyo anchors precision converting technology for ultra-thin 50 µm coextrusions.
China
Domestic snack brands accelerate adoption of ethylene vinyl alcohol laminations as preservative-free positioning gains consumer traction. SAMR and GB standards regulate food-contact material safety with increasing stringency. The Yangtze River Delta manufacturing belt hosts expanding metallization capacity for vapor-deposited aluminum oxide films.
India
Price-sensitive snack producers prioritize cost-optimized polyethylene structures over premium barrier tiers. FSSAI food safety regulations govern plastic food contact materials with evolving enforcement capacity. Gujarat and Maharashtra industrial corridors concentrate commodity film extrusion serving domestic FMCG distribution.
Oxygen Barrier Films and Coatings for Dry Food Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in oxygen barrier films for dry food. The upper tier commands multilayer coextrusion scale and direct retailer relationships, while specialists focus on vapor deposition precision or regional converting density. Three archetypes define positioning: metallization specialists with vacuum equipment depth, commodity converters leveraging coextrusion democratization, and hybrid players integrating paper-based sustainability credentials. Competitive intensity centers on capacity expansion in ethylene vinyl alcohol lamination lines and strategic partnerships locking in private-label volume commitments.
Within the integrated multinational tier, Amcor plc and Mondi Group exemplify scale-driven positioning across converting footprints. Amcor anchors global lamination capacity integration, while Mondi occupies a distinctive position in kraft-paper barrier hybrids responding to Western European retailer sustainability mandates. Sealed Air Corporation represents the specialized systems archetype, with vacuum skin lidding expertise targeting premium snack protection requirements.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Sealed Air Corporation |
| Toppan Inc. |
| Toray Industries Inc. |
| Mitsubishi Chemical Group Corporation |
| Avery Dennison Corporation |
| Berry Global Group Inc. |
| DuPont de Nemours Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German discount retailers and polyethylene converters lock in ethylene vinyl alcohol lamination capacity while stripping price volatility from quarterly procurement cycles. These contracts embed volume commitments that shield snack manufacturers from resin cost swings but compress converter margins when feedstock spikes.
Pricing Analysis
After-sales technical service contracts for multilayer coextrusion line maintenance drive lifetime value for equipment suppliers serving barrier film converters. Three-tier pricing structure across premium, standard, and economy levels separates vapor-deposited aluminum oxide lidding from metallized polyethylene terephthalate and commodity polyethylene snack bags. Cost compression in standard snack bag tiers is intensifying because private-label procurement consolidation forces converters to absorb resin volatility. Indian snack producers exhibit acute price sensitivity, while German centralized retailers demonstrate lowest elasticity due to specification standardization.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates inbound logistics costs for ethylene vinyl alcohol resin shipments from Japanese and South Korean polymer plants. Raw material supply concentrates in China, Germany, and the United States, with converters drawing from polyethylene feedstock clusters, metallization equipment manufacturers, and vapor deposition coating specialists. Single-source vulnerability in vacuum metallization equipment creates chokepoint risk for aluminum oxide barrier production. Distribution runs through co-packing facilities serving discount retail networks in the Rhine-Ruhr corridor and Midwest US cereal manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by EU Packaging and Packaging Waste Regulation compliance investment cycles that compressed converter margins ahead of specification upgrades.
For Market Incumbents: Shield ethylene vinyl alcohol lamination capacity through backward integration into resin compounding or exclusive offtake arrangements with polymer suppliers. Coextrusion technology democratization threatens metallization specialists with margin erosion; defend by locking in private-label volume commitments with German centralized retailers before qualification cycles complete. For New Entrants and Emerging Players: Lead with kraft-paper barrier hybrids targeting Western European retailer sustainability mandates where incumbent converters lack fiber-based production assets. Retortable instant meal pouches in Asian convenience food supply chains represent the most penetrable application segment. Pursue joint development agreements with Japanese precision converting technology licensors to shortcut qualification timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scale-efficient laminators with direct retailer relationships over specialized metallization equipment owners. Five-to-ten year viability hinges on circular economy infrastructure development for multilayer recyclability. Watch EFSA migration limit enforcement intensity as the inflection signal for bio-based barrier chemistry substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Vinyl Alcohol Resin Compounding | Captive supply of barrier polymer secures margin control against commodity resin volatility. |
| Kraft-Paper Barrier Hybrid Production Scale-Up | Mondi Group's positioning demonstrates retailer sustainability mandate compliance drives specification wins. |
| Vacuum Skin Lidding Systems Partnership | Sealed Air Corporation's premium snack protection expertise commands price premiums in Japanese retail channels. |
| Long-Term Supply Agreement with German Centralized Retailers | Aldi and Lidl volume commitments replace spot purchasing and compress competitor qualification windows. |
| Joint Venture for Retortable Nylon Barrier Coextrusion | Asian convenience food processor demand for thermal-stable sterilization compatibility creates capacity scarcity. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with multilayer film plant managers, snack manufacturer procurement leads, retailer category buyers, and food packaging R&D directors; and secondary validation through FDA food contact substance notifications, EFSA food contact material guidelines, EU Packaging and Packaging Waste Regulation revision documents, and customs trade data for ethylene vinyl alcohol resin shipments. Bottom-up capacity modeling across converting facilities triangulated against top-down demand estimates from snack and cereal production volumes.
Across the analysis window, the forecasting framework modeled segmentation dimensions including resin chemistry tier, end-use application, packaging format, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating substitution dynamics between metallized and coextruded barrier technologies. Forecast inputs included ethylene vinyl alcohol lamination line capacity expansion announcements and private-label procurement consolidation patterns in German retail.
The analysis sits within stated boundaries; outcomes outside EFSA migration limit enforcement timelines, EU circular economy infrastructure deployment, or polyethylene feedstock cost trajectories would require recalibration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Global Stretch and Shrink Film Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
Pipe Insulation Film Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market