
 Insulation Film Market | 2026-2036
Insulation Film Market Size, Share, and Industry Trends Forecast 2026-2036
Insulation Film Market Insights
Buyer concentration among electric vehicle OEMs and tier-one battery suppliers is restructuring procurement volumes for high-temperature insulation films. 3M Company leverages its fluoropolymer expertise to anchor premium thermal management contracts with automotive platforms. DuPont de Nemours, Inc. sustains polyimide film leadership through captive Kapton manufacturing and aerospace qualification pipelines. Saint-Gobain competes across glass-film laminates for building envelope applications where fire-rated assemblies command specification loyalty.
Insulation film comprises thin polymer substrates engineered with controlled dielectric strength, thermal resistance, and mechanical flexibility for electrical isolation and energy conservation. Polyethylene and polypropylene formulations dominate volume production for wire-and-cable wrapping and consumer goods packaging where cost thresholds govern selection. PET films occupy higher-margin electronics segments requiring dimensional stability under solder-reflow temperatures, while PVC grades face substitution pressure in construction amid halogen-free regulatory mandates. Application splits reveal automotive thermal barriers as the fastest-expanding consumption pool, though construction retrofit demand for reflective insulation retains steady replacement-cycle revenue.
The EPA oversees VOC emissions from solvent-based coating processes used in film manufacturing, pushing converters toward waterborne or hot-melt adhesive systems. REACH restrictions on phthalate plasticizers and halogenated flame retardants reshape PVC formulation strategies across European supply chains. China's GB standards and MIIT energy-efficiency directives enforce minimum thermal performance ratings for building materials and electric vehicle components. Stakeholders must monitor evolving UL 94 flammability classifications and regional carbon-border adjustments that threaten non-compliant import flows.
Market Dynamics
Cell chemistry advances in electric vehicle battery packs are compressing thermal runaway tolerance windows, forcing converters to engineer multilayer barrier films with nanoscale ceramic coatings that can withstand cascading failure temperatures exceeding 800°C.
Growth Catalysts
- MIIT Energy-Efficiency Directives:China's mandatory thermal performance ratings for building envelopes and EV components are pulling domestic converter capacity expansion and localized supply chain investment.
- Fluoropolymer Film Adoption:Battery pack manufacturers are specifying PTFE and FEP substrates for their dielectric stability across extreme temperature cycling in high-nickel cathode configurations.
- Construction Retrofit Cycles:European building stock renovation mandates under the EU Green Deal are sustaining reflective insulation film replacement demand across residential and commercial envelopes.
Market Restraints
- Specialized Polymer Feedstock Concentration:High-purity polyimide dianhydride and diamine precursors concentrate among Japanese and Korean chemical suppliers, exposing converters to allocation risk during semiconductor demand surges.
- REACH Phthalate Restrictions:ECHA's evolving candidate list for SVHCs is forcing PVC film reformulation, raising compound development costs and extending qualification timelines for construction applications.
- Halogen-Free Substitution Pressure:Brominated flame retardants face displacement by phosphorus-nitrogen systems in electronics-grade films, requiring capital-intensive extrusion line reconfiguration.
Strategic Opportunities
- Solid-State Battery Thermal Interfaces:Next-generation cell architectures with sulfide or oxide electrolytes demand compression-resistant ceramic-polymer hybrid films that current suppliers have not scaled.
- India PLI Scheme Alignment:Domestic cell and module manufacturing incentives are creating first-mover advantage for insulation film converters establishing local lamination and slitting operations.
- Waterborne Coating Conversion:EPA VOC enforcement is accelerating demand for aqueous adhesive systems in North American film manufacturing, rewarding early equipment adopters with regulatory compliance premiums.
Industry Challenges
- Polymer Scientist Talent Scarcity:Formulation expertise combining dielectric physics with high-temperature rheology concentrates among aging specialists at legacy aerospace suppliers, constraining R&D velocity at mid-tier converters.
- UL 94 Requalification Burden:Five-year recertification cycles for V-0 flame ratings demand continuous testing expenditure, particularly burdensome for smaller film processors serving fragmented building products distributors.
- Multi-Site Quality Harmonization:Battery OEMs are auditing film suppliers across geographically dispersed coating and metallization facilities, exposing variance in thickness tolerance control that threatens platform qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulation Film Market |
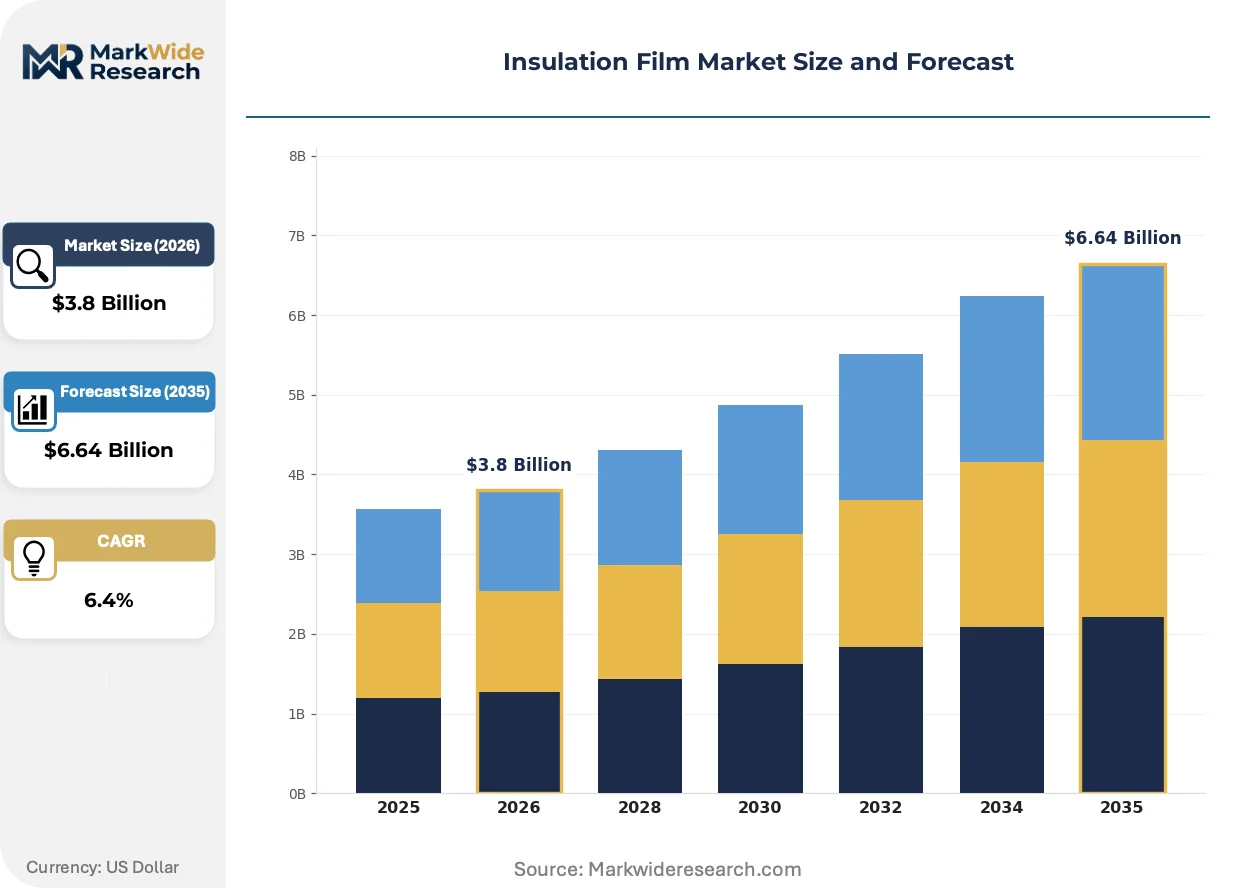
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Electronics, Automotive, Construction, Packaging End User: Manufacturers, Contractors, Retailers, Distributors Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | 3M Company, Eastman Chemical Company, Saint-Gobain, Avery Dennison Corporation, Toray Industries Inc., DuPont de Nemours, Inc., Garware Hi-Tech Films Ltd., Madico Inc., Kaneka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulation Film Market Trends and Innovations
Material science breakthroughs are fragmenting the insulation film value chain, with specialized converters capturing margin from commodity resin producers by embedding functional coatings that deliver application-specific performance certificates.
Atomic layer deposition of alumina and silica barrier layers is decentralizing the manufacturing of ultra-thin thermal protection films. Tier-one battery suppliers in South Korea and China are qualifying ALD-coated PET and PEN substrates for cell-to-pack architectures. This nanoscale coating capability is decentralizing film sourcing decisions from resin producers to equipment-integrated converters who control barrier precision.
REACH restrictions on per- and polyfluoroalkyl substances are compressing the addressable market for PTFE-based films in European construction and electronics applications. ECHA's proposed PFAS restriction is forcing formulators to validate silicone and ceramic-filled polyimide alternatives through accelerated aging protocols. Building envelope specifiers in Germany and France are already substituting glass-film laminates for fluoropolymer membranes in fire-rated assemblies.
Specification consolidation among EV platform engineers is collapsing the number of qualified film suppliers per battery program. Procurement teams at major automotive OEMs are reducing approved vendor lists from twelve to three converters per thermal barrier category, replacing spot-buying with multi-year volume commitments. This concentration is most visible in China's Yangtze River Delta cell manufacturing cluster, where CATL and BYD procurement offices co-locate technical auditors with converter R&D facilities.
Insulation Film Market Segmentation
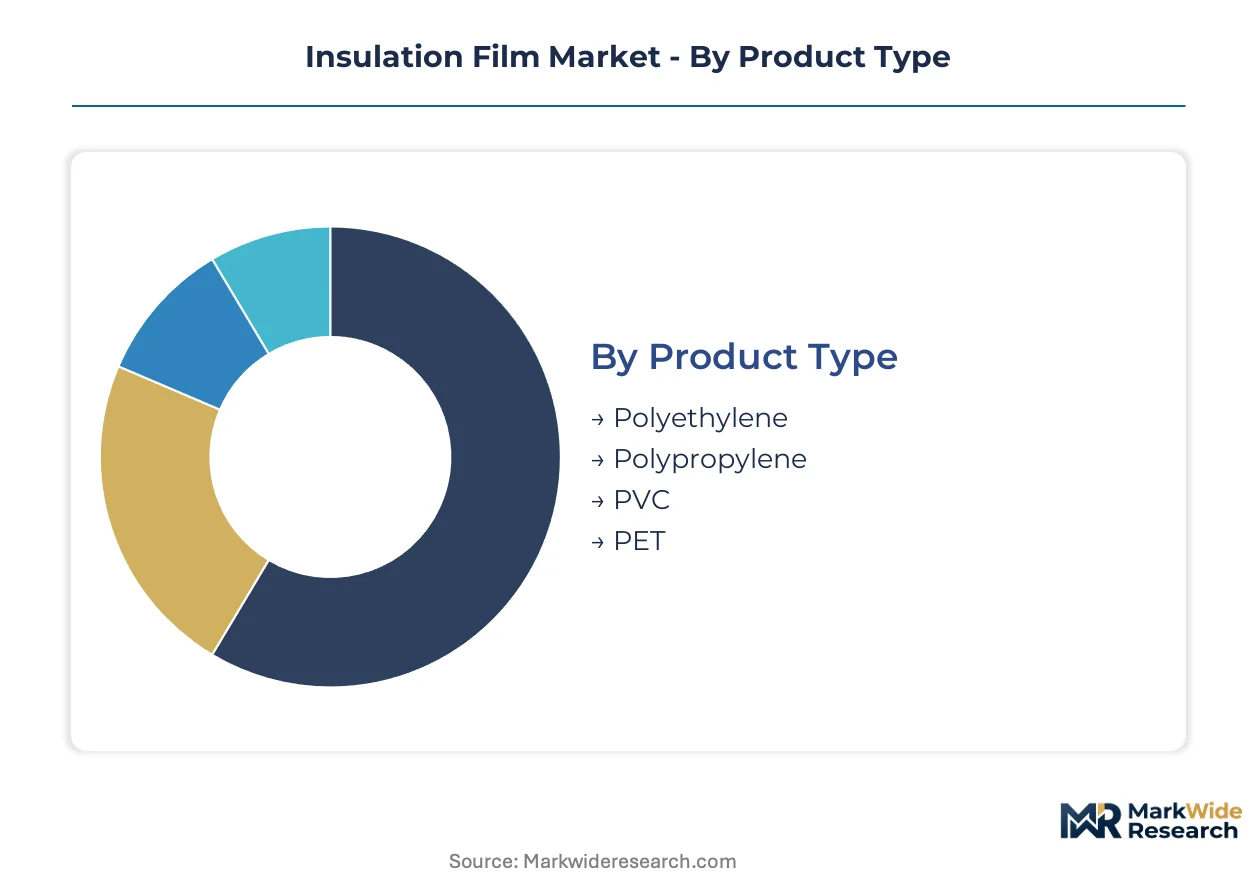
Insulation film procurement splits sharply between commodity resin grades and engineered substrates with functional coatings. Converter margins depend on matching polymer chemistry to thermal and dielectric specifications demanded by battery OEMs and building envelope contractors.
Product Type:
Polyethylene and polypropylene dominate tonnage shipments, while fluoropolymer and polyimide films capture premium pricing in electric vehicle thermal barriers.
- Polyethylene:Low-density formulations serve wire-and-cable wrapping and consumer goods packaging where cost thresholds govern selection. Demand concentrates in China's Yangtze River Delta manufacturing cluster as domestic converter capacity expands alongside electric vehicle output.
- Polypropylene:Biaxially oriented grades deliver dielectric stability for capacitor films and battery separator substrates. South Korean and Japanese chemical suppliers control high-purity precursor allocation, exposing converters to semiconductor demand surges.
- PVC:Flexible calendered grades face substitution pressure in construction amid REACH halogen-free mandates and ECHA phthalate restrictions.
- PET:Dimensional stability under solder-reflow temperatures positions this segment for electronics laminates and reflective insulation retrofits.
Today's leader: Polyethylene. Tomorrow's challenger: PET.
Application:
Automotive thermal barriers are climbing the fastest, though construction retrofit demand retains steady replacement-cycle revenue across European building stock renovation mandates.
- Electronics:PET and PEN substrates with atomic layer deposition coatings serve cell-to-pack battery architectures requiring nanoscale barrier precision.
- Automotive:Multilayer barrier films with ceramic coatings withstand cascading failure temperatures exceeding 800°C in high-nickel cathode configurations. Procurement teams at CATL and BYD are reducing approved vendor lists from twelve to three converters per thermal barrier category.
- Construction:Reflective insulation films for building envelopes command specification loyalty where fire-rated assemblies dominate. EU Green Deal renovation mandates sustain replacement demand across Germany and France.
- Packaging:Polyethylene formulations for consumer goods face margin compression from bio-based film alternatives.
Automotive applications show steepest expansion trajectory. Construction maintains defensive revenue stability.
End User:
Manufacturer procurement concentrates volume among tier-one battery suppliers, while contractor purchasing fragments across regional building products distributors.
- Manufacturers:Electric vehicle battery pack OEMs and tier-one cell suppliers drive qualification-intensive procurement with multi-year volume commitments replacing spot-buying.
- Contractors:Building envelope installers specify fire-rated glass-film laminates under German and French regulatory pressure against fluoropolymer membranes.
- Retailers:Consumer goods packaging demand flows through big-box distributors with limited technical specification involvement.
- Distributors:Regional film processors serving fragmented construction markets face UL 94 recertification burdens on five-year cycles.
Manufacturers pull supply chain investment. Distributors absorb compliance cost pressure.
Thickness:
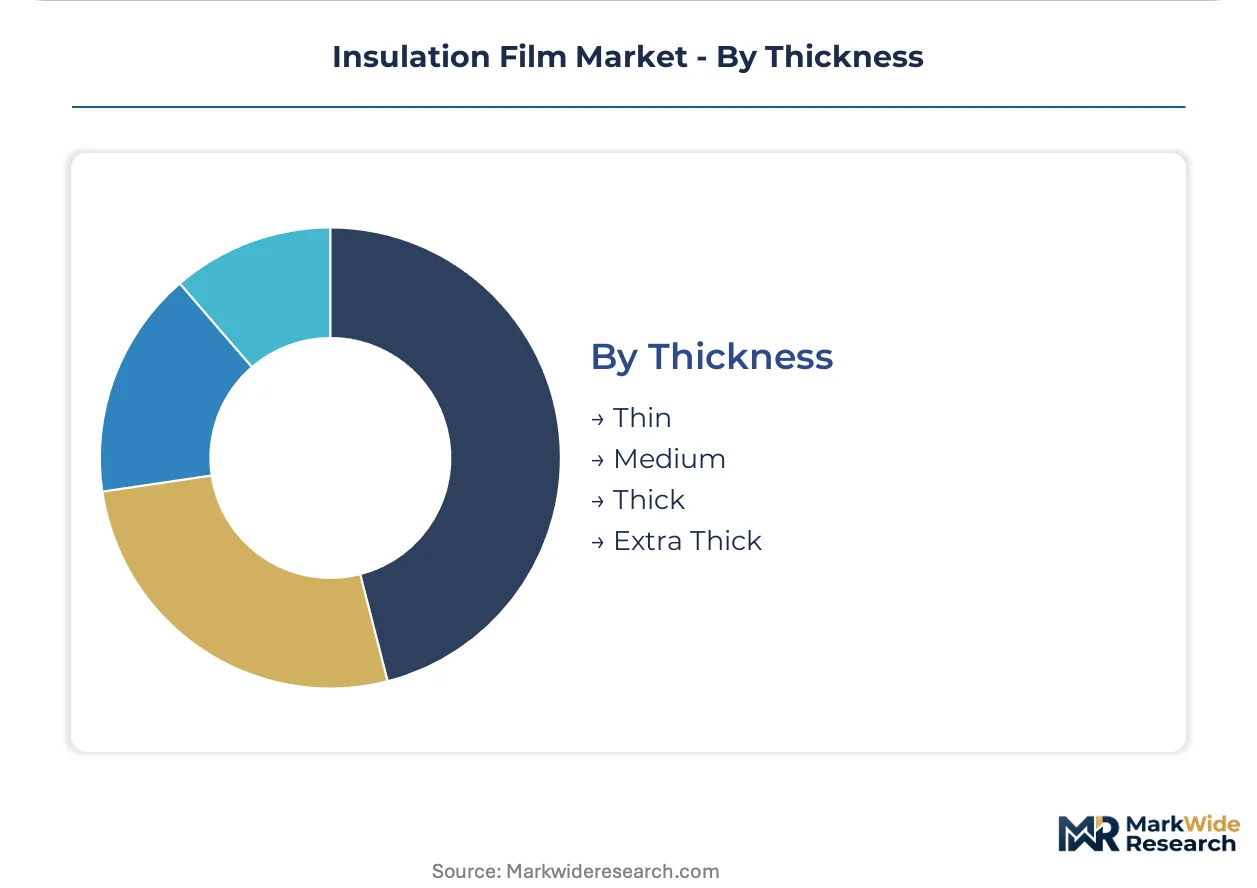
Thin films enable layer stacking in compact battery architectures, while extra-thick grades serve industrial equipment insulation with less stringent space constraints.
- Thin:Sub-25 micron PET and polyimide films with ALD alumina barrier layers decentralize sourcing decisions from resin producers to equipment-integrated converters.
- Medium:Standard gauge polyethylene and polypropylene grades balance mechanical durability with processing efficiency for wire wrapping applications.
- Thick:Calendered PVC and composite laminates for building envelope assemblies where thermal resistance ratings dictate minimum material mass.
- Extra Thick:Industrial-grade fluoropolymer and silicone composites for high-voltage equipment requiring compression-resistant ceramic-polymer hybrid structures.
Thin films gain share in battery platforms. Extra-thick grades defend industrial niche positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer scientist talent pools concentrate in legacy aerospace and chemical clusters, anchoring insulation film innovation in three dominant manufacturing geographies. Converter capacity expansion follows electric vehicle battery assembly localization, with regulatory pressure on halogen-free formulations accelerating regional specialization.
China
CATL and BYD procurement offices in the Yangtze River Delta drive thermal barrier film demand as cell energy densities rise. MIIT energy-efficiency directives enforce minimum thermal performance ratings for building envelopes and EV components. Converter R&D facilities in Suzhou and Ningbo co-locate with technical auditors from tier-one battery suppliers, compressing qualification timelines.
Germany
Automotive OEM thermal management engineering teams specify multilayer ceramic-coated films for high-nickel cathode configurations. ECHA's REACH restrictions on PFAS and phthalate plasticizers force PVC reformulation across European supply chains. Industrial clusters in Baden-Württemberg and Bavaria host film converters serving fire-rated building envelope assemblies under EU Green Deal renovation mandates.
United States
Battery pack manufacturers scale orders for fluoropolymer substrates as solid-state cell architectures advance. EPA VOC enforcement pushes converters toward waterborne adhesive systems in film manufacturing. The Southeast manufacturing corridor attracts lamination and slitting operations seeking proximity to Tesla and SK Innovation cell plants.
Japan
High-purity polyimide dianhydride and diamine precursor suppliers concentrate among Osaka and Tokyo chemical producers, exposing converters to allocation risk during semiconductor demand surges. METI industrial standards govern dielectric strength specifications for electronics-grade films. Toray Industries anchors domestic capacity for biaxially oriented polypropylene capacitor films.
South Korea
LG Energy Solution and Samsung SDI procurement teams qualify ALD-coated PET and PEN substrates for cell-to-pack architectures. MFDS chemical safety assessments intersect with automotive OEM material approval processes. The Gyeonggi-do battery manufacturing cluster pulls converter technical support centers from Japanese and Chinese suppliers.
Insulation Film Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the insulation film value chain, creating a tiered structure where captive resin production confers cost advantage. Three strategic archetypes dominate: integrated chemical-resin-to-film producers, equipment-integrated coating specialists, and regional converter-slitter operations. Competitive moves concentrate on M&A for coating technology access and capacity expansion near battery assembly clusters.
Among diversified materials conglomerates, 3M Company and DuPont de Nemours, Inc. occupy positions representing fluoropolymer and polyimide expertise archetypes. Saint-Gobain exemplifies the building envelope specialization vector. These three anchors sit within the premium-tier supplier category where aerospace qualification pipelines and automotive thermal management contracts intersect.
| Leading Market Players |
|---|
| 3M Company |
| Eastman Chemical Company |
| Saint-Gobain |
| Avery Dennison Corporation |
| Toray Industries Inc. |
| DuPont de Nemours, Inc. |
| Garware Hi-Tech Films Ltd. |
| Madico Inc. |
| Kaneka Corporation |
| Others |
Pricing and Supply Chain Analysis
Performance-grade bifurcation between aerospace-qualified polyimide films and commodity polyethylene wraps manifests in divergent pricing power and supply chain architectures. Premium thermal barrier contracts anchor to multi-year automotive platform commitments with dielectric certification premiums, while construction-grade PVC and PE volumes trade on spot resin indices with thin converter margins.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-gauge polyethylene and polypropylene films. Three-tier pricing structure across premium fluoropolymer, standard PET, and economy PE levels stratifies by UL 94 certification grade and volume scale. Cost compression in commodity grades intensifies as domestic converter capacity expands, while battery OEM procurement teams show least price sensitivity for ceramic-coated multilayer barriers.
Supply Chain Analysis
High-purity polyimide precursor supply rests on Japanese and Korean specialty chemical producers in Osaka and Ulsan industrial clusters. Raw material dependencies center on dianhydride monomers, biaxially oriented extrusion equipment, and halogen-free flame retardant additives. Single-source vulnerability concentrates in semiconductor-demand surge periods when precursor allocation shifts. Distribution runs through tier-one battery supplier technical auditors co-located with converter R&D facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where electric vehicle thermal runaway protection specifications are displacing cost-first procurement. Battery OEM platform engineers now mandate 800°C cascade-failure tolerance as a baseline qualification threshold.
For Market Incumbents: Anticipate specification consolidation by locking multi-year volume commitments with CATL and BYD procurement offices before approved vendor lists contract further. Defensive consolidation moves should prioritize captive precursor supply through backward integration into polyimide dianhydride production, while certification investment in REACH-compliant halogen-free formulations neutralizes regulatory displacement risk from emerging silicone-ceramic hybrid suppliers.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in automotive thermal barriers opens white-space at the mid-tier ceramic-coated PET segment where ALD equipment-integrated converters have not scaled. Target India's PLI-aligned cell manufacturing cluster with localized lamination operations, using waterborne adhesive qualification as a go-to-market angle to capture EPA compliance premiums in North American export channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional converter-slitter operations face UL 94 recertification burdens and multi-site quality harmonization audits from battery OEMs. Long-term viability favors equipment-integrated coating specialists with atomic layer deposition capabilities over pure-play resin distributors. Watch solid-state battery thermal interface qualification timelines as the inflection signal for ceramic-polymer hybrid film demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive dianhydride production secures allocation priority during semiconductor demand surges. |
| ALD Coating Capacity Expansion | Equipment-integrated converters capture barrier precision premiums from tier-one battery suppliers. |
| REACH-Compliant Formulation Investment | Halogen-free PVC alternatives retain European construction specification access against PFAS restrictions. |
| Localized Lamination Operations | India PLI scheme alignment creates first-mover advantage in domestic cell manufacturing clusters. |
| Multi-Year Platform Commitments | Long-term thermal barrier contracts lock volume before approved vendor lists contract to three suppliers. |
Research Methodology
Multiple input streams — converter procurement managers, battery OEM thermal engineers, polymer R&D directors, and building envelope contractors — were reconciled against secondary validation from MIIT directive filings, EPA enforcement databases, and ECHA SVHC candidate list updates. Primary interviews with tier-one supplier technical auditors and secondary synthesis of customs trade data, SEC chemical segment disclosures, and GB standards documentation enabled bottom-up volume triangulation with top-down market sizing.
Historical shipment patterns cross-referenced against expert panel input on solid-state battery thermal interface development shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include polymer chemistry tier, application end-use, thickness gauge, and regional converter capacity cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating electric vehicle production forecasts and building retrofit cycle timing, with dielectric strength specification evolution and flame retardant regulatory phase-outs as industry-specific forecast inputs.
Caveats apply where REACH PFAS restriction finalization, solid-state battery commercialization delays, or polyimide precursor allocation shocks could materially shift the outlook. Forecasts reflect assumptions about certification timeline compression and automotive platform standardization continuity. A small set of named triggers — ECHA restriction scope expansion, MIIT thermal performance rating revisions, and UL 94 reclassification proposals — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Nano Sealers Market
Packaging Barrier Films
Hydrocolloid Coating Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
North America Barrier Films Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Global Stretch and Shrink Film Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Packaging Barrier Films Market