
 Moisture Barrier Bags Market | 2026-2036
Moisture Barrier Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Moisture Barrier Bags Market Analysis
Multi-source procurement for specialty films is broadening as OEMs reduce dependency on single resin suppliers. Amcor Plc leverages its global extrusion network to sustain consistent alloy supply across three continents. 3M anchors North American demand through captive fluoropolymer technology and direct aerospace channel control. Mondi Plc competes via integrated kraft-paper and aluminum lamination lines serving European pharmaceutical contract packers.
Moisture barrier bags are engineered laminate structures combining aluminum foil, metallized films, or high-density polyethylene with sealant layers to achieve moisture vapor transmission rates below 0.0006 grams per 100 square inches per day, protecting hygroscopic goods from oxidation, corrosion, and potency loss during storage and transit. Flat bags dominate electronics and industrial dispatch due to economies in high-speed form-fill-seal operations, while zipper configurations capture growing pharmaceutical direct-to-patient formats where resealability reduces contamination risk. Aluminum foil laminations retain the highest margin pools in military and aerospace applications where MIL-PRF-131 compliance mandates extreme barrier performance.
FDA enforces 21 CFR 177.1390 for laminate structures in food and pharmaceutical contact, while EMA's Annex 1 sterile manufacturing guidelines extend barrier requirements to active ingredient shipping. China's NMPA and GB/T standards for drug packaging materials are converging with ICH Q1A stability testing protocols, raising qualification barriers for imported films. Stakeholders must monitor regulatory divergence between US, European, and Chinese pharmacopeial barrier test methods when qualifying unified product platforms.
Market Dynamics
Semiconductor manufacturers in Asia-Pacific are consolidating procurement specifications around ultra-low MVTR films, forcing laminate suppliers to qualify against unified performance benchmarks rather than regional variants. This standardization pressure is compressing margins for mid-tier converters while elevating technical barriers to entry.
Growth Catalysts
- EMA Annex 1 sterile manufacturing guidelines:The revised guidelines extend barrier requirements to active ingredient shipping, compelling European pharmaceutical contract packers to upgrade from standard polyethylene to aluminum-foil laminates with validated seal integrity.
- Precision manufacturing clusters in China, South Korea, and Germany:Concentrated demand from semiconductor fabs and aerospace subcontractors is creating specification pull-through effects that raise performance floors across adjacent industrial segments.
- Fluoropolymer coextrusion advances:Captive fluoropolymer technology enables North American suppliers to achieve MVTR specifications below 0.0003 grams per 100 square inches per day, opening military and satellite component applications previously served by European specialists.
Market Restraints
- Aluminum foil supply concentration:Rolling mill capacity for pharmaceutical-grade foil concentrates in a handful of European and Chinese producers, exposing converters to allocation risk during energy price spikes.
- REACH SVHC candidate list expansion:ECHA's periodic addition of plasticizers and adhesion promoters to the substances of very high concern list forces reformulation cycles that delay product requalification by 12-18 months.
- High-density polyethylene resin volatility:Ethylene feedstock price swings tied to naphtha-cracking economics compress converter margins on standard-grade barrier bags where pass-through clauses lag spot movements.
Strategic Opportunities
- Direct-to-patient pharmaceutical formats:Zipper-configured barrier bags for biologic stability during home delivery are capturing share from traditional vial-and-syringe packaging in US specialty pharmacy channels.
- India's PLI scheme for electronics manufacturing:The production-linked incentive program is attracting semiconductor assembly and test operations that will require qualified barrier packaging suppliers with local conversion capability.
- Dual carbon goals in China:MEE enforcement of carbon intensity benchmarks is creating preference for solventless lamination adhesives and thinner-gauge aluminum structures that reduce embodied emissions per unit barrier performance.
Industry Challenges
- MIL-PRF-131J certification timelines:Defense contractors face 18-24 month qualification cycles for new laminate structures, freezing product development roadmaps and limiting supplier switching flexibility.
- Multilayer coextrusion technician scarcity:The specialized skill set required for thin-gauge barrier film production concentrates in aging workforces at German and Japanese equipment manufacturers, constraining greenfield capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moisture Barrier Bags Market |
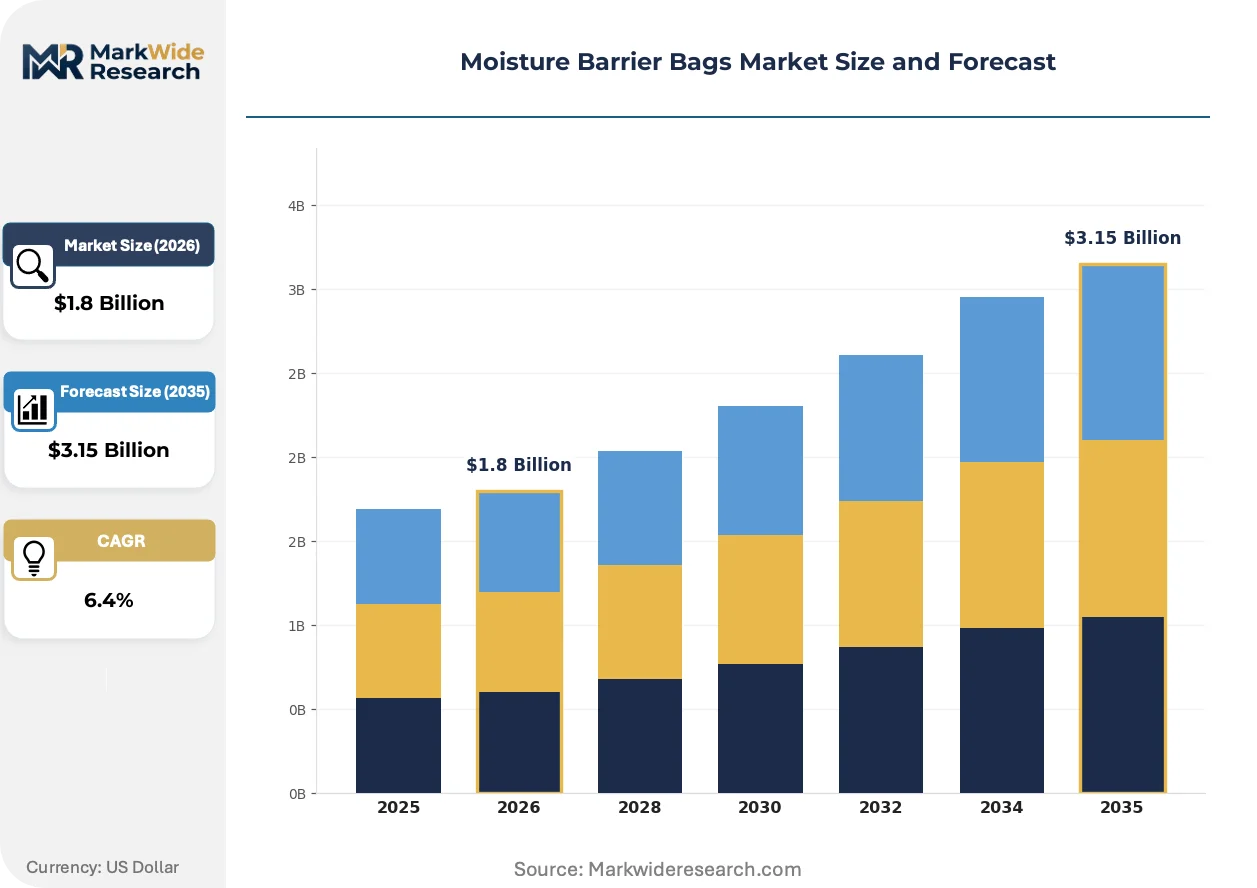
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Zipper Bags, Stand-Up Pouches Material: Polyethylene, Polypropylene, Nylon, Aluminum Foil End User: Food & Beverage, Electronics, Pharmaceuticals, Industrial Closure Type: Heat Seal, Zipper, Velcro, Adhesive |
| Companies Covered | Sonoco Products Company, Protective Packaging Corporation Inc, Amcor Plc, Twin Rivers Paper Company LLC, Flexopack SA, 3M, Mondi Plc, Billerudkorsnäs Ab, ProAmpac LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moisture Barrier Bags Market Emerging Trajectories
Active barrier technologies and digital traceability systems are converging to transform moisture barrier bags from passive protection into intelligent packaging nodes that report environmental exposure history throughout the supply chain.
Metallized polyethylene terephthalate with ceramic nanocoating is overtaking conventional aluminum foil in cost-sensitive electronics applications. Mid-tier semiconductor assemblers in Malaysia and Vietnam are adopting these structures for non-hermetic component dispatch. The technology is overtaking legacy foil laminates by 8-12 percentage points in annual procurement volume across ASEAN manufacturing zones while compressing unit economics for standard-grade barrier performance.
REACH authorization requirements for chromium(VI) compounds used in corrosion-resistant packaging are forcing European military suppliers to validate trivalent chromium and vapor-phase inhibitor alternatives. The regulation is compressing qualified supplier lists and extending procurement lead times for NATO-specification barrier bags by approximately six months as new adhesion chemistries undergo accelerated aging protocols.
Consolidated buying through integrated contract packers is displacing direct procurement relationships between film converters and pharmaceutical OEMs. Large European CDMOs now specify barrier performance tiers rather than laminate constructions, transferring formulation risk to packaging suppliers. This concentration is most visible in Germany and Switzerland where three contract packers control approximately sixty percent of biologic active ingredient secondary packaging decisions.
Moisture Barrier Bags Market Segmentation
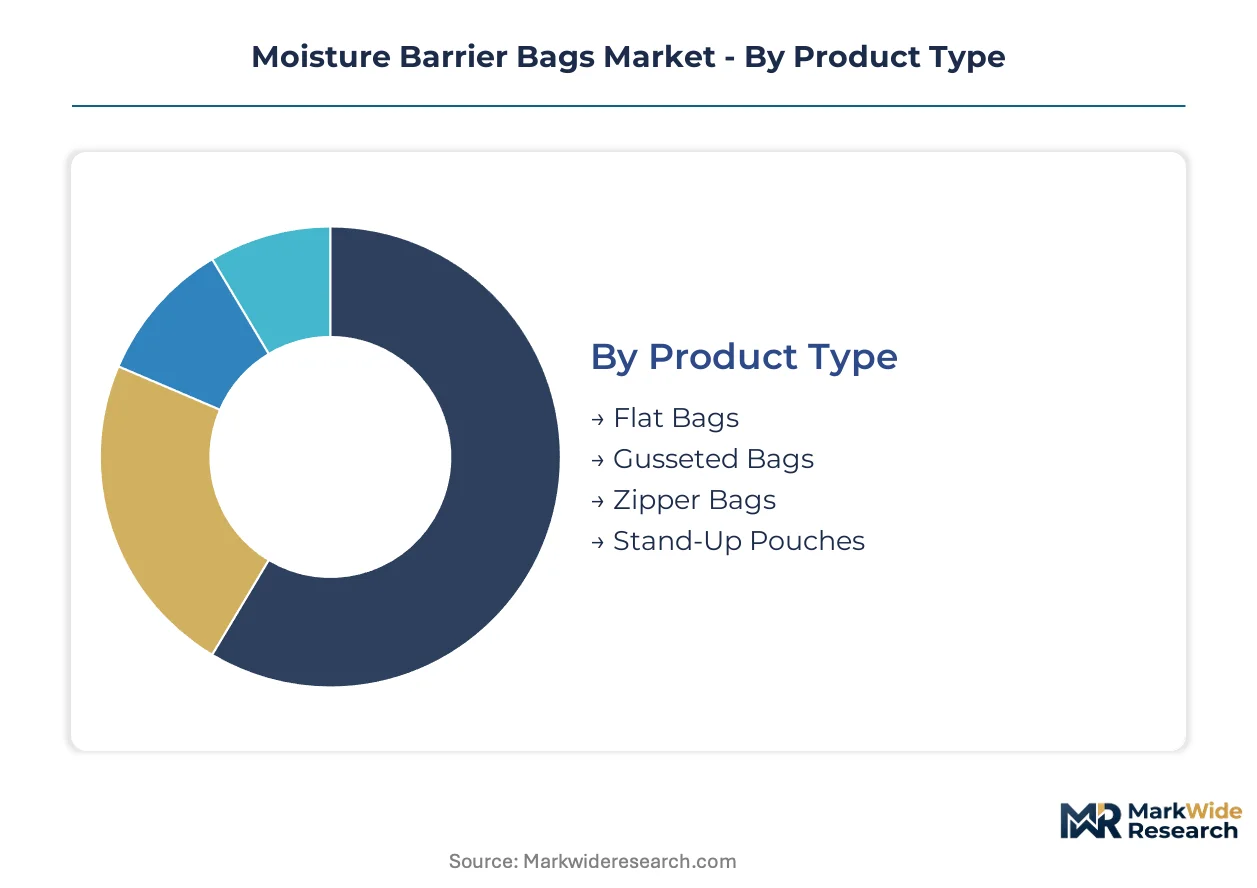
Segmentation in moisture barrier bags reveals how laminate engineering, closure mechanics, and end-use compliance requirements create distinct margin pools and qualification barriers. Specification divergence across product types and materials directly determines converter capacity allocation and customer switching costs.
Product Type:
Customization intensity spans from commodity flat formats to engineered resealable systems, with specification depth correlating directly to pharmaceutical and aerospace qualification timelines.
- Flat Bags:These structures employ aluminum-foil or metallized-film laminates with heat-seal layers to achieve sub-0.0006 MVTR ratings for semiconductor wafer and passive component dispatch. Electronics manufacturers in China and South Korea specify these for high-speed form-fill-seal operations where throughput economics dominate procurement decisions.
- Zipper Bags:Integrating resealable interlocking profiles with barrier substrates adds 15-20% material cost but enables multi-dose pharmaceutical stability for direct-to-patient biologic delivery. US specialty pharmacy channels are consolidating procurement around validated zipper seal integrity for temperature-sensitive therapeutics.
- Gusseted Bags:Side-folded expansion panels accommodate irregular industrial components and bulk active pharmaceutical ingredients while maintaining barrier performance during palletized transit.
- Stand-Up Pouches:Bottom-gusseted formats with barrier substrates serve diagnostic reagent kits and medical device kits requiring retail shelf presence alongside environmental protection.
Most installed capacity flows through Flat Bags. Expansion is steepest in Zipper Bags.
Material:
Material selection traces a cost-performance frontier from commodity polyolefins to engineered foil laminates, with qualification requirements fragmenting the supplier base by end-use sector.
- Aluminum Foil:Multi-layer laminates incorporating 6-12 micron foil achieve the lowest MVTR specifications required for military MIL-PRF-131 compliance and long-duration pharmaceutical stability. European rolling mill concentration in Germany and France creates supply allocation risk during energy price volatility.
- Polyethylene:High-density and linear low-density variants serve cost-sensitive electronics and industrial applications where sub-30-day transit durations reduce barrier performance requirements. Ethylene feedstock price swings tied to naphtha-cracking economics compress converter margins on standard-grade specifications.
- Polypropylene:Oriented and cast films provide intermediate barrier performance with improved clarity for medical device kits requiring visual inspection without package breach.
- Nylon:Polyamide layers contribute puncture resistance and oxygen barrier in multilayer coextrusions for vacuum-packed industrial components and aggressive chemical environments.
Aluminum Foil commands the highest margin pool. Polyethylene carries the greatest volume throughput.
End User:
End-use segmentation maps directly to regulatory jurisdiction, with pharmaceutical and food contact applications imposing the most stringent migration testing and stability validation protocols.
- Electronics:Semiconductor fabs and contract assemblers in Germany, China, and South Korea specify ultra-low MVTR films for moisture-sensitive device protection during global supply chain transit. REACH and RoHS compliance requirements restrict adhesive and coating chemistries in European-bound shipments.
- Pharmaceuticals:Active ingredient shippers and CDMOs demand validated seal integrity and extractables testing under FDA 21 CFR 177.1390 and EMA Annex 1 sterile manufacturing guidelines. European contract packers in Switzerland and Germany now specify performance tiers rather than laminate constructions.
- Food & Beverage:Dried ingredients and sensitive nutraceuticals require intermediate barrier performance with cost constraints that favor metallized films over full foil laminates.
- Industrial:Aerospace subcontractors and defense contractors face 18-24 month MIL-PRF-131J qualification cycles that freeze supplier relationships and limit price competition.
Electronics drives the largest procurement volume. Pharmaceuticals exhibits the steepest specification escalation.
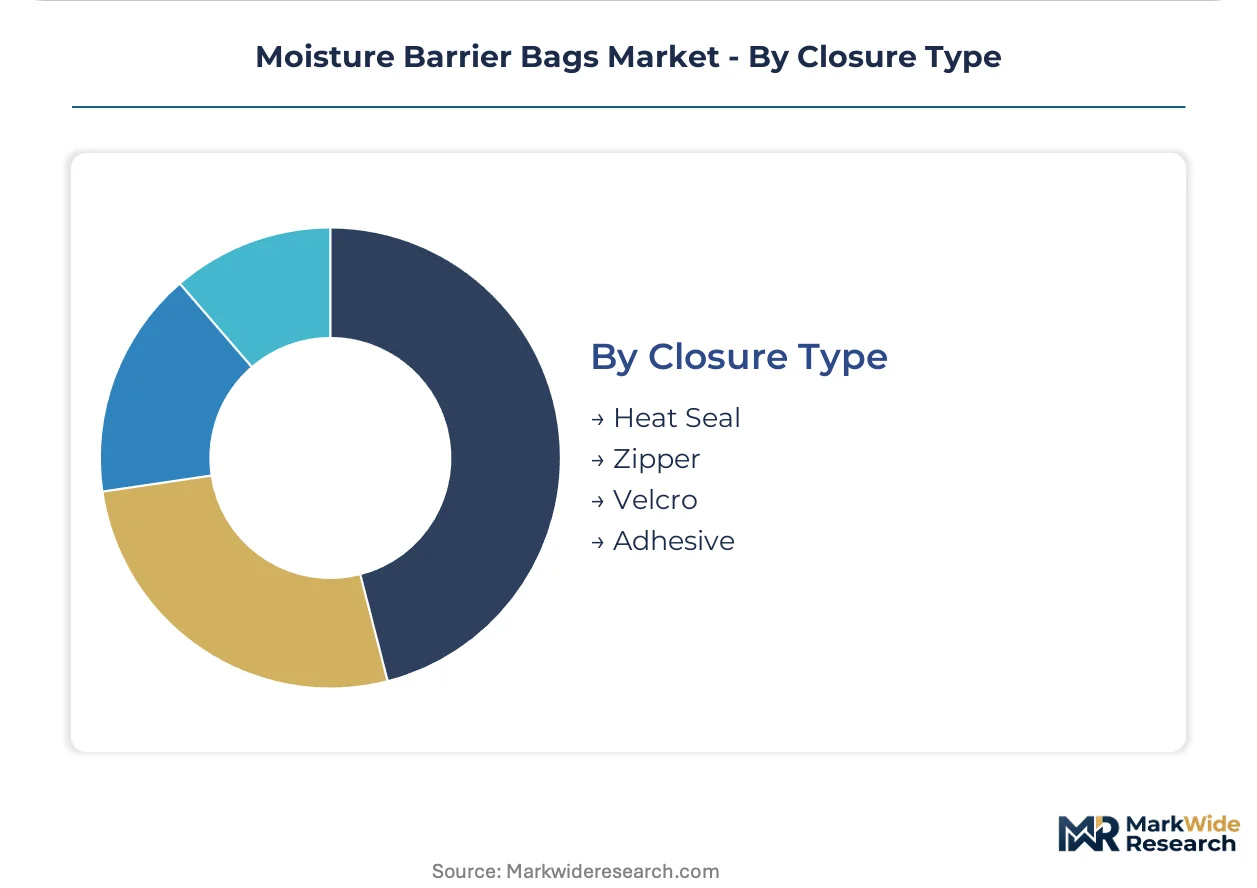
Closure Type:
Closure mechanics determine package reopening behavior and contamination risk, with heat-seal dominance in industrial applications yielding to resealable formats in pharmaceutical direct-to-patient channels.
- Heat Seal:Thermal fusion of coextruded sealant layers provides tamper-evidence and hermetic integrity for single-use pharmaceutical and military applications. FDA and EMA guidelines emphasize seal strength validation as a critical quality attribute.
- Zipper:Interlocking profile systems enable multiple access cycles for multi-dose regimens without compromising barrier performance. Children's safety regulations in the US and EU add complexity to zipper design qualification.
- Velcro:Hook-and-loop systems serve reusable industrial tool kits and maintenance supplies where frequent access outweighs maximum barrier requirements.
- Adhesive:Pressure-sensitive and cohesive closure systems provide intermediate resealability for diagnostic and laboratory supply packaging.
Heat Seal retains the largest installed base. Zipper configurations are gaining share fastest in pharmaceutical channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's precision manufacturing clusters in the Yangtze River Delta and Pearl River Delta drive the steepest specification escalation for ultra-low MVTR films, with semiconductor fabs consolidating procurement around unified performance benchmarks.
China
Semiconductor assembly and test operations in Jiangsu and Shanghai provinces are expanding capacity under the dual carbon goals enforced by MEE, favoring solventless lamination adhesives and thinner-gauge aluminum structures that reduce embodied emissions per unit barrier performance.
United States
Specialty pharmacy channels are consolidating procurement around validated zipper seal integrity for temperature-sensitive therapeutics, with FDA 21 CFR 177.1390 compliance extending barrier requirements to active ingredient shipping formats across the Northeast and California biotech corridors.
Germany
EMA Annex 1 sterile manufacturing guidelines are compelling pharmaceutical contract packers in Bavaria and North Rhine-Westphalia to upgrade from standard polyethylene to aluminum-foil laminates with validated seal integrity, compressing qualified supplier lists.
South Korea
Memory and logic chip manufacturers in Gyeonggi Province and the Seoul Capital Area are driving specification pull-through effects that raise performance floors across adjacent industrial segments, with MFDS alignment to ICH Q1A stability testing protocols raising qualification barriers for imported films.
India
The PLI scheme for electronics manufacturing is attracting semiconductor assembly and test operations to Gujarat and Karnataka that will require qualified barrier packaging suppliers with local conversion capability, with CDSCO convergence toward ICH protocols accelerating material validation timelines.
Moisture Barrier Bags Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and aerospace qualification pathways. The supplier base stratifies between integrated multinational converters with captive resin supply and regional specialists serving single-country electronics clusters. Three archetypes dominate: integrated paper-plastic converters leveraging kraft-aluminum lamination lines, fluoropolymer technology holders with direct defense channel access, and contract packaging aggregators transferring formulation risk upstream. Consolidation through regional acquisition and capacity co-location near semiconductor fabs represent the dominant competitive moves.
Among publicly traded packaging conglomerates, Amcor Plc and Mondi Plc exemplify the integrated multinational archetype with extrusion networks spanning multiple continents, while 3M occupies a distinct position as a fluoropolymer technology anchor with direct aerospace channel control. These three entities represent the premium-tier competitive vector where technical specification depth and regulatory qualification breadth create the steepest barriers to challenger entry.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Protective Packaging Corporation Inc |
| Amcor Plc |
| Twin Rivers Paper Company LLC |
| Flexopack SA |
| 3M |
| Mondi Plc |
| Billerudkorsnäs Ab |
| ProAmpac LLC |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialty film converters have consolidated regional capacity across the American Midwest and German industrial corridors, tightening pricing discipline through shared procurement desks while simultaneously constraining supply flexibility during aluminum foil allocation crunches.
Pricing Analysis
Ethylene feedstock volatility and rolling mill energy surcharges transmit directly into converter quotations with 60-90 day lags. Three-tier pricing structure across premium, standard, and economy levels separates MIL-PRF-131 certified aerospace laminates from pharmaceutical-grade foils and commodity metallized films. Cost compression in standard-grade polyethylene bags is intensifying because naphtha-cracking economics compress margins where pass-through clauses lag spot movements. Electronics contract assemblers in Malaysia and Vietnam exhibit the highest price sensitivity, while defense contractors face the lowest due to 18-24 month qualification lock-ins.
Supply Chain Analysis
EMA Annex 1 and FDA 21 CFR 177.1390 qualification requirements gate entry to pharmaceutical and aerospace tiers, concentrating qualified supply among converters with validated cleanroom lamination lines and extractables testing capabilities. Pharmaceutical-grade aluminum foil rolling capacity concentrates in Germany, France, and China, while fluoropolymer resin supply anchors in the United States and Japan. The supply chain rests on ethylene feedstock from naphtha crackers, 6-12 micron aluminum foil from European and Chinese rolling mills, and solventless adhesives subject to REACH SVHC restrictions. Single-source vulnerability concentrates in pharmaceutical-grade foil during European energy price spikes. Distribution runs through integrated contract packers in Germany and Switzerland who now specify performance tiers rather than laminate constructions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The moisture barrier bags market functions as a geographic-arbitrage play where India's PLI scheme for electronics manufacturing offers 15-25% cost advantages against Chinese coastal zones while requiring identical ICH Q1A qualification protocols.
For Market Incumbents: Acquire solventless lamination adhesive formulation capabilities to preempt REACH SVHC-driven reformulation cycles. Defensive consolidation through regional acquisition near semiconductor fabs in Gujarat and Karnataka locks in PLI-linked demand before local conversion capacity saturates. Capacity co-location with memory chip manufacturers in Gyeonggi Province captures specification pull-through effects that raise performance floors across adjacent industrial segments. For New Entrants and Emerging Players: Capture India's PLI-driven electronics manufacturing expansion by establishing qualified barrier packaging conversion in Gujarat or Karnataka before incumbent capacity co-location completes. The most penetrable segment is zipper-configured pharmaceutical direct-to-patient formats where resealability requirements are displacing traditional vial-and-syringe packaging. A go-to-market angle through US specialty pharmacy channel partnerships bypasses the 18-24 month MIL-PRF-131J qualification barrier that freezes defense sector entry. For Investors and Strategic Acquirers: Valuations sit cheapest among regional European converters with kraft-paper aluminum lamination lines serving pharmaceutical contract packers but lacking fluoropolymer technology or aerospace channel access. Long-term viability over the next decade hinges on regulatory qualification breadth across FDA, EMA, and NMPA jurisdictions rather than commodity volume scale. The signal to watch is CDSCO convergence toward ICH protocols in India, which will accelerate material validation timelines and compress first-mover advantages for local conversion capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Co-location Near Semiconductor Fabs | Captures specification pull-through effects from memory and logic chip manufacturers in Gyeonggi Province. |
| REACH-Compliant Solventless Adhesive Transition | Preempts 12-18 month reformulation delays from ECHA SVHC candidate list expansions. |
| Dual Carbon Goals Alignment | MEE enforcement in China creates preference for thinner-gauge aluminum structures with lower embodied emissions. |
| Zipper Seal Integrity Validation | FDA 21 CFR 177.1390 compliance enables capture of US specialty pharmacy direct-to-patient biologic delivery channels. |
| Fluoropolymer Technology Acquisition | MIL-PRF-131J certification opens military and satellite component applications with 18-24 month qualification moats. |
Methodological Framework
Direct dialogue with procurement directors at semiconductor fabs, pharmaceutical contract packers, and aerospace subcontractors grounded qualitative findings in operational realities. Secondary validation drew from FDA 21 CFR filings, EMA Annex 1 guidance documents, NMPA drug packaging material registrations, and customs trade data on aluminum foil and ethylene polymer flows. Bottom-up capacity assessments at laminate converters across Germany, China, South Korea, and India triangulated against top-down demand modeling from electronics and pharmaceutical shipment volumes.
Segment-level projections across the analysis window combined product type, material grade, closure mechanism, and end-use regulatory cluster dimensions. CAGRs emerged from elasticity-calibrated demand curves incorporating semiconductor fab capacity expansion, PLI scheme uptake rates, and sterile manufacturing guideline enforcement trajectories. Industry-specific inputs included MVTR specification escalation curves from precision manufacturing clusters and REACH SVHC reformulation cycle timelines.
Underlying measurement precision varies by segment; aluminum foil laminates for military and pharmaceutical applications carry tighter precision than commodity polyethylene formats due to qualification documentation density. Forecasts reflect assumptions on regulatory convergence timelines, feedstock price pass-through coefficients, and contract packer consolidation trajectories. A model refresh is warranted upon material change in ECHA SVHC candidate list composition or MEE dual carbon goals enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Insulation Film Market
Packaging Barrier Films
Heat Transfer Films Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Antimicrobial Packaging Market