
 Pallet Boxes Market | 2026-2036
Pallet Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Boxes Market Outlook
Reusable polymer engineering is tilting pallet box design toward closed-loop supply systems. ORBIS Corporation leverages its captive resin compounding network to control material consistency across North American production. Schoeller Allibert anchors European demand through pooled rental programs serving automotive tier-one suppliers. Craemer GmbH dominates heavy-duty injection molding for chemical and agriculture bulk containment.
Pallet boxes are rigid, stackable bulk containers engineered for unitized transport of goods on standard pallet footprints, typically constructed from high-density polyethylene, thermoformed ABS, or laminated corrugated board with rated load capacities from 250 to 1500 kilograms. Plastic pallet boxes lead value contribution due to longer service life and washdown compatibility in food and pharmaceutical chains. Wood retains volume share in agriculture and construction where single-trip economics prevail. Metal variants occupy premium niches for hazardous material containment and defense logistics.
EPA hazardous waste container standards, FDA food contact material regulations, and ISO 8611 pallet testing protocols shape product certification requirements and market access thresholds in the United States. The EU Packaging and Packaging Waste Regulation drives recyclability quotas and extended producer responsibility fees across European supply chains. Stakeholders must monitor evolving state-level plastic restrictions and bio-based content mandates to align material strategies with compliance timelines.
Market Dynamics
Closed-loop supply systems are restructuring pallet box economics as pharmaceutical distributors and automotive tier-one suppliers demand asset tracking, washdown compatibility, and rapid turnaround cycles that single-trip containers cannot satisfy.
Growth Catalysts
- Cold chain logistics mandates:FDA food contact material regulations and pharmaceutical distribution protocols require temperature-stable bulk containment. Pooled rental fleets with integrated tracking satisfy compliance while reducing capital burden.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility fees and recyclability quotas penalize single-use packaging. Reusable polymer engineering captures compliance value across European supply chains.
- Automotive tier-one supplier consolidation:Just-in-sequence manufacturing in Germany's industrial logistics corridor demands standardized, returnable bulk containers with rated load capacities exceeding 1000 kilograms.
Market Restraints
- Resin price volatility:High-density polyethylene feedstock costs fluctuate with crude oil benchmarks, compressing margins for injection molding operations without captive compounding capacity.
- Supply concentration in German heavy-duty molding:Craemer GmbH and Schoeller Allibert dominate European production of chemical and agriculture bulk containment, creating bottleneck risk for specialized designs.
- Wood substitution in single-trip agriculture:Laminated corrugated board and untreated timber retain cost advantage in harvest-season logistics where return logistics are uneconomical.
Strategic Opportunities
- Pharmaceutical distribution networks:Cold chain adoption among vaccine and biologics distributors creates demand for insulated polymer containers with integrated data loggers.
- Bio-based content mandates:EU Green Deal targets and national plastic restrictions incentivize recycled HDPE and bio-polymer formulations that meet ISO 8611 testing protocols.
- Pooled rental program expansion:ORBIS Corporation's North American resin compounding network demonstrates scalability for asset-light logistics models beyond captive automotive applications.
Industry Challenges
- ISO 8611 certification timelines:Pallet testing protocols require extended validation cycles for new polymer formulations, delaying product launches and freezing design iterations.
- Legacy fleet interoperability:Existing wood and metal container infrastructure in defense logistics and construction sectors resists standardization with polymer footprint dimensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Boxes Market |
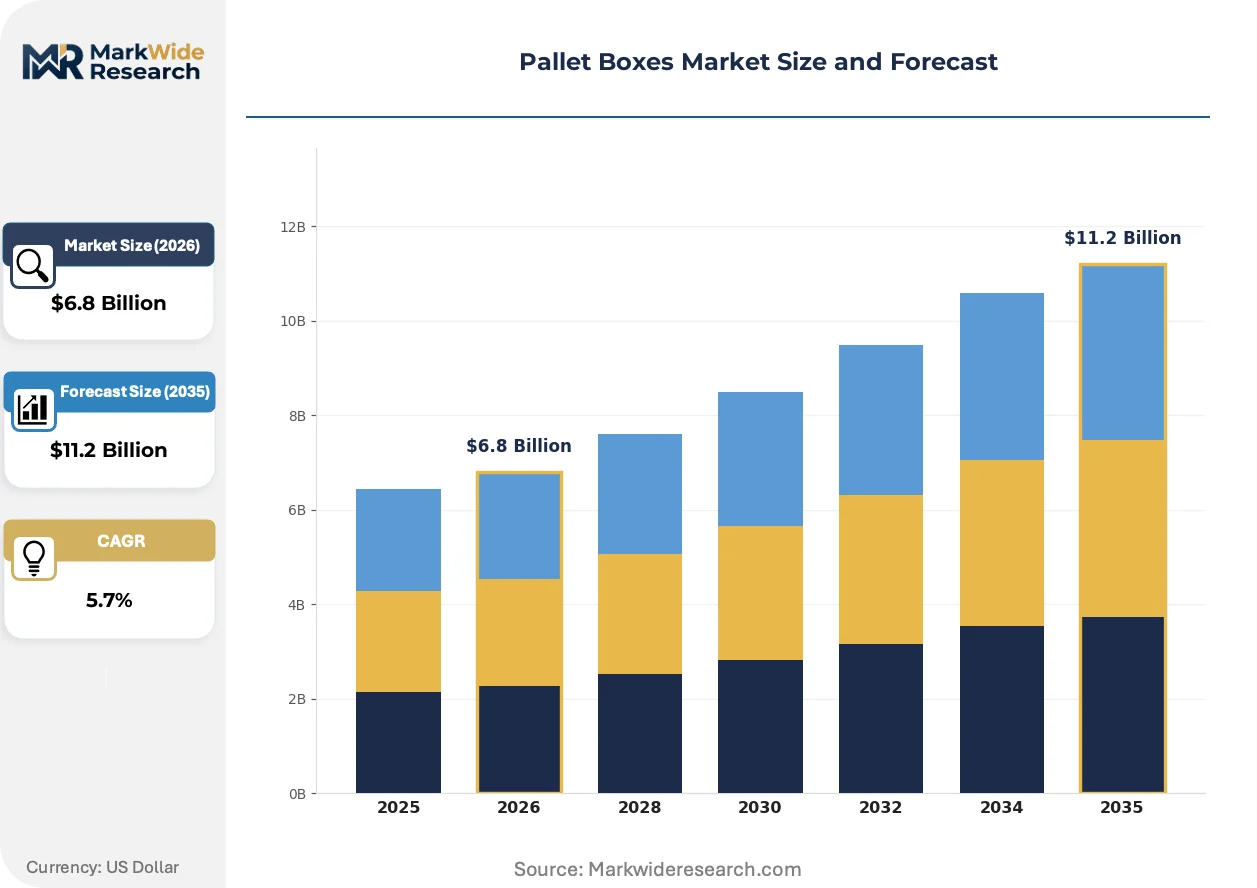
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood, Plastic, Metal, Cardboard End User: Retail, Logistics, Agriculture, Pharmaceuticals Capacity: 1000 Liters, 500 Liters, 250 Liters, 1500 Liters Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | ORBIS Corporation, Craemer GmbH, CHEP (Brambles Limited), Elkhart Plastics, Kamps Pallets, PalletOne, Schoeller Allibert, XuanSheng, Rehrig Pacific Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Boxes Market Strategic Shifts
Radio-frequency identification and embedded sensor networks are transforming pallet boxes from passive containers into active supply chain nodes that report location, temperature, and shock events in real time.
Embedded RFID and IoT sensor modules are enabling pharmaceutical distributors to monitor cold chain integrity throughout distribution. Temperature excursions trigger automated alerts before product compromise occurs. This sensor integration is rendering obsolete manual temperature logging and batch-based quality sampling in high-value logistics.
REACH chemical registration requirements and EU Green Deal packaging targets are tightening material disclosure obligations for polymer suppliers. Manufacturers must document recycled content percentages and substance-of-very-high-concern screening. European automotive and chemical sectors are responding by specifying certified circular polymers with full chain-of-custody documentation.
Asset-light procurement through third-party logistics pooling is displacing direct ownership models among mid-sized food processors. Rental programs transfer washing, repair, and fleet balancing burdens to specialized operators. This shift concentrates most visibly in Germany's dense logistics corridor where automotive supplier density supports rapid container turnaround economics.
Pallet Boxes Market Segmentation
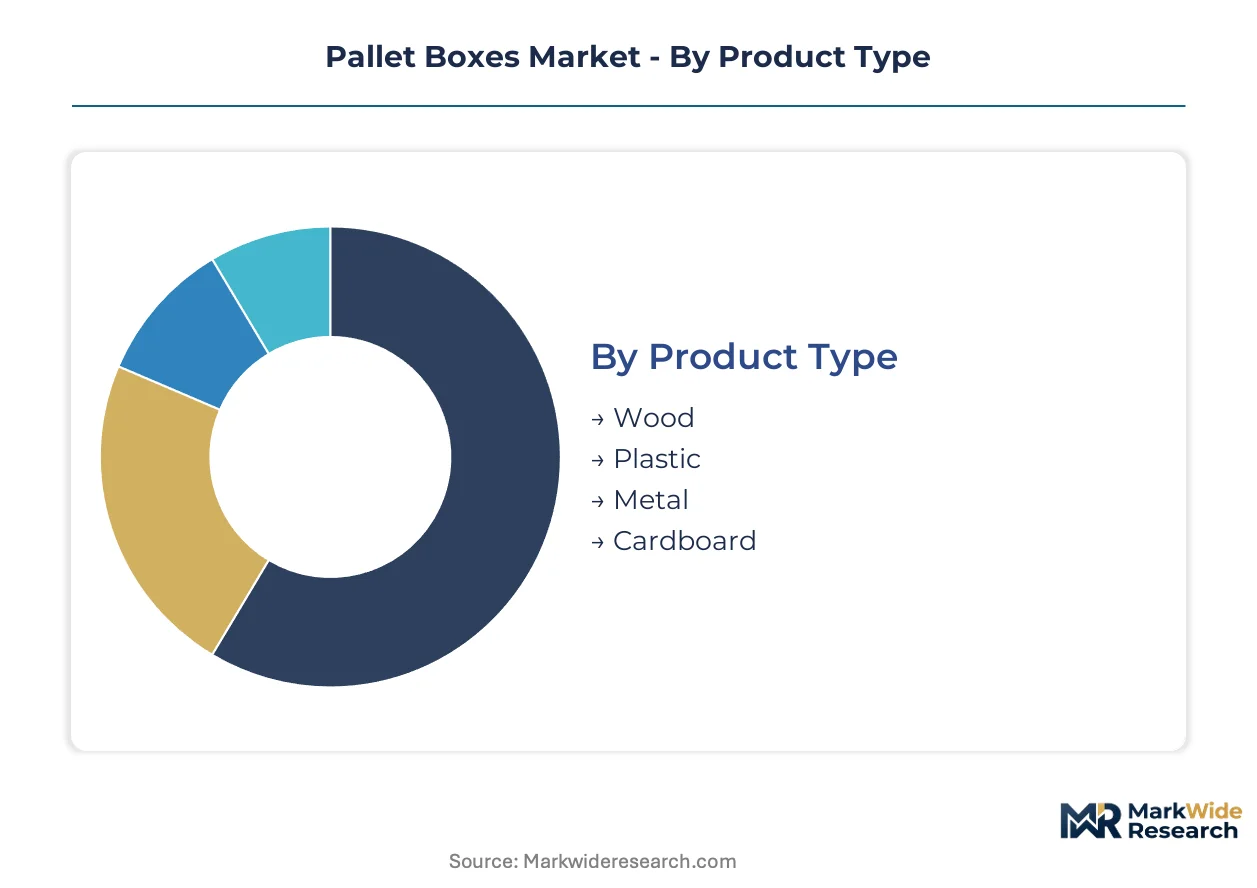
Material selection, load specifications, and procurement pathways each impose distinct cost structures and compliance obligations on pallet box deployments. Understanding how demand fragments across these dimensions enables suppliers to align production capacity with the operational realities of pharmaceutical cold chains, automotive just-in-sequence manufacturing, and seasonal agricultural logistics.
Product Type:
Material engineering dictates service life, washdown compatibility, and regulatory acceptance across food, pharmaceutical, and chemical supply chains.
- Plastic:High-density polyethylene formulations deliver extended cycle life and FDA-compliant surfaces for temperature-controlled pharmaceutical distribution. German automotive tier-one suppliers specify plastic pallet boxes for returnable container programs exceeding 1000-kilogram rated loads.
- Wood:Untreated timber and laminated corrugated board retain cost advantage in single-trip agriculture and construction applications where return logistics are uneconomical. Harvest-season volume concentrates in regions with abundant softwood supply.
- Metal:Steel and aluminum variants satisfy EPA hazardous waste container standards and defense logistics specifications for hazardous material containment. Premium pricing reflects fabrication complexity and corrosion-resistant coatings.
- Cardboard:Laminated corrugated constructions serve lightweight, disposable applications in retail display and promotional logistics where unit cost minimization outweighs durability requirements.
The dominant share belongs to Plastic, while Metal is closing the gap fastest through defense and chemical sector specification.
End User:
Operational intensity and regulatory exposure vary sharply across sectors handling perishables, hazardous materials, and high-value finished goods.
- Pharmaceuticals:Cold chain mandates from FDA and EMA drive specification of insulated polymer containers with integrated data loggers for vaccine and biologics distribution. Pooled rental fleets reduce capital burden while ensuring washdown validation.
- Logistics:Third-party operators manage asset-light procurement through rental programs, transferring washing, repair, and fleet balancing burdens to specialized pooling providers. Germany's dense logistics corridor supports rapid container turnaround economics.
- Agriculture:Seasonal harvest patterns favor single-trip wood and cardboard solutions where return logistics costs exceed container replacement value. Bulk grain and produce handling prioritizes ventilation and moisture resistance.
- Retail:Point-of-sale display and promotional logistics demand lightweight, collapsible designs with printed branding surfaces. Turn velocity and aesthetic customization outweigh structural load ratings.
Pharmaceuticals commands premium pricing tiers, with Logistics expanding most quickly through third-party pooling adoption.
Capacity:
Volume engineering directly correlates with handling equipment compatibility and freight density optimization in road, rail, and intermodal networks.
- 1000 Liters:Standard footprint for automotive just-in-sequence manufacturing and chemical bulk containment. Craemer GmbH and Schoeller Allibert dominate European production of this specification.
- 500 Liters:Mid-range capacity serves food processing and intermediate pharmaceutical ingredient handling. Washdown compatibility and stack stability prioritize polymer construction.
- 250 Liters:Compact dimensions suit retail distribution and last-mile logistics where vehicle cube utilization and manual handling constraints apply. Lighter tare weight reduces fuel consumption.
- 1500 Liters:Maximum volume for heavy agriculture, mining, and construction bulk materials. Reinforced base structures and forklift entry design accommodate extreme point loads.
The 1000 Liters specification anchors volume, though 500 Liters is gaining share fastest through food and pharmaceutical intermediate handling.
Distribution Channel:
Procurement pathway selection reflects customer scale, technical support requirements, and fleet management sophistication.
- Direct Sales:Large automotive and pharmaceutical manufacturers negotiate multi-year supply agreements with injection molders for standardized, returnable container programs. Technical collaboration on RFID integration and custom dimensions is common.
- Distributors:Regional inventory positioning enables rapid fulfillment for mid-sized food processors and agricultural cooperatives. Local repair and washing services extend value beyond product delivery.
- Wholesalers:Volume aggregation serves small retail and construction customers with limited specification expertise. Standardized catalog offerings predominate over custom engineering.
- Online Retail:Digital procurement platforms capture price-sensitive, low-volume orders for cardboard and lightweight plastic variants. Lead time compression and transparent pricing appeal to occasional purchasers.
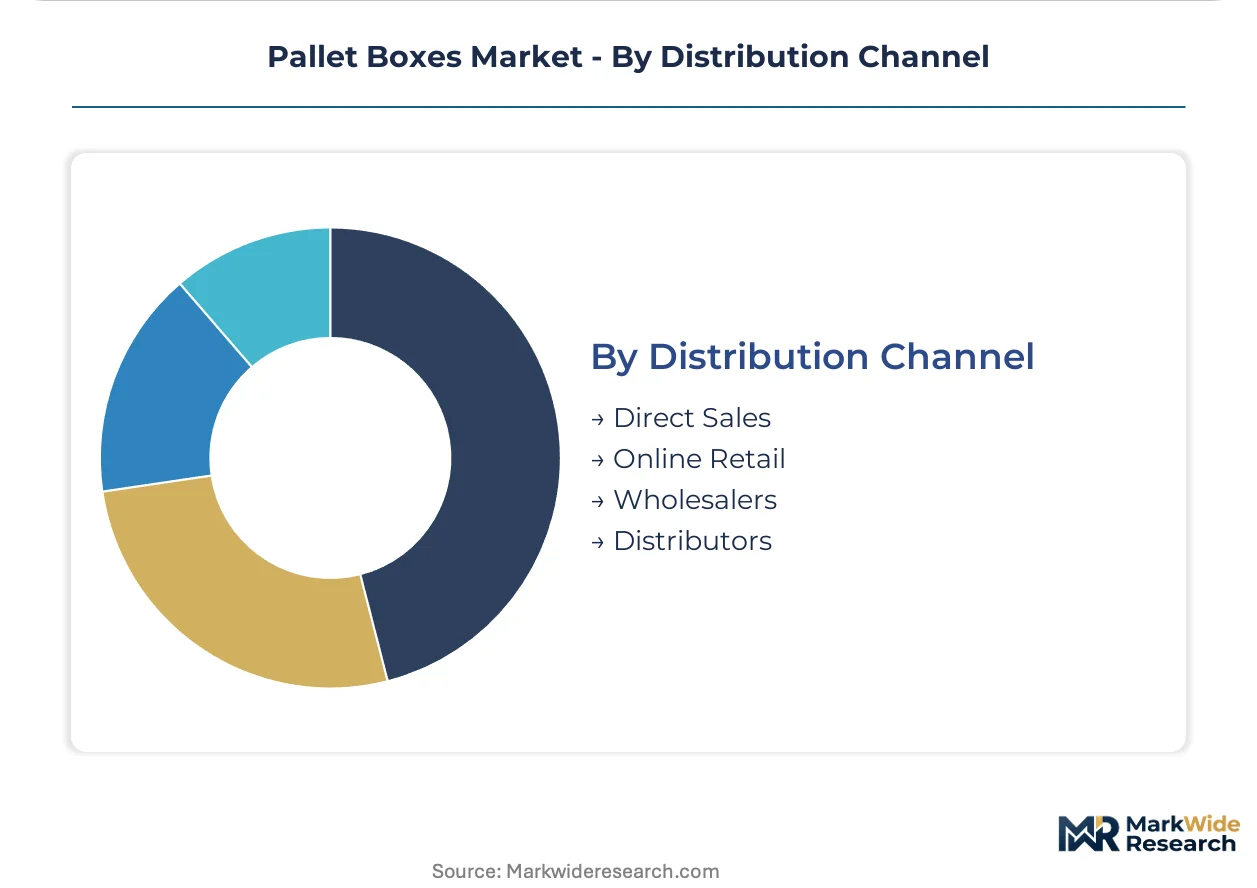
Direct Sales retains the largest revenue concentration, while Distributors are climbing the fastest through pooled rental program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered polymer pallet boxes to automotive assembly plants across Poland, Czech Republic, and Hungary. This eastward trade corridor concentrates demand for standardized returnable container systems rated above 1000 kilograms.
United States
Pharmaceutical cold chain expansion drives specification of insulated HDPE containers with integrated data loggers. FDA food contact material regulations mandate washdown-compatible surfaces for vaccine distribution networks. The Chicago-Milwaukee logistics corridor hosts major pooling operations serving Midwestern food processors.
Germany
Automotive just-in-sequence manufacturing demands standardized bulk containers with rapid turnaround cycles. EU Packaging and Packaging Waste Regulation penalties push manufacturers toward certified circular polymers. The industrial logistics corridor spanning Stuttgart-Munich-Nuremberg anchors European production of heavy-duty injection-molded designs.
China
E-commerce fulfillment centers specify lightweight collapsible pallet boxes for last-mile cube optimization. GB standards for plastic pallets align with ISO 8611 testing protocols for intermodal compatibility. Yangtze River Delta manufacturing clusters drive volume production of export-grade polymer formulations.
India
Agricultural cooperatives adopt single-trip corrugated solutions for harvest-season grain handling. FSSAI food safety regulations increasingly specify food-grade polymer alternatives for processed commodity storage. Maharashtra and Gujarat logistics hubs concentrate demand for ventilated bulk containers in spice and cotton supply chains.
Netherlands
Third-party logistics operators expand pooled rental fleets serving Benelux food and chemical distributors. REACH chemical registration requirements tighten material disclosure for polymer suppliers. The Rotterdam-Antwerp port cluster facilitates container turnaround for North Sea shipping lanes.
Pallet Boxes Market Competitive Environment
On the supply side, the industry is bifurcated between captive resin compounders serving closed-loop automotive programs and independent molders addressing spot agricultural demand. European producers dominate heavy-duty specifications through pooled rental infrastructure. North American operators compete on material consistency and rapid tooling iteration. Strategic moves concentrate on backward integration into resin compounding and geographic licensing of pooling software platforms.
Among German-based specialists, Craemer GmbH and Schoeller Allibert occupy positions exemplifying the heavy-duty molding archetype for chemical and automotive tier-one supply chains. ORBIS Corporation represents the North American captive compounding model with integrated resin network control. These three entities anchor the competitive structure across their respective regional production zones.
| Leading Market Players |
|---|
| ORBIS Corporation |
| Craemer GmbH |
| CHEP (Brambles Limited) |
| Elkhart Plastics |
| Kamps Pallets |
| PalletOne |
| Schoeller Allibert |
| XuanSheng |
| Rehrig Pacific Company |
| Others |
Value Chain & Pricing Dynamics
Stuttgart-Munich-Nuremberg industrial corridor capacity dynamics directly shape downstream pricing power for heavy-duty injection-molded pallet boxes, with Craemer GmbH and Schoeller Allibert commanding premium positioning through pooled rental infrastructure that transfers fleet management economics to automotive tier-one suppliers.
Pricing Analysis
Current-generation RFID-integrated polymer containers command substantial premiums over prior-generation passive designs, while next-generation bio-based formulations with certified circular content remain supply-constrained. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical-grade units from automotive returnable containers and single-trip agricultural wood alternatives. Cost compression in standard-grade plastic pallet boxes is intensifying because resin price volatility compresses margins for molders without captive compounding capacity. Agricultural cooperatives exhibit highest price sensitivity due to seasonal harvest economics, while pharmaceutical distributors prioritize compliance validation over unit cost.
Supply Chain Analysis
Dual-use technology export controls on advanced polymer formulations and embedded sensor modules limit cross-border flows of next-generation cold chain containers. Manufacturing gravity centers on Germany, China, and the United States, with production drawing from high-density polyethylene feedstock, thermoformed ABS sheet, and laminated corrugated board inputs. Single-source vulnerability concentrates in German heavy-duty molding for 1000-liter chemical containment specifications. Distribution runs through third-party logistics pooling operators that manage asset-light procurement for mid-sized food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pallet box economics increasingly hinge on service-attach revenue streams, with washing, repair, and RFID fleet management expanding faster than hardware sales as rental programs displace direct ownership models among pharmaceutical and food processing customers.
For Market Incumbents: Entrench market position through backward integration into captive resin compounding networks that buffer margin compression from crude oil-linked feedstock volatility, while accelerating ISO 8611 certification pipelines to freeze out competitors during extended validation cycles. ORBIS Corporation's North American model demonstrates scalability for asset-light logistics software licensing beyond captive automotive applications. For New Entrants and Emerging Players: Build out specialized capacity in insulated pharmaceutical containers with integrated data loggers, where cold chain mandates among vaccine distributors create penetrable white space unclaimed by established automotive-focused molders. India's agricultural cooperatives and Maharashtra logistics hubs offer entry points through FSSAI-compliant food-grade polymer alternatives to single-trip corrugated solutions. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because EU Packaging and Packaging Waste Regulation penalties and extended producer responsibility fees structurally advantage reusable polymer engineering over disposable alternatives. Target molders with established pooled rental software platforms and documented chain-of-custody certification capabilities. Monitor REACH chemical registration disclosure obligations as inflection indicator for material strategy pivots.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive HDPE supply buffers margin compression from oil price volatility for injection molders. |
| Pooled Rental Program Expansion | Asset-light procurement transfers washing and repair burdens to specialized third-party operators. |
| RFID and Sensor Module Integration | Embedded IoT networks transform passive containers into active cold chain compliance nodes. |
| Bio-based Polymer Formulation Development | EU Green Deal targets incentivize recycled content and bio-polymer alternatives meeting ISO protocols. |
| Geographic Licensing of Pooling Software | ORBIS Corporation's North American platform demonstrates scalability beyond captive automotive applications. |
Study Parameters
The analysis maps plastic, wood, metal, and cardboard pallet box sub-sectors, each validated through procurement directors at automotive tier-one suppliers, pharmaceutical distribution executives, agricultural cooperative managers, and third-party logistics operators. Primary interview findings triangulated against customs trade data, EU Packaging and Packaging Waste Regulation filings, FDA food contact material registrations, and SEC disclosures from listed pooling operators. Bottom-up capacity assessments at German, Chinese, and North American production facilities cross-checked against top-down demand modeling from automotive assembly plant container specifications.
Assumptions held fixed include EU Packaging and Packaging Waste Regulation penalty structures, FDA food contact material compliance timelines, and ISO 8611 testing protocol validity across the analysis window. Segmentation dimensions modeled encompass material type, end-user industry, capacity specification, and procurement channel. CAGRs derived from production capacity expansion announcements, rental fleet growth disclosures, and substitution elasticity estimates between reusable polymer and single-trip wood alternatives. Resin price volatility scenarios and cold chain logistics adoption curves served as primary forecast sensitivity inputs.
Stress conditions across crude oil price bands, EU extended producer responsibility fee schedules, and pharmaceutical cold chain penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and automotive production scheduling stability. Material shifts in REACH chemical registration requirements or state-level plastic restriction mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
India Pallets Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Block Pallets Market