
 Disposable Barrier Sleeves Market | 2026-2036
Disposable Barrier Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Barrier Sleeves Market Outlook
The split between premium and commodity tiers is shifting as hospitals demand certified sterile barriers while food processors prioritize cost-per-unit economics. Kimberly-Clark leverages its healthcare distribution network to anchor the premium clinical segment. Medline Industries competes on scale across mid-tier hospital purchasing contracts. Placon specializes in thermoformed polyethylene solutions for industrial and food-grade applications.
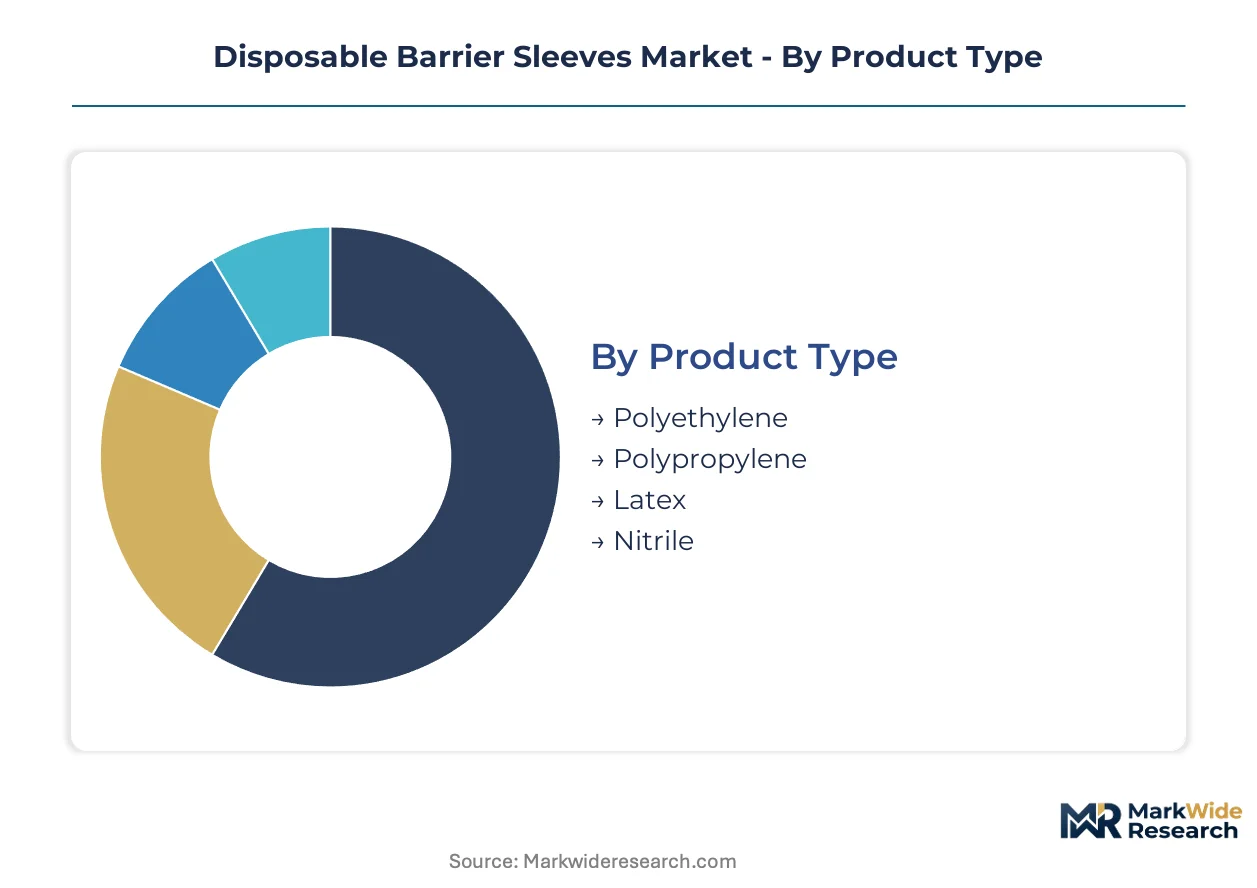
Disposable barrier sleeves are single-use protective coverings manufactured from polyethylene, polypropylene, latex, or nitrile, designed to shield equipment surfaces from contamination in sterile or controlled environments. Polyethylene dominates volume production due to low resin costs and heat-seal compatibility, though nitrile is gaining share where chemical resistance and tactile sensitivity matter. Healthcare applications command the highest unit margins, while food processing drives bulk volume procurement. Laboratory end users represent a concentrated but technically demanding niche requiring documented lot traceability.
FDA, OSHA, and ISO 13485 collectively govern material safety, workplace exposure limits, and quality management systems for disposable barrier sleeve manufacturers. FDA oversight of medical device classifications elevates documentation burdens for clinical-grade suppliers, while OSHA bloodborne pathogen standards mandate consistent replacement protocols in dental and surgical settings. Stakeholders must monitor evolving EPA guidance on single-use plastics and state-level extended producer responsibility frameworks that could reshape resin selection and end-of-life obligations.
Market Dynamics
OSHA workplace standards and FDA device regulations are tightening material certification requirements for clinical-grade barrier sleeves, forcing manufacturers to document lot traceability and sterility assurance while dental clinics and ambulatory surgery centers accelerate single-use protocols.
Growth Catalysts
- FDA Medical Device Classification:Elevated documentation burdens for clinical-grade suppliers create competitive moats for certified manufacturers serving hospital purchasing contracts.
- Ambulatory Surgery Center Construction:United States facility expansion sustains above-average procurement volumes for sterile barrier covers in outpatient settings.
- Nitrile Material Substitution:Chemical resistance and tactile sensitivity advantages drive adoption in laboratory and dental applications where polyethylene falls short.
Market Restraints
- Polyethylene Resin Cost Volatility:Feedstock price swings compress margins for high-volume food-grade sleeve producers competing on unit economics.
- Supply Concentration in Southeast Asia:Thermoforming capacity clustering creates geographic vulnerability for North American and European distributors.
- Reusable Barrier Systems:Autoclavable silicone and stainless-steel alternatives threaten commodity-tier disposable penetration in cost-sensitive industrial settings.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:State-level mandates in California and New York reshape resin selection and end-of-life obligations, favoring bio-based material innovators.
- Home Healthcare Expansion:Remote patient monitoring device protection creates demand for retail-packaged barrier sleeves outside institutional channels.
- ISO 13485 Quality Convergence:Laboratory end users requiring documented traceability pull certified suppliers into technically demanding niche segments.
Industry Challenges
- Sterilization Validation Timelines:FDA 510(k) clearance pathways for novel barrier materials extend commercialization cycles beyond 18 months.
- Legacy Equipment Compatibility:Dental chair and surgical instrument dimensional variability forces custom sleeve development, fragmenting production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Barrier Sleeves Market |
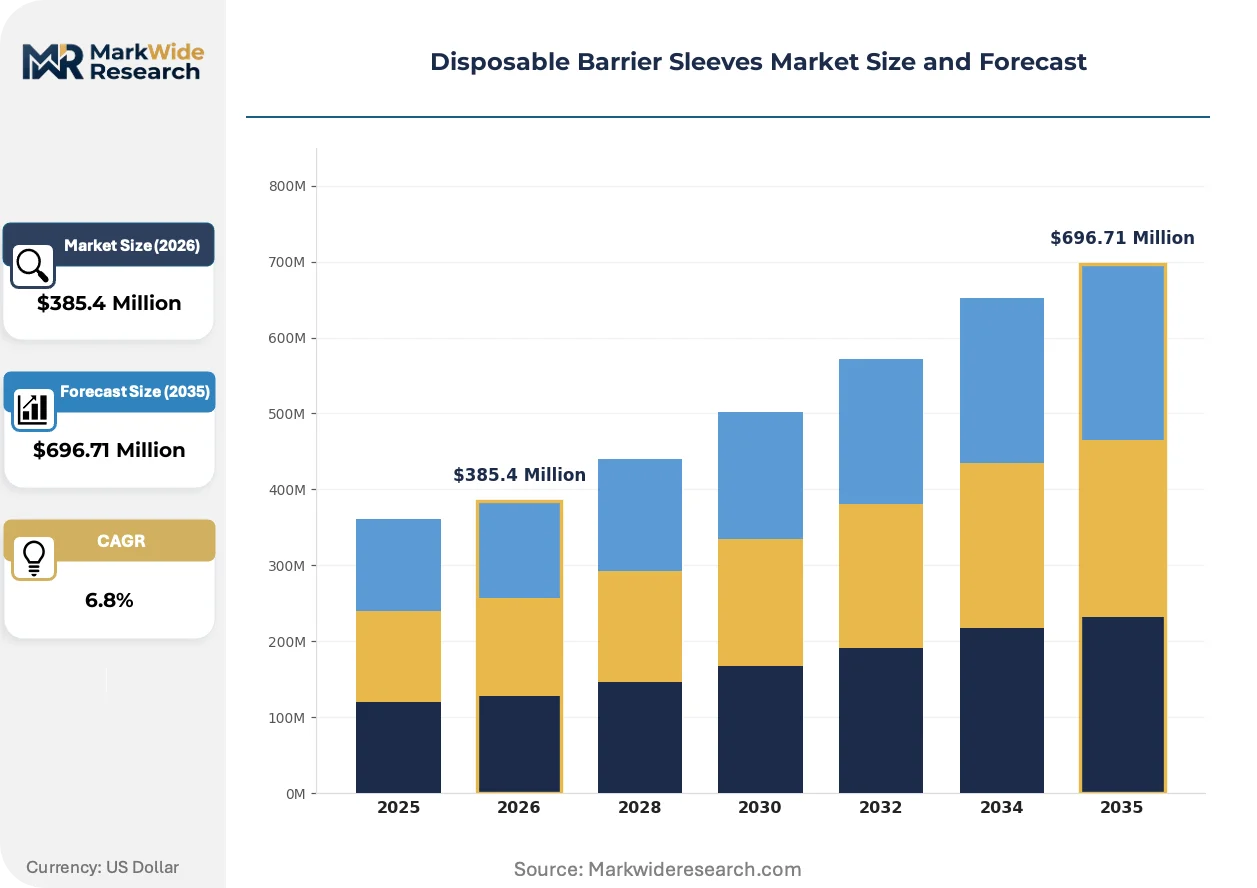
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Latex, Nitrile Application: Healthcare, Food Processing, Industrial, Laboratory Size: Small, Medium, Large, Extra Large End User: Clinics, Hospitals, Manufacturing, Research Facilities |
| Companies Covered | Kimberly-Clark, Medline Industries, 3M, Steripack, Placon, DuPont, Cardinal Health, Bemis, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Barrier Sleeves Market Strategic Shifts
Material science advances and regulatory documentation requirements are reshaping competitive positioning across clinical, food-grade, and industrial barrier sleeve segments. Manufacturers now face simultaneous pressure to reduce environmental footprint while elevating sterility assurance.
Biodegradable polyethylene additives and compostable polypropylene formulations are decentralizing supply chain risk for European and North American manufacturers facing landfill diversion mandates. Food processors in Germany and France are piloting certified compostable sleeves to preempt ECHA restrictions on conventional plastics. This material transition is compressing procurement consolidation around suppliers with dual-certified resin streams.
EPA guidance on single-use plastics and emerging state-level extended producer responsibility frameworks are forcing resin selection changes with immediate procurement consequences. Healthcare distributors in the United States are demanding supplier sustainability scorecards to satisfy institutional purchasing committee requirements. Dental group purchasing organizations in Texas and Florida are now weighting environmental compliance equally with unit price in contract awards.
Direct sourcing from thermoformers is displacing traditional medical distribution intermediaries for high-volume food processing accounts. Regional dairy cooperatives in Wisconsin and California are negotiating annual contracts with Placon and comparable converters, bypassing Medline and McKesson markup structures. This channel compression is most visible in commodity polyethylene applications where certification requirements remain minimal.
Disposable Barrier Sleeves Market Segmentation
Disposable barrier sleeve procurement splits sharply between high-margin clinical certifications and bulk commodity volumes. Understanding where each segment concentrates demand reveals which material specifications and distribution channels capture value.
Product Type:
Polyethylene dominates tonnage while nitrile commands premium positioning in regulated environments.
- Polyethylene:Low-density and linear-low formulations dominate thermoformed sleeve production due to heat-seal compatibility and resin cost economics. Food processors in Wisconsin and California negotiate direct annual contracts with converters, bypassing distributor markups for high-volume procurement.
- Nitrile:Synthetic rubber formulations deliver chemical resistance and tactile sensitivity for dental instrument protection and laboratory handling. FDA device classification requirements elevate documentation burdens, creating competitive moats for certified manufacturers serving hospital purchasing contracts.
- Polypropylene:Higher melting point and rigidity suit applications requiring dimensional stability during steam sterilization cycles. Compostable formulations are piloting in Germany and France to preempt ECHA restrictions.
- Latex:Natural rubber proteins limit adoption to non-clinical industrial barriers where allergic sensitization risks are manageable. Manufacturing plants in Southeast Asia concentrate production capacity.
Mature deployment sits with polyethylene. Newer deployment is concentrated in nitrile.
Application:
Healthcare applications anchor premium pricing while food processing drives scale economies.
- Healthcare:Sterile barrier covers for surgical instruments and dental equipment require lot traceability and ISO 13485 quality management certification. Ambulatory surgery center construction across Texas and Florida sustains above-average procurement volumes.
- Food Processing:Dairy cooperatives and protein packers prioritize cost-per-unit economics over certification depth. Direct sourcing from thermoformers displaces traditional medical distribution intermediaries.
- Industrial:Equipment protection in automotive and electronics assembly relies on commodity polyethylene with minimal regulatory documentation. Reusable silicone alternatives threaten penetration in cost-sensitive settings.
- Laboratory:Documented sterility assurance and chemical compatibility requirements create technically demanding niche demand. Research facilities in Massachusetts and North Carolina weight environmental compliance equally with unit price.
Healthcare claims the steepest expansion trajectory. Food processing holds the volume base.
Size:
Dimensional standardization fragments across legacy equipment footprints versus newer instrument designs.
- Small:Precision dental handpieces and microsurgical instruments drive specification. Custom development requirements fragment production runs.
- Medium:General-purpose clinical and laboratory equipment covers represent the procurement sweet spot for distributor stocking programs.
- Large:Industrial machinery and food processing line components require heavier gauge material to prevent tearing during application.
- Extra Large:Specialized surgical robots and automated processing equipment need custom thermoforming with reinforced seams.
Medium sizes dominate distributor inventory. Extra large is expanding most quickly with automation adoption.
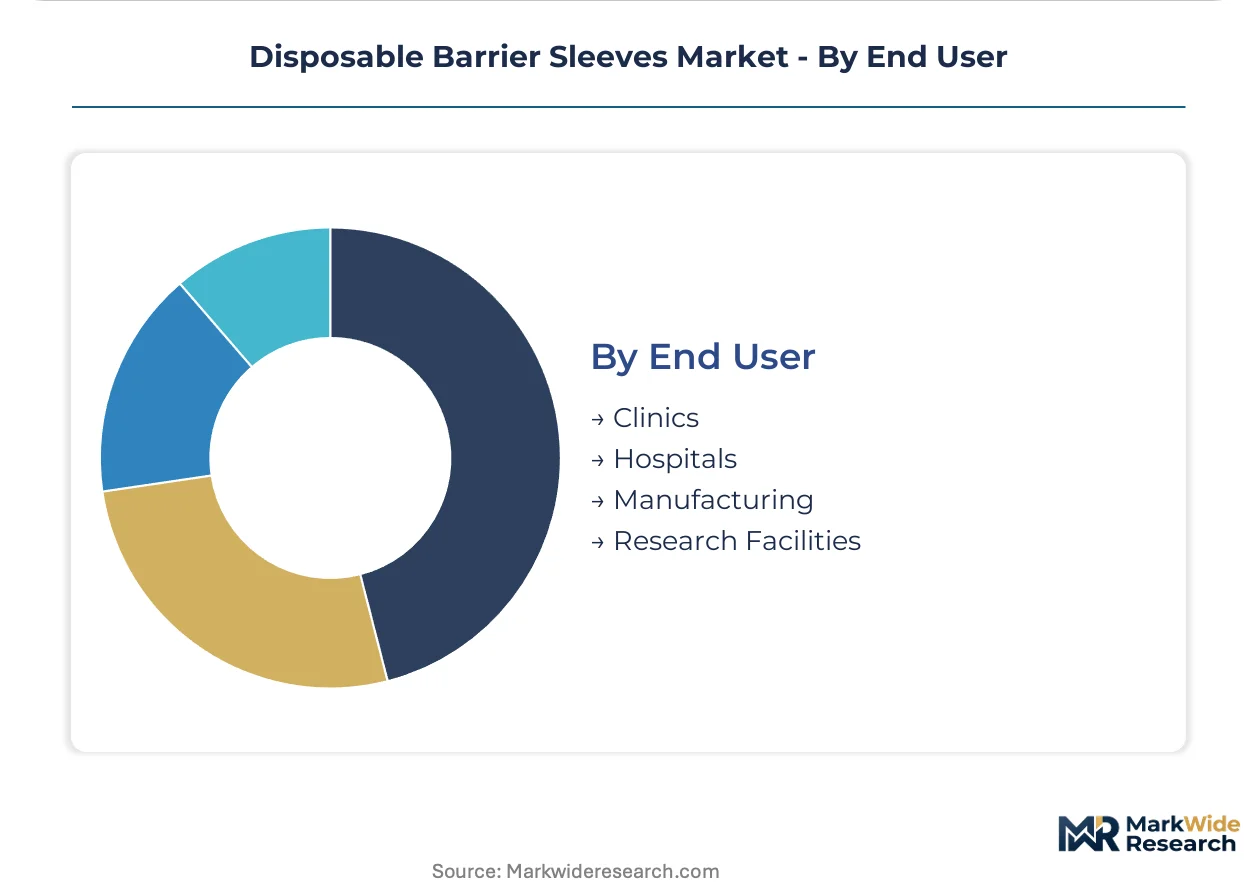
End User:
Institutional procurement committees versus direct manufacturing buyers create divergent purchasing dynamics.
- Clinics:Dental group purchasing organizations in Texas and Florida now weight sustainability scorecards equally with unit pricing. OSHA bloodborne pathogen standards mandate consistent replacement protocols.
- Hospitals:Central supply departments demand certified sterile barriers with full documentation for liability protection. FDA oversight elevates supplier qualification timelines.
- Manufacturing:Food and automotive plants prioritize resin cost stability and supply security over certification depth. Annual contract structures dominate procurement.
- Research Facilities:Academic and government laboratories require documented traceability for grant compliance and reproducibility standards. State-level extended producer responsibility frameworks reshape resin selection.
Hospital systems anchor premium tier deployment. Research facilities are gaining share fastest with quality convergence requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milwaukee anchors North American thermoforming capacity for food-grade polyethylene sleeves, with regional dairy cooperatives negotiating direct annual contracts that bypass traditional distribution markups.
United States
Texas and Florida dental group purchasing organizations now weight sustainability scorecards equally with unit pricing in contract awards. OSHA bloodborne pathogen standards mandate consistent replacement protocols across ambulatory surgery centers. Wisconsin dairy processors concentrate procurement volume for direct converter relationships.
Germany
Food processors in Bavaria pilot certified compostable polypropylene sleeves to preempt ECHA restrictions on conventional plastics. The EU Green Deal accelerates landfill diversion mandates for single-use medical devices. Stuttgart industrial clusters drive demand for chemical-resistant nitrile barriers in precision manufacturing.
China
Southeast Asian thermoforming capacity clustering creates geographic vulnerability for North American distributors sourcing commodity polyethylene. NMPA medical device classifications elevate documentation burdens for clinical-grade suppliers. Yangtze River Delta manufacturing zones concentrate resin conversion for export markets.
France
Parisian hospital central supply departments demand certified sterile barriers with full documentation for liability protection. ECHA REACH compliance requirements reshape resin selection toward bio-based alternatives. Lyon-based food cooperatives test compostable sleeve formulations for dairy packaging lines.
Japan
Tokyo metropolitan dental clinics accelerate single-use protocols under METI workplace safety guidelines. PMDA quality management standards elevate supplier qualification timelines for imported barriers. Osaka industrial zones maintain captive thermoforming for electronics assembly protection.
Disposable Barrier Sleeves Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and distribution channel control. Healthcare-focused suppliers capture value through ISO 13485 documentation and sterile barrier validation, while food-grade converters compete on resin cost stability and annual contract scale. Three archetypes dominate: diversified healthcare conglomerates with captive distribution, specialized thermoformers serving industrial accounts, and regional converters with direct sourcing relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves as players defend position against reusable silicone alternatives.
Within the diversified healthcare tier, Kimberly-Clark and Medline Industries occupy positions that exemplify scale-driven distribution control, with the former anchoring premium clinical segments through established hospital purchasing networks and the latter competing across mid-tier procurement contracts. Placon represents the specialized thermoformer archetype, with its geographic naming convention indicating regional production concentration for food-grade and industrial polyethylene applications.
| Leading Market Players |
|---|
| Kimberly-Clark |
| Medline Industries |
| 3M |
| Steripack |
| Placon |
| DuPont |
| Cardinal Health |
| Bemis |
| Honeywell |
| Others |
Value Chain & Pricing Dynamics
California's extended producer responsibility mandates gate both qualified supply and premium-tier pricing access, forcing manufacturers to document bio-based resin streams before hospital purchasing committees will award contracts above commodity rates. Food processors in Wisconsin negotiate direct annual contracts with thermoformers, bypassing distributor markups entirely for polyethylene volumes where certification requirements remain minimal.
Pricing Analysis
Outcome-based pricing anchors premium clinical tiers, with hospitals paying for documented sterility assurance and lot traceability rather than raw material weight. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified barriers from dental clinic commodities and food-grade polyethylene sleeves. Cost compression in commodity polyethylene intensifies because dairy cooperatives prioritize unit economics over certification depth. Food processors exhibit highest price sensitivity, while hospital central supply departments accept premium positioning for liability protection.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian thermoforming capacity clustering, where resin conversion concentrates for export markets serving North American distributors. Raw material flows draw from Saudi Arabian polyethylene feedstock, Malaysian nitrile rubber production, and German compostable polypropylene formulations. Tariff exposure threatens margin stability for US distributors sourcing commodity sleeves through Yangtze River Delta manufacturing zones. Distribution runs through healthcare GPOs for clinical tiers and direct converter relationships for food processing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable barrier sleeves market sits in a material-transition phase, with compostable polypropylene and biodegradable polyethylene additives displacing conventional resins under landfill diversion mandates.
For Market Incumbents: Acquire thermoforming capacity in the US Midwest to anchor direct sourcing relationships with dairy cooperatives and protein packers. Secure backward integration into bio-based resin streams before ECHA restrictions tighten in Germany and France. Reusable silicone alternatives threaten commodity-tier penetration in cost-sensitive industrial settings. For New Entrants and Emerging Players: Enter via home healthcare retail channels, where remote patient monitoring device protection creates demand outside institutional procurement committees. Target laboratory end users in Massachusetts and North Carolina, where documented traceability requirements pull certified suppliers into technically demanding niches. Lead with sustainability scorecards weighted equally with unit pricing. For Investors and Strategic Acquirers: FDA 510(k) clearance timelines extending beyond 18 months is the leading indicator that material science innovators with validated sterilization protocols will command acquisition premiums. Five-to-ten year viability favors suppliers with dual-certified resin streams serving both clinical and compostable food-grade applications. Watch for state-level extended producer responsibility framework adoption as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Resin Certification | California and New York EPR mandates force resin selection changes with immediate procurement consequences. |
| Direct Converter Relationships | Wisconsin dairy cooperatives bypass Medline and McKesson markups through annual thermoformer contracts. |
| ISO 13485 Quality Convergence | Laboratory end users in Massachusetts pull certified suppliers into technically demanding niche segments. |
| Compostable Formulation Piloting | German and French food processors preempt ECHA restrictions with certified compostable sleeve testing. |
| Ambulatory Surgery Center Partnerships | Texas and Florida facility expansion sustains above-average procurement volumes for sterile barrier covers. |
Study Parameters
FDA 510(k) filings, OSHA regulatory guidance documents, and hospital procurement databases formed the secondary backbone, supplemented by customs records tracking polyethylene and nitrile resin trade flows. Primary interviews with dental group purchasing organization managers, biomedical engineers at ambulatory surgery centers, thermoformer operations directors, and food processing procurement leads validated demand assumptions. Bottom-up and top-down triangulation cross-checked unit volume estimates against resin consumption data and distributor stocking patterns.
Bottom-up modeling built from product-level specifications across material type, application, and end-user segments, then aggregated to market totals. Segmentation dimensions included polyethylene versus nitrile versus polypropylene formulations, healthcare versus food processing versus industrial versus laboratory applications, and clinic versus hospital versus manufacturing versus research facility end users. CAGRs were derived from installed base growth rates, replacement protocol frequency changes, and ambulatory surgery center construction pipelines. Feedstock price volatility and extended producer responsibility framework adoption curves served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid biodegradable material adoption or sudden polyethylene resin cost spikes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Heat Seal Coating Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Tray Liners Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Specialty Films Market