
 LDPE and LLDPE Sealant Web Films Market | 2026-2036
LDPE and LLDPE Sealant Web Films Market Size, Share, and Industry Trends Forecast 2026-2036
LDPE and LLDPE Sealant Web Films Market Foresight
Polyethylene terephthalate (PET) is rebalancing sealant web economics as converters evaluate total laminate cost against performance thresholds. Dow Inc. leverages its upstream ethylene integration to secure feedstock cost advantages across North American flexible packaging lines. Berry Global Inc. anchors its position through blown film capacity concentrated near Midwestern US food processing corridors. SABIC competes via specialized metallocene LLDPE grades engineered for high-speed form-fill-seal equipment.
LDPE and LLDPE sealant web films constitute coextruded or monolayer polyethylene structures, typically ranging from 20 to 80 microns, designed to deliver heat-seal initiation temperatures between 95°C and 115°C for lamination to oriented substrates. Their primary purpose is to provide hermetic closure integrity in flexible packaging while maintaining optical clarity and puncture resistance. Multi-layer films capture margin pools where barrier properties justify premium positioning over monolayer alternatives. Food packaging dominates volume consumption as retail-ready formats displace rigid containers across fresh produce and frozen protein categories.
REACH registration requirements and FDA food-contact notification protocols govern monomer migration limits and additive compositions, compelling reformulation of slip and anti-block packages. EFSA evaluates new substance petitions for polyethylene additives on timelines that can delay European product introductions by eighteen to thirty-six months. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in California and New York that will reshape post-consumer collection economics for polyethylene packaging structures.
Market Dynamics
Multi-layer coextrusion technology is compressing sealant film economics as converters consolidate gauge structures to reduce resin consumption per thousand square feet of packaged goods.
Growth Catalysts
- E-commerce grocery fulfillment:Fresh and frozen food delivery networks in Germany, China, and Brazil require puncture-resistant sealant webs that withstand automated handling. Converter investments in high-speed form-fill-seal lines accelerate specification upgrades.
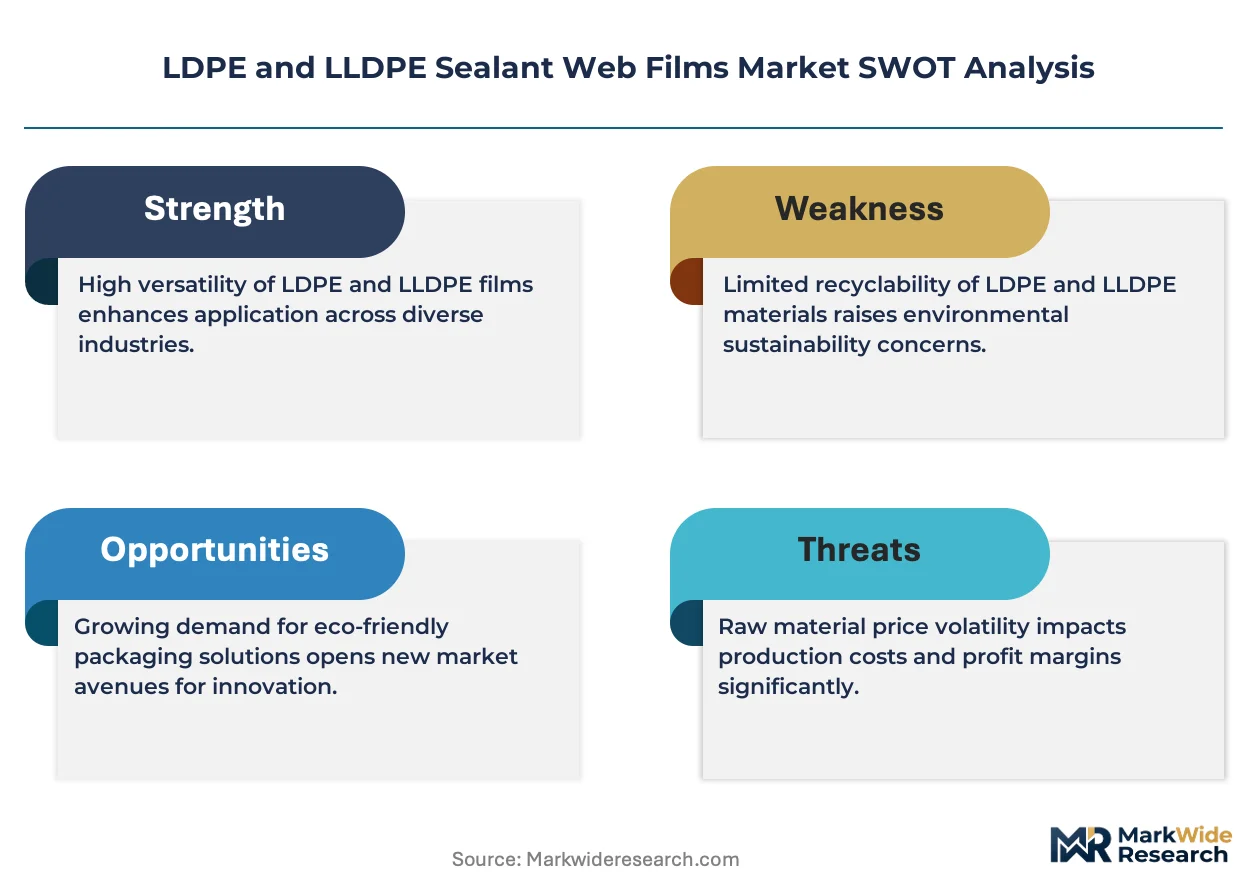
- REACH substance registration:ECHA compliance deadlines are forcing additive package reformulations that favor compliant LLDPE grades over legacy LDPE alternatives with restricted slip agents.
- Metallocene catalyst advances:Narrow molecular weight distribution resins deliver seal initiation temperatures below 100°C, enabling faster line speeds for dairy and bakery packaging applications.
Market Restraints
- Ethylene feedstock volatility:Naphtha and ethane price swings in US Gulf Coast and Middle Eastern supply corridors compress margin predictability for non-integrated film producers.
- Barrier property ceiling:Polyethylene sealant webs lack intrinsic oxygen and moisture barrier performance, requiring lamination to EVOH or metallized substrates that add cost and complexity.
- California EPR framework:State-level extended producer responsibility legislation is reshaping post-consumer collection economics, creating compliance cost uncertainty for flexible packaging structures.
Strategic Opportunities
- India food processing corridor expansion:FSSAI-mandated packaging safety standards and cold chain investments in Maharashtra and Gujarat create specification upgrade demand for imported metallocene grades.
- Mono-material recyclable structures:CEFLEX and How2Recycle guidelines favor all-polyethylene laminates that eliminate incompatible substrate layers from post-consumer recycling streams.
- Digital printing convergence:HP Indigo and BOBST press installations enable short-run customized graphics on sealant webs, collapsing minimum order quantities for regional food brands.
Industry Challenges
- Multi-layer extrusion technician scarcity:Operating precision coextrusion lines with 5+ layers requires specialized die gap calibration skills that outpace vocational training pipeline output in Midwestern US manufacturing zones.
- FDA food-contact notification timelines:New additive petitions face eighteen-to-thirty-six-month evaluation periods that delay product launches for innovative anti-fog or slip packages.
- Legacy lamination asset stranding:Solvent-based adhesive coating lines face air quality enforcement in California's San Joaquin Valley, forcing premature capital redeployment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LDPE and LLDPE Sealant Web Films Market |
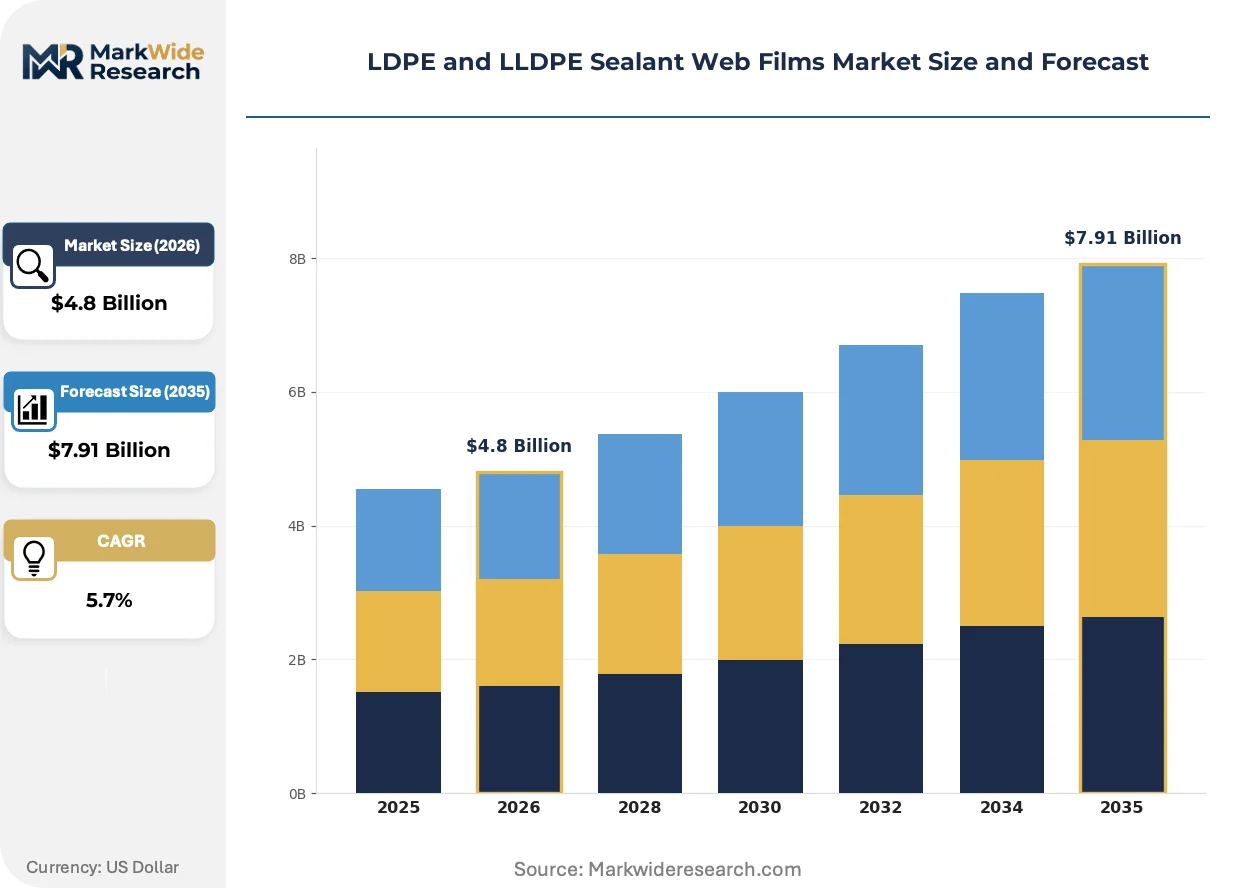
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LDPE Film, LLDPE Film, Bilingual Films, Multi-layer Films End Use Industry: Food Packaging, Medical Supplies, Consumer Goods, Industrial Applications Thickness: Thin, Medium, Thick, Ultra-thin Application: Flexible Packaging, Shrink Wrap, Surface Protection, Agricultural Films |
| Companies Covered | Mondi Group, Jindal Poly Films, Berry Global Inc., SABIC, Dow Inc., Amcor plc, Coveris Holdings S.A., ExxonMobil Corporation, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LDPE and LLDPE Sealant Web Films Market Shifts & Advancements
Sealant web formulation is pivoting toward circular design principles as mechanical recycling infrastructure and chemical recycling pilot plants reshape resin quality specifications and additive selection criteria.
Metallocene LLDPE is overtaking conventional Ziegler-Natta resins in high-speed form-fill-seal applications. Dairy and fresh produce packagers in Germany and the Netherlands specify these grades for seal integrity at reduced temperatures. The shift is compressing demand for legacy LDPE sealant layers in premium flexible packaging segments.
EFSA additive re-evaluation programs are tightening migration limits for polyethylene contact materials. Manufacturers must reformulate anti-block and slip packages to maintain compliance across European retail supply chains. Frozen protein and ready-meal segments face the steepest reformulation timelines as notified body certification gates tighten.
Direct-to-retail procurement models are consolidating buyer power among German and Brazilian supermarket chains. National account specifications now mandate recycled content thresholds and recyclability certifications that smaller converters struggle to meet. This concentration is visible in São Paulo's food packaging cluster where three retail groups control sixty percent of flexible film purchasing decisions.
LDPE and LLDPE Sealant Web Films Market Segmentation
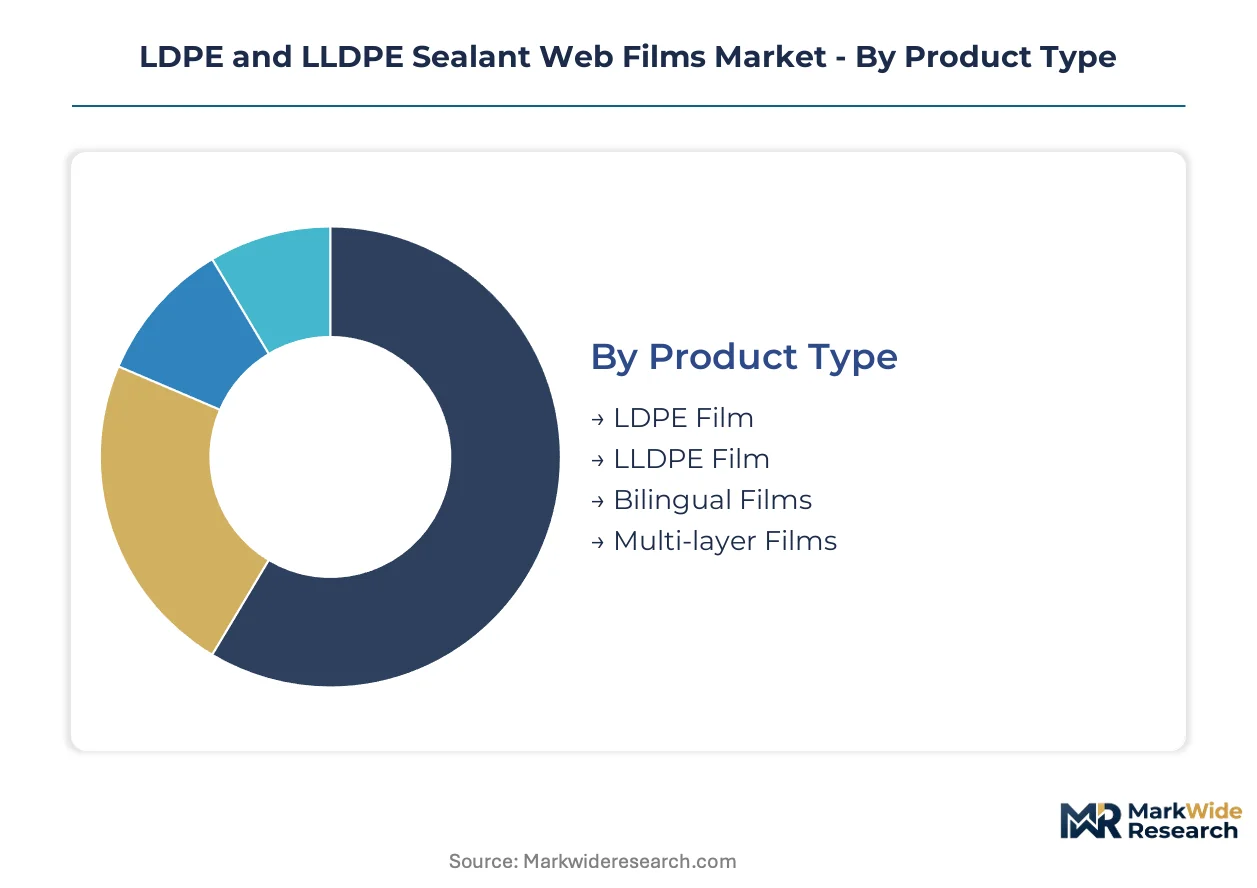
Sealant web film specifications diverge sharply across end-use requirements, with converter investments in multi-layer extrusion lines driving specification fragmentation. Product type and thickness selections directly determine heat-seal performance, barrier integration, and recyclability compliance across food, medical, and industrial packaging formats.
Product Type:
Converters are upgrading from legacy monolayer structures to engineered multi-layer configurations as form-fill-seal line speeds advance and regulatory migration limits tighten.
- LDPE Film:Conventional low-density polyethylene delivers seal initiation temperatures between 95°C and 105°C through branched molecular architecture. Demand concentrates in cost-sensitive frozen protein packaging across Brazilian supermarket chains where legacy equipment dominates converter floors.
- LLDPE Film:Linear low-density polyethylene incorporates alpha-olefin comonomers to enhance puncture resistance and dart impact strength. German dairy packagers specify metallocene-catalyzed grades for high-speed lines running above 200 packages per minute.
- Bilingual Films:Dual-resin formulations blend LDPE processability with LLDPE toughness for intermediate performance tiers. These structures serve Midwestern US meat processing corridors requiring cold-temperature seal integrity without full metallocene grade premiums.
- Multi-layer Films:Coextruded five-to-nine-layer structures integrate tie layers and barrier polymers for modified atmosphere packaging. EVOH-compatible sealant webs command specification priority in European ready-meal segments.
Volume placements concentrate in LLDPE Film; the faster expansion belongs to Multi-layer Films.
End Use Industry:
Regulatory notification timelines and contamination risk thresholds create divergent margin structures across consumer-facing versus industrial applications.
- Food Packaging:Hermetic closure requirements for fresh produce, frozen proteins, and bakery items drive specification complexity. EFSA migration limit enforcement and FDA food-contact notifications govern additive package selection for direct-contact layers.
- Medical Supplies:Sterile barrier systems for device packaging require validated seal strength consistency and particulate contamination controls. ISO 11607 compliance mandates documented seal peel characteristics across sterilization modalities.
- Consumer Goods:Personal care and household product overwrap emphasizes optical clarity and shelf appeal over barrier performance. Digital printing compatibility is displacing rotogravure specifications for short-run regional brand launches.
- Industrial Applications:Pallet unitization and component protection films prioritize load containment and UV stability. These segments tolerate wider gauge tolerances and higher reclaimed content ratios than food-contact grades.
Food Packaging commands the dominant placement volume; Medical Supplies is climbing the fastest on sterilization validation requirements.
Thickness:
Gauge reduction initiatives and downgassing compliance pressures are compressing median thickness selections while ultra-thin segments face equipment capability constraints.
- Thin:Twenty-to-thirty-micron structures serve lightweight overwrap and liner applications where puncture demands remain modest. Chinese e-commerce fulfillment networks specify these gauges for apparel and consumer electronics protection.
- Medium:Thirty-to-fifty-micron films balance processability across standard form-fill-seal equipment with adequate abuse resistance. This tier captures the majority of European retail-ready produce bag specifications.
- Thick:Fifty-to-eighty-micron grades deliver puncture resistance for bone-in meat and frozen seafood with irregular geometries. Brazilian protein exporters specify thick sealant webs for ocean freight containerization.
- Ultra-thin:Sub-twenty-micron experimental gauges target source reduction mandates and EPR compliance frameworks. California extended producer responsibility legislation is accelerating converter trials despite bubble stability challenges on high-speed lines.
Medium thickness dominates current converter commitments; Ultra-thin is gaining share fastest on circular design imperatives.
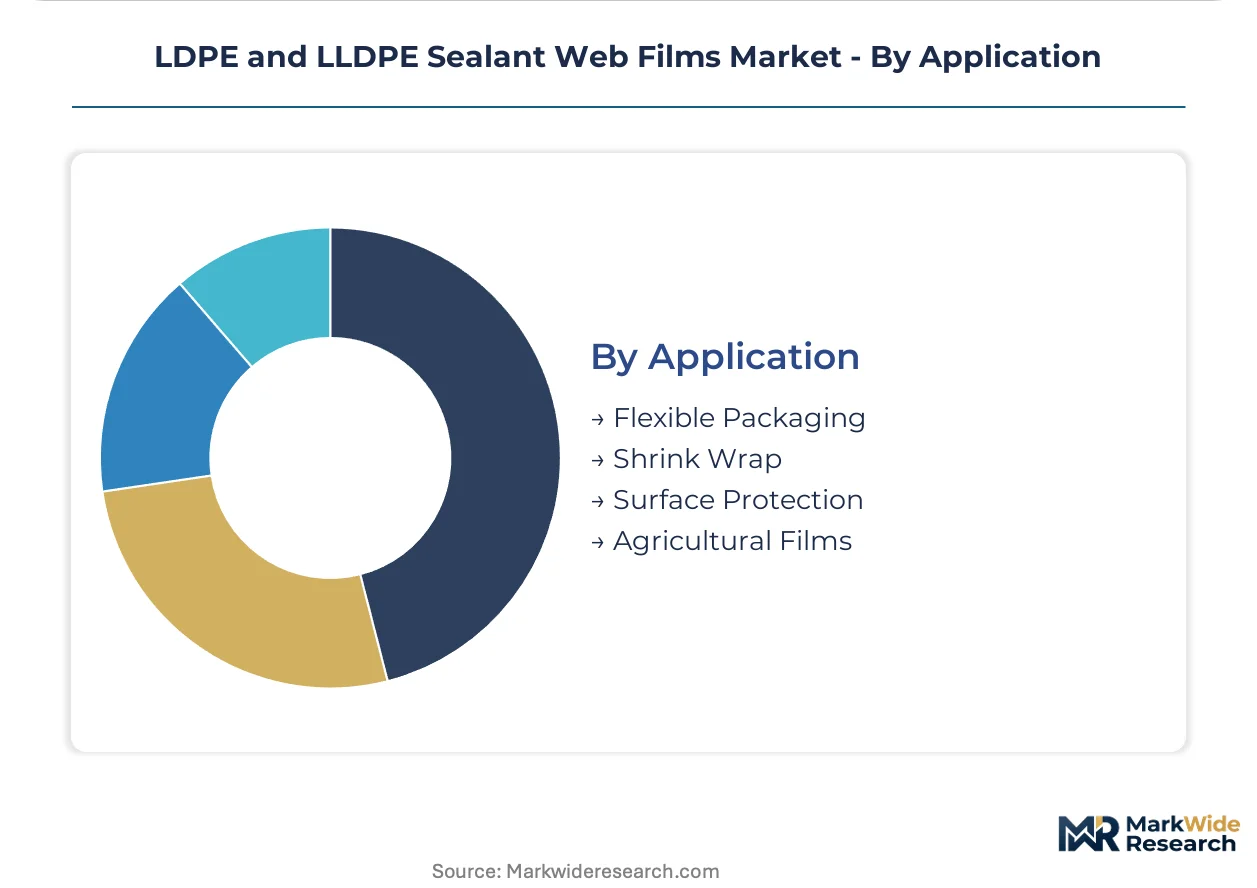
Application:
Equipment retrofit cycles and substrate lamination requirements determine application-level specification stickiness and switching costs.
- Flexible Packaging:Laminated pouch and bag structures constitute the core demand pool, integrating sealant webs with oriented PET or PA substrates. CEFLEX design guidelines favor all-polyethylene constructions compatible with existing mechanical recycling infrastructure.
- Shrink Wrap:Biaxially oriented and heat-shrinkable formulations require controlled shrink force characteristics for pallet stability. These applications tolerate higher seal initiation temperatures than food-contact flexible packaging.
- Surface Protection:Temporary adhesive-backed films for appliance and automotive component guarding emphasize clean peel and residue-free removal. These specifications prioritize clarity and lay-flat over seal performance.
- Agricultural Films:Greenhouse and mulch applications incorporate UV stabilizers and anti-drip additives for extended field service life. Soil contact exemptions reduce migration limit scrutiny compared to food packaging.
Flexible Packaging anchors volume commitments; Surface Protection is expanding most quickly on electronics manufacturing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter demand concentrates in Germany, China, Brazil, and the United States, where food processing clusters and e-commerce fulfillment networks drive specification upgrades for puncture-resistant sealant webs. Regulatory divergence across REACH, FDA, and state-level EPR frameworks is fragmenting formulation requirements.
United States
Midwestern meat processing corridors in Iowa and Illinois anchor converter demand for cold-temperature seal integrity. FDA food-contact notification protocols govern additive compositions for direct-contact layers. Berry Global Inc. concentrates blown film capacity near these food processing zones to reduce logistics costs.
Germany
Dairy and ready-meal packagers specify metallocene LLDPE grades for form-fill-seal lines exceeding 200 packages per minute. EFSA migration limit enforcement and ECHA REACH compliance deadlines are forcing additive package reformulations. The Ruhr industrial cluster hosts multi-layer extrusion investments serving pan-European retail chains.
China
E-commerce grocery fulfillment networks in Shanghai and Shenzhen require puncture-resistant webs for automated handling systems. GB standards and SAMR regulations govern food-contact material safety. Yangtze River Delta converters are installing high-speed lines to serve fresh produce delivery platforms.
Brazil
Supermarket chains in São Paulo control sixty percent of flexible film purchasing decisions through direct-to-retail procurement consolidation. ANVISA regulates food-contact packaging safety for protein exports. Southeastern converter clusters serve ocean freight containerization demand for bone-in meat and frozen seafood.
India
Cold chain investments in Maharashtra and Gujarat are creating specification upgrade demand for imported metallocene grades. FSSAI-mandated packaging safety standards tighten migration limits for direct food contact. Mumbai-Pune industrial corridor converters are trialing multi-layer structures for dairy and bakery applications.
LDPE and LLDPE Sealant Web Films Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated resin producers capturing margin pools in high-specification grades while regional converters dominate commodity volumes. The vendor base arranges into three tiers: upstream-integrated petrochemical majors, mid-scale blown film specialists, and toll-coating converters serving private-label brands. Two dominant competitive moves are reshaping positions: backward integration into ethylene feedstock and strategic partnerships with form-fill-seal equipment OEMs.
Within the integrated petrochemical tier, Dow Inc. and SABIC exemplify upstream-backed positioning through captive ethylene supply. Berry Global Inc. occupies a position among North American blown film specialists with capacity concentrated near food processing demand centers. These three companies represent divergent archetypes: Dow anchors resin-to-film integration, SABIC exemplifies specialized metallocene grade development, and Berry Global illustrates geographic proximity strategies for perishable goods logistics.
| Leading Market Players |
|---|
| Mondi Group |
| Jindal Poly Films |
| Berry Global Inc. |
| SABIC |
| Dow Inc. |
| Amcor plc |
| Coveris Holdings S.A. |
| ExxonMobil Corporation |
| Sealed Air Corporation |
| Others |
Supply & Pricing Matrix
Metallocene grade certification splits the LDPE and LLDPE sealant web market into divergent pricing and sourcing configurations, with FDA food-contact notification tiers and EFSA migration compliance creating procurement ladders that reshape converter supplier relationships and inventory strategies across Germany, China, and Brazil.
Pricing Analysis
Volume placements concentrate in commodity LLDPE grades where per-kilogram margins compress under ethylene feedstock volatility, while metallocene-certified tiers command premiums through seal initiation temperature performance and FDA notification documentation. Price differentiation rests on catalyst technology tier and migration limit certification, with German dairy packagers least sensitive and Brazilian frozen protein converters most price-responsive. Cost compression in legacy LDPE segments is intensifying because REACH-compliant additive reformulations raise formulation expenses.
Supply Chain Analysis
FDA food-contact notification and EFSA additive re-evaluation programs gate supplier qualification, concentrating certified resin supply in the United States, Germany, and Saudi Arabia where Dow Inc., SABIC, and integrated petrochemical majors control upstream ethylene and metallocene catalyst production. Raw material dependencies center on naphtha and ethane feedstocks, metallocene catalyst systems, and compliant anti-block additive packages. Single-source vulnerability runs through Middle Eastern ethane supply corridors. Distribution feeds from regional blown film clusters near Midwestern US meat processing zones and Ruhr industrial converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LDPE and LLDPE sealant web market operates as a cost-of-compliance story where EFSA migration limit enforcement and FDA food-contact notification timelines erect eighteen-to-thirty-six-month barriers that protect incumbent positions from fast-follower competition.
For Market Incumbents: Lock in metallocene grade supply agreements with form-fill-seal equipment OEMs to secure specification lock-in as line speeds advance past 200 packages per minute. Deepen backward integration into ethylene feedstock to defend margin position against naphtha price swings in US Gulf Coast corridors. Prioritize EFSA pre-notification additive packages to compress European product introduction timelines. For New Entrants and Emerging Players: E-commerce fulfillment platform procurement portals offer direct specification influence routes into Chinese fresh produce delivery networks and Indian cold chain investments. Target Maharashtra and Gujarat converter clusters where FSSAI-mandated standards create upgrade demand for imported metallocene grades absent domestic supply. Lead with digital printing compatibility certifications to capture short-run regional brand launches. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale blown film specialists possessing EVOH-compatible multi-layer extrusion capability given CEFLEX mono-material recyclable structure tailwinds. Five-to-ten-year viability favors converters with documented FDA master files and EFSA notified body relationships. Watch California EPR framework implementation timelines as inflection indicators for post-consumer collection economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Dow Inc.'s upstream integration secures margin stability against naphtha volatility in Gulf Coast supply corridors. |
| Metallocene Catalyst Technology Licensing | SABIC's specialized grade development captures specification priority in German dairy packaging lines exceeding 200 ppm. |
| Multi-layer Extrusion Capacity Expansion | Berry Global's Midwestern US proximity strategy reduces logistics costs for Iowa and Illinois meat processing zones. |
| FDA Food-Contact Notification Investment | Documented master files compress eighteen-to-thirty-six-month evaluation timelines for innovative anti-fog additive packages. |
| Digital Printing Compatibility Certification | HP Indigo and BOBST press validations enable short-run customized graphics for regional food brand procurement. |
Research Methodology
Document review covered FDA food-contact notification databases, EFSA additive re-evaluation registers, and REACH substance registration filings, complemented by interviews with blown film plant managers, flexible packaging procurement leads at German supermarket chains, metallocene catalyst R&D directors, and form-fill-seal equipment OEM technical specialists. Secondary validation drew from customs and trade data, SEC 10-K resin segment disclosures, and CEFLEX design guideline documentation. Bottom-up converter capacity assessments and top-down ethylene derivative demand modeling enabled triangulation.
Segment-level volume and value trajectories emerged from product type, end-use industry, thickness tier, and application-specific elasticity modeling across the projection horizon. Analytical frameworks incorporated heat-seal initiation temperature performance curves, migration limit compliance cost functions, and e-commerce fulfillment network expansion rates. CAGRs derived from regression against historical flexible packaging demand correlations and converter investment cycle timing.
The model holds under stable ethylene feedstock pricing and regulatory notification timeline baselines; deviation in EFSA re-evaluation acceleration or California EPR enforcement stringency would shift volume trajectories. Forecasts reflect documented assumptions about metallocene grade adoption curves and multi-layer extrusion line installation rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Barrier Coatings for Packaging Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market