
 72 Inch Paint Protection Film Market | 2026-2036
72 Inch Paint Protection Film Market Size, Share, and Industry Trends Forecast 2026-2036
72 Inch Paint Protection Film Market Intelligence
Buyer concentration among professional installers and automotive dealers is shifting as independent detail shops multiply across suburban markets. XPEL Inc. leverages its training academy network to anchor installer loyalty in North America. Avery Dennison Corporation competes through color-matched film portfolios that extend beyond clear protection into aesthetic customization. Saint-Gobain S.A. dominates European supply through captive TPU resin production and OEM certification programs.
72 Inch Paint Protection Film denotes a thermoplastic urethane or polyvinyl chloride sheet, typically 6 mil to 8 mil thick, engineered with a self-healing elastomeric topcoat and pressure-sensitive acrylic adhesive for bonding to painted vehicle surfaces. The film absorbs stone chip impact and UV degradation while maintaining optical clarity. Self-healing formulations command premium positioning due to thermal-repair chemistry that eliminates swirl marks. Hydrophobic variants are gaining fastest in marine and high-end residential applications where water spotting resistance differentiates service tiers. TPU material continues to displace PVC in professional channels as thermal stability and conformability around complex body lines improve margin pools for certified installers.
The EPA oversees VOC emissions from adhesive solvents used in film manufacturing, pushing producers toward water-based coating systems. REACH compliance in Europe restricts certain phthalate plasticizers in PVC formulations, accelerating TPU migration. China's MEE enforces stricter environmental audits on petrochemical feedstock suppliers, tightening resin availability. Stakeholders must monitor raw material certification pipelines and regional compliance timelines to secure uninterrupted market access.
Market Dynamics
Factory-applied PPF programs at luxury automotive OEMs are compressing the aftermarket installation window while elevating material specifications across the entire supply chain. This OEM pull-through is forcing TPU resin producers and film converters to synchronize certification timelines with vehicle launch cycles.
Growth Catalysts
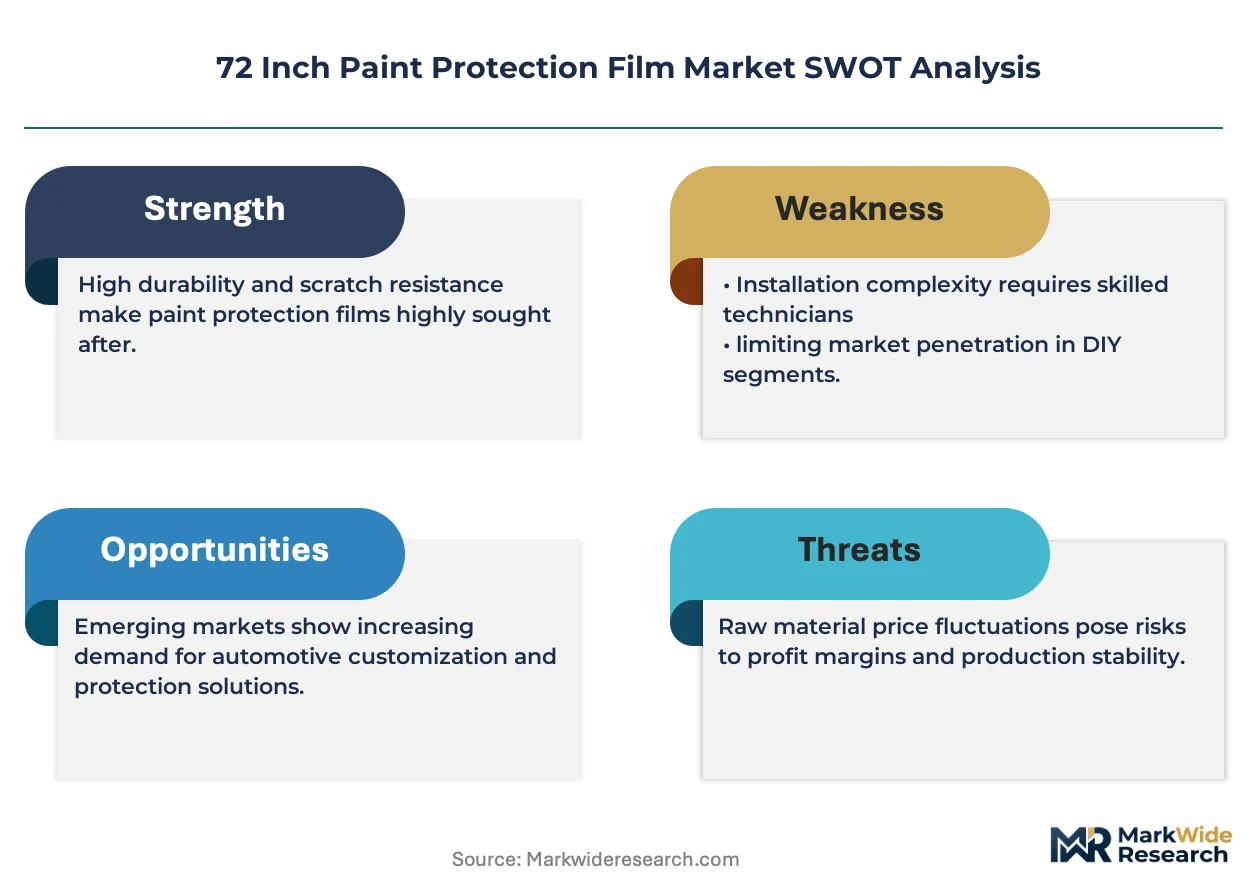
- REACH plasticizer restrictions:ECHA's phasing of phthalate additives in PVC formulations accelerates TPU material substitution across European professional channels.
- Self-healing topcoat chemistry:Thermal-repair elastomeric formulations eliminate swirl marks without heat gun intervention, commanding premium positioning in detail shop networks.
- China's premium vehicle sales:MEE environmental audits on petrochemical feedstock suppliers tighten domestic resin availability, favoring certified importers with established supply pipelines.
Market Restraints
- Aliphatic TPU resin concentration:Three specialized polymer producers control optical-grade feedstock supply, creating single-source vulnerability for film converters.
- EPA VOC emission limits:Adhesive solvent regulations force capital-intensive water-based coating system conversions at manufacturing facilities.
- Paint correction dependency:Surface preparation requirements before PPF installation limit same-day service economics and compress installer throughput.
Strategic Opportunities
- Marine superyacht finishing:Hydrophobic PPF variants address saltwater spotting resistance in Mediterranean and Caribbean refit yards.
- Residential architectural glass:UV-degradation protection films migrate from automotive to high-end glazing applications in coastal markets.
- IRA clean vehicle credits:US domestic content incentives for EV manufacturing extend to supplier certification programs, opening OEM qualification pathways.
Industry Challenges
- Certified installer scarcity:XPEL's training academy model requires months-long skill development, constraining network expansion velocity.
- Adhesive climate calibration:Pressure-sensitive acrylic formulations demand regional viscosity adjustments, complicating inventory management across temperature zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 72 Inch Paint Protection Film Market |
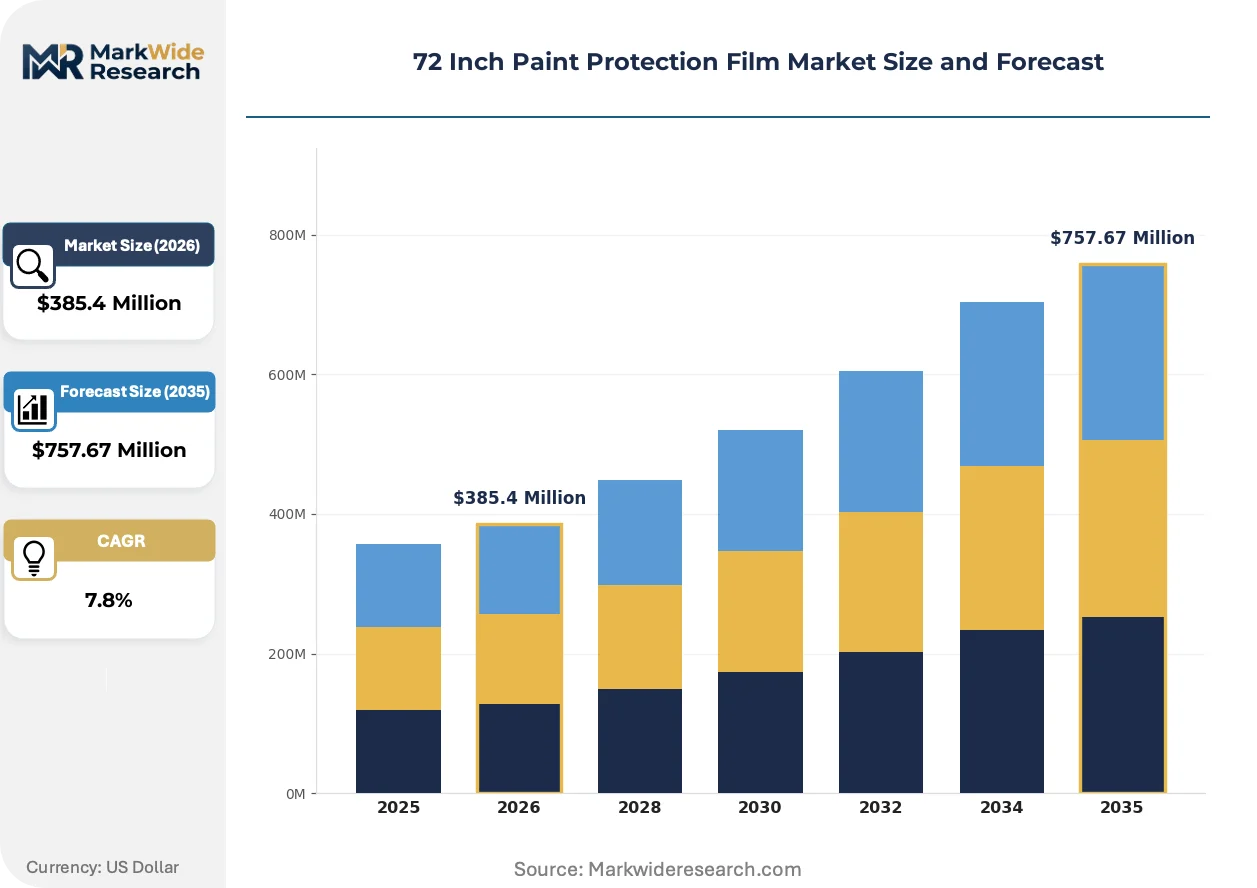
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Healing, Hydrophobic, Gloss, Matte Application: Automotive, Residential, Commercial, Marine Material: PVC, TPU, Polyurethane, Vinyl End User: DIY Enthusiasts, Professional Installers, Automotive Dealers, Retailers |
| Companies Covered | Avery Dennison Corporation, STEK Automotive, 3M Company, Schweitzer-Mauduit International, Inc., HEXIS S.A., XPEL Inc., Saint-Gobain S.A., ORAFOL Europe GmbH, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
72 Inch Paint Protection Film Market Strategic Shifts & Innovations
Precision cutting systems and digital templating are eliminating material waste while compressing installation labor hours. These workflow innovations are reshaping how professional detail shops structure service pricing and technician deployment.
Computer-vision measurement systems paired with robotic plotters are automating pattern generation for complex body panels. Certified installers in Germany and the United States are adopting these systems fastest, reducing film waste from fifteen percent to under four percent per vehicle. This automation is compressing the labor component of installation quotes while elevating throughput capacity per bay.
REACH compliance deadlines for phthalate-free formulations are forcing PVC film producers to reformulate or exit professional channels entirely. European converters face eighteen-month recertification cycles with OEM partners. TPU suppliers with pre-validated optical-grade resins capture displaced volume as brand-agnostic installers switch material specifications.
Buyer preference is fragmenting between factory-integrated protection and independent aftermarket installation. Luxury vehicle purchasers in China increasingly specify PPF at point of sale, bypassing detail shop networks entirely. This channel rotation is visible in Shanghai and Shenzhen dealership data, where paint protection attachment rates now exceed ceramic coating penetration by a widening margin.
72 Inch Paint Protection Film Market Segmentation
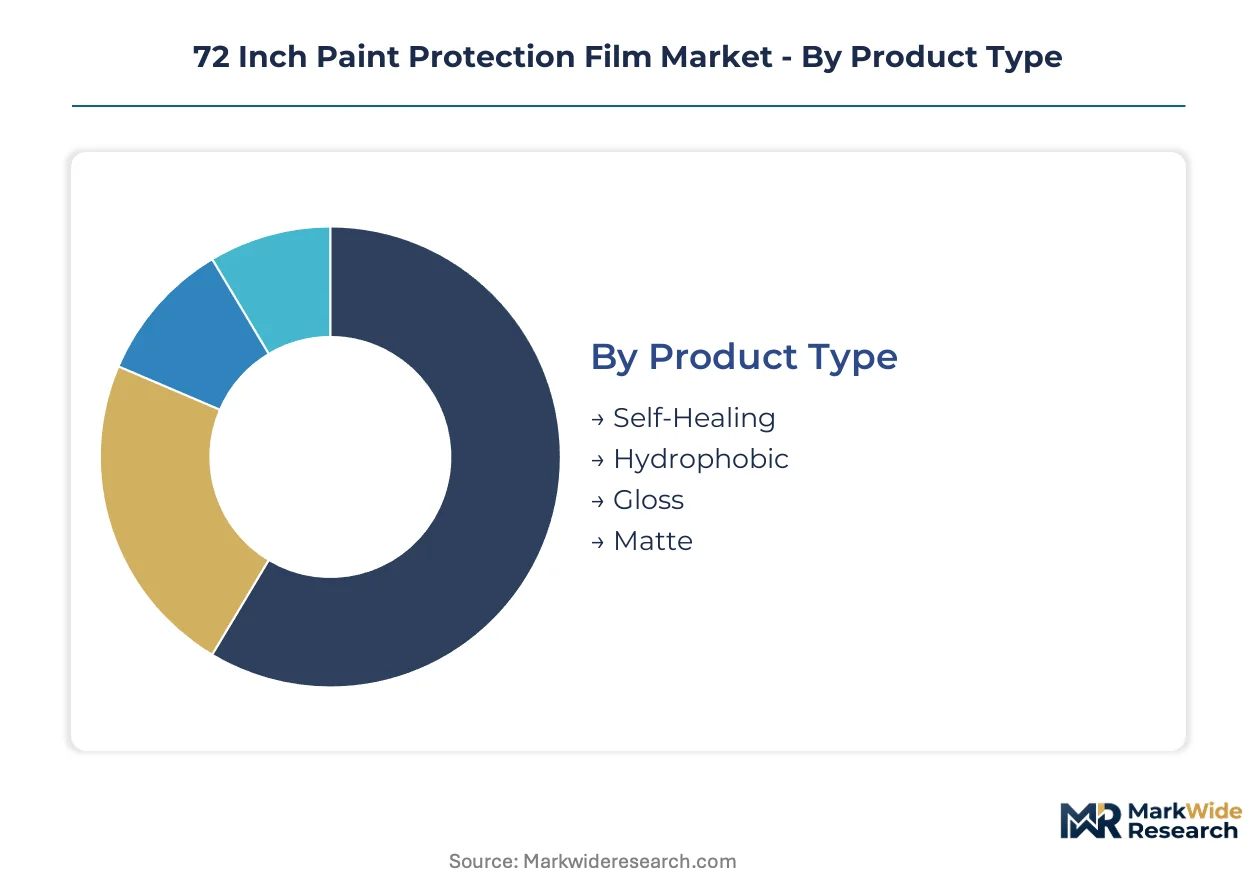
Product differentiation in paint protection film hinges on installer certification tiers and surface performance specifications. Material chemistry and application channel segmentation determine margin capture across factory-applied and aftermarket service models.
Product Type:
Installer certification level and warranty backing drive product selection more than upfront material cost.
- Self-Healing:Thermal-repair elastomeric topcoats eliminate swirl marks through ambient heat or sun exposure without mechanical intervention. Detail shops in Germany and the United States specify these formulations for luxury vehicle clientele demanding flawless optical clarity over multi-year ownership cycles. Premium positioning reflects extended warranty terms and factory-backed certification requirements.
- Hydrophobic:Fluoropolymer-modified surfaces repel water spotting and salt accumulation through reduced surface tension. Marine refit yards in Florida and Mediterranean ports specify these variants for superyacht finishing where saltwater exposure demands differentiated service tiers.
- Gloss:High-clarity optical-grade TPU maintains factory paint reflectance for show vehicle and collector car applications.
- Matte:Satin-finish formulations match factory matte paint programs at BMW, Mercedes-Benz, and Porsche without altering surface texture.
Self-healing formulations lead on scale; hydrophobic variants gain share fastest in coastal marine channels.
Application:
Channel structure varies dramatically by installation environment and regulatory exposure.
- Automotive:Factory-applied programs at luxury OEMs compress aftermarket installation windows while elevating material specifications. China's premium vehicle purchasers increasingly specify PPF at point of sale in Shanghai and Shenzhen dealerships, bypassing independent detail networks entirely.
- Marine:Saltwater spotting resistance commands premium pricing in Mediterranean and Caribbean refit yards where superyacht owners demand multi-season optical performance.
- Residential:UV-degradation protection migrates from automotive glazing to high-end architectural glass in coastal California and Florida markets.
- Commercial:Fleet protection programs for luxury transportation and rental vehicle operators emphasize throughput economics over individual vehicle aesthetics.
Automotive channels dominate revenue concentration; marine applications show steepest expansion trajectory in refit yard procurement.
Material:
REACH compliance deadlines and thermal stability requirements are accelerating chemistry transitions.
- TPU:Aliphatic thermoplastic urethane delivers superior conformability around complex body lines and thermal stability across climate zones. ECHA phthalate restrictions on PVC formulations displace competing materials across European professional channels as converters face eighteen-month OEM recertification cycles.
- PVC:Legacy formulations face forced exit from certified installer networks due to plasticizer regulatory pressure and inferior thermal performance.
- Polyurethane:Cast urethane variants serve specific OEM factory-applied programs requiring batch-to-batch color consistency.
- Vinyl:Cost-positioned alternatives retain presence in DIY retail channels outside professional certification requirements.
TPU commands professional channel volume; polyurethane maintains OEM factory-program exclusivity.
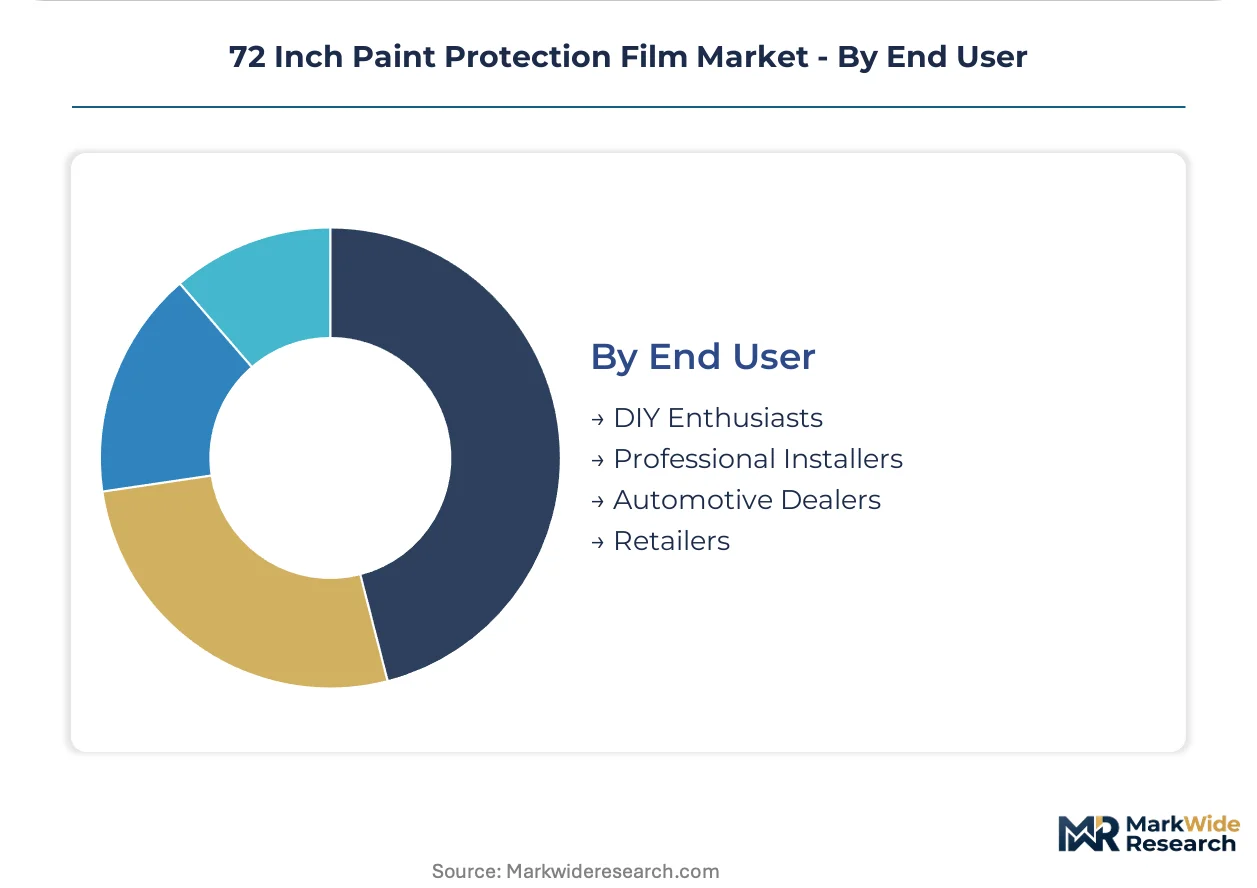
End User:
Skill certification and warranty liability separate addressable segments.
- Professional Installers:XPEL's training academy model requires months-long skill development, constraining network expansion velocity while anchoring loyalty through exclusive product access and warranty backing.
- Automotive Dealers:Luxury OEM point-of-sale attachment programs in China and Germany integrate PPF specification into vehicle configuration workflows.
- DIY Enthusiasts:Pre-cut pattern kits and reduced-thickness films serve cost-sensitive buyers accepting shorter service life and no labor warranty.
- Retailers:E-commerce and auto parts chains stock entry-grade inventory without installation support or performance guarantees.
Professional installers lead on revenue per transaction; automotive dealers expand fastest through OEM integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's factory-applied PPF certification programs operate at tighter OEM integration than China's rapidly expanding dealership attachment networks, creating divergent channel architectures across the two largest automotive markets.
United States
Luxury vehicle sales in California and Florida sustain dense installer networks specializing in hydrophobic and self-healing formulations. EPA VOC emission limits from adhesive manufacturing push converters toward water-based coating systems in Ohio and Michigan production facilities. XPEL's training academy anchors certified installer concentration in Dallas-Fort Worth and Orange County metro clusters.
Germany
Baden-Württemberg and Bavaria host OEM certification programs requiring eighteen-month material recertification cycles for factory-applied protection. ECHA REACH phthalate restrictions accelerate TPU substitution across European professional channels. Stuttgart and Munich dealership networks integrate PPF specification into vehicle configuration workflows at BMW, Mercedes-Benz, and Porsche point-of-sale systems.
China
Shanghai and Shenzhen dealerships report paint protection attachment rates exceeding ceramic coating penetration as premium vehicle purchasers specify factory-integrated protection. MEE environmental audits on domestic petrochemical feedstock suppliers tighten aliphatic TPU resin availability. Yangtze River Delta converters with established import pipelines capture displaced volume from domestic resin shortages.
United Kingdom
London and Southeast England concentrate independent detail shops serving supercar and collector vehicle clientele demanding gloss and matte optical-grade formulations. Post-BREACH regulatory alignment maintains phthalate restrictions on PVC film imports from non-EU suppliers. Midlands-based distributors manage inventory across pressure-sensitive adhesive formulations requiring regional viscosity calibration for temperate maritime climate zones.
Japan
Kanto region automotive refinish specialists adopt precision cutting systems and digital templating for complex body panel applications. METI industrial standards influence material specifications for domestic OEM factory-applied programs. Osaka-based converter networks supply optical-grade TPU formulations to premium import vehicle service channels across Kansai industrial clusters.
72 Inch Paint Protection Film Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across material supply and certified installation networks. The market structure concentrates around three strategic archetypes: chemical conglomerates with captive resin production, film converters with OEM certification pipelines, and installer-network operators with training academy models. Dominant competitive moves include backward integration into aliphatic TPU resin supply and geographic expansion through certified installer academy replication.
Among diversified material suppliers, Eastman Chemical Company and Saint-Gobain S.A. occupy positions anchored by optical-grade polymer production capabilities. XPEL Inc. exemplifies the pure-play specialist archetype through its training academy network. Avery Dennison Corporation sits within the converter tier with color-matched film portfolio diversification. These three company types represent the competitive structure: resin-integrated conglomerates, installer-network operators, and diversified film converters.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| STEK Automotive |
| 3M Company |
| Schweitzer-Mauduit International, Inc. |
| HEXIS S.A. |
| XPEL Inc. |
| Saint-Gobain S.A. |
| ORAFOL Europe GmbH |
| Eastman Chemical Company |
| Others |
Cost & Logistics Intelligence
Aliphatic TPU resin feedstock flows from specialized polymer producers through film converters to certified installer networks, with each transfer point embedding margin layers that stratify final service quotes across premium, standard, and economy tiers.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for optical-grade aliphatic TPU resin, compressing margins for European and North American converters lacking backward integration. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and warranty backing rather than raw material cost alone. Cost compression in the DIY retail tier is intensifying because vinyl alternatives erode entry-grade positioning. Fleet operators and commercial vehicle managers exhibit highest price sensitivity, while superyacht owners and luxury automotive collectors accept substantial premiums for hydrophobic and self-healing formulations with factory-backed installation warranties.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns that position pressure-sensitive adhesive formulations for climate-calibrated viscosity adjustments. Manufacturing concentrates in Germany, the United States, and China, with Yangtze River Delta converters drawing from established import pipelines during domestic resin shortages. Feedstock supply rests on petrochemical derivatives from specialized aliphatic TPU producers, optical-grade polymer additives, and acrylic adhesive components. Single-source vulnerability pervades optical-grade resin supply, as three specialized polymer producers control certified feedstock for professional channel converters. Distribution runs through authorized distributor networks that manage inventory across temperature-calibrated SKUs for certified installer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as luxury vehicle penetration and factory-applied OEM integration create durable replacement demand and recurring specification upgrades across vehicle ownership cycles.
For Market Incumbents: Lock in resin supply security through captive production or long-term offtake agreements with aliphatic TPU specialists, as feedstock concentration threatens margin stability. Expand training academy replication into underserved suburban clusters to preempt independent detail shop consolidation. XPEL's academy model demonstrates that installer loyalty anchors product pull-through, but emerging regional competitors threaten network exclusivity in China and Germany. For New Entrants and Emerging Players: Begin with marine superyacht refit yards in Florida and Mediterranean ports, where hydrophobic specification demand outpaces established supplier coverage and price sensitivity remains muted. Target residential architectural glass applications in coastal California and Florida markets, where UV-degradation protection migrates from automotive with minimal competitive density. Pursue direct-to-installer digital templating partnerships that bypass legacy distributor markups and accelerate pattern library development. For Investors and Strategic Acquirers: Consolidation pressure builds where certified installer scarcity constrains volume expansion for pure-play specialists lacking academy infrastructure. The five-to-ten-year viability window favors resin-integrated conglomerates and installer-network operators with durable certification pipelines over undifferentiated converters. Acquisition targets include regional training academy operators in China and Germany, and hydrophobic formulation specialists with marine channel penetration. Watch MEE environmental audit intensity as the signal indicating domestic resin availability inflection and import pipeline value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aliphatic TPU Resin | Eastman Chemical and Saint-Gobain secure captive optical-grade feedstock supply against single-source vulnerability. |
| Training Academy Network Expansion | XPEL's Dallas-Fort Worth and Orange County clusters demonstrate installer loyalty anchoring through months-long certification. |
| Hydrophobic Formulation Development | Fluoropolymer-modified surfaces capture premium positioning in Mediterranean and Caribbean superyacht refit yards. |
| Digital Templating and Robotic Plotter Deployment | German and United States certified installers reduce film waste from fifteen percent to under four percent per vehicle. |
| REACH-Compliant PVC Reformulation or Exit | ECHA phthalate restrictions force eighteen-month OEM recertification cycles that TPU suppliers with pre-validated resins exploit. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with film converter plant managers, certified installer network heads, automotive dealer F&I directors, marine refit yard procurement leads, and regulatory affairs specialists at resin producers with secondary validation. Secondary sources included customs and trade data for TPU resin and finished film flows, EPA VOC emission enforcement records, ECHA REACH compliance filings, SEC 10-K disclosures from listed material suppliers, and MEE environmental audit bulletins. Bottom-up volume builds from installer throughput estimates and factory-applied program volumes triangulated against top-down resin consumption and trade flow analysis.
Segment-weighting approaches distributed value across the analysis window according to product type tier, application channel, material chemistry, and end-user certification level, with automotive OEM integration intensity and marine penetration velocity as industry-specific dimensions. CAGRs derived from logistic curve fitting to historical adoption patterns, adjusted for regulatory phase-in timelines and resin supply pipeline maturity. Forecast inputs incorporated REACH compliance deadline impacts on PVC displacement, MEE audit intensity scenarios for Chinese domestic resin availability, and IRA clean vehicle credit supplier certification pathway development.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting TPU resin tariffs, breakthrough self-healing chemistry obsolescence of current thermal-repair formulations, and luxury automotive OEM program cancellations. Forecasts reflect documented assumptions about installer network expansion velocity and resin supply pipeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Biodegradable Plastic Films Market