
 Cross-Linked Shrink Films Market | 2026-2036
Cross-Linked Shrink Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cross-Linked Shrink Films Market Outlook
Multi-source procurement for irradiation and cross-linking services is repositioning how film converters secure capacity and quality consistency. SABIC leverages its petrochemical feedstock position to anchor polyolefin resin supply for downstream film producers. Syfan specializes in narrow-web specialty grades for medical and electronics applications where clarity and seal integrity command premium positioning. Intertape Polymer Group extends its North American manufacturing footprint to compete on delivery speed against Asian imports.
Cross-linked shrink films are thermoplastic polymers—predominantly polyolefin, PVC, and PET—that undergo electron-beam or chemical cross-linking to create three-dimensional molecular bonds, yielding films with shrink forces exceeding 200 psi and puncture resistance superior to standard monolayer alternatives; this chemistry enables tight unitization of irregular loads through controlled directional shrinkage during heat tunnel processing. Polyolefin formulations dominate food packaging applications where FDA and EFSA compliance for direct food contact under elevated temperatures remains mandatory, while PVC retains share in industrial bundling where cost sensitivity outweighs sustainability preferences. E-commerce end users represent the fastest-expanding demand pool as automated fulfillment centers specify high-clarity films that support barcode scanning through printed graphics.
FDA food-contact regulations and EPA emissions standards for irradiation facilities shape product formulation and capital investment decisions across US manufacturing sites. REACH substance restrictions and the EU Green Deal packaging waste directives are accelerating substitution away from PVC toward recyclable polyolefin structures in European markets. Stakeholders must monitor evolving extended producer responsibility frameworks and irradiation capacity buildouts to align product portfolios with compliance timelines and regional supply availability.
Market Dynamics
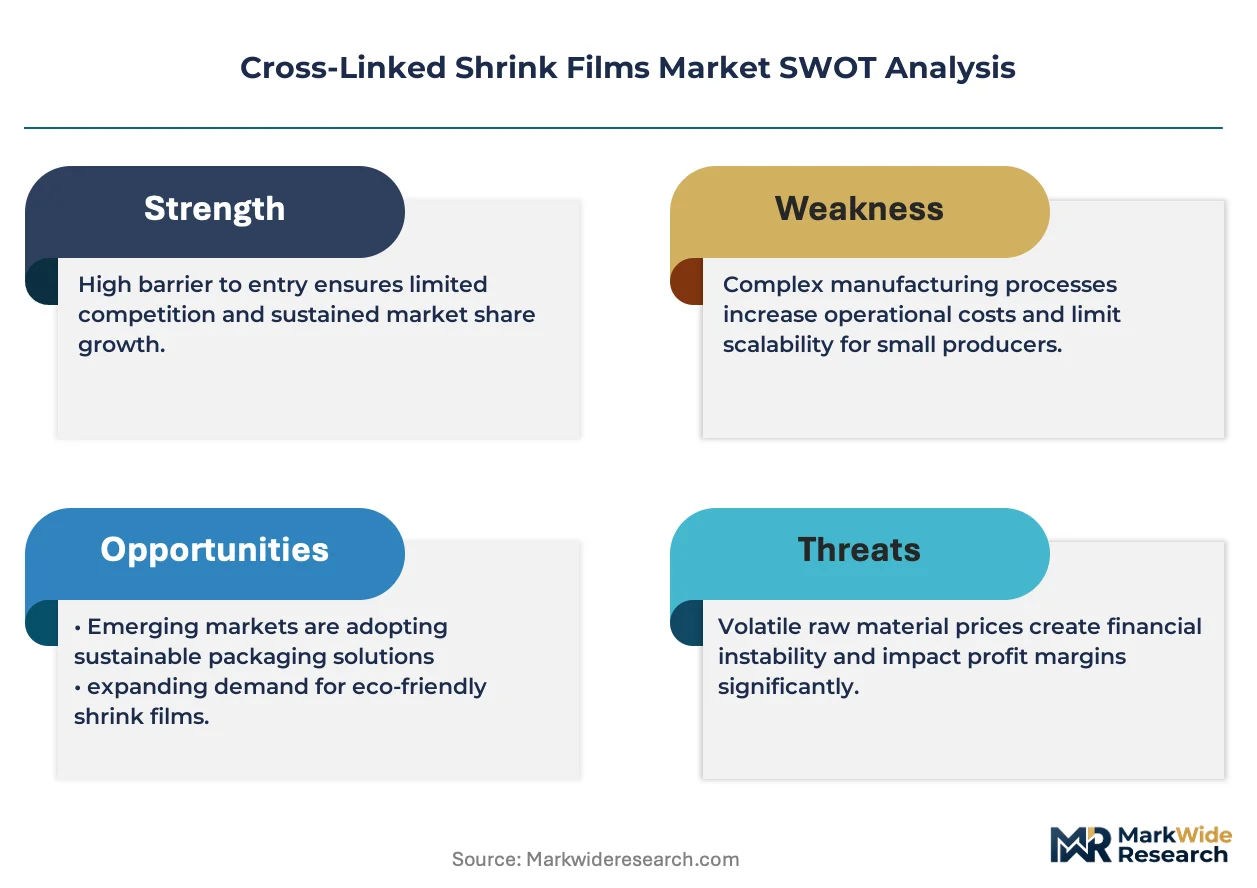
Electron-beam irradiation capacity constraints are concentrating supply power among film converters with captive cross-linking assets, forcing smaller processors into tolling arrangements that erode margin control and elongate lead times for specialty grades.
Growth Catalysts
- EU Green Deal packaging mandates:REACH substance restrictions and extended producer responsibility frameworks are compelling food processors across Germany, France, and Italy to replace PVC wraps with recyclable polyolefin shrink films certified for mechanical recycling streams.
- E-commerce fulfillment automation:Automated sortation centers in the United States and China are specifying high-clarity cross-linked films that maintain barcode scannability through printed graphics during high-speed tunnel shrink operations.
- Polyolefin formulation advances:Metallocene-catalyzed resin technologies are enabling downgauged films with puncture resistance exceeding 200 psi, allowing meat and poultry packers to reduce material usage without sacrificing load containment integrity.
Market Restraints
- Irradiation capacity concentration:Electron-beam and gamma cross-linking services cluster in Germany, the United States, and Japan, creating geographic bottlenecks that limit film converter expansion in emerging production zones lacking regional irradiation infrastructure.
- Ethylene feedstock volatility:Polyolefin resin costs track naphtha and natural gas liquid pricing, exposing film margins to petrochemical commodity swings that converters cannot fully pass through to price-sensitive industrial bundling customers.
- PVC cost anchoring:Conventional PVC shrink film retains 15-25% cost advantage in non-food applications, slowing substitution in developing markets where sustainability premiums face procurement resistance.
Strategic Opportunities
- Medical device sterilization packaging:Tyvek-compatible cross-linked films with validated EO and gamma sterilization resistance are capturing share from conventional thermoformed trays in Class II device applications.
- India's organized retail expansion:Cold chain modernization under the PLI scheme for food processing is creating first-mover advantage for converters establishing local irradiation partnerships to serve quick-commerce grocery platforms.
- Chemical recycling alignment:Advanced polyolefin grades designed for pyrolysis feedstock compatibility are securing preferential offtake terms from petrochemical producers seeking circular content certificates under EU Taxonomy requirements.
Industry Challenges
- Irradiation process certification:FDA 21 CFR Part 820 and ISO 11137 compliance for medical-grade films demands 18-24 month validation timelines that lock working capital and delay revenue recognition for new production lines.
- Cross-linking technician scarcity:Specialized expertise in dose mapping, dosimetry, and polymer rheology under irradiation is concentrating among aging workforces in Germany and the United States, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross-Linked Shrink Films Market |
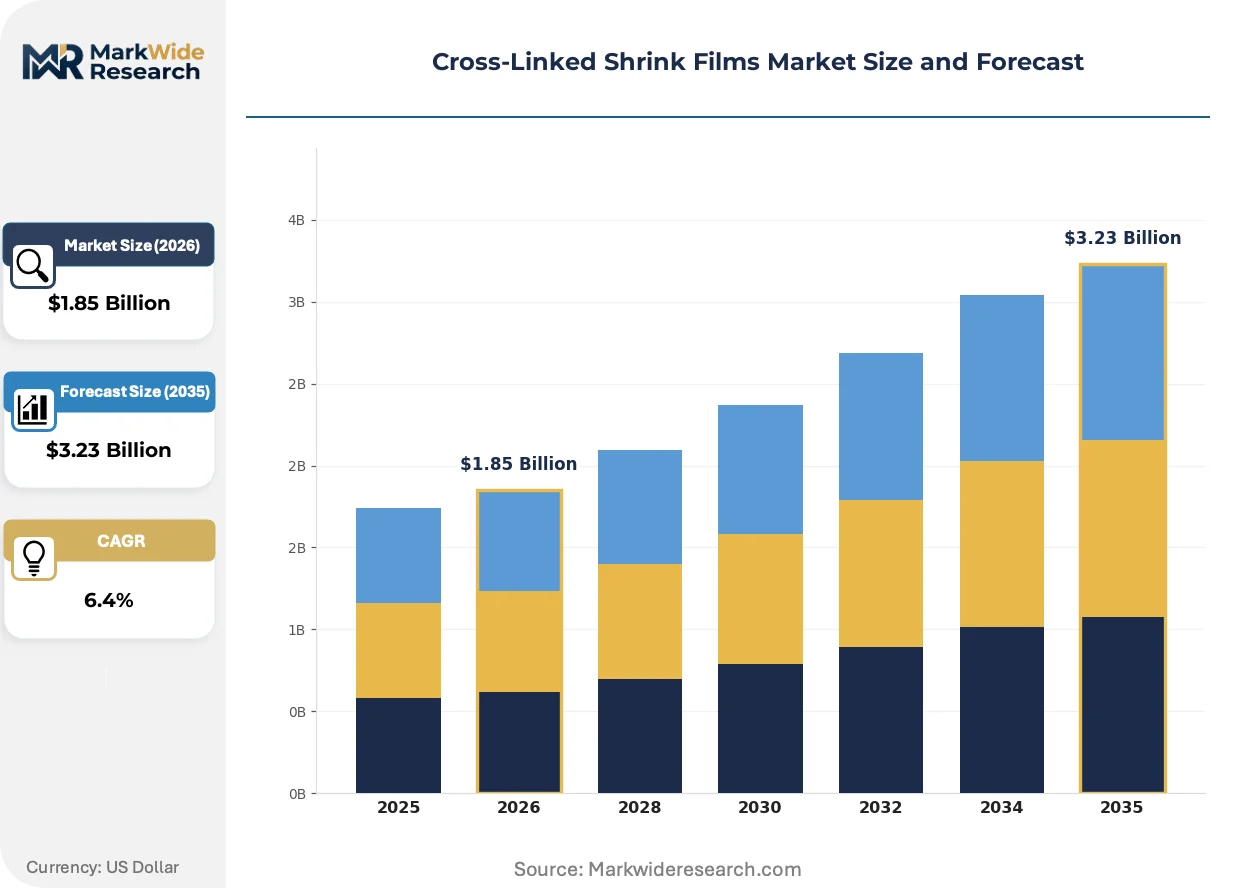
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, PET, Others Application: Food Packaging, Industrial Packaging, Beverage Packaging, Consumer Goods Packaging End User: Retail, Manufacturing, Logistics, E-Commerce Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Intertape Polymer Group, Bollore Group, Syfan, SABIC, Schlichter GmbH, Yorkshire Packaging Systems, Bagla Group, Clearpack Singapore Pte Ltd, WM Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross-Linked Shrink Films Market Strategic Shifts
Digital printing compatibility and downgauging imperatives are forcing simultaneous investment in resin formulation and converting equipment, compressing the window for technology adoption before regulatory deadlines lock in material specifications.
Multilayer coextrusion with tie-layer adhesion promotion is rewriting the performance ceiling for cross-linked shrink films. Food processors in the United States and Western Europe are adopting five-layer structures at annual rates exceeding 12% for fresh protein applications. This architecture is compressing the addressable market for monolayer alternatives by enabling sub-40-micron gauges with equivalent puncture resistance.
REACH Annex XVII restrictions on phthalate plasticizers are accelerating PVC displacement in European consumer goods bundling. Industrial packagers in Germany and Poland are qualifying polyolefin alternatives ahead of 2025 compliance deadlines. The substitution wave is reshaping converter product development priorities toward high-shrink-force grades previously dominated by plasticized vinyl.
Consolidated buying by quick-commerce grocery platforms is compressing supplier qualification cycles from 24 months to 8-12 months in metropolitan India and Southeast Asia. Large format retailers are unbundling film supply from equipment maintenance contracts, forcing converters to compete on unit economics rather than captive machinery lock-in. This behavior is most visible in Bangalore and Mumbai, where Swiggy Instamart and Zepto are consolidating packaging specifications across dark store networks.
Cross-Linked Shrink Films Market Segmentation
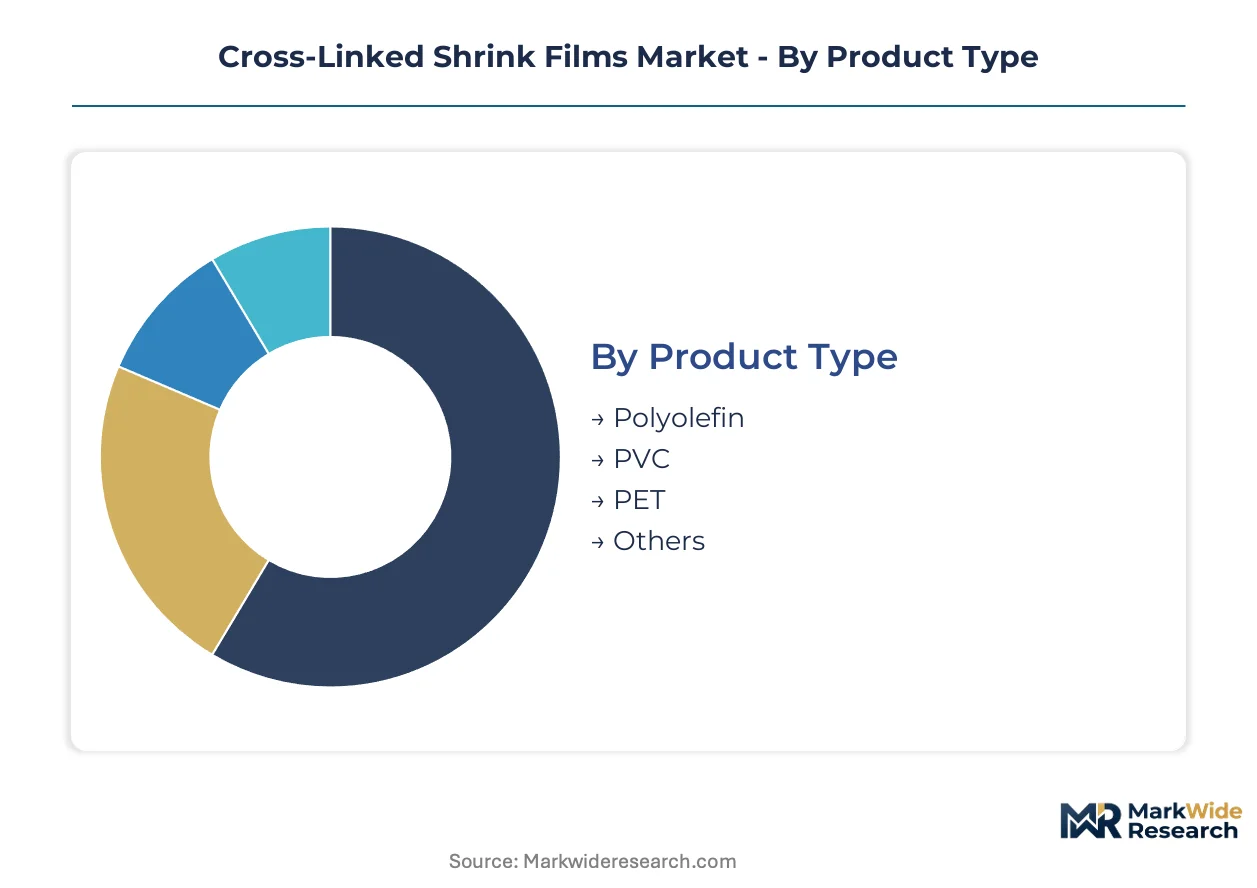
Cross-linked shrink films serve divergent performance requirements across food safety, industrial load containment, and automated fulfillment channels. Segment boundaries reflect incompatible technical specifications—FDA-compliant polyolefin formulations cannot substitute for cost-optimized PVC in non-food bundling. Procurement patterns vary sharply by end-use, with e-commerce platforms demanding clarity and scannability while industrial buyers prioritize puncture resistance.
Product Type:
Resin supply concentration in Saudi Arabia, South Korea, and the US Gulf Coast shapes converter sourcing strategies and margin structures.
- Polyolefin:Metallocene-catalyzed polyethylene and polypropylene grades dominate fresh protein packaging in Germany and the United States. FDA and EFSA compliance for direct food contact under elevated tunnel temperatures locks in formulation specifications. Meat and poultry processors in North Rhine-Westphalia and Iowa are specifying downgauged structures below 40 microns to reduce material intensity without sacrificing load integrity.
- PVC:Plasticized vinyl retains cost advantage in industrial bundling applications across Poland and Mexico where sustainability premiums face procurement resistance. REACH Annex XVII phthalate restrictions are accelerating displacement in European consumer goods, though developing markets continue specifying conventional grades for non-food unitization.
- PET:Polyester-based films offer dimensional stability for high-temperature sterilization applications in medical device packaging. Japanese converters are qualifying PET grades for gamma-stable tray lidding.
- Others:Niche biodegradable and bio-based formulations are emerging in Swiss and Austrian premium organic food segments. Limited irradiation compatibility constrains scale.
Polyolefin absorbs the bulk of installed capacity; PET is expanding most quickly in medical sterilization applications.
Application:
Cost tier differentiation separates premium food-grade specifications from commodity industrial bundling where price-per-meter dominates procurement.
- Food Packaging:Fresh protein, dairy, and prepared meal applications in France and Italy require EFSA-certified polyolefin structures with validated mechanical recycling pathways. Automated tray sealing lines in Lyon and Milan are driving specification consolidation toward five-layer coextruded films.
- Industrial Packaging:Machinery and automotive exporters in Germany's industrial corridor specify high-shrink-force grades exceeding 200 psi for pallet unitization. Load containment integrity outweighs clarity requirements in Stuttgart and Wolfsburg distribution centers.
- Beverage Packaging:Multipack collation for bottled water and soft drinks in China's Yangtze River Delta favors high-clarity films supporting printed brand graphics. NMPA food-contact regulations govern formulation choices.
- Consumer Goods Packaging:Electronics and cosmetics bundling in South Korea and Japan demands premium optical properties and tamper-evident seal performance. Shrink-sleeve applications for smartphones in Gyeonggi Province are specifying ultra-thin gauges.
Food packaging commands the highest unit margins; e-commerce fulfillment is gaining share fastest in beverage and consumer goods collation.
End User:
Customer type determines specification complexity, with automated fulfillment centers imposing the most demanding technical requirements.
- Retail:Supermarket chains in Spain and Portugal are consolidating film specifications across private-label meat and produce operations. Centralized procurement in Madrid and Lisbon is compressing supplier qualification cycles.
- Manufacturing:Food processors and consumer goods producers in the Netherlands specify films compatible with existing heat tunnel equipment. Retrofit avoidance drives gauge and shrink-force standardization.
- Logistics:Third-party warehouse operators in the US Midwest prioritize puncture resistance for mixed-load pallet containment. Chicago and Indianapolis distribution hubs are testing downgauged alternatives to reduce freight cost allocation.
- E-Commerce:Quick-commerce platforms in Bangalore and Mumbai are specifying high-clarity films maintaining barcode scannability through printed graphics. Swiggy Instamart and Zepto dark stores are unbundling film supply from equipment maintenance contracts.
Manufacturing absorbs the bulk of volume; e-commerce is climbing the fastest as quick-commerce platforms consolidate specifications.
Distribution Channel:
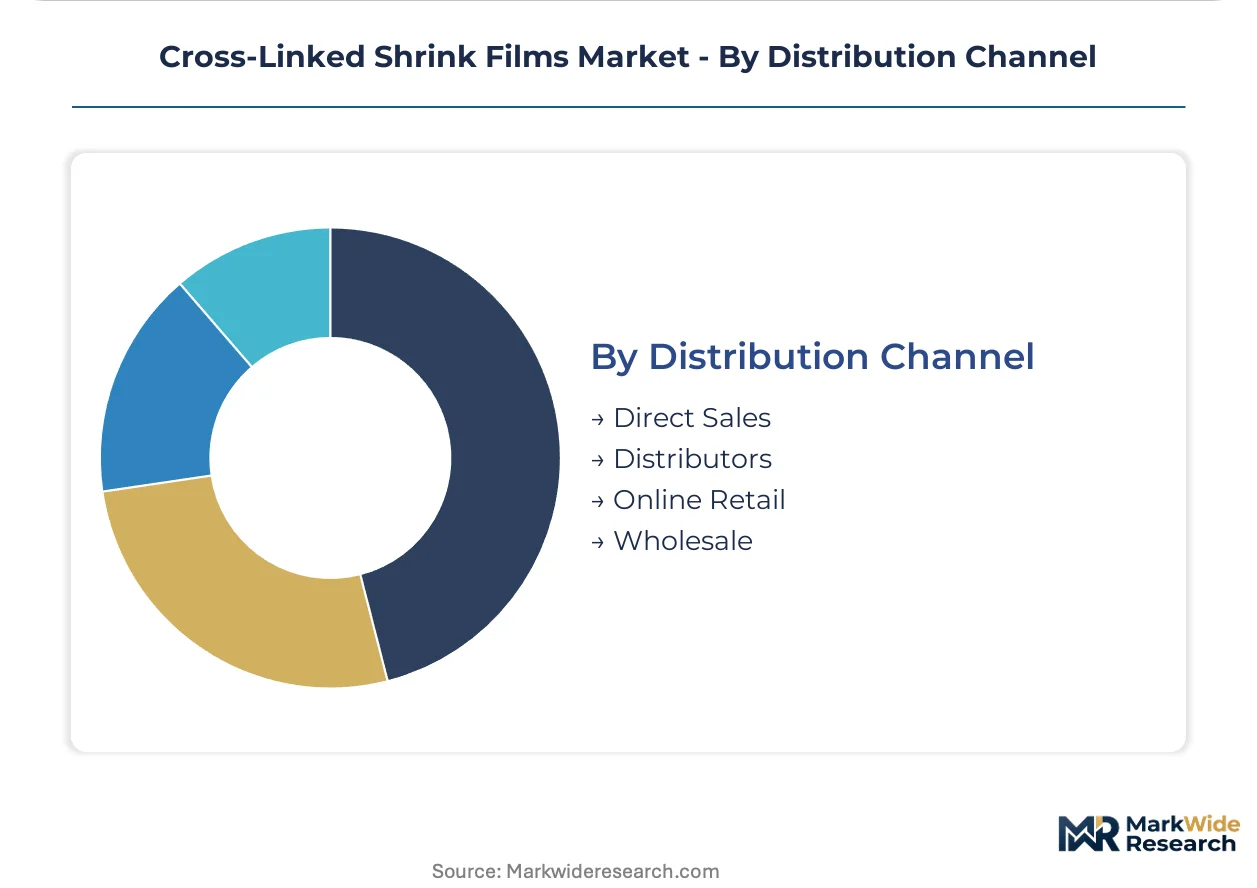
Geography and order scale determine channel selection, with direct relationships dominating large-volume food and industrial accounts.
- Direct Sales:Major food processors and automotive exporters in Germany and the United States negotiate multi-year supply agreements with captive irradiation capacity guarantees. Direct relationships lock in formulation continuity for validated packaging lines.
- Distributors:Regional converters in Italy and Poland rely on specialized film distributors for technical support and inventory buffering. Local language service requirements favor distributor intermediation.
- Online Retail:Small-format retailers and startup food brands in Southeast Asia are sourcing standard gauges through B2B platforms. Limited technical support constrains specification optimization.
- Wholesale:Industrial bundling customers in Mexico and Brazil purchase commodity PVC grades through packaging wholesalers. Price transparency and immediate availability outweigh performance customization.
Direct sales captures the bulk of value; online retail is expanding most quickly among emerging-market small enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene feedstock concentration along the US Gulf Coast and in Saudi Arabia anchors polyolefin resin supply for cross-linked shrink film converters worldwide. Irradiation infrastructure clusters in Germany, the United States, and Japan create geographic bottlenecks that shape regional competitive dynamics. Demand fragmentation across food packaging, industrial bundling, and e-commerce fulfillment channels produces divergent specification requirements by market.
United States
Meat and poultry processors in Iowa and Nebraska specify downgauged polyolefin structures below 40 microns for fresh protein packaging. FDA 21 CFR Part 820 compliance requirements for medical-grade films drive 18-24 month validation timelines at irradiation facilities. Chicago and Indianapolis distribution hubs serve as testing grounds for puncture-resistant alternatives in third-party logistics operations.
Germany
Automotive and machinery exporters in Stuttgart and Wolfsburg require high-shrink-force grades exceeding 200 psi for pallet unitization. REACH Annex XVII phthalate restrictions accelerate PVC displacement in consumer goods bundling ahead of 2025 deadlines. North Rhine-Westphalia's industrial packaging corridor concentrates converter activity near captive electron-beam irradiation assets.
China
Beverage multipack collation in the Yangtze River Delta favors high-clarity films supporting printed brand graphics for bottled water and soft drinks. NMPA food-contact regulations govern formulation choices for domestic and export-bound production. Shanghai and Suzhou manufacturing clusters integrate resin compounding with film converting for integrated supply chain control.
India
Quick-commerce grocery platforms in Bangalore and Mumbai consolidate packaging specifications across dark store networks under 8-12 month supplier qualification cycles. PLI scheme incentives for food processing cold chain modernization create first-mover opportunities for converters establishing local irradiation partnerships. Maharashtra and Karnataka absorb the bulk of emerging organized retail demand.
Japan
Medical device sterilization packaging in the Kanto region specifies gamma-stable PET grades for tray lidding applications. METI industrial standards shape performance requirements for electronics bundling in consumer goods segments. Osaka-based converters qualify Tyvek-compatible structures for Class II device applications requiring EO and gamma sterilization resistance.
Cross-Linked Shrink Films Market Competitive Environment
Capacity expansion dominates the current landscape as film converters secure captive irradiation assets to bypass tolling bottlenecks. The vendor base stratifies between petrochemical-integrated resin suppliers, specialty narrow-web converters, and regional packaging systems integrators. Three archetypes anchor competitive positioning: feedstock-backward players controlling polyethylene supply chains, irradiation-captive specialists with validated medical-grade capacity, and equipment-integrated distributors competing on delivery speed. Geographic expansion and portfolio diversification toward medical sterilization applications represent the dominant competitive moves.
Among North American fabricators, Intertape Polymer Group exemplifies the equipment-integrated archetype with manufacturing footprint extension strategies. SABIC represents the feedstock-backward tier leveraging petrochemical integration for resin supply security. Syfan occupies a position within the specialty narrow-web segment where clarity and seal integrity command premium positioning in medical and electronics applications.
| Leading Market Players |
|---|
| Intertape Polymer Group |
| Bollore Group |
| Syfan |
| SABIC |
| Schlichter GmbH |
| Yorkshire Packaging Systems |
| Bagla Group |
| Clearpack Singapore Pte Ltd |
| WM Technology |
| Others |
Value Chain & Pricing Dynamics
Ethylene feedstock volatility traces a direct path from naphtha and natural gas liquid pricing swings through polyolefin resin costs to compressed margins at film converters serving price-sensitive industrial bundling customers in Poland and Mexico. This input-cost transmission forces converters into multi-year supply agreements with captive irradiation guarantees to defend pricing power.
Pricing Analysis
Warranty and equipment-maintenance bundling formerly locked industrial customers into single-source relationships, though quick-commerce platforms in Bangalore and Mumbai now unbundle film supply to compete on unit economics. Three-tier pricing structure across premium medical-grade, standard food-contact, and economy industrial-bundling levels separates FDA-validated structures from commodity PVC alternatives. Cost compression in the economy tier intensifies because PVC retains 15-25% cost advantage in non-food applications. Industrial bundling customers in developing markets exhibit highest price sensitivity, while medical device sterilization packaging commands least.
Supply Chain Analysis
FDA 21 CFR Part 820 and ISO 11137 compliance validation gates electron-beam irradiation capacity, concentrating supply power among German, United States, and Japanese converters with captive cross-linking assets. Resin supply draws from Saudi Arabia, South Korea, and the US Gulf Coast petrochemical complexes, with metallocene-catalyzed polyethylene and polypropylene as dominant inputs. Single-source vulnerability pervades the irradiation services layer where specialized dose-mapping expertise concentrates among aging workforces. Distribution runs through direct sales for major food processors and automotive exporters, with regional distributors buffering inventory for Italian and Polish converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Irradiation capacity concentration is forcing smaller film converters into tolling arrangements that erode margin control, accelerating consolidation toward players with captive cross-linking assets and validated medical-grade capacity.
For Market Incumbents: Lock in multi-year supply agreements with major food processors and automotive exporters by guaranteeing captive irradiation capacity and formulation continuity for validated packaging lines. Expand electron-beam assets in Germany's North Rhine-Westphalia corridor to preempt tolling bottlenecks. Defend against PVC displacement in European consumer goods by accelerating REACH Annex XVII-compliant polyolefin qualification ahead of regulatory deadlines. For New Entrants and Emerging Players: Quick-commerce grocery platforms in metropolitan India represent the most penetrable buyer archetype, with supplier qualification cycles compressed from 24 months to 8-12 months creating entry windows. Target Maharashtra and Karnataka dark store networks with local irradiation partnerships under PLI scheme cold chain incentives. Lead with high-clarity films maintaining barcode scannability through printed graphics to differentiate from equipment-integrated incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor irradiation-captive specialists with validated medical-grade capacity in Germany and the United States where technician scarcity constrains greenfield expansion. Five-to-ten-year viability hinges on securing positions in medical device sterilization packaging and chemical-recycling-aligned polyolefin grades. Watch for EU Taxonomy circular content certificate demand as inflection indicator for premium grade offtake.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Irradiation Capacity Buildout | Electron-beam asset ownership in Germany bypasses tolling bottlenecks and secures margin control. |
| Medical-Grade Validation Investment | FDA 21 CFR Part 820 compliance opens Class II device packaging with 18-24 month revenue timelines. |
| Local Irradiation Partnership in India | Maharashtra and Karnataka facility access captures quick-commerce platform consolidation under PLI incentives. |
| Chemical Recycling Alignment | Pyrolysis-feedstock-compatible grades secure preferential offtake from EU Taxonomy-seeking petrochemical producers. |
| Five-Layer Coextrusion Adoption | Sub-40-micron structures with 200+ psi puncture resistance displace monolayer alternatives in fresh protein packaging. |
Study Parameters
Independent corroboration across film converter executives, irradiation facility operators, food processor procurement leads, and medical device packaging engineers underwrites the qualitative findings in this study. Primary interviews with technical R&D directors at resin suppliers and distribution channel partners in Germany, the United States, and India combined with secondary validation from customs and trade data, SEC 10-K filings, and REACH regulatory filings. Bottom-up volume modeling across resin grades, gauge specifications, and end-use applications triangulated against top-down petrochemical capacity and irradiation infrastructure assessments.
Comparable historical periods anchored the projection horizon to capture cyclical ethylene feedstock patterns and regulatory compliance wave timing. Segmentation dimensions modeled include resin chemistry, film gauge tier, application requirements, end-user procurement complexity, and regional irradiation availability. CAGRs derived from installed capacity buildouts, substitution rate assumptions, and validated demand elasticity coefficients. Forecast inputs incorporated metallocene resin adoption curves and quick-commerce platform specification consolidation rates.
Revisions become necessary when electron-beam irradiation capacity expansion materially exceeds technician training pipeline output, or when EU Green Deal packaging mandates accelerate PVC displacement faster than polyolefin qualification timelines. Forecasts reflect assumptions about resin supply continuity from Gulf Coast and Saudi petrochemical complexes and irradiation dose-mapping expertise retention. A model refresh is warranted upon material change in ethylene feedstock pricing volatility or REACH substance restriction scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Biodegradable Plastic Films Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
Liquid Masking Film Market