
 Still Drinks Market | 2026-2036
Still Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Still Drinks Market Intelligence
The capital-intensity gap between vertically integrated beverage giants and smaller, asset-light brands is unwinding. This shift allows niche players to challenge established leaders. The Coca-Cola Company leverages its vast global distribution network to maintain market share. Meanwhile, PepsiCo competes through a diversified portfolio including functional drinks, while Nestlé specializes in the premium bottled water category, anchoring its brand on purity.
Still drinks are non-carbonated beverages, encompassing formulations not pressurized with carbon dioxide during packaging. Their primary commercial purpose is providing hydration, often enhanced with flavors, vitamins, or other functional additives. Within product types, bottled water and fruit juices constitute mature, high-volume categories, while flavored water shows strong growth. Plastic bottles remain the dominant packaging format, though cartons and cans gain share as consumer preference shifts toward sustainable options.
Regulations from the U.S. FDA and the European Food Safety Authority (EFSA) dictate stringent labeling requirements for nutritional content and health claims. In parallel, standards from India's FSSAI and China's SAMR govern beverage composition and safety, shaping market access. Navigating the complex patchwork of national sugar taxes and evolving plastic packaging mandates is a central strategic consideration for all market participants.
Market Dynamics
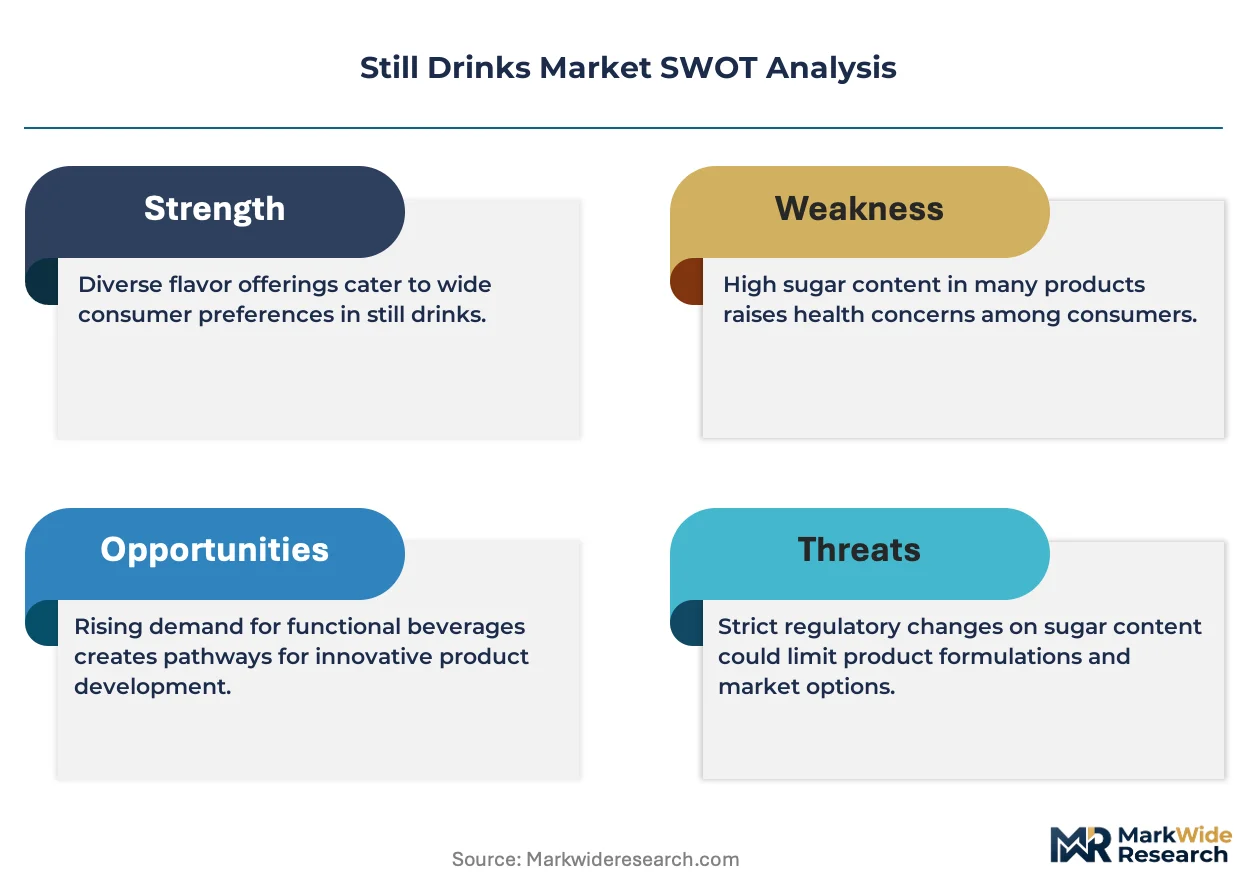
The central dynamic shaping the still drinks market is the escalating tension between consumer demand for functional health benefits and a complex, fragmented global regulatory environment aimed at reducing sugar consumption and plastic waste.
Growth Catalysts
- Functional Formulations:Demand from athletes and wellness-oriented consumers for beverages fortified with vitamins, minerals, and electrolytes propels development in the functional water and enhanced juice categories.
- Urbanization in Asia:The concentration of middle-class consumers in major cities across India and China creates dense markets for premium bottled water and high-quality fruit juices, driven by concerns over tap water safety and a preference for convenience.
- Favorable Health Policies:Regulations like India's FSSAI rules for fortified foods can create a favorable environment for beverage brands to launch products with approved health claims, aligning with public health objectives.
Market Restraints
- Input Price Volatility:Fluctuation in the cost of agricultural commodities, including fruit concentrates, sugar, and natural flavorings, creates margin pressure and complicates long-term pricing strategies for manufacturers.
- Packaging Regulation Divergence:A patchwork of differing national mandates on plastic content, recycling, and labeling, such as those in the EU versus North America, increases compliance costs and operational complexity.
- Substitution from Tap Water Systems:The increasing quality and popularity of in-home water filtration systems and reusable bottles present a direct substitute for single-use bottled water, particularly in environmentally conscious households.
Strategic Opportunities
- Direct-to-Consumer Models:Niche brands can leverage online subscription services to build direct relationships with consumers, bypassing traditional retail gatekeepers for specialized products like nootropic drinks or plant-based protein beverages.
- Smart Packaging Integration:The convergence of digital technologies with packaging, such as QR codes linking to ingredient provenance or personalized hydration advice, offers a new frontier for brand differentiation.
- Rural Market Penetration:Underdeveloped rural regions in Southeast Asia and Africa represent a significant volume opportunity for affordable, safe, and basic hydration products, including bottled water and simple juice drinks.
Industry Challenges
- Sustainable Packaging Transition:Shifting production lines from lightweight PET bottles to heavier glass, aluminum cans, or aseptic cartons requires substantial capital investment and creates new logistical and supply chain hurdles.
- Reformulation Timelines:Meeting staggered deadlines for national sugar taxes, like those implemented in the United Kingdom and Mexico, forces costly and time-consuming research and development cycles to maintain taste profiles with alternative sweeteners.
- Nutritional Labeling Compliance:Adhering to evolving and stringent nutritional information and health claim regulations from bodies like the U.S. FDA and EFSA demands constant vigilance and specialized regulatory expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Still Drinks Market |
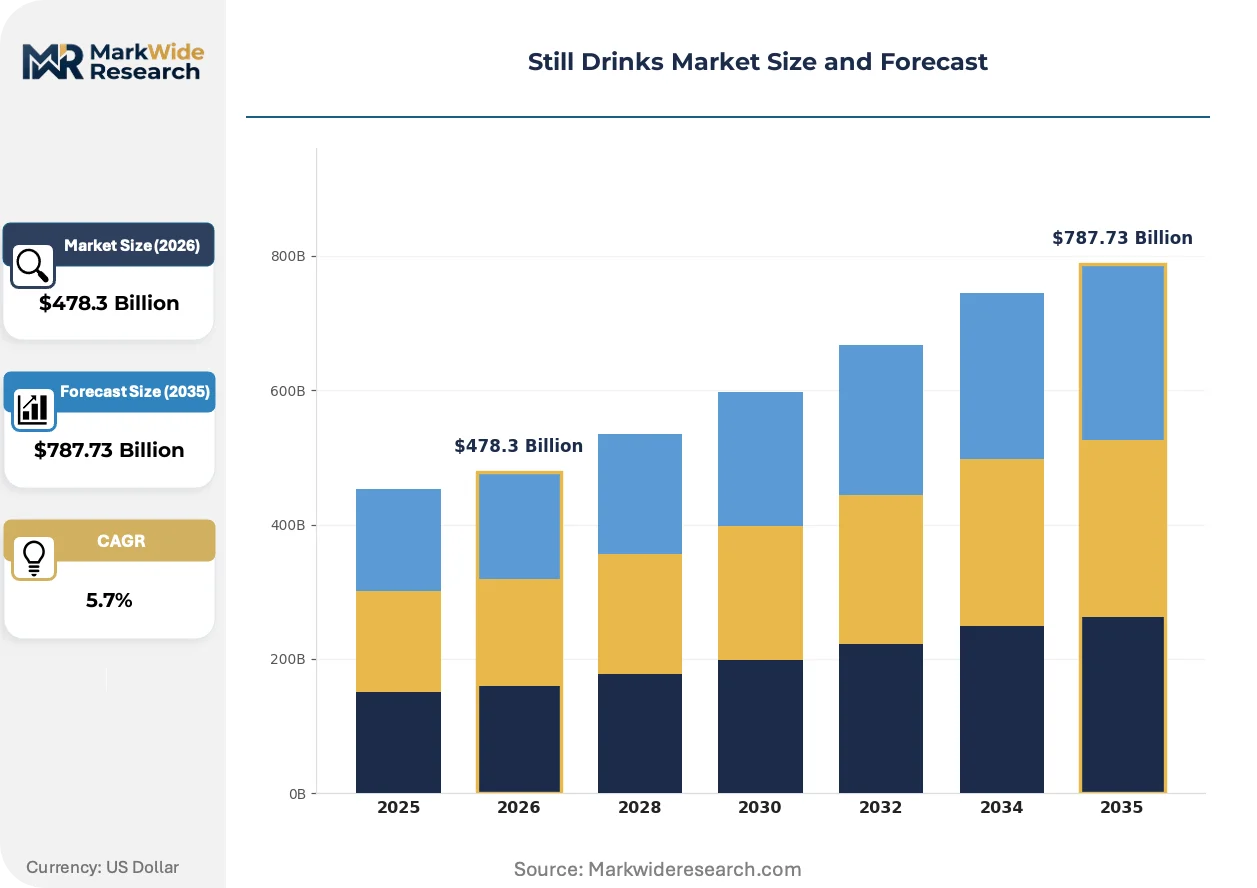
| Market Size in 2026 | $478.3 Billion |
| Market Size in 2035 | $787.73 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Juices, Bottled Water, Flavored Water, Iced Tea, Energy Drinks Packaging Type: Plastic Bottles, Glass Bottles, Cartons, Cans, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines, Foodservice Customer Type: Adults, Teenagers, Children, Elderly, Fitness Enthusiasts |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestlé, Suntory Beverage & Food, Keurig Dr Pepper, Monster Beverage, Red Bull GmbH, Danone, Dr Pepper Snapple Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Still Drinks Market Strategic Shifts & Innovations
Product formulation has become the primary arena for competition and innovation, as manufacturers respond to the dual pressures of consumer health consciousness and proactive public health policies on sugar and ingredients.
High-pressure processing (HPP) is a non-thermal pasteurization method that preserves the flavor and nutritional integrity of beverages. This method is gaining traction among producers of premium, cold-pressed juices and functional smoothies who target health-focused consumers. This technology is decomposing the traditional boundary between perishable fresh-squeezed juices and long-life shelf-stable beverages, creating a new premium category.
European Union directives promoting extended producer responsibility (EPR) under the European Green Deal are altering packaging economics. These regulations compel beverage manufacturers to finance the collection and recycling of their packaging waste, directly impacting operational costs. The bottled water and juice categories, heavily reliant on PET bottles, are most affected, which is accelerating investment in recycled plastic (rPET) and alternative materials like cartons.
A consumer-led push for transparency is altering brand selection criteria, particularly for premium products. Shoppers increasingly favor brands that offer verifiable data on ingredient sourcing and ethical production, often accessed via QR codes on packaging. This trend, most visible in the United States and Germany, disrupts loyalty based on advertising and benefits brands that can prove their supply chain integrity.
Still Drinks Market Segmentation
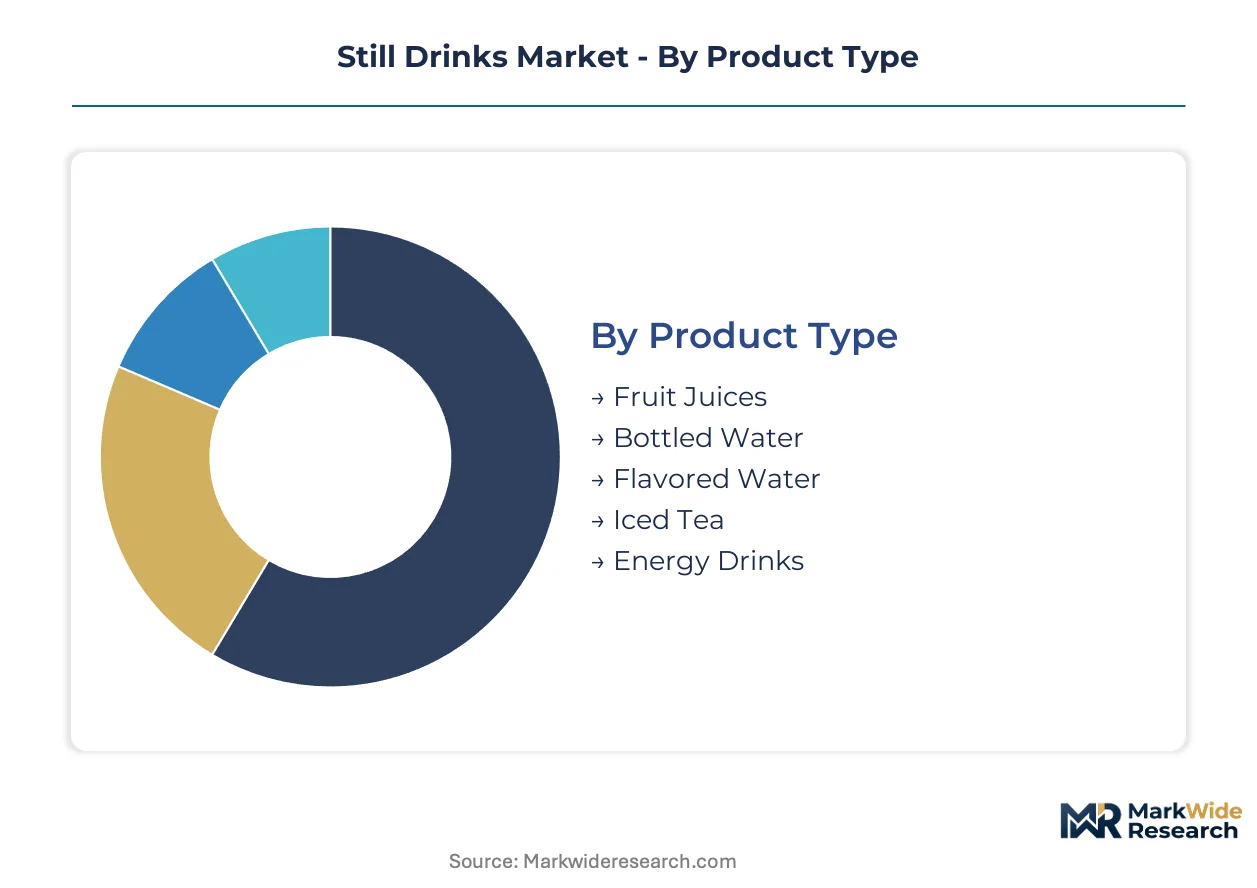
The still drinks market exhibits a diverse landscape, driven by varied consumer preferences and evolving product functionalities. Understanding these distinct segments allows market participants to tailor product development and distribution strategies effectively.
Product Type:
The array of still drinks reaches consumers through a complex channel mix, ranging from mass-market retail outlets to specialized health food stores.
- Bottled Water:This category includes purified, spring, mineral, and distilled water, available in various formats. Demand for premium bottled water concentrates in urban centers across China and India, driven by tap water safety concerns.
- Fruit Juices:Derived from natural fruit extracts, these vary from 100% juice to nectars. Health-conscious consumers in Europe and North America focus on cold-pressed options, seeking nutritional integrity.
- Flavored Water:Water infused with flavors, often enhanced with vitamins or electrolytes.
- Iced Tea:Ready-to-drink tea beverages, available in various flavors, offering an alternative to carbonated soft drinks.
- Energy Drinks:Formulated to boost performance, these drinks contain caffeine, taurine, and B vitamins, targeting younger demographics.
Bottled Water dominates installed base. Flavored Water is where expansion concentrates.
Packaging Type:
The maturity of packaging technologies significantly influences product shelf life, cost structures, and environmental impact.
- Plastic Bottles:Primarily made from PET, these lightweight and cost-effective containers are widespread. Regulatory mandates in the EU are accelerating investment in recycled plastic (rPET) materials.
- Cartons:Aseptic cartons provide extended shelf life for juices and plant-based beverages without refrigeration. Consumer preference shifts toward sustainable options in Germany are driving increased adoption.
- Glass Bottles:Valued for premium perception and recyclability, glass is prevalent in high-end juice and bottled water segments.
- Cans:Aluminum cans offer excellent barrier properties and recyclability, gaining share in functional beverages and iced tea.
- Pouches:Flexible, lightweight packaging solutions for children's juices and sport drinks provide convenience and reduced material usage.
Cost efficiency drives widespread use of Plastic Bottles. Environmental concerns are accelerating the shift towards Cartons and Cans.
Distribution Channel:
The choice of distribution channel often aligns directly with the target customer type, ensuring products are accessible where and when consumers seek them.
- Supermarkets:These large retail formats offer extensive product assortments and competitive pricing, serving as the primary channel for household purchases. Brand visibility in the United States and Canada is critical for market share.
- Online Retail:E-commerce platforms and direct-to-consumer models provide convenience and access to niche products. This channel shows significant growth in the UK and Australia, driven by logistics improvements.
- Convenience Stores:Offering immediate consumption, these smaller outlets are crucial for on-the-go purchases of single-serve drinks.
- Vending Machines:Automated units provide quick access to beverages in high-traffic locations, catering to impulse buys.
- Foodservice:Restaurants, cafes, and institutional settings provide still drinks for immediate on-premise consumption.
Broad consumer access is secured through Supermarkets. Rapid expansion for niche brands is occurring through Online Retail.
Customer Type:
Still drinks are formulated with specific functional benefits or taste profiles to meet the diverse needs of various consumer groups.
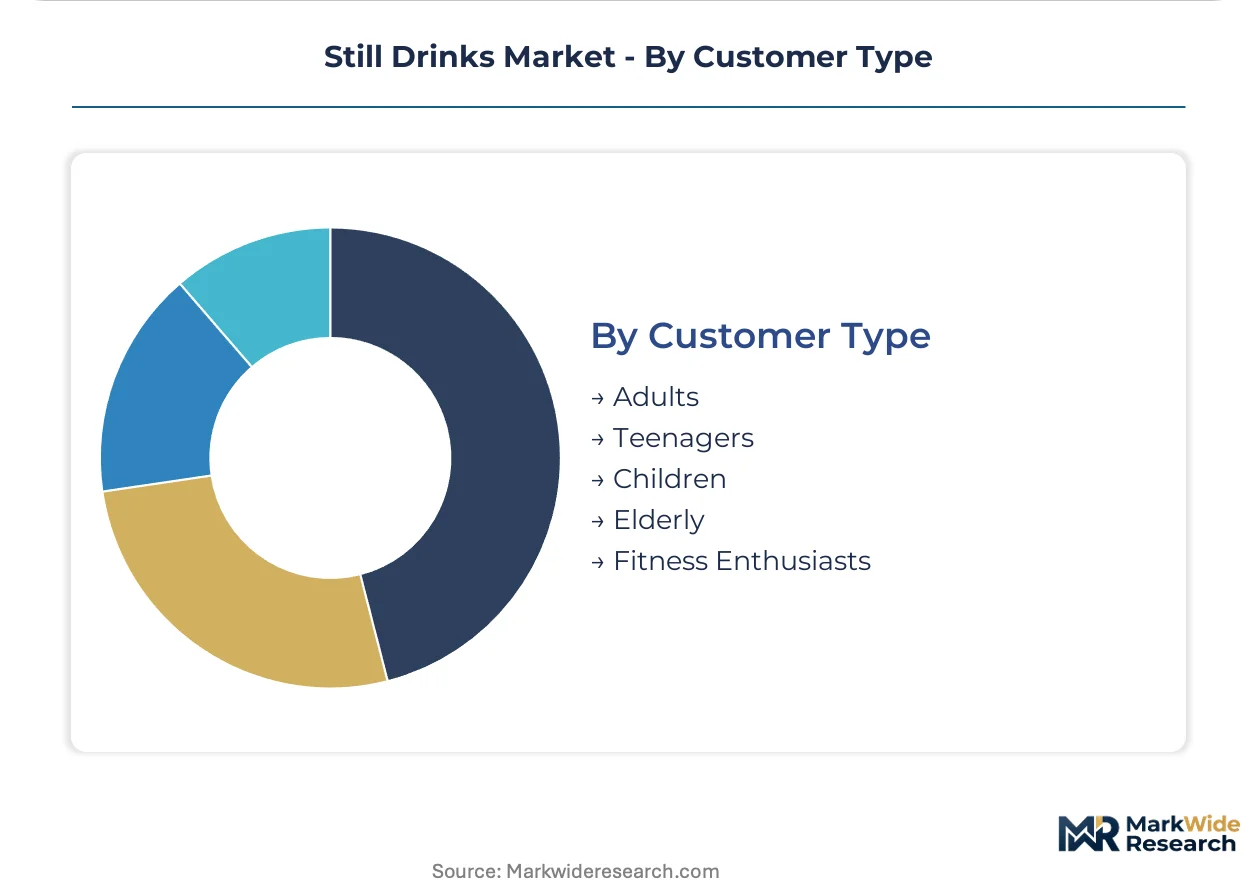
- Fitness Enthusiasts:This segment demands functional beverages fortified with electrolytes, vitamins, and protein for hydration and recovery. Demand is high in wellness-focused markets like the United States and Germany.
- Adults:Seeking refreshment and health benefits, adult consumers drive demand for low-sugar options and premium juices. This demographic often prioritizes ingredient transparency.
- Teenagers:This group is drawn to flavored waters, energy drinks, and fruit juices with appealing taste and convenient packaging.
- Children:Parents prioritize juices and flavored waters with reduced sugar content and added vitamins in child-friendly packaging.
- Elderly:This demographic seeks hydrating and nutritious options, including fortified beverages and easily digestible fruit juices.
Tailored formulations for Fitness Enthusiasts offer significant growth potential. The broad appeal of Adults ensures stable foundational demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry is evident, with developed markets like the United States supporting premiumization while emerging economies such as India prioritize affordability. This dynamic shapes product offerings and distribution strategies across diverse geographies. Governments also influence market access through varied regulatory frameworks.
United States
Demand for functional beverages among fitness enthusiasts drives product innovation in the United States. The U.S. FDA imposes stringent labeling requirements for nutritional content and health claims. Major metropolitan areas like New York and Los Angeles exhibit high consumption of premium and specialized still drinks.
China
Urbanization concentrates demand for premium bottled water and fruit juices in China. Regulations from SAMR govern beverage composition and safety, influencing market entry. Cities such as Shanghai and Beijing represent significant markets for high-quality, convenient still drink options.
Germany
Health-conscious consumers in Germany seek cold-pressed fruit juices and low-sugar options. The European Food Safety Authority (EFSA) dictates nutritional content and health claim standards. Major urban centers like Berlin and Munich show strong preference for sustainable packaging formats, including cartons.
India
Middle-class consumers in India create dense markets for bottled water and fruit juices, driven by safety concerns. India's FSSAI rules for fortified foods create a favorable environment for new product launches. Metropolitan hubs such as Mumbai and Delhi are focal points for premium still drink consumption.
Mexico
Government-implemented sugar tax regulations are reshaping product formulations in Mexico towards lower-calorie options. These policies directly impact manufacturers' ingredient choices and R&D cycles. Mexico City and Guadalajara are key areas where consumers adapt to new product offerings under these tax structures.
Still Drinks Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the still drinks market. The competitive landscape features a distinct mix of global beverage giants and agile niche players. Strategic archetypes include vertically integrated mass-market producers, focused on volume and efficiency, and asset-light, specialized brands targeting specific consumer needs. Dominant competitive moves across the industry involve continuous portfolio diversification and aggressive geographic expansion into emerging markets.
At the scale-driven end, The Coca-Cola Company and PepsiCo exemplify global beverage conglomerates leveraging vast distribution networks and diversified portfolios. The Coca-Cola Company utilizes its extensive global reach, particularly for its flavored and fortified water offerings, to maintain market share across various still drink categories globally. PepsiCo, a U.S.-based Inc., competes through a broad range of functional drinks, expanding its presence in health-oriented segments and responding to evolving consumer preferences for healthier options. Nestlé, a Swiss AG, occupies a premium position, anchoring its brand on purity and quality within the bottled water category, particularly in urban centers. These entities represent the established market leaders, commanding significant operational scale and brand recognition across multiple geographies.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestlé |
| Suntory Beverage & Food |
| Keurig Dr Pepper |
| Monster Beverage |
| Red Bull GmbH |
| Danone |
| Dr Pepper Snapple Group |
| Others |
Cost & Logistics Intelligence
U.S. FDA labeling requirements gate supply qualification for functional beverages and enable price differentiation for health-claimed products. This regulatory influence directly impacts both product formulation and market positioning across diverse geographies.
Pricing Analysis
Configured-to-order pricing is not prevalent in still drinks; instead, pricing stratifies across premium, standard, and economy tiers. Brand premium and specific certification levels, such as FSSAI approval for fortified products, drive price differentiation. Input price volatility, particularly for fruit concentrates and sugar, creates margin pressure for manufacturers. Fitness enthusiasts and urban consumers exhibit lower price sensitivity for premium offerings, while general household purchases remain highly price-sensitive.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume, perishable still drinks, while some specialized ingredients might require strategic stockpiles. Geographic supply for key inputs concentrates in Brazil for sugar and China for certain fruit concentrates. The still drinks market draws from global petrochemical hubs for PET resin. Packaging regulation divergence, particularly on plastic content across the EU and North America, presents a structural supply chain risk. Distribution runs through a fragmented network of supermarkets, convenience stores, and rapidly expanding online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Still Drinks Market offers a defensive moat, largely due to regulatory entrenchment which creates high barriers to entry for new formulations. This structural advantage protects established players.
For Market Incumbents:Compound global distribution networks by integrating last-mile delivery solutions in urban centers across India and China. Diversify existing portfolios towards functional beverages to counter the threat from smaller, asset-light brands. Invest in advanced HPP technology to extend shelf life for premium cold-pressed juices without compromising nutritional integrity. Strengthen channel control in supermarkets and convenience stores to maintain market share against new entrants.
For New Entrants and Emerging Players:Lead with specialized functional formulations targeting underserved consumer needs, such as nootropic drinks or plant-based protein beverages. Leverage online retail and direct-to-consumer subscription models to penetrate niche segments, bypassing traditional retail gatekeepers. The rural markets in Southeast Asia and Africa represent a penetrable segment for affordable, basic hydration products. Focus on transparent ingredient sourcing to appeal to health-conscious consumers in the United States and Germany.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across packaging and reformulation segments due to sustainability mandates. Focus on asset-light brands with strong consumer loyalty in niche functional categories as potential acquisition targets. These brands often possess agile R&D capabilities and direct consumer relationships. The long-term viability hinges on resilience against evolving sugar taxes and plastic packaging regulations over the next decade. Revision becomes warranted when global input commodity prices cross critical volatility thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Functional Drinks | Addresses growing demand from fitness enthusiasts for enhanced hydration. |
| Investment in Recycled PET (rPET) Capacity | Mitigates plastic packaging mandates from the EU Green Deal. |
| Direct-to-Consumer (D2C) Channel Expansion | Bypasses traditional retail gatekeepers for niche beverage brands. |
| High-Pressure Processing (HPP) Adoption | Preserves nutritional integrity for premium cold-pressed juices. |
| Rural Market Penetration in Africa | Captures significant volume opportunity for affordable hydration products. |
Research Approach
Desk research of regulatory filings, industry reports, and financial disclosures preceded structured interviews with beverage R&D directors, supply chain managers, and marketing leads. This primary and secondary data collection ensured comprehensive market understanding. Bottom-up data aggregation and top-down market sizing validated the findings, providing a robust analytical foundation for the study.
Variance decomposition identified key drivers impacting market growth across the analysis window, utilizing a quantitative model. Segmentation dimensions included product type, packaging type, distribution channel, and customer type, with a specific focus on functional additives. Compound annual growth rates were derived from historical trends and projected market dynamics. Consumer health consciousness and evolving plastic packaging mandates served as critical forecast inputs.
The analysis sits within stated boundaries; outcomes outside stable regulatory environments or predictable consumer shifts would require recalibration. Forecasts reflect assumptions regarding macroeconomic stability and predictable technological evolution. Revision becomes warranted when global input commodity prices cross critical volatility thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Solid Beverages Market
Beverages
Chill Block Market
Beverages
Blenders Market
Beverages
Victorian Jars Market
Beverages
Dairy Based Beverages Market
Beverages
Caffeine Mint Market
Beverages
South America Energy Drink Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Morocco Bottled Water Market
Beverages
Popping Bobas Market
Beverages
Superfood Infused Beverages Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Tonic Water Market
Beverages
India Bottled Water Market
Beverages
Low Fat Drinks Market
Beverages
Japan Kombucha Market