
 Bottled Craft Beer Market | 2026-2036
Bottled Craft Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Craft Beer Market Outlook
American independent brewers is pivoting toward regional malt sourcing and localized distribution networks to reduce transport costs and strengthen terroir narratives. The Boston Beer Company leverages its diversified brand architecture to sustain volume across seasonal and year-round portfolios. Sierra Nevada Brewing Co. anchors its competitive position through in-house production of hops and energy-independent brewery operations. D.G. Yuengling & Son Inc. dominates the mid-Atlantic and Southeastern states with heritage lager formulations and deep wholesaler relationships.
Bottled craft beer denotes small-batch, independently produced fermented beverages packaged in sealed glass containers, typically exhibiting alcohol-by-volume concentrations between four and twelve percent and brewed with traditional or experimental malted barley, hops, yeast, and water profiles. The product serves premium consumer occasions where flavor complexity, provenance transparency, and brand storytelling command price premiums over mass-market alternatives. Ales and IPAs occupy the fastest-expanding flavor territory as hop-forward profiles attract younger demographics, while glass bottles retain structural importance in gift and collector segments despite aluminum can growth in convenience retail. Distribution through bars and restaurants captures the highest margin pools per hectoliter, though online channels are extending reach into underserved postal codes.
The Alcohol and Tobacco Tax and Trade Bureau enforces labeling, formula approval, and excise tax compliance for American craft brewers, while the FDA oversees ingredient safety and allergen disclosure under the Food Safety Modernization Act. In Europe, EFSA and national regulators apply varying additive restrictions and alcohol taxation tiers that fragment cross-border product standardization. Stakeholders must monitor evolving deposit-return schemes and single-use packaging mandates, as regulatory divergence between jurisdictions will determine which brewers can scale bottled formats profitably versus retreating into draft or can-only portfolios.
Market Dynamics
The EU Green Deal's packaging waste mandates are forcing brewers to redesign bottle formats and carbon accounting systems ahead of enforcement deadlines, compressing margins for exporters while rewarding domestic circular-economy investments.
Growth Catalysts
- Deposit-Return Schemes:Germany's DRS expansion under EU Single-Use Plastics Directive is accelerating glass bottle recovery rates and reducing virgin material costs for compliant brewers.
- Gastropub Channel Expansion:Specialty bars in Munich and Berlin are dedicating tap handles to hyperlocal craft portfolios, creating captive demand for limited-release bottled variants.
- Carbon Labeling Requirements:The EU Green Deal's Product Environmental Footprint framework is differentiating low-emission brewers in retail shelf placement decisions.
Market Restraints
- Barley Price Volatility:Ukrainian grain supply disruptions and Canadian drought cycles are squeezing malt input costs for independent brewers without long-term purchase agreements.
- Glass Furnace Concentration:European container glass production clusters in Germany, Italy, and France, creating single-source vulnerability for craft brands dependent on amber and green bottle supply.
- Cross-Border Tax Fragmentation:Varying alcohol excise tiers between EU member states block standardized pricing and force costly formula adjustments for export-bound batches.
Strategic Opportunities
- Poland's Underserved Premium Tier:Warsaw and Krakow's emerging craft scenes lack domestic bottled alternatives, creating import white space for German and Czech brewers with established DRS logistics.
- Direct-to-Consumer Subscription Models:Brewery-owned monthly clubs bypass wholesale markups and capture full margin from collector segments seeking limited releases.
- Renewable Thermal Energy Integration:Breweries installing biogas or solar thermal systems qualify for EU Green Deal transition financing, offsetting capital intensity of bottle line upgrades.
Industry Challenges
- Brewmaster Talent Scarcity:Traditional German brewing apprenticeships are not producing sufficient personnel trained in experimental hop profiles and mixed-culture fermentation demanded by craft consumers.
- Legacy ERP Integration:Mid-sized brewers attempting to implement batch-tracking software for EU digital product passport compliance face data migration friction with decades-old production management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Craft Beer Market |
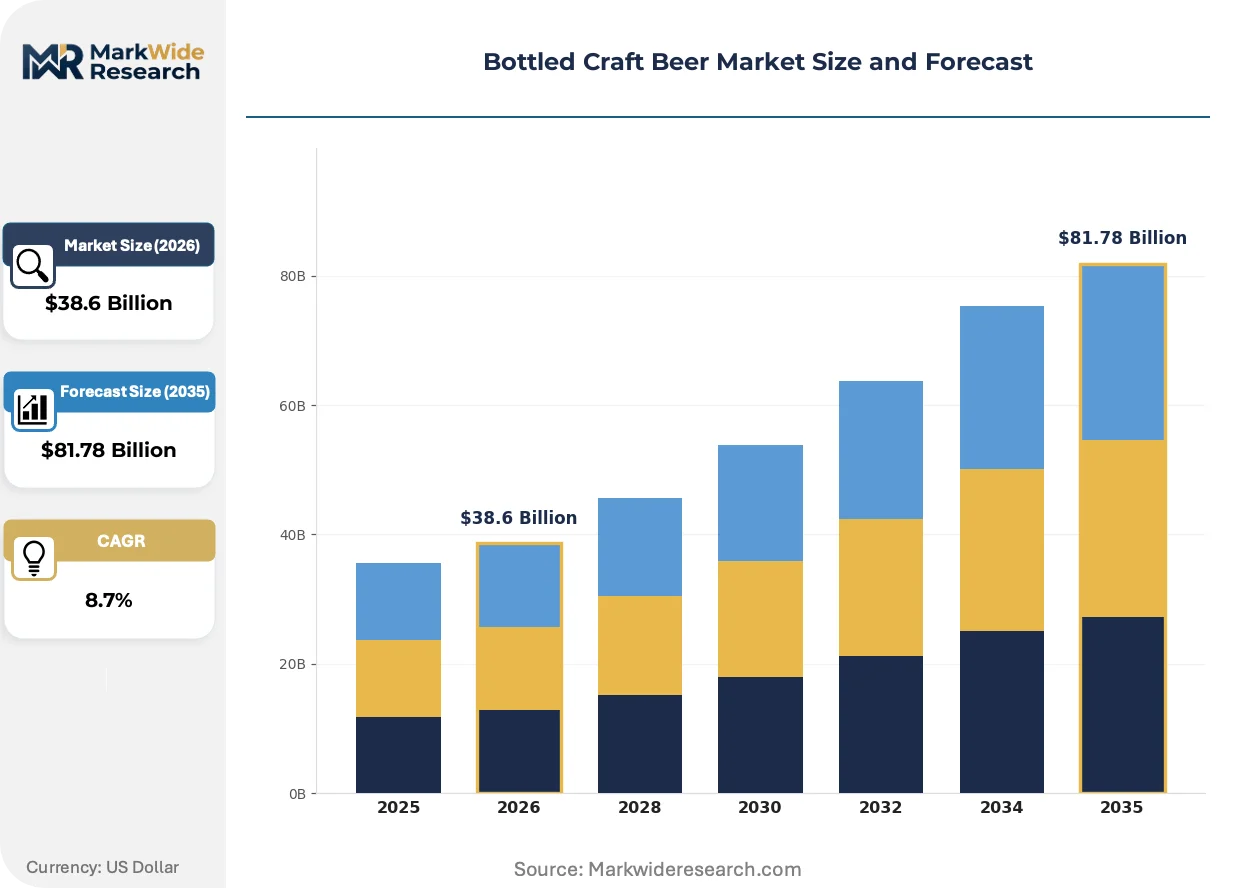
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ales, Lagers, Stouts, IPAs Flavor Profile: Citrus, Malty, Hoppy, Spicy Packaging Type: Glass Bottles, Cans, Kegs, Draft Distribution Channel: Retail Stores, Online, Bars, Restaurants |
| Companies Covered | Anheuser-Busch InBev, Heineken NV, The Boston Beer Company Inc., Molson Coors Beverage Company, Constellation Brands, Inc, Sierra Nevada Brewing Co., D.G. Yuengling & Son Inc., New Belgium Brewing Company Inc., Bell’s Brewery, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Craft Beer Market Strategic Shifts
Packaging technology and regulatory disclosure requirements are converging to reshape how craft beer reaches premium consumers, with sustainability credentials now functioning as a sorting mechanism between shelf-stable and perishable channel strategies.
Reusable bottle pooling systems are modularizing supply chain relationships across Northern Europe. Danish and Dutch brewers are adopting standardized bottle formats compatible with shared washing and redistribution infrastructure. This technology is compressing packaging cost structures for participants while excluding non-compliant competitors from retail listings.
The EU Green Deal's Corporate Sustainability Reporting Directive is mandating Scope 3 emissions disclosure for brewers above revenue thresholds. German producers are deploying blockchain-enabled provenance tracking to satisfy auditor requirements. Mid-sized independent breweries lacking compliance infrastructure face exclusion from supermarket private-label contracts.
Collector behavior is rotating toward limited-edition bottle releases with verifiable scarcity mechanisms. Specialty retailers in Hamburg and Cologne are hosting allocation lotteries for barrel-aged variants. This pattern is most visible in urban centers where craft consumption has matured beyond discovery-phase experimentation into asset-like acquisition habits.
Bottled Craft Beer Market Segmentation
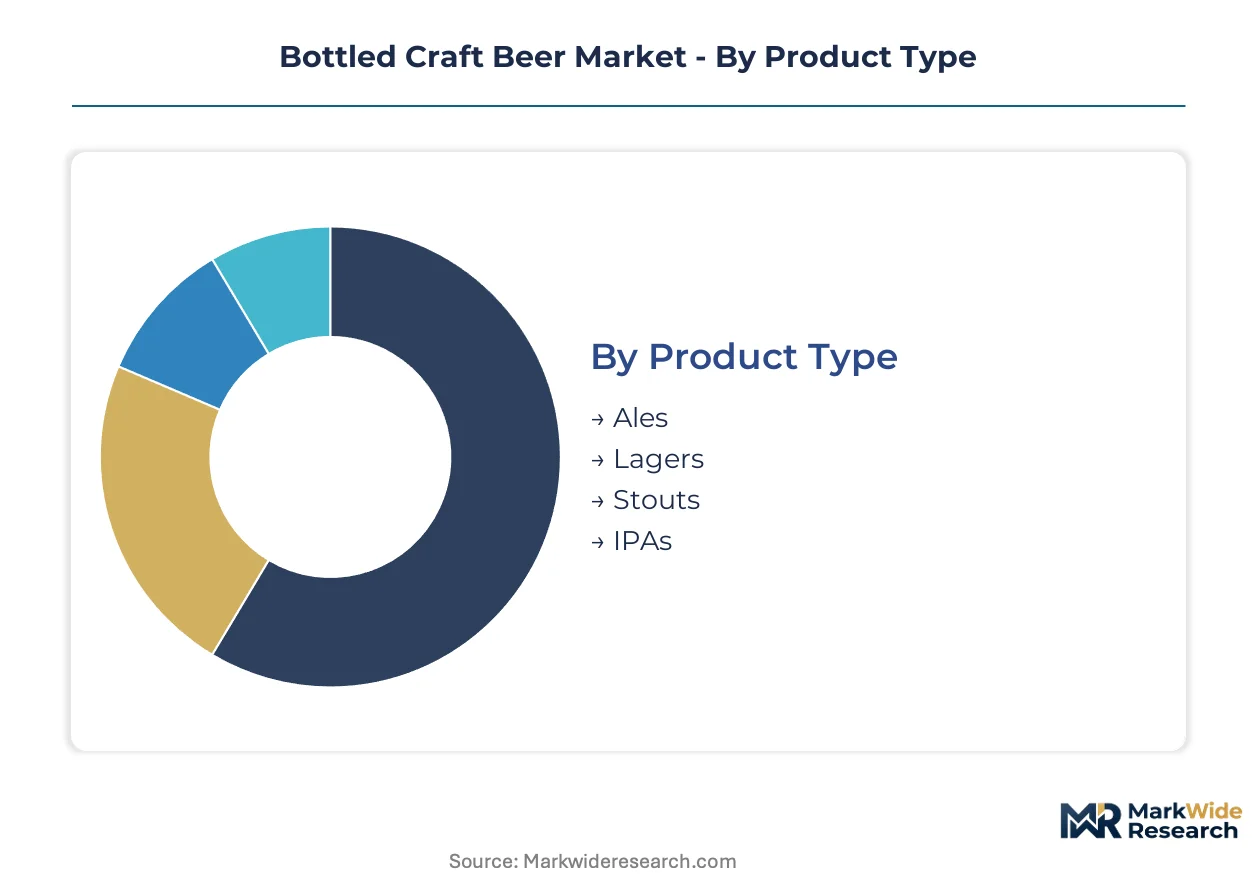
Segmentation in bottled craft beer separates commodity-adjacent volume plays from margin-rich premium positioning. Brewers configure production runs, packaging formats, and channel investments around these divides to capture either scale efficiency or price premiums.
Product Type:
Standardization dominates lager formulations while ales and experimental styles permit ingredient differentiation and seasonal rotation.
- Ales:Fermented at warmer temperatures with top-fermenting yeast strains, producing fruit-forward ester profiles. Demand concentrates in UK and Belgian import channels where traditional brewing heritage validates premium positioning against domestic lager alternatives.
- IPAs:India Pale Ale variants deploy aggressive dry-hopping schedules and elevated bitterness units. American independent brewers anchor portfolio innovation here, as hop-forward profiles attract younger demographics seeking flavor intensity over sessionability.
- Lagers:Bottom-fermented styles requiring extended cold conditioning periods. German Reinheitsgebot-compliant formulations dominate export credibility.
- Stouts:Dark-roasted malt bills delivering coffee and chocolate notes. Barrel-aging programs create collector-tier scarcity in urban specialty retail.
Leading the category by volume: Lagers. Growing fastest: IPAs.
Flavor Profile:
Flavor intensity maps directly to ingredient cost structures and brewing complexity, with hop-derived profiles commanding sourcing investments that malt-based alternatives avoid.
- Hoppy:Multiple kettle and dry-hop additions elevate raw material costs. Pacific Northwest hop contracts anchor supply security for American craft producers.
- Citrus:Achieved through hop varietals or adjunct fruit additions. Belgian and German regulators under EFSA jurisdiction scrutinize non-traditional ingredient declarations.
- Malty:Caramel and Munich malts create amber coloration and residual sweetness. Traditional German brewing apprenticeships emphasize these profiles over experimental alternatives.
- Spicy:Phenolic yeast strains or adjunct additions produce clove and pepper notes. Saison and farmhouse categories cluster here with seasonal production constraints.
Highest margin capture: Hoppy. Steepest expansion trajectory: Citrus.
Packaging Type:
Packaging choice determines shelf stability, transport economics, and regulatory exposure under diverging deposit-return schemes.
- Glass Bottles:Amber and green variants provide UV protection for hop-sensitive compounds. Germany's DRS expansion under EU Single-Use Plastics Directive rewards compliant domestic producers with reduced virgin material costs.
- Cans:Aluminum formats reduce shipping weight and enable opaque graphic design. American independent brewers favor cans for outdoor recreation occasions where glass restrictions apply.
- Kegs:Stainless steel returnable containers for on-premise draft service. Gastropub channel expansion in Munich and Berlin sustains demand for limited-release keg-only variants.
- Draft:Direct-to-tap systems bypass packaging entirely. Highest margin per hectoliter accrues to brewers with owned taproom real estate.
Dominant by volume: Glass Bottles. Gaining share fastest: Cans.
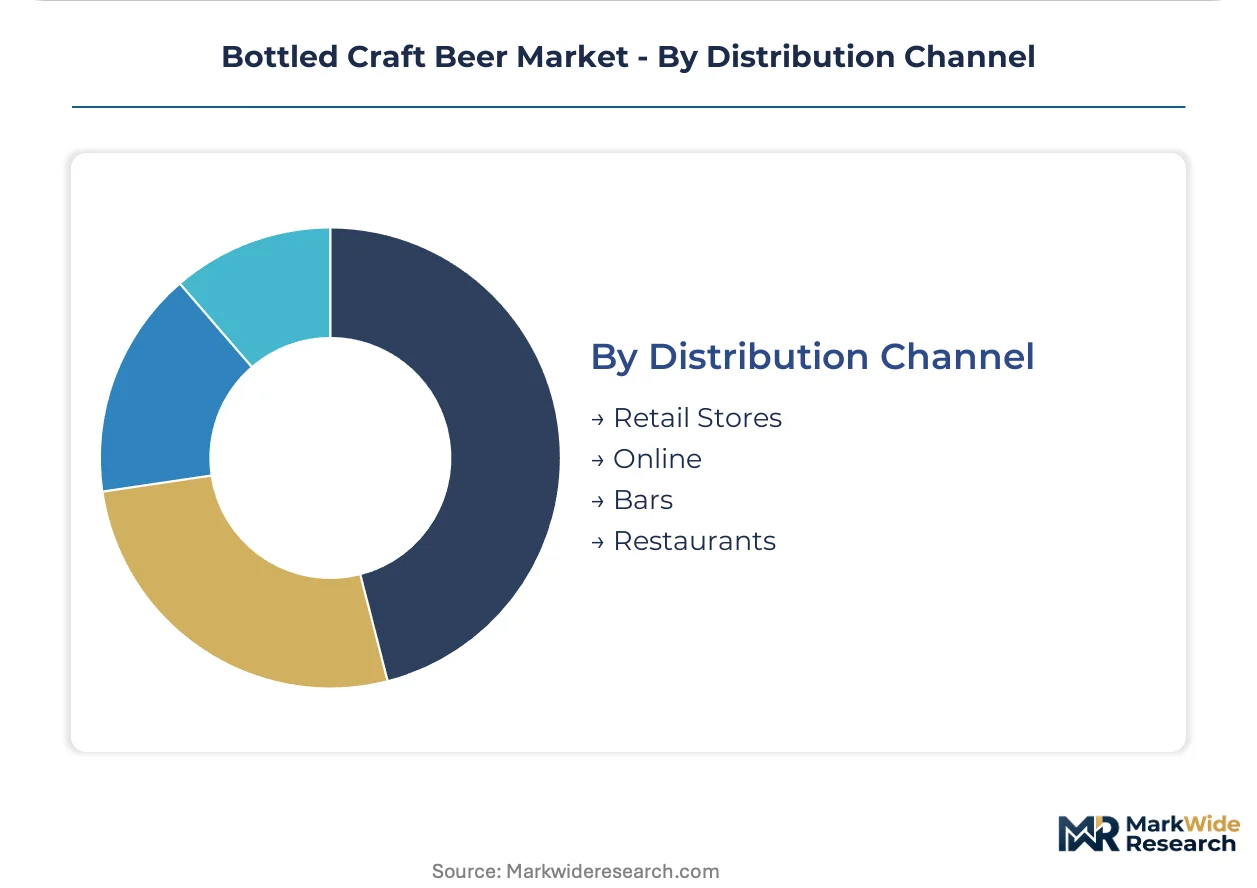
Distribution Channel:
Channel selection exposes brewers to margin compression from wholesale tiers or capital intensity from direct service requirements.
- Bars and Restaurants:On-premise accounts capture experiential consumption with trained staff recommendation. Specialty bars in Berlin dedicate tap handles to hyperlocal portfolios, creating captive demand for limited bottled releases.
- Retail Stores:Supermarket and independent off-license placements require slotting fees and promotional support. EU Green Deal carbon labeling requirements now influence shelf placement decisions.
- Online:Direct-to-consumer subscriptions bypass wholesale markups and capture full margin from collector segments. Brewery-owned monthly clubs extend reach into underserved postal codes.
Highest revenue concentration: Bars and Restaurants. Expanding most quickly: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barley cultivation belts in Canada and Germany anchor raw-material security for malt-dependent brewing operations, while urban consumption clusters in the United States and United Kingdom concentrate demand for premium bottled formats.
United States
Pacific Northwest hop farms and Colorado malt houses supply independent brewers with traceable ingredients that command terroir premiums. The Alcohol and Tobacco Tax and Trade Bureau enforces formula approval and excise tax tiers that fragment interstate distribution economics. Denver and Portland sustain dense brewery clusters where taproom real estate anchors direct-to-consumer margin capture.
Germany
Reinheitsgebot heritage intersects with experimental craft experimentation in Berlin and Munich gastropub channels. The EU Green Deal's packaging waste mandates under the Single-Use Plastics Directive accelerate deposit-return scheme compliance investments. Bavarian brewing apprenticeships supply traditional technical talent while Hamburg specialty retailers drive collector-tier allocation lotteries for barrel-aged variants.
United Kingdom
London and Manchester specialty bars dedicate tap handles to hyperlocal craft portfolios, creating captive demand for limited-release bottled variants. EFSA additive restrictions and national alcohol taxation tiers fragment cross-border standardization with EU suppliers. Scottish malt producers anchor supply relationships for English independent brewers seeking provenance differentiation.
Belgium
Traditional farmhouse and saison categories leverage phenolic yeast strains with seasonal production constraints that create scarcity premiums. REACH chemical regulations and national excise structures complicate export formula adjustments for North American-bound batches. Brussels and Antwerp retail channels concentrate demand for gift-segment glass bottle formats despite aluminum can growth elsewhere.
Canada
Prairie barley belts reduce transport costs for Ontario and Quebec independent brewers pursuing regional malt sourcing narratives. Health Canada oversees ingredient safety and allergen disclosure requirements under the Food and Drugs Act. Vancouver and Toronto urban centers sustain gastropub channel expansion that rewards hyperlocal bottled craft portfolios with premium shelf placement.
Bottled Craft Beer Market Competitive Environment
Global majors compete with regional champions across brand architecture and distribution reach, producing a tiered structure where scale efficiency confronts terroir authenticity. The vendor base separates into multinational beverage conglomerates with diversified alcohol portfolios, mid-sized independent brewers with geographic density in single markets, and hyperlocal nanobreweries serving captive metropolitan demand. Strategic archetypes include heritage lager specialists leveraging wholesaler relationships, hop-forward innovators anchoring portfolio rotation, and sustainability-first operators capturing EU Green Deal transition financing. Dominant competitive moves encompass backward integration into malt and hop production, plus direct-to-consumer subscription models that bypass wholesale markups.
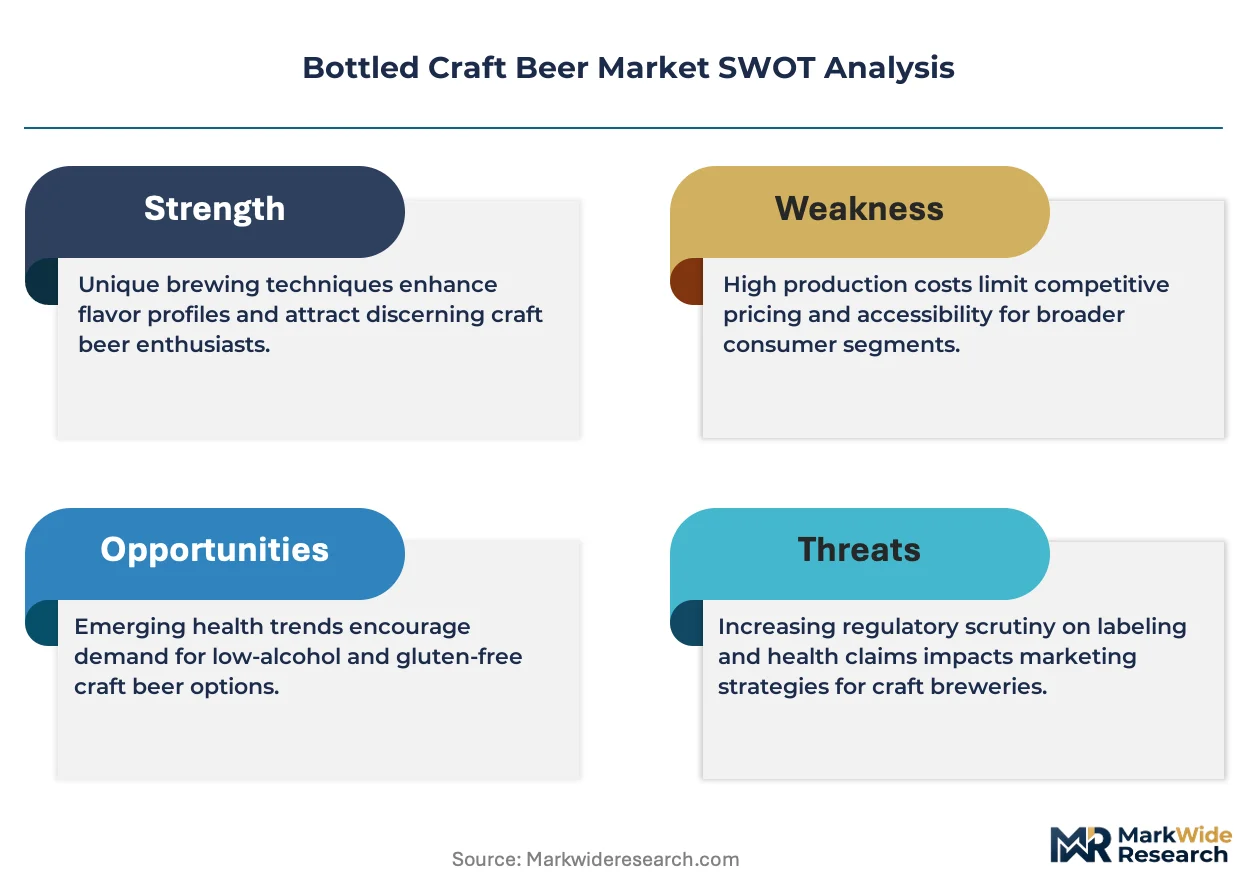
Among American independent brewers, The Boston Beer Company and Sierra Nevada Brewing Co. exemplify contrasting scale strategies within the craft segment. The Boston Beer Company occupies a diversified brand architecture position that sustains volume across seasonal and year-round portfolios. Sierra Nevada Brewing Co. represents the in-house production archetype through captive hop supply and energy-independent brewery operations. D.G. Yuengling & Son Inc. anchors the heritage-focused tier with deep wholesaler relationships concentrated in the mid-Atlantic and Southeastern states. These three entities illustrate how geographic focus, supply chain configuration, and brand narrative differentiation separate viable competitors in a consolidating market.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken NV |
| The Boston Beer Company Inc. |
| Molson Coors Beverage Company |
| Constellation Brands, Inc |
| Sierra Nevada Brewing Co. |
| D.G. Yuengling & Son Inc. |
| New Belgium Brewing Company Inc. |
| Bell's Brewery, Inc. |
| Others |
Value Chain & Pricing Dynamics
Gastropub procurement managers in Berlin and Munich concentrate purchasing power for limited-release bottled variants, anchoring a three-tier pricing structure across premium, standard, and economy levels that rewards provenance transparency and scarcity mechanics.
Pricing Analysis
After-sales service bundling separates collector-tier allocation lotteries from standard retail placements, with barrel-aged variants commanding premiums through verified scarcity mechanisms. Price differentiation rests on Reinheitsgebot certification status and hop varietal sourcing contracts. Pricing pressure stems from barley price volatility as Ukrainian grain supply disruptions compress margins for independent brewers without long-term purchase agreements. Mass-market lager segments exhibit highest price sensitivity, while urban specialty retail collectors show lowest elasticity for limited releases.
Supply Chain Analysis
Malted barley supply draws from Canadian prairie belts and German cultivation regions, with Pacific Northwest hop farms anchoring aroma varietal security for American craft producers. Glass furnace concentration in Germany, Italy, and France creates single-source vulnerability for amber and green bottle procurement. Tariff exposure runs through cross-border excise fragmentation between EU member states. Distribution runs through wholesaler tiers in mid-Atlantic states and direct-to-consumer subscription models bypassing retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging waste mandates are forcing capital-intensive compliance investments that will consolidate independent brewers unable to fund circular-economy transitions.
For Market Incumbents: Anchor competitive position through backward integration into hop production and captive renewable thermal energy systems that qualify for EU transition financing. Defend against aluminum can displacement by emphasizing gift-segment glass bottle formats with blockchain-enabled provenance tracking. Deepen wholesaler relationships in heritage lager strongholds while deploying direct-to-consumer subscription models for collector segments. For New Entrants and Emerging Players: Blockchain-enabled carbon accounting platforms offer a technology-first wedge into mid-sized brewery compliance gaps left by legacy ERP integration failures. Target Poland's underserved premium tier in Warsaw and Krakow, where domestic bottled alternatives remain scarce. Pursue white-label contract brewing arrangements with established DRS logistics providers to bypass capital-intensive bottle line investments. For Investors and Strategic Acquirers: The window for entry favors sustainability-first operators with completed EU Green Deal compliance infrastructure and verified Scope 3 emissions disclosure systems. Mid-sized German independents with circular-economy investments represent prime acquisition archetypes as margin compression accelerates. Watch for brewmaster talent scarcity triggering operational disruption signals in experimental fermentation programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hop Production | Pacific Northwest varietal contracts anchor supply security for IPA-forward portfolios against commodity volatility. |
| Direct-to-Consumer Subscription Launch | Brewery-owned monthly clubs capture full margin from collector segments in underserved postal codes. |
| Renewable Thermal Energy Installation | Biogas and solar thermal systems qualify for EU Green Deal financing while offsetting bottle line upgrade costs. |
| Blockchain Provenance Tracking Deployment | German producers satisfy CSRD auditor requirements for supermarket private-label contract eligibility. |
| Reusable Bottle Pooling System Adoption | Standardized formats compatible with Danish and Dutch shared infrastructure compress packaging cost structures. |
Study Parameters
Independent corroboration across brewmaster interviews, gastropub procurement managers, and glass furnace operators underwrites the qualitative findings in this analysis. Primary fieldwork engaged malt house technical directors, specialty retail buyers in Hamburg and Cologne, and EU regulatory compliance officers. Secondary validation drew from TTB formula approval databases, EFSA additive restriction filings, and German DRS recovery rate statistics. Bottom-up production volume estimates triangulated against top-down consumption surveys across the analysis window.
Comparable historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions including product type, flavor profile, packaging format, and distribution channel. CAGRs were derived through trend extrapolation moderated by regulatory enforcement timelines and input cost cycle assumptions. Forecast inputs incorporated barley futures volatility patterns and deposit-return scheme expansion schedules.
Several conditions sit outside the modeled scope, including sudden Ukrainian grain supply restoration, accelerated aluminum can substitution rates, and unilateral national excise adjustments. Forecasts reflect documented assumptions about EU Green Deal enforcement consistency and hop varietal yield stability. A small set of named triggers warrants ongoing watch: brewmaster apprenticeship graduation rates, legacy ERP migration failure frequencies, and cross-border tax harmonization negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Coconut Alcohol Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Frozen Cocktails Market