
 India Bottled Water Market | 2026-2036
India Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
India Bottled Water Market Insights
The gap between premium mineral water and basic packaged drinking water is broadening in India. Bisleri International leverages its decades-old distribution network to sustain dominance in tier-two and tier-three towns. PepsiCo anchors its position through Aquafina's mass-market pricing and deep modern-trade penetration. Tata Consumer Products differentiates via Himalayan's alpine sourcing story, occupying the premium shelf space in upscale retail.
Bottled water in India refers to packaged drinking water and natural mineral water sealed in food-grade containers, treated through reverse osmosis, UV sterilization, or ozonation to meet potable standards, and distributed for commercial consumption where municipal supply remains inconsistent or unsafe. The product serves households, offices, restaurants, and events as a substitute for unreliable tap water or bulky filtration installations. Still water leads volume across all distribution channels, while mineral water commands the highest margin pool due to source-certification requirements and premium positioning. Plastic bottles dominate packaging type by unit economics, though glass bottles and tetra packs gain traction in airport lounges and corporate HoReCa segments where sustainability optics influence procurement.
FSSAI labeling rules and BIS IS 14543 standards shape product formulation and quality testing cycles for every commercial bottler operating in India. The Bureau of Indian Standards mandates periodic plant audits that filter out sub-scale operators and redirect volume toward organized manufacturers with laboratory capabilities. State-level pollution control boards enforce plastic waste management rules that increase compliance costs for single-use PET formats. Stakeholders must monitor how extended producer responsibility obligations and proposed deposit-return schemes alter packaging economics and channel profitability across India's fragmented retail landscape.
Market Dynamics
Metro rail expansion and airport modernization across Maharashtra, Gujarat, and Karnataka are compressing purchase cycles for packaged hydration. FSSAI quality protocols and BIS certification mandates are filtering sub-scale operators while redirecting volume toward organized manufacturers with laboratory capabilities.
Growth Catalysts
- Urban transit infrastructure:Metro rail corridors in Mumbai, Delhi, and Bangalore generate captive foot traffic at station kiosks. Commuters purchase single-serve formats during interchanges where municipal water remains unavailable.
- FSSAI labeling mandates:The Food Safety and Standards Authority of India requires source disclosure and mineral content tables. Compliance investments separate organized bottlers from informal suppliers.
- Reverse osmosis advancement:Membrane technology costs have declined, enabling mid-tier plants to achieve IS 14543 purity thresholds without imported equipment.
Market Restraints
- PET resin price volatility:Crude-linked feedstock swings compress margin predictability for single-use bottle producers. Small bottlers lack hedging mechanisms available to integrated petrochemical players.
- Groundwater depletion:NGT extraction caps in water-stressed districts of Tamil Nadu and Rajasthan constrain source security for bulk processors. Permitting timelines now extend eighteen to twenty-four months.
- Reverse osmosis home units:Residential filtration systems priced below fifteen thousand rupees displace weekly bottled water purchases in middle-income apartment clusters.
Strategic Opportunities
- Tier-three town penetration:Cold-chain gaps in Madhya Pradesh and Odisha leave organized supply underserved. Distributor partnerships with regional dairy cooperatives offer last-mile access.
- Extended producer responsibility credits:Plastic waste management rules reward recyclate incorporation. Early compliance generates brand differentiation ahead of mandatory recycled content thresholds.
- Aluminum bottle formats:Premium hospitality and airport lounge segments pilot metal packaging for sustainability signaling. Higher unit economics offset logistics complexity.
Industry Challenges
- Microbiology laboratory scarcity:IS 14543 mandates weekly pathogen testing. Tier-two cities lack certified third-party labs, forcing bottlers to maintain captive facilities or ship samples to state capitals.
- State pollution control fragmentation:Consent-to-operate renewals vary across Maharashtra PCB, Gujarat PCB, and Karnataka SPCB. Multi-state operators navigate non-uniform inspection calendars and documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Bottled Water Market |
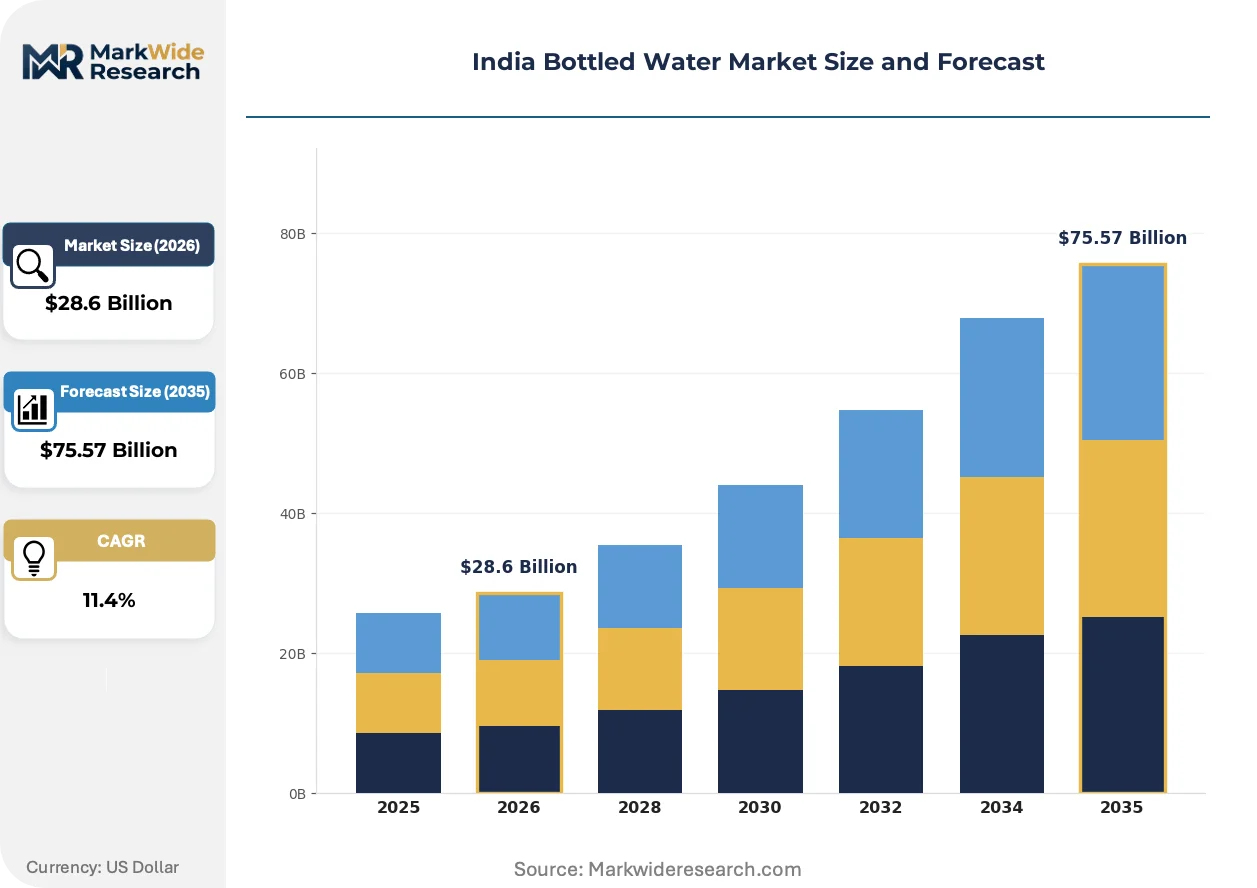
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Still Water, Sparkling Water, Flavored Water, Mineral Water Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retail, HoReCa End User: Households, Offices, Restaurants, Events |
| Companies Covered | Bisleri International, The Coca-Cola Company, PepsiCo, Parle Agro Pvt Ltd, Tata Consumer Products, DS Group, Himalayan, Manikchand Group, Reliance Consumer Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Bottled Water Market Trends and Innovations
Packaging material substitution and regulatory tightening are compressing conventional PET economics while opening premium positioning for certified sustainable formats. Technology convergence between filtration and traceability systems is reshaping quality assurance investments.
Ozonation combined with UV sterilization is overtaking chlorine-based treatment in organized plant installations. Airport caterers and institutional buyers now specify zero-residual chemical protocols in procurement tenders. This shift compresses capital recovery timelines for legacy chlorine infrastructure while elevating technical service contracts.
BIS IS 14543 audit frequency intensified under 2023 amendments. Plant certification now requires quarterly unannounced inspections rather than annual scheduled reviews. Maharashtra and Karnataka bottlers absorb compliance costs through line-item pricing to modern trade accounts.
HoReCa buyers now unbundle water procurement from beverage supply agreements. Independent hotels in Goa and Kerala negotiate direct bottler contracts rather than accepting distributor-assigned brands. This fragmentation compresses volume commitments while elevating sourcing transparency demands.
India Bottled Water Market Segmentation
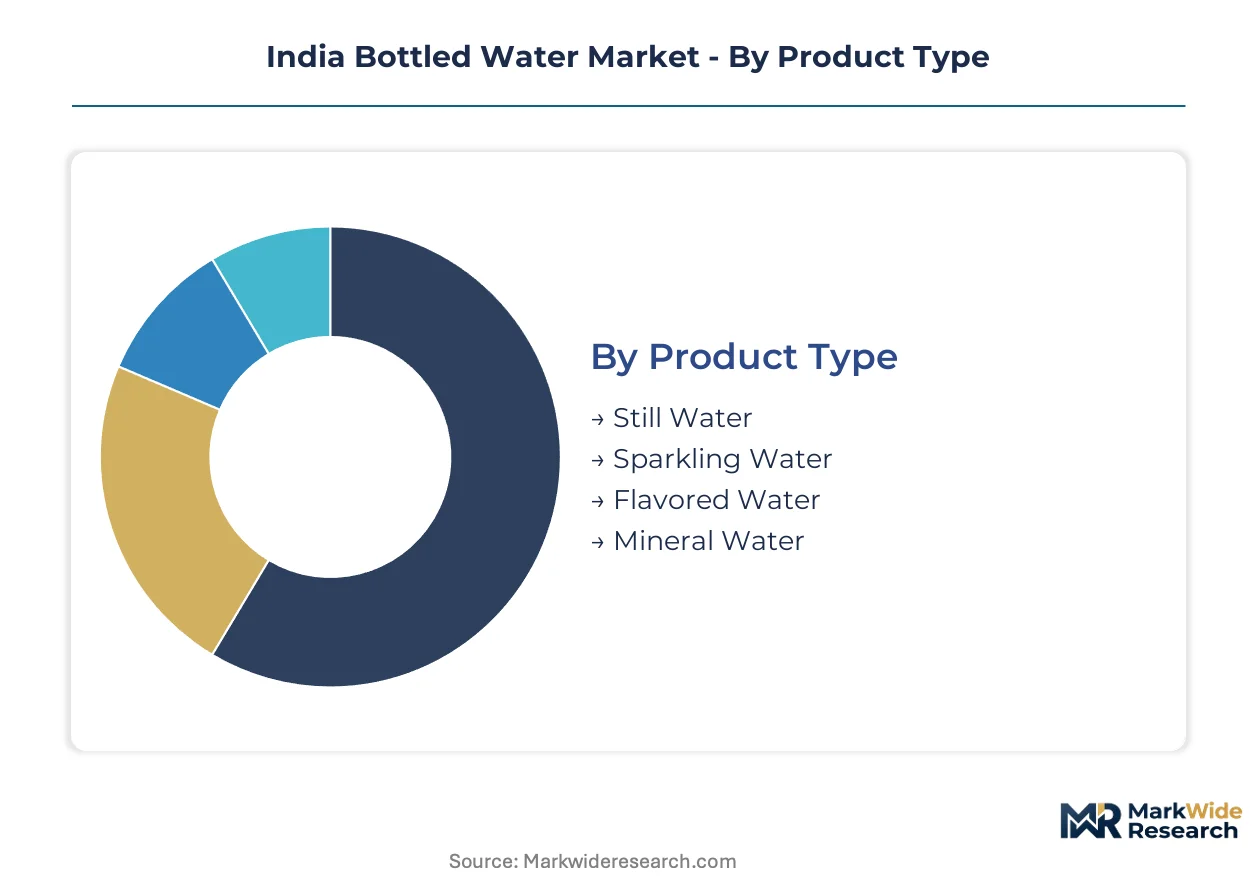
Segmentation in India's bottled water market reveals how purchase occasions, packaging economics, and channel access split consumer willingness-to-pay. Organized bottlers calibrate SKU portfolios across these divides to capture volume in mass transit while defending margin in premium hospitality.
Product Type:
Buyers in this category separate by hydration purpose versus taste preference, with certification requirements and source geography driving price ladders.
- Still Water:Plain packaged drinking water treated through reverse osmosis and UV sterilization dominates unit sales across all Indian distribution channels. Maharashtra and Gujarat metro corridors generate the highest throughput at station kiosks where commuters prioritize portability over taste complexity. FSSAI IS 14543 compliance costs filter out informal suppliers and consolidate volume toward organized manufacturers with captive laboratory facilities.
- Mineral Water:Naturally sourced water with certified mineral content tables commands premium shelf placement in upscale retail and airport lounges. Himalayan foothill extraction permits and BIS source-authentication requirements create scarcity value that supports three-to-four times the unit economics of treated still water. Karnataka and Goa hospitality clusters specify mineral water in procurement tenders to signal quality positioning to international guests.
- Sparkling Water:Carbonated variants appeal to urban millennials in Mumbai and Bangalore cafes seeking alternatives to sugary sodas.
- Flavored Water:Fruit-infused formulations target health-conscious consumers in modern trade formats avoiding artificial sweeteners.
Still water leads volumes today; mineral water is gaining share fastest.
Packaging Type:
Material choice here tracks the tension between unit economics and sustainability signaling across customer touchpoints.
- Plastic Bottles:PET formats dominate by cost efficiency, with single-serve 500ml and 1-liter units generating the bulk of metro rail and convenience store transactions. Crude-linked resin volatility compresses margin predictability for bottlers lacking petrochemical hedging capabilities. Extended producer responsibility obligations under plastic waste management rules are elevating compliance investments that favor scaled operators.
- Glass Bottles:Premium hospitality and corporate HoReCa segments in Delhi and Bangalore specify glass for sustainability optics and reuse logistics. Higher per-unit freight costs and breakage rates limit geographic radius to 150 kilometers from bottling plants, creating regional supply fragmentation.
- Tetra Packs:Aseptic carton formats gain trial in airport lounges and institutional catering where shelf stability and rectangular stacking density matter.
- Pouches:Flexible film sachets serve price-sensitive rural markets in Bihar and Uttar Pradesh where single-use affordability trumps environmental concerns.
Plastic bottles anchor current volume; glass formats are expanding most quickly in premium channels.
Distribution Channel:
Channel selection determines working capital intensity and brand control, with modern trade consolidation reshaping competitive access.
- Supermarkets:Organized retail chains in Mumbai, Bangalore, and Delhi negotiate centralized procurement contracts that demand volume commitments and promotional funding. Private label water programs at Reliance Retail and BigBasket are compressing branded shelf space and forcing national bottlers to defend position through direct-store-delivery investments.
- HoReCa:Hotels, restaurants, and caterers in Goa and Kerala are unbundling water procurement from beverage supply agreements to negotiate direct bottler contracts with sourcing transparency requirements. Independent properties specify BIS-certified sources and zero-residual chemical treatment protocols in tender documentation.
- Convenience Stores:Kirana networks and petrol station kiosks in tier-two towns remain the primary hydration access point where cold-chain gaps limit organized supply penetration.
- Online Retail:Quick-commerce platforms in dense urban clusters are piloting scheduled bulk water delivery to apartment complexes with reverse osmosis home unit displacement.
Supermarkets capture the largest revenue pool; HoReCa is climbing the fastest as procurement fragmentation accelerates.
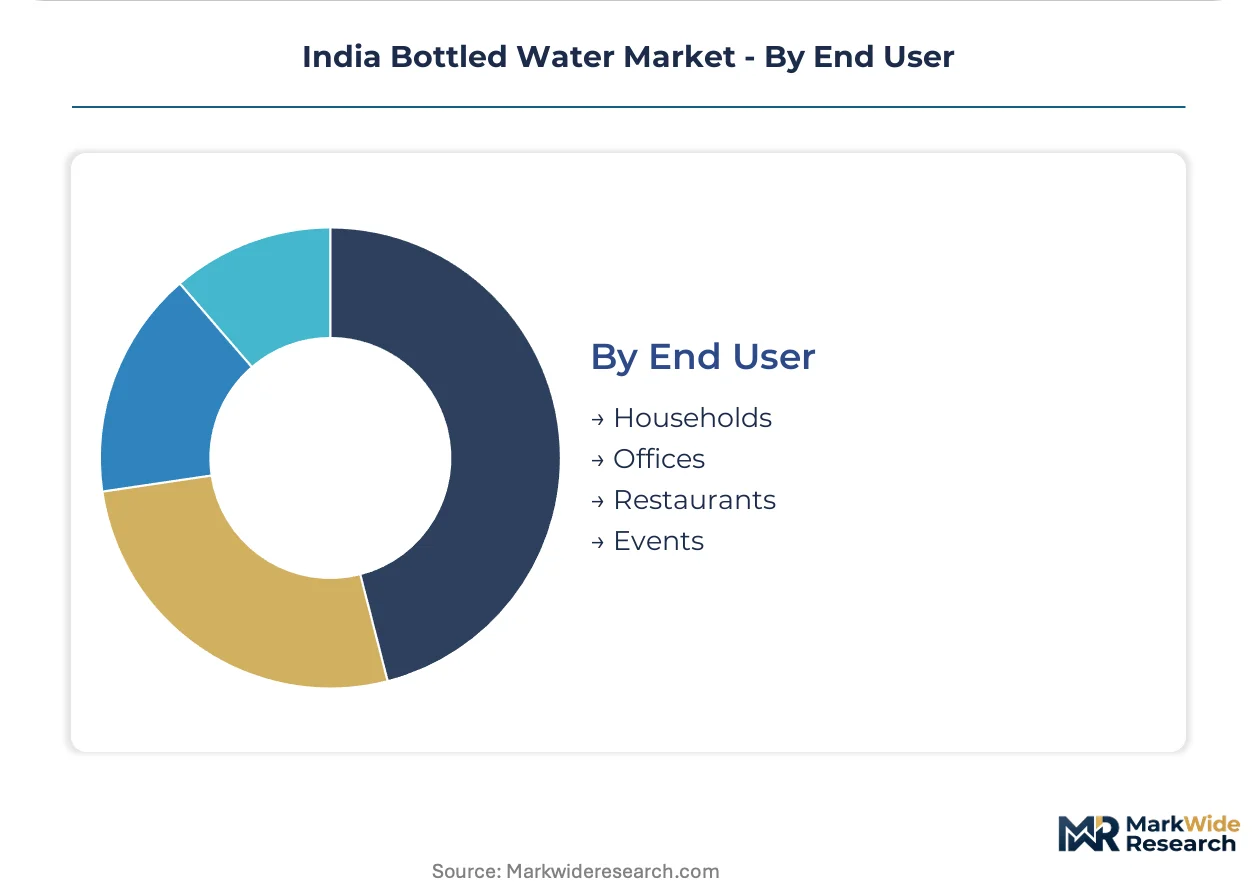
End User:
Final consumption context shapes purity expectations, purchase frequency, and format size in this segmentation.
- Households:Weekly bulk purchases of 20-liter jars dominate residential consumption in middle-income apartment clusters across Pune and Hyderabad. Residential reverse osmosis systems priced below fifteen thousand rupees are displacing bottled subscriptions in complexes with reliable municipal electricity.
- Offices:Corporate campuses in Bangalore and Gurgaon specify dispenser-compatible bulk formats with quarterly BIS laboratory testing certificates for liability protection.
- Restaurants:Dining establishments in Mumbai and Delhi source branded 1-liter bottles for table service while deploying treated still water for kitchen operations.
- Events:Wedding planners and conference organizers in Rajasthan and Gujarat negotiate single-serve bulk contracts with logo customization for sponsor visibility.
Households anchor current consumption; offices are expanding most quickly as return-to-work patterns stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's bottled water workforce clusters around distribution logistics specialists and quality compliance officers concentrated in western and southern manufacturing belts.
Maharashtra
Mumbai Metro corridors and Pune expressway halts generate captive commuter demand at station kiosks. FSSAI mandates source disclosure on all labels, forcing bottlers to maintain laboratory documentation. Nashik bottling clusters supply Mumbai's modern trade chains with daily refrigerated truck rotations.
Gujarat
Surat diamond polishing units and Ahmedabad corporate parks drive institutional bulk procurement. BIS IS 14543 quarterly audit protocols filter sub-scale operators from organized supply chains. Vadodara's petrochemical corridor provides captive PET resin access to integrated bottlers.
Karnataka
Bangalore's airport modernization and Whitefield tech campus expansion elevate premium mineral water placement. State Pollution Control Board consent-to-operate renewals now require eighteen-month groundwater extraction permits. Mysuru's natural spring sources anchor Himalayan foothill sourcing narratives for upscale hospitality.
Tamil Nadu
Chennai's film production catering and Coimbatore manufacturing canteens sustain mid-tier volume. NGT extraction caps in water-stressed districts constrain source security, extending permitting timelines to twenty-four months. Tiruppur's textile belt HoReCa segment specifies BIS-certified zero-residual chemical protocols.
Delhi-NCR
Gurugram corporate return-to-work patterns and Noida event management sectors drive office dispenser format growth. Extended producer responsibility obligations under plastic waste management rules elevate compliance investments for PET formats. Faridabad's logistics hubs enable same-day replenishment to Delhi's quick-commerce platforms.
India Bottled Water Market Competitive Landscape
Capital-heavy producers with captive bottling plants and groundwater extraction permits compete with asset-light distributors leasing third-party manufacturing capacity. The market structure tilts toward organized concentration as BIS laboratory requirements and FSSAI compliance investments filter informal suppliers. Three archetypes dominate: heritage brands with decades-old distribution networks, multinational beverage conglomerates leveraging modern trade scale, and conglomerate-backed premium specialists commanding alpine sourcing narratives. Competitive moves center on distributor partnerships with regional dairy cooperatives for tier-three penetration and direct-store-delivery investments to defend supermarket shelf space against private label expansion.
Within the heritage distribution tier, Bisleri International anchors mass-market penetration through tier-two and tier-three town networks accumulated over decades. PepsiCo occupies the scale-driven position via Aquafina's mass-market pricing and deep modern-trade relationships. Tata Consumer Products exemplifies the premium-conglomerate archetype through Himalayan's foothill sourcing story and upscale retail shelf positioning. These three represent the structural fault lines between volume, access, and margin defense in India's organized bottled water sector.
| Leading Market Players |
|---|
| Bisleri International |
| The Coca-Cola Company |
| PepsiCo |
| Parle Agro Pvt Ltd |
| Tata Consumer Products |
| DS Group |
| Himalayan |
| Manikchand Group |
| Reliance Consumer Products |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap bottlers with decades-old groundwater extraction permits anchor supply-side discipline across Maharashtra and Gujarat, translating source scarcity into pricing power that resists commoditization despite PET resin volatility.
Pricing Analysis
Bundled beverage supply agreements are unbundling into standalone water procurement contracts across Goa and Kerala hospitality clusters. Three-tier pricing structure across premium mineral, standard packaged, and economy still water levels separates Himalayan foothill sourcing from reverse-osmosis treated supply from unbranded local bottlers. Price differentiation hinges on BIS source-authentication certification and cold-chain delivery guarantees. Cost compression in economy PET formats is intensifying because Reliance Retail and BigBasket private-label programs force branded players to fund direct-store-delivery investments. Price-sensitive kirana networks in tier-two towns reject premium positioning, while airport lounges and corporate campuses absorb three-to-four times markup for glass-bottle mineral water with zero-residual chemical protocols.
Supply Chain Analysis
Single-source vulnerability sits with Tamil Nadu and Rajasthan groundwater basins where NGT extraction caps now extend permitting timelines to eighteen-to-twenty-four months. Geographic supply concentration centers on Maharashtra, Gujarat, and Karnataka where organized bottlers cluster around petrochemical corridors and metro rail distribution nodes. Raw material dependencies rest on crude-linked PET resin, food-grade ozone generation equipment, and membrane filtration systems imported from Germany and Japan. Regulatory restriction risk intensifies as state pollution control boards enforce non-uniform plastic waste management rules across Maharashtra PCB, Gujarat PCB, and Karnataka SPCB jurisdictions. Distribution runs through dairy cooperative partnerships in Madhya Pradesh and Odisha tier-three towns, modern trade centralized procurement in Mumbai and Bangalore, and quick-commerce same-day replenishment in Delhi-NCR.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in India's bottled water sector rests on aluminum format premiumization and extended producer responsibility credit monetization ahead of mandatory recycled content thresholds.
For Market Incumbents: To counter private-label compression at Reliance Retail and BigBasket, Bisleri International and PepsiCo must deepen direct-store-delivery investments in tier-two kirana networks and secure quarterly BIS IS 14543 certification ahead of unannounced inspection mandates. Captive microbiology laboratory capabilities in Nashik and Vadodara clusters filter sub-scale competitors and defend shelf space through compliance credibility.
For New Entrants and Emerging Players: Tier-three town cold-chain gaps in Madhya Pradesh and Odisha offer distributor partnership opportunities with regional dairy cooperatives already possessing last-mile refrigerated logistics. Aluminum bottle pilots in Bangalore airport lounges and premium hospitality segments enable sustainability-signaling positioning at unit economics that offset logistics complexity. The most penetrable entry vector targets corporate campuses with dispenser-compatible bulk formats and quarterly laboratory testing certificates.
For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light distributors leasing third-party manufacturing capacity rather than capital-heavy producers with captive groundwater permits and petrochemical integration. Long-term viability across the analysis window favors organized concentration as FSSAI compliance investments and BIS laboratory requirements filter informal suppliers. The signal to watch is mandatory recycled content threshold announcements under extended producer responsibility rules, which would accelerate consolidation toward scaled recyclate-incorporating players.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Bottle Format Introduction | Premium hospitality procurement tenders in Bangalore and Mumbai now specify metal packaging for sustainability signaling. |
| Dairy Cooperative Distribution Partnership | Tier-three penetration in Madhya Pradesh leverages existing cold-chain infrastructure without capital-heavy buildout. |
| Captive Microbiology Laboratory Investment | Weekly IS 14543 pathogen testing compliance filters sub-scale competitors in tier-two cities lacking certified third-party facilities. |
| Extended Producer Responsibility Credit Accumulation | Early recyclate incorporation generates brand differentiation ahead of mandatory thresholds under plastic waste management rules. |
| Direct-to-Corporate Bulk Contracting | Independent hotels in Goa and Kerala now unbundle water procurement from beverage supply agreements for sourcing transparency. |
Research Methodology
Multiple input streams — bottler plant managers, modern trade category buyers, FSSAI compliance officers, and state pollution control board regulators — were reconciled against customs records, BIS certification databases, retail audit data from Nielsen and Circana, and SEC filings from multinational beverage parents. Primary interviews with distribution channel partners and HoReCa procurement heads in Mumbai, Bangalore, and Delhi validated secondary estimates. Bottom-up SKU-level volume builds across still water, mineral water, and sparkling variants were triangulated against top-down category value assessments.
Data-stream reconciliation applied a segmentation framework across product type, packaging material, distribution channel, and end-user context throughout the forecast period. CAGRs were derived from trend extrapolation of metro rail commuter throughput, airport passenger volumes, and household reverse osmosis displacement patterns. Modeled inputs incorporated FSSAI labeling mandate compliance cost trajectories, PET resin price volatility bands, and groundwater extraction permit approval timelines across Maharashtra, Gujarat, Karnataka, and Tamil Nadu.
Underlying measurement precision varies by segment; modern trade and airport lounge channels carry tighter precision than kirana network and rural pouch estimates due to data availability. Forecasts reflect assumptions around regulatory enforcement intensity, infrastructure completion schedules, and resin price normalization. Groundwater depletion acceleration, NGT extraction cap expansion, or residential filtration technology cost breakthroughs could materially revise trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Breakfast Drink Market
Beverages
Drinking Water Market
Beverages
Collagen Drinks Market
Beverages
Caffeine Mint Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Spring Water Market
Beverages
Sparkling Water Market
Beverages
Herb Infused Water Market
Beverages
Fermented Drinks Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
US Bubble Tea Market
Beverages
Sparkling Bottled Water Market
Beverages
Collagen-Infused Water Market
Beverages
Craft Soda Market
Beverages
Hot Cocoa Mix Market
Beverages
Packaged Milkshake Market