
 Popping Bobas Market | 2026-2036
Popping Bobas Market Size, Share, and Industry Trends Forecast 2026-2036
Popping Bobas Market Insights
EU F-Gas Regulation is pivoting refrigeration-dependent popping boba supply chains toward climate-friendly cold-chain logistics. Possmei International Co., Ltd. leverages integrated alginate sourcing to sustain cost advantages across Asian export corridors. Hangzhou Boduo Industrial Trade Co., Ltd. anchors large-scale automated spherification capacity that dominates contract manufacturing for European distributors. Bossen competes through flavor-library breadth that extends beyond conventional fruit profiles into savory and botanical lines.
Popping bobas are gel-encapsulated juice spheres formed through reverse spherification, where a thin alginate or gellan membrane surrounds a flavored liquid core that bursts under mastication pressure. The primary commercial purpose is delivering concentrated flavor release and textural contrast in beverages, frozen desserts, and confectionery applications. Fruit Flavor formulations occupy the dominant volume position, while Tea Flavor variants capture premium positioning in specialty café channels. The Beverages application segment leads absolute consumption, though the Baking application segment generates higher per-unit margins through ingredient-grade certification requirements.
Food Standards Australia New Zealand (FSANZ) and the FDA enforce additive and labeling standards that determine market access for alginate-based encapsulation systems. The EU's REACH framework governs calcium chloride and cross-linking agent thresholds in food-contact applications, directly constraining formulation flexibility for exporters. Stakeholders must monitor evolving clean-label certification requirements and cold-chain infrastructure investments as decisive variables for geographic expansion decisions.
Market Dynamics
Clean-label alginate reformulation under EU REACH calcium chloride thresholds is compressing formulation flexibility while simultaneously opening premium positioning for compliant exporters.
Growth Catalysts
- EU F-Gas Regulation:Climate-friendly cold-chain logistics investments are creating compliant distribution corridors for temperature-sensitive popping boba exports into European specialty beverage channels.
- South Korea dessert café culture:Premium tea-flavor variants command shelf-space allocation in Seoul's high-traffic beverage districts, pulling volume through specialty retail.
- Reverse spherification automation:Large-scale continuous-flow encapsulation systems are reducing unit production costs for contract manufacturers serving European distributors.
Market Restraints
- Alginate input concentration:Brown seaweed harvesting capacity concentrates in Southeast Asian coastal zones, exposing processors to climate-driven supply interruptions.
- Calcium chloride cross-linker thresholds:EU REACH food-contact limits constrain shell-thickness optimization, capping burst-release performance in premium applications.
- Gellan gum substitution threat:Thermo-reversible gellan membranes offer superior heat stability in baking applications, displacing alginate in high-temperature confectionery segments.
Strategic Opportunities
- Clean-label certification tailwind:EU organic and additive-free labeling schemes reward reformulated alginate-gellan hybrid shells with retail placement premiums.
- Baking application white space:Ingredient-grade certification for oven-stable popping bobas unlocks higher per-unit margins in European artisanal bakery supply chains.
- Botanical flavor convergence:Lavender, yuzu, and herbal profiles are penetrating specialty café menus in Taiwan and South Korea beyond conventional fruit matrices.
Industry Challenges
- Spherification technician scarcity:Automated continuous-flow systems require operators trained in calcium bath chemistry and membrane rheology, creating hiring bottlenecks for mid-scale producers.
- Cold-chain capex intensity:Refrigerated transport and storage infrastructure demands upfront capital allocation that strains regional distributor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Popping Bobas Market |
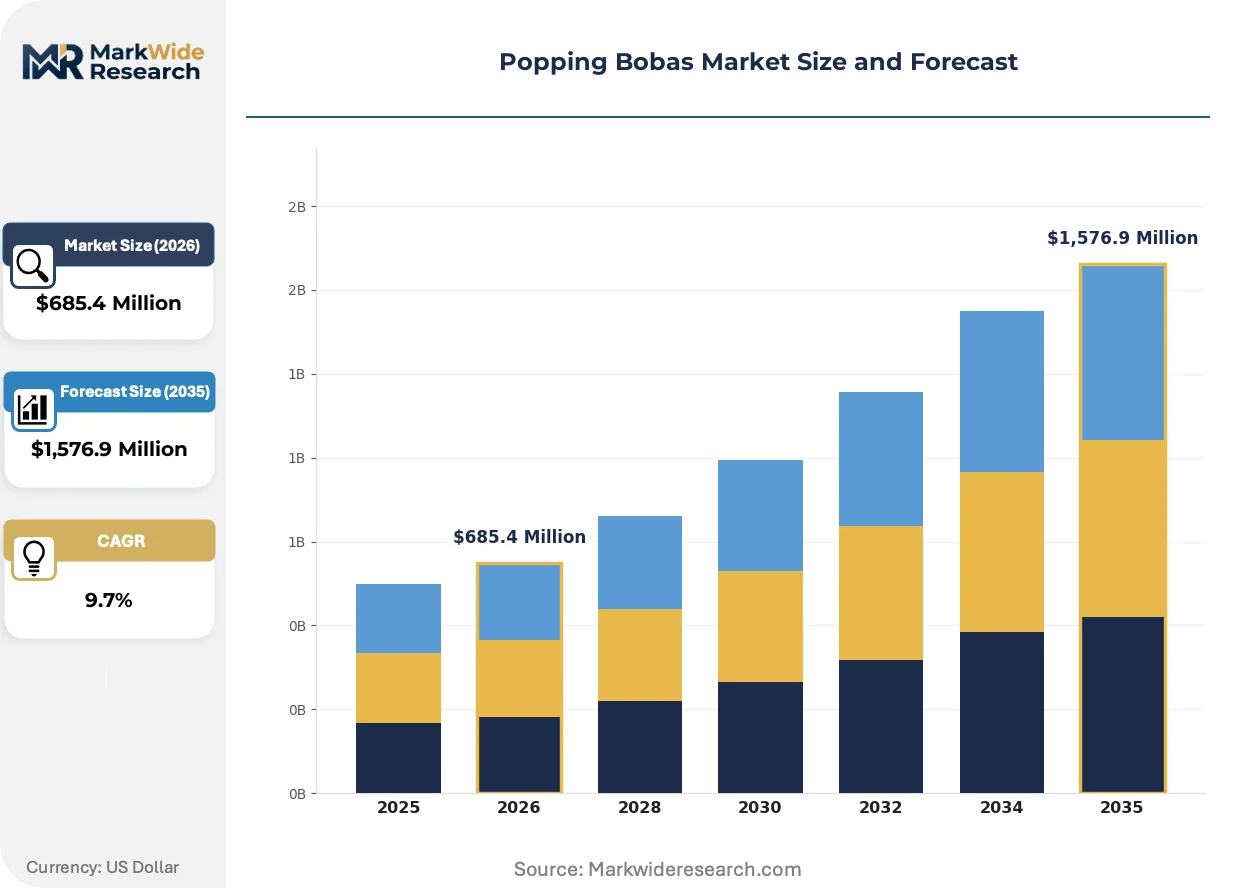
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Flavor, Tea Flavor, Yogurt Flavor, Dessert Flavor Application: Beverages, Desserts, Snacks, Baking Distribution Channel: Online Retail, Supermarkets, Food Service, Event Catering End User: Food Manufacturers, Restaurants, Cafes, Home Consumers |
| Companies Covered | Possmei International Co., Ltd., Hangzhou Boduo Industrial Trade Co., Ltd., Sunnysyrup Food Co., Ltd., Boba Box Limited, Bossen, Nordic Boba ApS, Tachiz Group, BOBAVIDA, Fanale Drinks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Popping Bobas Market Trends and Innovations
Formulation science and regulatory compliance are converging to reshape competitive positioning across alginate-based encapsulation systems. Three distinct vectors are currently active.
Gellan-alginate hybrid membranes are integrating thermal stability and burst-release control into single-shell architectures. European dessert manufacturers are adopting these formulations at accelerated procurement cycles to satisfy clean-label requirements. The technology is integrating previously separate performance tiers into unified ingredient-grade certifications.
REACH calcium chloride thresholds are constraining cross-linker concentrations in food-contact applications. Exporters to EU markets must reformulate shell compositions or forfeit retail placement in premium channels. Beverage-grade popping bobas face stricter documentation burdens than confectionery variants under EFSA guidance.
Direct-procurement relationships between bubble tea chains and encapsulation specialists are compressing traditional distributor margins. Specialty café operators in Taipei and Seoul are sourcing custom flavor profiles through bilateral contracts rather than wholesale intermediaries. This pattern is most visible in high-volume urban clusters where menu differentiation drives repeat visitation.
Popping Bobas Market Segmentation
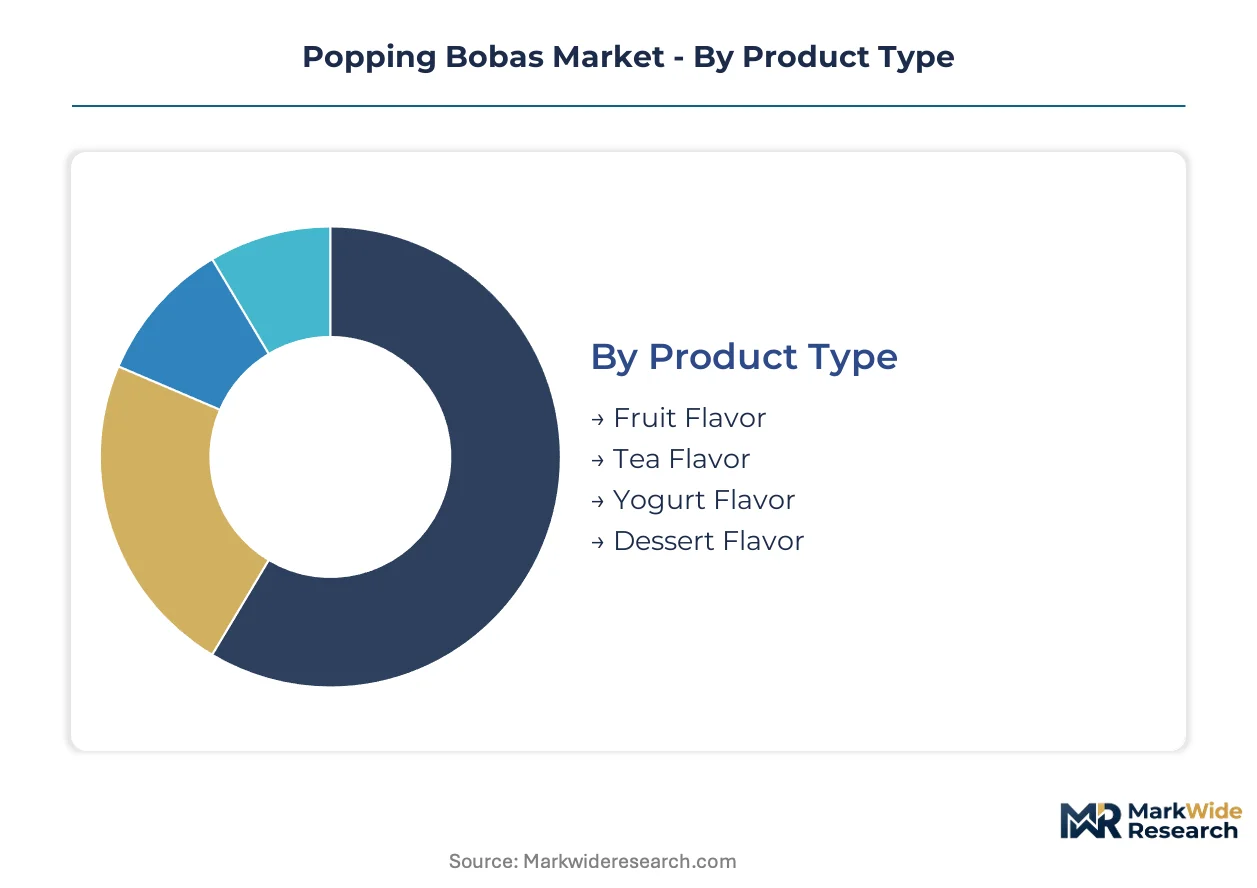
Popping boba segmentation reflects divergent technical requirements across encapsulation chemistries and thermal stability specifications. Formulation choices directly determine shelf-life parameters and end-use compatibility, creating distinct procurement patterns among bubble tea chains versus artisanal bakeries.
Product Type:
Alginate membrane thickness and cross-linker density vary sharply across flavor matrices, determining burst-release kinetics and cold-chain tolerance.
- Fruit Flavor:Juice concentrates from mango, strawberry, and lychee dominate commercial volumes through reverse spherification with standard calcium bath protocols. Taiwan's specialty beverage sector and South Korea's dessert café culture pull the majority of procurement through direct-procurement contracts with encapsulation specialists.
- Tea Flavor:Oolong, matcha, and Earl Grey infusions command premium positioning via tighter membrane control for concentrated flavor release. Seoul's high-traffic beverage districts allocate disproportionate shelf space to these variants, driving bilateral sourcing agreements that bypass traditional wholesale intermediaries.
- Yogurt Flavor:Dairy-based cores require modified alginate-gellan hybrid shells for pH stability.
- Dessert Flavor:Chocolate and vanilla formulations target confectionery integration with heat-resistant membrane options.
Mature deployment sits with Fruit Flavor. Newer deployment is concentrated in Tea Flavor.
Application:
End-use thermal exposure dictates shell architecture, separating ambient-stable beverage grades from oven-certified baking grades.
- Beverages:Cold-chain-dependent spherification dominates bubble tea and specialty café channels through alginate membranes optimized for refrigerated transport. EU F-Gas Regulation compliance investments are creating certified distribution corridors for temperature-sensitive exports into European specialty channels.
- Baking:Ingredient-grade certification demands gellan-alginate hybrid membranes with thermo-reversible properties for oven stability. European artisanal bakery supply chains generate higher per-unit margins through additive-free labeling schemes that reward compliant shell reformulation.
- Desserts:Frozen yogurt and gelato applications prioritize burst-release timing over heat resistance.
- Snacks:Dry-packaged popping bobas for retail confectionery require moisture-barrier secondary packaging.
Volume leadership belongs to Beverages. Margin expansion is climbing the fastest in Baking.
Distribution Channel:
Cold-chain infrastructure intensity separates capital-intensive food service logistics from direct-to-consumer parcel delivery.
- Food Service:Refrigerated transport networks serving bubble tea chains and dessert cafés concentrate procurement in Taiwan and South Korea. Automated continuous-flow encapsulation systems at Hangzhou Boduo anchor contract manufacturing scale for this channel.
- Online Retail:Direct-to-home consumers of DIY bubble tea kits drive ambient-stable formulation demand with extended shelf-life specifications.
- Supermarkets:Mass retail placement requires clean-label certification and multilingual packaging compliance.
- Event Catering:Mobile beverage stations source single-serve portion formats with disposable dispensing systems.
Procurement scale concentrates in Food Service. Channel diversification is gaining share fastest in Online Retail.
End User:
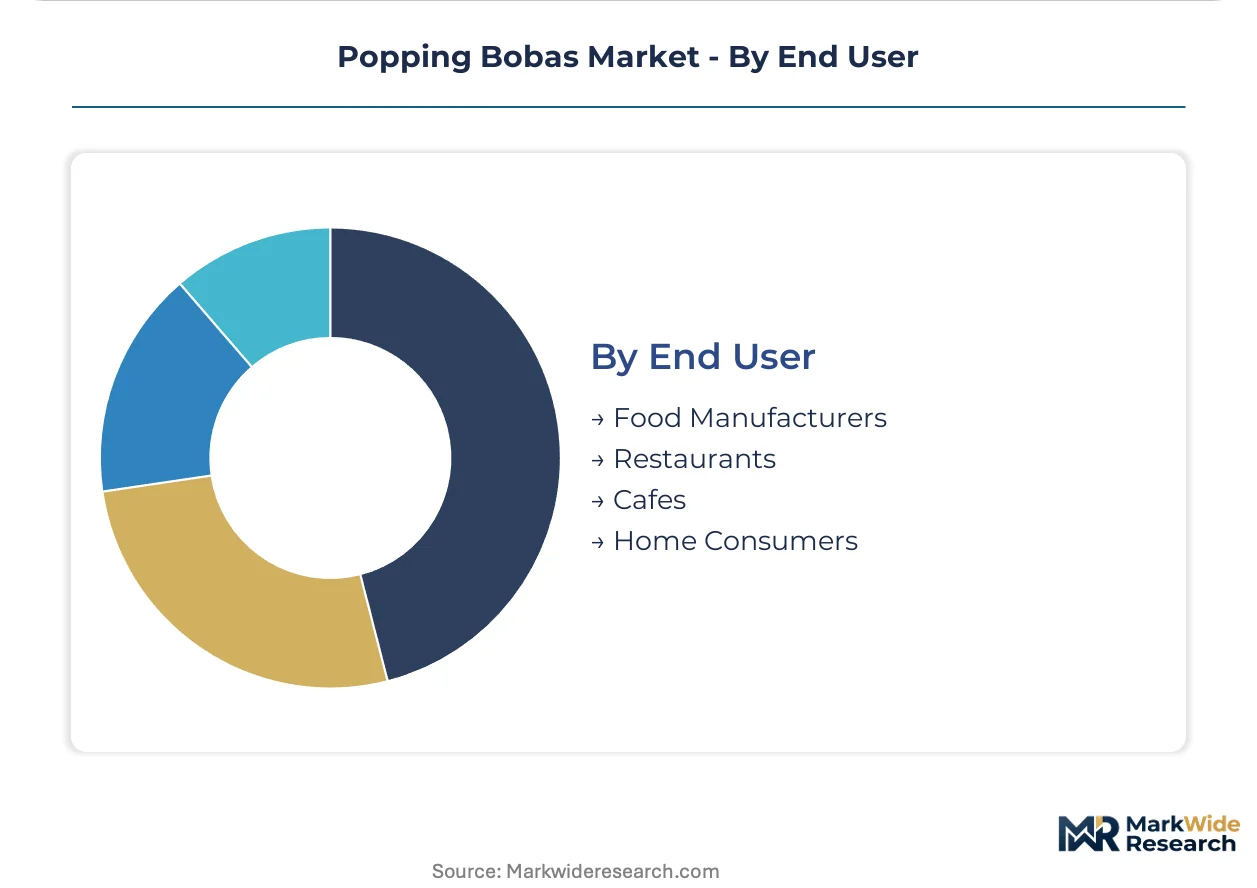
Technical capability and formulation customization requirements segment buyers across industrial-scale automation versus artisanal manual processing.
- Restaurants:Menu differentiation in Taipei and Seoul's urban clusters drives custom flavor profile development through direct encapsulation specialist relationships. These operators bypass distributors to secure exclusive botanical and savory line extensions.
- Food Manufacturers:Industrial-scale spherification demands ingredient-grade certification and batch consistency documentation for co-manufacturing agreements.
- Cafes:Specialty beverage operators prioritize rapid inventory turnover and localized flavor trends.
- Home Consumers:DIY kit purchasers favor pre-portioned formats with simplified calcium bath instructions.
Contract sophistication peaks with Food Manufacturers. Customization intensity is expanding most quickly in Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for popping bobas concentrates in East Asian specialty beverage markets, with Taiwan and South Korea driving premium flavor innovation. Export corridors into Europe face reformulation pressures from REACH calcium chloride thresholds. Cold-chain infrastructure investments are reshaping distribution economics across temperate climate zones.
Taiwan
Taipei's bubble tea chains source custom botanical profiles through direct-procurement contracts with encapsulation specialists. The country's food safety regulator enforces additive disclosure standards for alginate-based encapsulation systems. Taichung's industrial corridor hosts automated spherification facilities serving domestic café clusters and European export orders.
South Korea
Seoul's dessert café culture pulls disproportionate procurement volume for premium tea-flavor variants with tighter membrane specifications. MFDS maintains strict calcium chloride limits in food-contact applications that align with EU REACH thresholds. Busan-Ulsan logistics hubs coordinate refrigerated export shipments into Southeast Asian specialty beverage channels.
United States
Bubble tea chain expansion across California and New York Metro drives ingredient-grade certification demand for co-manufacturing agreements. FDA additive and labeling standards govern alginate membrane compositions for interstate commerce. Los Angeles-based distributors are investing in climate-controlled warehousing to reduce cold-chain spoilage rates.
Germany
Artisanal bakery supply chains in Bavaria and North Rhine-Westphalia generate premium pricing for oven-stable gellan-alginate hybrid shells. EFSA guidance imposes stricter documentation burdens on beverage-grade popping bobas than confectionery variants. Hamburg's port logistics infrastructure anchors import distribution for alginate raw materials from Southeast Asian coastal zones.
United Kingdom
Specialty café operators in London source clean-label certified popping bobas for menu differentiation in high-traffic beverage districts. The Food Standards Agency enforces additive labeling requirements that reward reformulated shell compositions with retail placement premiums. Midlands-based contract manufacturers are upgrading continuous-flow encapsulation capacity to serve European distributor networks.
Popping Bobas Market Competitive Landscape
Taiwanese producers anchor the premium flavor-innovation tier; Chinese manufacturers hold scale-driven contract manufacturing positions. The vendor base separates into three distinct strata: integrated alginate sourcers, automated encapsulation specialists, and flavor-library diversifiers. Strategic moves concentrate on backward integration into brown seaweed supply chains and bilateral direct-procurement relationships with bubble tea chains.
Among Taiwan-based specialists, Possmei International Co., Ltd. exemplifies integrated alginate sourcing advantages across Asian export corridors. Hangzhou Boduo Industrial Trade Co., Ltd. occupies the automated spherification tier with large-scale continuous-flow capacity serving European distributors. Bossen represents the flavor-diversification archetype, extending profiles beyond conventional fruit matrices into savory and botanical lines.
| Leading Market Players |
|---|
| Possmei International Co., Ltd. |
| Hangzhou Boduo Industrial Trade Co., Ltd. |
| Sunnysyrup Food Co., Ltd. |
| Boba Box Limited |
| Bossen |
| Nordic Boba ApS |
| Tachiz Group |
| BOBAVIDA |
| Fanale Drinks |
| Others |
Pricing and Supply Chain Analysis
Brown seaweed alginate spot indices from Southeast Asian coastal harvest zones cascade through three distinct pricing tiers, compressing margins for non-integrated processors while rewarding Possmei International's captive sourcing arrangements with cost pass-through advantages in European export corridors.
Pricing Analysis
Volume leadership in Fruit Flavor alginate spheres trades at commodity-thin margins, while Tea Flavor variants with tighter membrane specifications capture premium positioning in Seoul's specialty café channels. Price differentiation rests on REACH-compliant certification grades and direct-procurement contract scale, with smaller regional distributors facing intensifying cost compression from automated continuous-flow competitors. Food Manufacturers exhibit highest price sensitivity due to co-manufacturing agreement pressures, whereas Restaurants in Taipei and Seoul prioritize menu differentiation over unit cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised popping boba shipments concentrate rework costs on Southeast Asian cold-chain distributors, forcing write-downs that erode already-thin food service margins. Raw material harvesting anchors in Indonesian and Philippine coastal zones, with calcium chloride cross-linker inputs drawing from Chinese chemical processing clusters. Single-source vulnerability in brown seaweed supply exposes processors to climate-driven harvest interruptions. Distribution runs through refrigerated transport networks serving bubble tea chains, with Hangzhou Boduo's automated spherification capacity dominating contract manufacturing for European distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gellan-alginate hybrid membrane technology is displacing legacy alginate-only formulations, creating a transition window where backward integration into seaweed sourcing and certification investments separate viable competitors from stranded asset risk.
For Market Incumbents: Deploy captive brown seaweed sourcing to insulate alginate input costs from climate-driven supply interruptions while accelerating REACH-compliant clean-label certification investments to defend European retail placement against emerging gellan gum substitution threats in baking applications. For New Entrants and Emerging Players: Specialty café operators in secondary Taiwanese and South Korean urban clusters represent the most penetrable channel target, offering bilateral contract pathways that bypass established distributor relationships through rapid custom flavor profile development and localized botanical line extensions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale encapsulation specialists with existing automated continuous-flow capacity in China's Yangtze River Delta, where cold-chain capex intensity strains regional distributor balance sheets and creates acquisition windows ahead of EU F-Gas Regulation compliance deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Sourcing | Possmei International's captive alginate supply anchors cost advantages across Asian export corridors. |
| Clean-Label Certification Investment | EU organic and additive-free labeling schemes reward compliant shell reformulation with retail placement premiums. |
| Automated Continuous-Flow Capacity Expansion | Hangzhou Boduo's large-scale spherification systems dominate contract manufacturing for European distributor networks. |
| Direct-Procurement Channel Development | Bilateral contracts with Taipei and Seoul specialty cafés compress traditional wholesale distributor margins. |
| Gellan-Alginate Hybrid R&D Program | Thermo-reversible membrane technology unlocks oven-stable baking applications with higher per-unit margins. |
Research Methodology
Independent corroboration across encapsulation specialist executives, bubble tea chain procurement directors, and European distributor logistics managers underwrites the qualitative findings, with secondary validation drawing from EFSA guidance documents, FDA additive standards, MFDS calcium chloride filings, and customs trade data on alginate imports, combining bottom-up production capacity assessments with top-down consumption pattern triangulation.
Comparable historical reference periods anchored the forecast window to pre-pandemic baseline volumes and post-regulatory-shift demand trajectories, with segmentation modeling across flavor matrix, application thermal stability, distribution channel cold-chain intensity, and end-user technical capability dimensions, deriving growth trajectories from alginate input cost elasticity, clean-label certification penetration rates, and automation adoption curves in spherification processing.
Caveats apply where EU REACH threshold revisions, brown seaweed harvest disruptions from climate events, or gellan gum substitution acceleration in high-temperature confectionery could materially shift the outlook. Practitioners should monitor EFSA guidance updates, Southeast Asian coastal zone weather patterns, and baking application membrane technology adoption for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
North America Yerba Mate Market
Beverages
Indonesia Bottled Water Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Pineapple Juice Market
Beverages
Sparkling Juice Drinks Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Soft Serves Market
Beverages
Commercial Drink Mixers Market
Beverages
India Cafes & Bars Market
Beverages
Low Fat Drinks Market
Beverages
Carbonate Drink Maker Market
Beverages
Kvass Market
Beverages
Premium Bottled Water Market
Beverages
United States and Australia Coconut Water Market
Beverages
Global Beverage Emulsion Market