

Chill Block Market Size, Share, and Industry Trends Forecast 2026-2036
Chill Block Market Insights
Phase-change material formulation is tilting toward bio-derived and reusable chemistries that extend cycle life and reduce disposal costs. SGL Carbon leverages its graphite expertise to engineer high-thermal-conductivity substrates that accelerate heat absorption rates in medical-grade chill blocks. Mersen anchors European supply through vertically integrated carbon manufacturing and direct pharmaceutical distributor relationships. Castool Tooling Systems specializes in aluminum-extrusion-cooled inserts that bridge industrial process cooling with portable cold-chain applications.
Chill blocks are engineered thermal masses—typically water-based ice blocks, gel packs, or phase-change materials sealed in polymer shells—designed to absorb, store, and release thermal energy at controlled temperatures to maintain product integrity during transport or storage. Their primary industrial purpose centers on stabilizing temperature-sensitive cargo against ambient fluctuations without active refrigeration. Phase-change materials command premium positioning due to tighter temperature band control and longer duration stability than conventional ice blocks. Gel-based compositions sustain faster growth in laboratory cooling and medical storage as research institutions prioritize precise thermal regulation. Carbon dioxide-based dry ice occupies a mature niche where ultra-low temperatures justify higher handling complexity and ventilated infrastructure.
The FDA enforces pharmaceutical cold-chain validation standards that mandate documented thermal performance across distribution lanes, directly shaping product certification requirements for chill block suppliers. EPA regulations on refrigerant alternatives and carbon dioxide handling protocols constrain material choices and disposal pathways for single-use cooling media. ISO standards for temperature-controlled supply chains further harmonize performance testing methodologies across North American and European markets. Stakeholders must monitor evolving polymer sustainability mandates and bio-derived phase-change material scale-up economics to anticipate which material compositions will retain cost-competitive regulatory clearance.
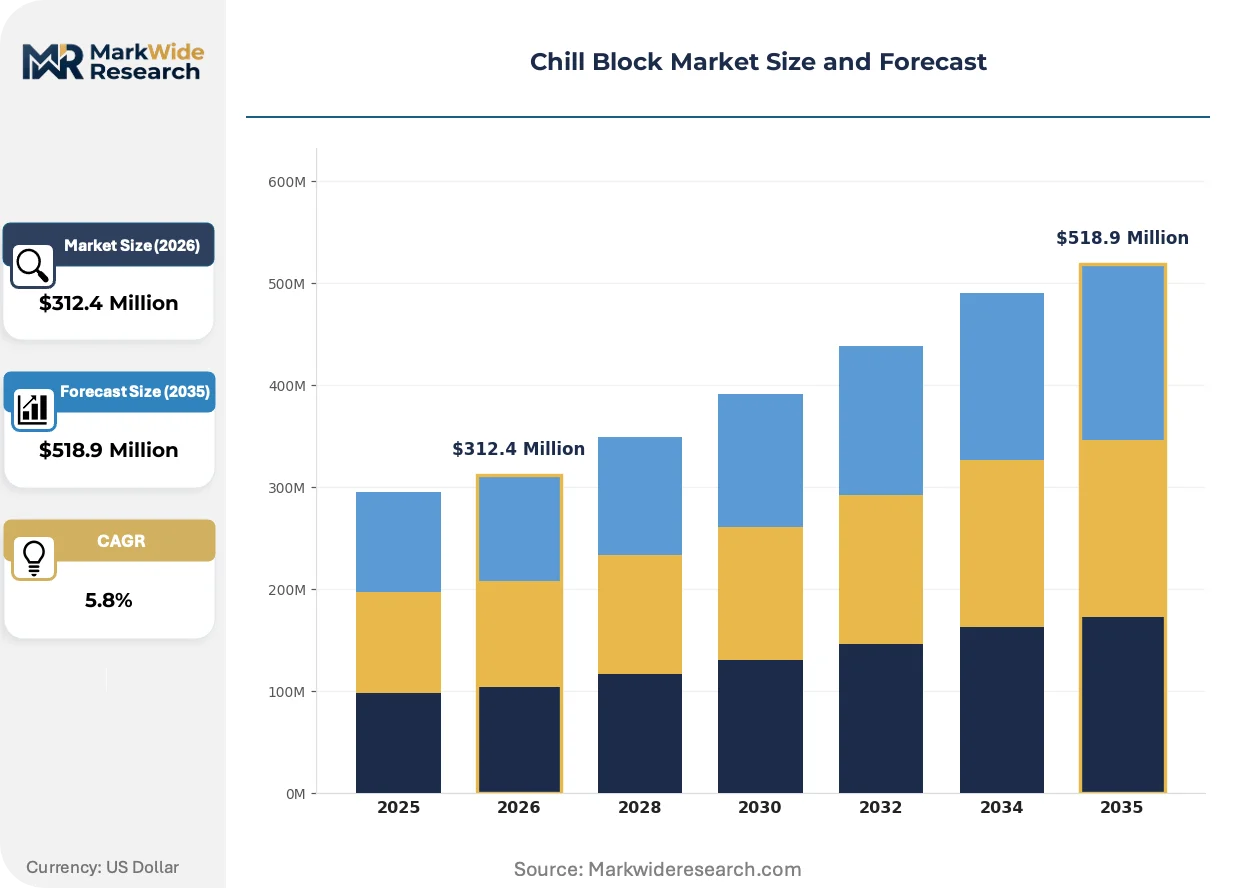
Market Dynamics
The FDA's tightened pharmaceutical cold-chain validation standards are compressing supplier certification timelines and forcing thermal packaging manufacturers to document performance across every distribution lane before market entry.
Growth Catalysts
- Temperature-sensitive biologics expansion:Pharmaceutical distributors are scaling cold-chain infrastructure to handle mRNA vaccines and cell therapies that demand precise thermal stability during transport.
- REACH compliance for sustainable chemistries:European manufacturers are accelerating bio-derived phase-change material development to meet ECHA restrictions on synthetic refrigerants and disposal protocols.
- German precision manufacturing clusters:Dense logistics networks around Stuttgart and Munich support rapid adoption of advanced thermal masses with integrated sensor validation.
Market Restraints
- Petroleum-derived polymer shell costs:Input price volatility for high-density polyethylene constrains margin flexibility for disposable gel pack producers.
- Carbon dioxide handling infrastructure:Ultra-low-temperature dry ice applications require ventilated transport fleets that concentrate supply capability with specialized logistics providers.
- ISO thermal performance testing harmonization delays:Divergent certification timelines across North American and European testing laboratories extend product launch cycles.
Strategic Opportunities
- Reusable phase-change material platforms:Closed-loop rental systems for medical-grade chill blocks reduce per-use costs for hospital networks and research institutions.
- India's cold-chain infrastructure gaps:Underpenetrated pharmaceutical distribution corridors present whitespace for modular thermal packaging with passive cooling duration extension.
- EU Green Deal circular economy mandates:Regulatory pressure for recyclable thermal masses creates first-mover advantage for bio-based formulation suppliers.
Industry Challenges
- Thermal engineer talent scarcity:Specialized expertise in phase-change material formulation and heat transfer modeling concentrates with senior researchers approaching retirement.
- Multi-lane validation documentation:FDA requirements for documented performance across ambient, refrigerated, and frozen distribution lanes demand extensive field testing capital.
- Legacy sensor integration complexity:New smart chill blocks with embedded temperature logging face interoperability friction with existing pharmaceutical inventory management systems.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chill Block Market Trends and Innovations
Material science breakthroughs and regulatory sustainability mandates are converging to transform how thermal energy storage solutions are formulated, validated, and deployed across temperature-controlled supply chains.
Graphite-impregnated polymer substrates are rendering obsolete conventional water-based ice blocks in medical transport applications. Hospital procurement teams and specialty pharmaceutical distributors are specifying these high-thermal-conductivity materials for biologics shipments exceeding 72 hours. The technology is rendering obsolete legacy gel packs that cannot maintain sub-8°C stability across extended ambient exposure windows.
EPA refrigerant alternative regulations under the AIM Act are constraining hydrofluorocarbon content in disposable cooling media. Industrial consequence includes accelerated reformulation timelines for synthetic phase-change materials toward bio-derived paraffin and fatty acid ester chemistries. Medical-grade chill block suppliers serving US pharmaceutical distributors are responding with dual-track certification pipelines to maintain supply continuity.
Direct distributor relationships are displacing traditional thermal packaging intermediaries in European pharmaceutical cold chains. Large hospital networks and contract research organizations now specify performance-based contracts with chill block manufacturers rather than logistics aggregators. This pattern is most visible in Germany where precision manufacturing clusters enable rapid custom formulation turnaround for clinical trial material shipments.
Chill Block Market Segmentation
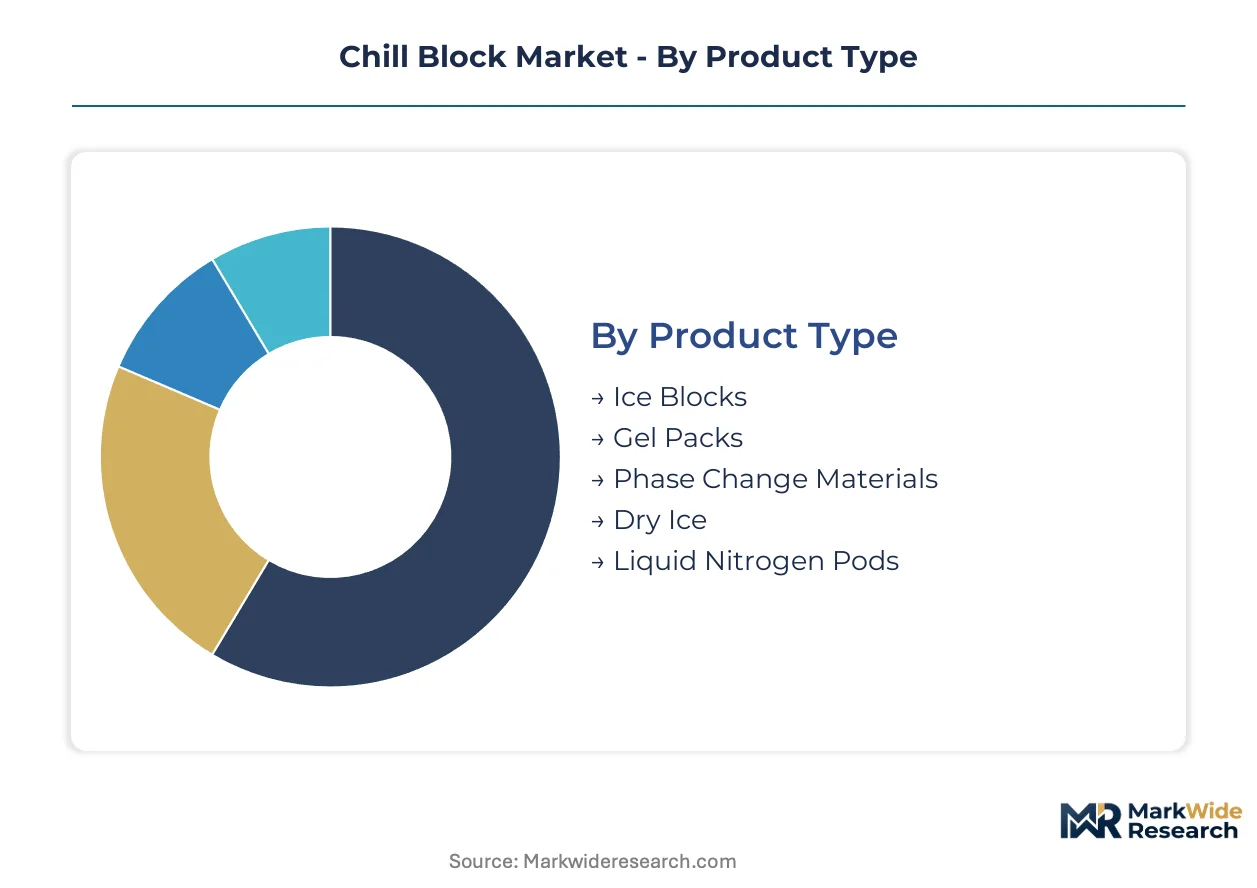
Chill block procurement patterns diverge sharply across thermal performance requirements, regulatory exposure, and operational scale. Understanding how product specifications map to end-use constraints enables suppliers to align formulation investments with margin-accretive demand pockets.
Product Type:
Cost tier structures the competitive landscape, with premium phase-change materials commanding sustained price premiums against commodity alternatives.
- Ice Blocks:Simple water-based thermal masses sealed in polyethylene shells serve short-duration food preservation and event cooling. Procurement concentrates with catering services and retail outlets where cost minimization outweighs precision requirements.
- Gel Packs:Polymer-thickened aqueous solutions deliver moderate duration stability for laboratory cooling and medical storage. Research institutions in Germany specify these for specimen transport requiring 24-48 hour thermal protection without active refrigeration infrastructure.
- Phase Change Materials:Engineered paraffin and fatty acid ester formulations maintain tighter temperature bands across extended ambient exposure. Pharmaceutical distributors specify bio-derived variants to satisfy REACH compliance and EU Green Deal circular economy mandates.
- Dry Ice:Solid carbon dioxide achieves ultra-low temperatures for specialized biologics transport. Handling complexity and ventilated infrastructure requirements concentrate supply capability with specialized logistics providers serving cell therapy manufacturers.
- Liquid Nitrogen Pods:Cryogenic thermal masses address extreme temperature requirements in advanced medical storage. Deployment remains limited to research institutions with established cryogenic handling protocols and safety infrastructure.
Ice blocks command the established base. The steepest expansion runs through phase change materials.
Application:
End-use thermal specifications determine formulation complexity, with pharmaceutical cold chain transportation imposing the most stringent validation requirements.
- Cold Chain Transportation:Multi-lane distribution of temperature-sensitive biologics demands documented thermal performance across ambient, refrigerated, and frozen lanes. FDA validation standards compress supplier certification timelines and favor phase-change materials with embedded sensor integration.
- Laboratory Cooling:Precise thermal regulation for specimen and reagent storage drives specification of gel-based and polymer-based formulations. Research institutions prioritize reusable platforms to reduce per-use disposal costs and regulatory documentation burden.
- Medical Storage:Hospital networks and pharmaceutical distributors require extended-duration stability for vaccine and cell therapy inventory. German precision manufacturing clusters enable rapid custom formulation turnaround for clinical trial material shipments.
- Food Preservation:Commodity ice blocks and gel packs serve short-haul agricultural and seafood distribution. Cost sensitivity limits adoption of advanced phase-change materials outside premium organic and specialty food segments.
- Event Cooling:Temporary temperature control for catering and outdoor hospitality relies on disposable ice blocks and gel packs. Seasonal demand concentration creates working capital challenges for suppliers without diversified end-use exposure.
Cold chain transportation anchors revenue concentration. Laboratory cooling is expanding most quickly as research institutions scale biologics handling capacity.
Material Composition:
Regulatory pressure on synthetic chemistries is accelerating migration toward bio-derived formulations with favorable disposal pathways.
- Water-Based:Lowest-cost thermal mass composition dominates commodity food preservation and event cooling applications. Margins compress with petroleum-derived polyethylene shell cost volatility.
- Gel-Based:Polymer-thickened formulations balance cost and performance for laboratory and medical storage segments. ECHA restrictions on synthetic refrigerants are forcing reformulation toward bio-derived thickeners.
- Polymer-Based:Encapsulated phase-change materials enable precise temperature band control. Graphite-impregnated substrates from SGL Carbon and Mersen serve medical-grade applications exceeding 72-hour stability requirements.
- Liquid-Based:Pumped thermal storage systems bridge industrial process cooling with portable cold-chain applications. Castool Tooling Systems specializes in aluminum-extrusion-cooled inserts for this hybrid segment.
- Carbon Dioxide-Based:Dry ice and liquid carbon dioxide pods serve ultra-low-temperature requirements. EPA AIM Act constraints on hydrofluorocarbon alternatives are sustaining demand despite handling complexity.
Water-based formulations retain volume leadership. Polymer-based compositions are gaining share fastest on pharmaceutical distributor specification.
End User:
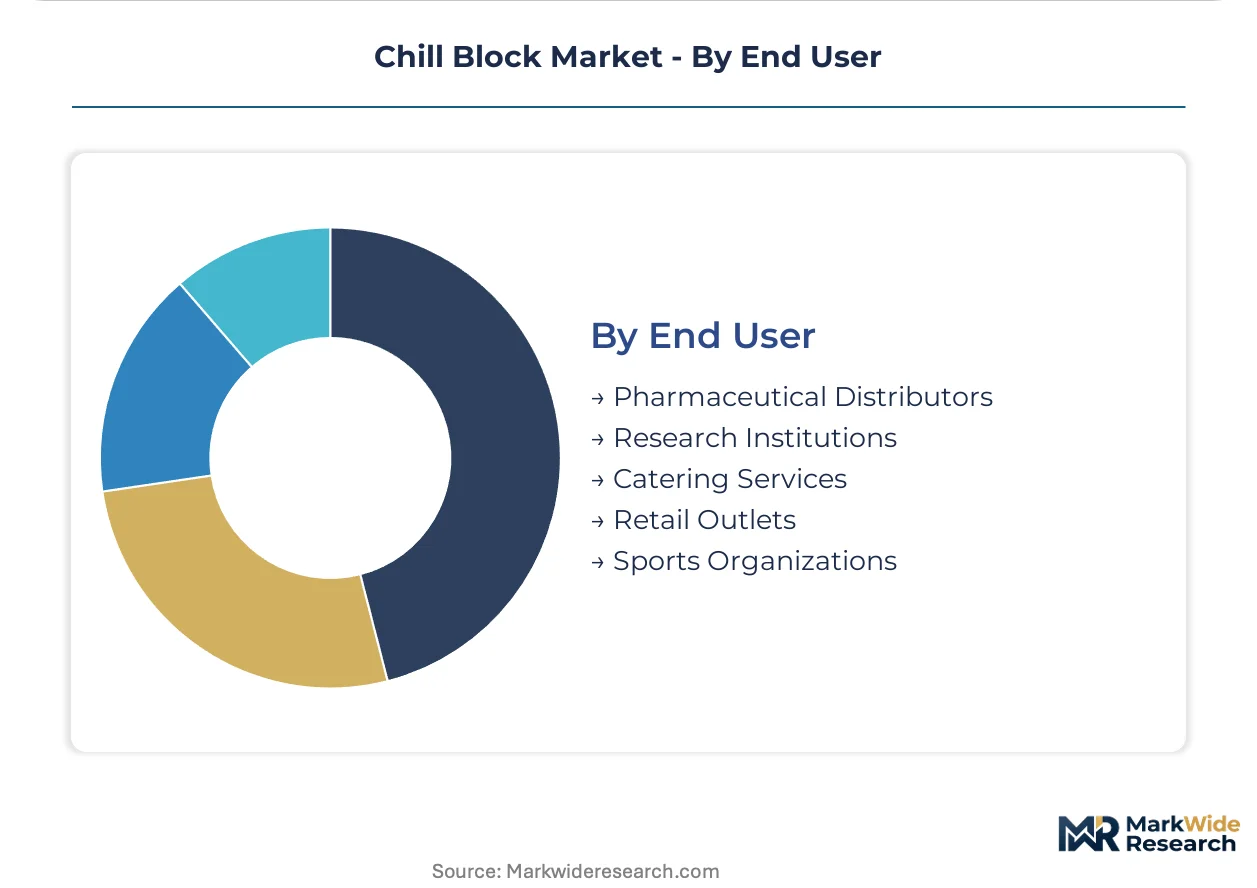
Customer procurement sophistication varies dramatically, with pharmaceutical distributors demanding outcome-based performance contracts and research institutions prioritizing total cost of ownership.
- Pharmaceutical Distributors:Large hospital networks and contract research organizations now specify direct manufacturer relationships with performance-based thermal validation guarantees. FDA multi-lane documentation requirements favor suppliers with established certification pipelines.
- Research Institutions:Academic and government laboratories prioritize precise thermal regulation and reusable platform economics. Procurement teams specify closed-loop rental systems to reduce per-use costs and disposal compliance burden.
- Catering Services:Event and hospitality operators prioritize lowest-unit-cost disposable solutions. Seasonal demand concentration and price sensitivity limit supplier margin capture.
- Retail Outlets:Grocery and specialty food retailers deploy commodity ice blocks and gel packs for short-haul distribution. Sustainability mandates from corporate procurement are gradually shifting specification toward recyclable thermal masses.
- Sports Organizations:Athletic training and outdoor event operations require portable cooling for injury treatment and hydration. Fragmented procurement limits supplier scale economies.
Pharmaceutical distributors command the premium tier. Research institutions represent the steepest expansion trajectory as biologics research funding accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturers export advanced phase-change materials to pharmaceutical distributors across North America and Asia-Pacific, establishing the Rhine-Main corridor as the dominant trade-flow hub for medical-grade thermal packaging.
Germany
Stuttgart and Munich manufacturing clusters supply graphite-impregnated substrates to European pharmaceutical networks. ECHA REACH restrictions on synthetic refrigerants accelerate bio-derived formulation development among Baden-Württemberg chemical specialists. Bavarian precision engineering firms integrate sensor validation into custom chill block designs for clinical trial shipments.
United States
FDA multi-lane validation requirements compress supplier certification timelines for temperature-sensitive biologics distribution. EPA AIM Act constraints on hydrofluorocarbon alternatives force reformulation toward sustainable chemistries. Boston and San Francisco biotech corridors specify direct manufacturer relationships with performance-based thermal guarantees.
China
NMPA pharmaceutical cold-chain standards tighten documentation requirements for imported thermal packaging. Dual carbon goals under MEE oversight accelerate domestic bio-derived phase-change material production. Yangtze River Delta chemical parks scale paraffin and fatty acid ester manufacturing for regional vaccine distribution.
India
CDSCO pharmaceutical distribution regulations mandate validated thermal protection for temperature-sensitive drug shipments. PLI scheme incentives attract cold-chain infrastructure investment into underpenetrated corridors. Maharashtra and Gujarat pharmaceutical clusters drive specification of modular passive cooling systems with extended duration.
Japan
PMDA biologics handling guidelines enforce precise thermal stability documentation across distribution lanes. METI circular economy mandates favor reusable phase-change material platforms in hospital procurement. Osaka-Kobe manufacturing belt supplies advanced polymer substrates for regional cell therapy logistics.
Chill Block Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers: integrated carbon material specialists, precision thermal engineering firms, and regional packaging fabricators. Consolidation pressure concentrates among graphite substrate and phase-change material formulators with direct pharmaceutical distributor relationships. Strategic archetypes include backward-integrated carbon manufacturers, aluminum-extrusion cooling specialists, and chemical formulation licensors. Dominant competitive moves span capacity expansion in bio-derived material production and technology licensing agreements for sensor-integrated thermal masses.
Among carbon-based substrate specialists, SGL Carbon, Mersen, and Nippon Carbon occupy positions within the premium material tier. SGL Carbon represents the vertically integrated archetype leveraging graphite expertise for high-thermal-conductivity medical-grade applications. Mersen anchors European supply through captive manufacturing and established pharmaceutical channel relationships. Nippon Carbon exemplifies the Asia-Pacific specialist model serving regional biologics distribution networks. Castool Tooling Systems sits within the aluminum-extrusion cooling segment bridging industrial process and portable cold-chain applications. Morgan Advanced Materials and GrafTech International represent diversified advanced materials conglomerates with thermal management portfolio exposure. Kyocera occupies a ceramic substrate position adjacent to core chill block formulations. ASK Chemicals and Inductotherm Group represent industrial equipment and chemical supply channels with thermal mass adjacencies.
| Leading Market Players |
|---|
| SGL Carbon |
| Morgan Advanced Materials |
| Mersen |
| Nippon Carbon |
| GrafTech International |
| Kyocera |
| Castool Tooling Systems |
| ASK Chemicals |
| Inductotherm Group |
| Others |
Pricing and Supply Chain Analysis
German graphite substrate manufacturers concentrate upstream supply capability, anchoring margin capture with pharmaceutical distributors downstream while compressing pricing flexibility for commodity gel pack fabricators. REACH compliance costs and bio-derived formulation premiums widen the spread between certified medical-grade chill blocks and disposable food-service alternatives.
Pricing Analysis
Next-generation graphite-impregnated polymer substrates command substantial premiums against conventional water-based ice blocks and mid-tier gel formulations. Three-tier pricing structure across premium, standard, and economy levels segments procurement: pharmaceutical distributors absorb premium pricing for FDA-validated phase-change materials with embedded sensors, research institutions negotiate mid-tier contracts for reusable laboratory platforms, and catering services drive economy-tier commoditization. Pricing pressure stems from petroleum-derived polyethylene shell cost volatility squeezing disposable gel pack margins. Food preservation and event cooling segments exhibit highest price sensitivity, while cell therapy logistics buyers prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from large hospital networks and pharmaceutical distributors strain working capital for mid-tier formulation specialists without captive raw material supply. Manufacturing concentrates in Germany, China, and the United States, with Baden-Württemberg chemical parks supplying bio-derived paraffin formulations, Yangtze River Delta facilities scaling fatty acid ester production, and Boston-area biotech corridors demanding rapid custom turnaround. Supply chains draw from graphite mining operations, petroleum-derived polymer feedstocks, and specialty refrigerant chemistries. Single-source vulnerability concentrates in German precision manufacturing clusters serving European pharmaceutical networks. Distribution runs through direct manufacturer relationships displacing traditional thermal packaging intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA multi-lane validation mandates and EPA AIM Act refrigerant constraints constitute a dual regulatory inflection accelerating market disruption. Technological substitution toward bio-derived phase-change materials with integrated sensor validation separates growth trajectories across supplier tiers.
For Market Incumbents: Insulate certification pipelines against emerging bio-based formulation specialists by accelerating backward integration into graphite substrate production and locking long-term supply agreements with Baden-Württemberg chemical specialists. Defensive priority centers on capturing reusable platform rental economics before hospital procurement committees consolidate vendor relationships. Threat vectors include sensor-integrated challengers and ECHA disposal protocol tightening.
For New Entrants and Emerging Players: Build out modular passive cooling systems targeting India's underpenetrated pharmaceutical distribution corridors where CDSCO regulations mandate validated thermal protection but domestic supply capability lags demand. White-space concentration sits with extended-duration gel formulations for Maharashtra and Gujarat clinical trial shipments. Go-to-market leverage partners established logistics providers for field validation documentation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thermal packaging roll-ups consolidating regional gel pack fabricators without pharmaceutical certification depth. Long-term viability favors suppliers with demonstrated FDA multi-lane validation and direct hospital network contracts over commodity food-service exposure. Acquisition target archetype: mid-cap phase-change material formulators with REACH-compliant bio-derived pipelines and German manufacturing footprint. Signal to monitor: CDSCO enforcement intensity accelerating import substitution in Indian pharmaceutical cold chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Derived Formulation Scale-Up | ECHA REACH restrictions on synthetic refrigerants force accelerated paraffin and fatty acid ester chemistry investment. |
| Sensor-Integrated Thermal Mass Development | FDA multi-lane validation requirements favor chill blocks with embedded temperature logging for biologics distribution. |
| Direct Distributor Relationship Establishment | Large hospital networks now specify performance-based contracts bypassing traditional thermal packaging intermediaries. |
| Reusable Platform Rental System Launch | Closed-loop economics reduce per-use costs for research institutions prioritizing total cost of ownership. |
| Indian Market Modular System Deployment | CDSCO mandates and PLI scheme incentives create whitespace for extended-duration passive cooling in underpenetrated corridors. |
Research Methodology
A standing panel of pharmaceutical cold-chain logistics directors, thermal packaging procurement managers, phase-change material formulation chemists, and FDA regulatory affairs consultants provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with hospital supply chain executives and contract research organization shipping coordinators with secondary validation through ECHA substance restriction databases, FDA guidance document repositories, and ISO temperature-controlled supply chain standards. Customs trade data from German chemical export statistics and US pharmaceutical thermal packaging import records anchored supply-side triangulation. Bottom-up demand modeling across end-use segments was cross-referenced against top-down market sizing from industry association aggregates.
Scenario-bracketing framed analytical outputs across conservative, baseline, and expansion pathways throughout the forecast period. Segmentation dimensions modeled encompassed product type tier, application thermal specification, material composition regulatory cluster, and end-user procurement sophistication. CAGRs were derived from elasticity-adjusted demand projections and supply capacity buildout timelines. Industry-specific forecast inputs incorporated ECHA REACH compliance cost trajectories and NMPA pharmaceutical cold-chain standard implementation intensity.
Stress conditions across petroleum feedstock price volatility, German manufacturing cluster disruption, and FDA validation timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and bio-derived material scale-up economics. Macroeconomic contraction, accelerated ECHA disposal protocol tightening, or breakthrough solid-state thermal storage technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.