
 Japan Kombucha Market | 2026-2036
Japan Kombucha Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Kombucha Market Outlook
Multi-source sourcing of tea bases and probiotic cultures is rebalancing toward domestic Japanese suppliers as freight volatility persists. GT's Living Foods anchors its presence through premium positioning in Tokyo health stores. Culture and Leaf leverages local ingredient partnerships to differentiate on provenance claims. Kombucha Ship competes through direct-to-consumer subscription models that bypass conventional retail markups.
Kombucha denotes a fermented tea beverage produced through symbiotic culture of bacteria and yeast (SCOBY) action on sweetened tea, yielding organic acids, trace ethanol, and carbonation with live culture counts typically exceeding 10^6 CFU per milliliter. Organic and Functional product types command margin premiums as Japanese consumers prioritize clean-label positioning and gut-health substantiation. Health Stores and Online Retail distribution channels outpace Supermarkets in velocity for premium-priced formats, while Bottles retain dominant packaging share despite Can growth in convenience-channel placements.
PMDA oversight of functional food claims and FSSCI-aligned import standards constrain formulation and labeling choices for kombucha marketed with health benefits. METI's sustainability disclosure requirements and JIS packaging standards add compliance layers that favor established operators with technical documentation capacity. Stakeholders must monitor evolving probiotic health claim thresholds and channel-specific registration pathways to secure shelf access.
Market Dynamics
METI's functional food labeling standards are compressing formulation choices and concentrating shelf access among operators with technical documentation capacity, rebalancing competitive position toward established domestic suppliers.
Growth Catalysts
- PMDA functional claim pathways:Clarified probiotic health claim thresholds enable substantiated gut-health positioning that commands retail premium placement.
- Tokyo-Osaka metropolitan corridor density:Health-conscious urban consumer concentration sustains velocity for premium-priced formats in dedicated channels.
- Domestic tea base sourcing:Freight volatility acceleration is rebalancing supply chains toward Kyushu and Shizuoka growers, reducing landed cost variability.
Market Restraints
- FSSCI-aligned import standards:Stringent culture strain documentation requirements create friction for foreign probiotic suppliers seeking Japanese market entry.
- Glass bottle supply concentration:Packaging input dependence on limited domestic glassworks exposes margin compression during energy price spikes.
- Ethanol content thresholds:Trace fermentation alcohol levels trigger beverage tax reclassification risks that constrain SCOBY fermentation protocols.
Strategic Opportunities
- Hokkaido and Tohoku underpenetration:Regional health store network gaps outside Pacific coastal corridors offer first-mover subscription capture potential.
- METI sustainability disclosure alignment:Early carbon footprint certification unlocks preferential placement in government procurement channels and corporate wellness programs.
- Direct-to-consumer fermentation kits:Home-brew equipment convergence with digital coaching platforms bypasses retail markup structures entirely.
Industry Challenges
- SCOBY culture banking expertise:Qualified fermentation microbiologists command scarcity premiums that strain mid-scale operator R&D budgets.
- JIS packaging standard recertification:Revised container integrity testing timelines delay seasonal product launches by 8-14 weeks.
- Legacy supermarket slotting fee structures:Conventional retail access requires upfront trade spend that erodes direct-to-consumer unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Kombucha Market |
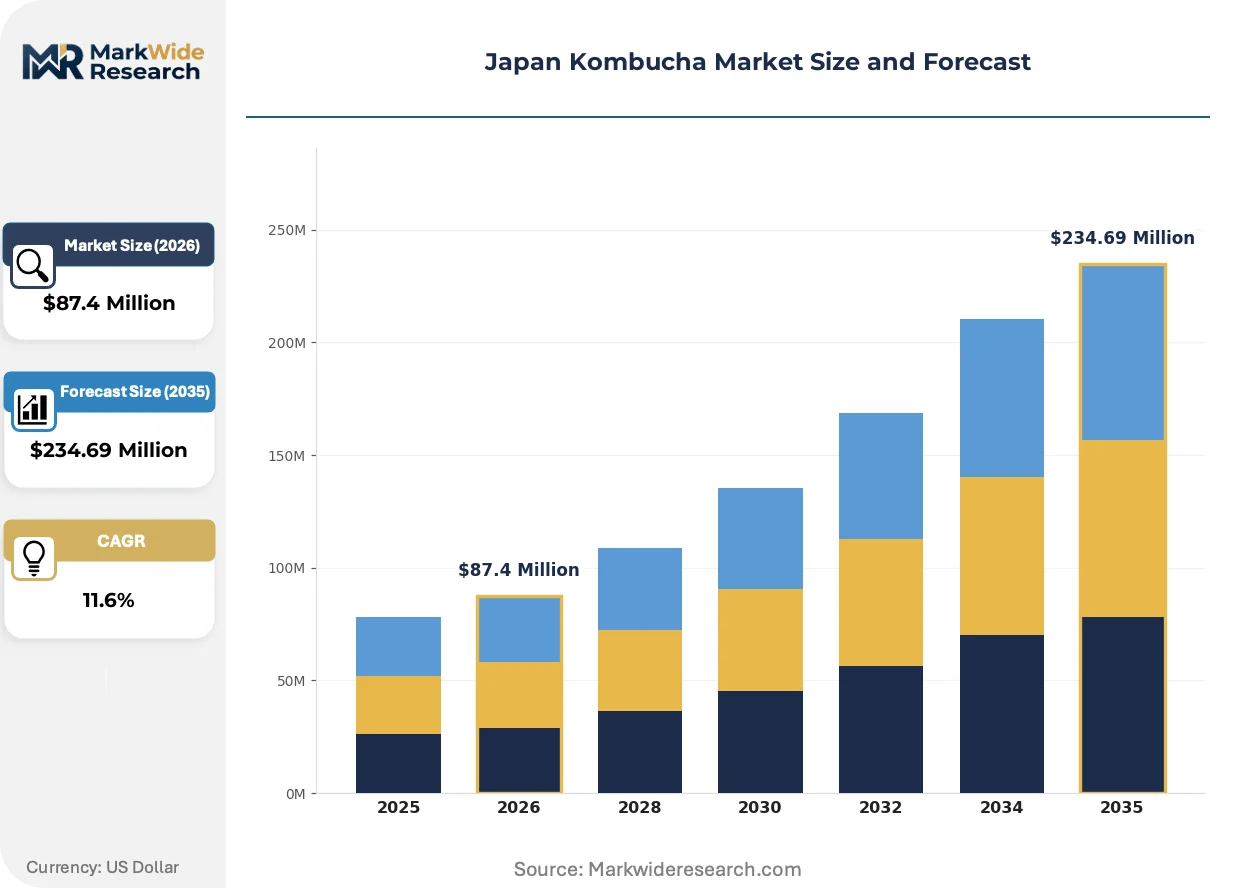
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Flavored, Unflavored, Functional Distribution Channel: Supermarkets, Health Stores, Online Retail, Cafes End User: Health-Conscious Consumers, Millennials, Organic Food Enthusiasts, Fitness Aficionados Packaging Type: Bottles, Cans, Kegs, Pouches |
| Companies Covered | The Hain Celestial Group, Culture and Leaf, Kombucha Ship, Remedy Drinks, Wow Kombucha, GT's Living Foods, KeVita, Inc., Red Bull GMBH, Buchi Kombucha, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Kombucha Market Strategic Shifts
Live culture stabilization and packaging format diversification are compressing traditional channel boundaries, while regulatory clarity on functional claims is enabling new positioning strategies that reward technical investment.
Flash-pasteurization alternatives using high-pressure processing are overtaking thermal treatment as the dominant live-culture preservation method. Premium health store buyers and direct-to-consumer operators are adopting cold-chain HPP lines at accelerating capital deployment rates. This technology is overtaking conventional bottling infrastructure by enabling extended shelf stability without colony-forming unit degradation, compressing the advantage gap between national distribution and regional craft producers.
PMDA's evolving probiotic substantiation guidelines are tightening documentation requirements for gut-health claims on fermented beverages. Manufacturers must now submit strain-specific clinical evidence packages that extend new product development cycles by 12-18 months. Functional-positioned kombucha lines targeting Tokyo metropolitan health stores are responding with preemptive third-party culture authentication investments to secure shelf access ahead of enforcement phase-in.
Subscription-based replenishment models are displacing conventional supermarket trial purchases among core urban demographics. Direct-to-consumer platforms bypass retail markups while capturing consumption-pattern data that enables flavor rotation personalization. This channel shift concentrates revenue visibility in Kanto and Kansai corridors where delivery density supports unit-economic viability.
Japan Kombucha Market Segmentation
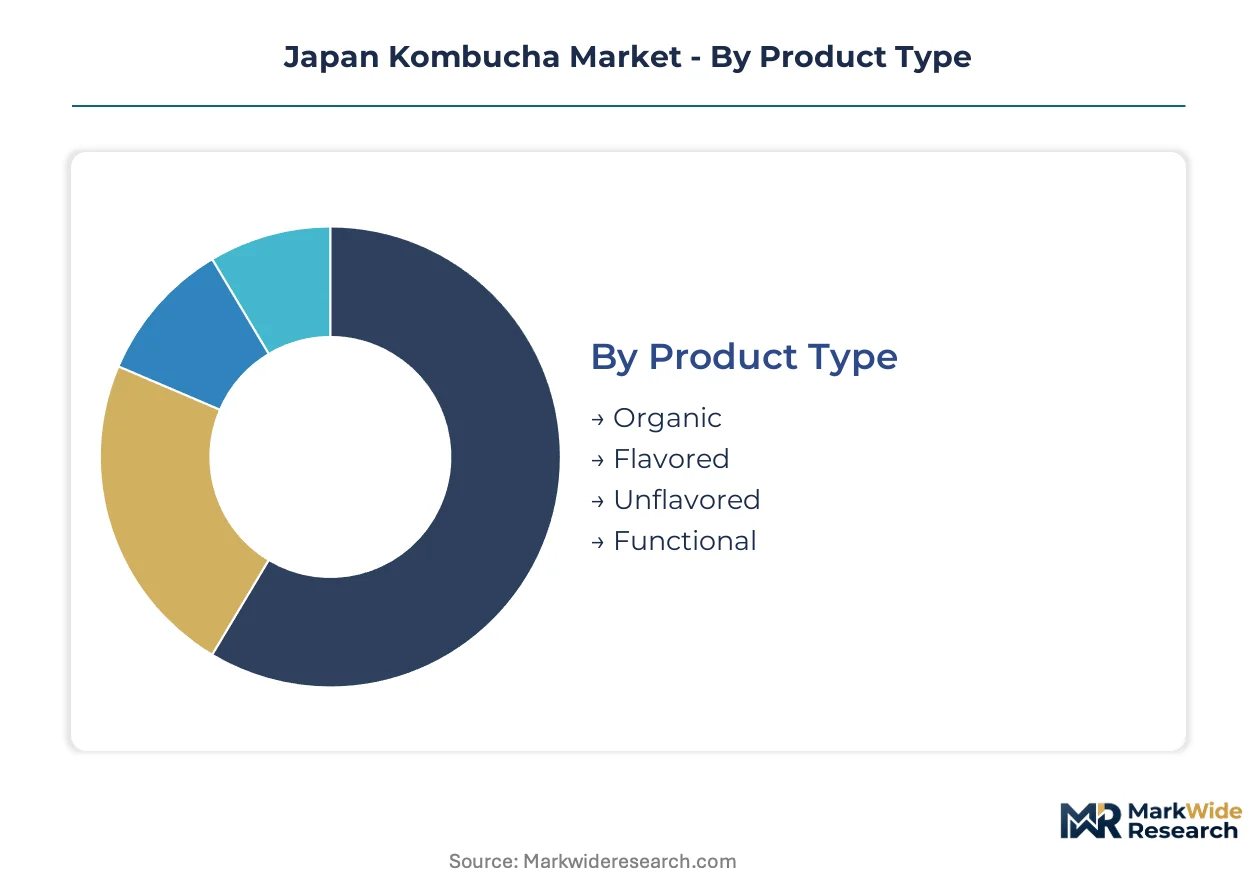
Japanese kombucha purchasing patterns fragment across four distinct dimensions that shape formulation priorities, channel economics, and margin capture. Product type and packaging format decisions determine PMDA compliance pathways and shelf positioning, while distribution channel selection governs customer acquisition cost structures in Tokyo-Osaka corridors versus regional expansion.
Product Type:
Premium positioning hinges on certification depth and functional claim substantiation rather than flavor novelty alone.
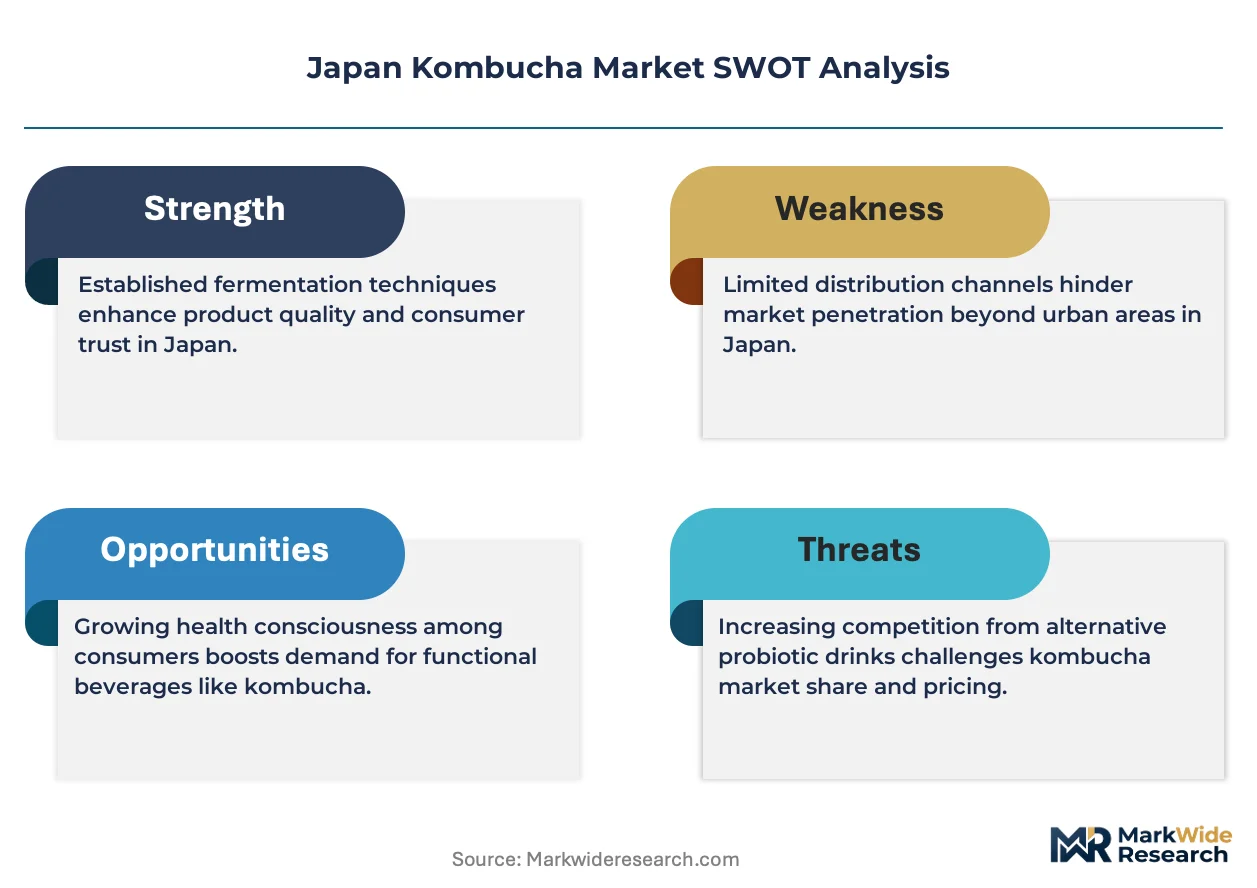
- Organic:JAS-certified tea bases and SCOBY cultures command 20-40% shelf price premiums in Tokyo health stores. Kyushu and Shizuoka domestic sourcing reduces freight exposure while satisfying METI sustainability disclosure requirements for corporate wellness procurement channels.
- Functional:Strain-specific gut-health positioning requires PMDA-compliant clinical documentation extending development cycles. Demand concentrates among fitness aficionados seeking post-workout microbiome recovery solutions with verified colony-forming unit counts.
- Flavored:Yuzu, matcha, and seasonal fruit infusions target millennial trial purchases through limited-rotation releases.
- Unflavored:Traditional fermented tea profiles appeal to organic food enthusiasts prioritizing ingredient transparency over palate complexity.
Volume sits with Organic; growth tilts toward Functional.
Distribution Channel:
Channel selection determines margin retention, customer data capture, and regulatory exposure simultaneously.
- Health Stores:Dedicated gut-health merchandising and trained staff consultation justify 35-50% price premiums over supermarket equivalents. Tokyo and Osaka metropolitan density supports cold-chain logistics with minimal spoilage loss.
- Online Retail:Subscription replenishment models bypass conventional slotting fees while capturing consumption-pattern data for flavor personalization algorithms. Direct-to-consumer economics favor Kanto and Kansai delivery corridors where route density minimizes per-unit fulfillment costs.
- Supermarkets:Legacy trade spend structures and standardized shelving constrain premium positioning for substantiated functional claims.
- Cafes:On-premise fermentation and draft dispensing create experiential differentiation with limited scale economics.
Transaction volume concentrates in Health Stores; subscriber lifetime value expansion favors Online Retail.
End User:
Demographic targeting must reconcile willingness-to-pay gradients with channel accessibility patterns.
- Health-Conscious Consumers:Urban prefecture density drives repeat purchase velocity for premium-priced formats with clean-label positioning and domestic provenance verification.
- Millennials:Digital-native purchasing habits favor subscription platforms and social media discovery over conventional retail trial.
- Organic Food Enthusiasts:JAS certification and ingredient traceability requirements filter purchasing toward established domestic suppliers with technical documentation capacity.
- Fitness Aficionados:Post-exercise microbiome recovery positioning commands functional premium placement in gym-adjacent health stores and direct-to-consumer channels.
Health-Conscious Consumers anchor current volume; Fitness Aficionados show steepest expansion trajectory.
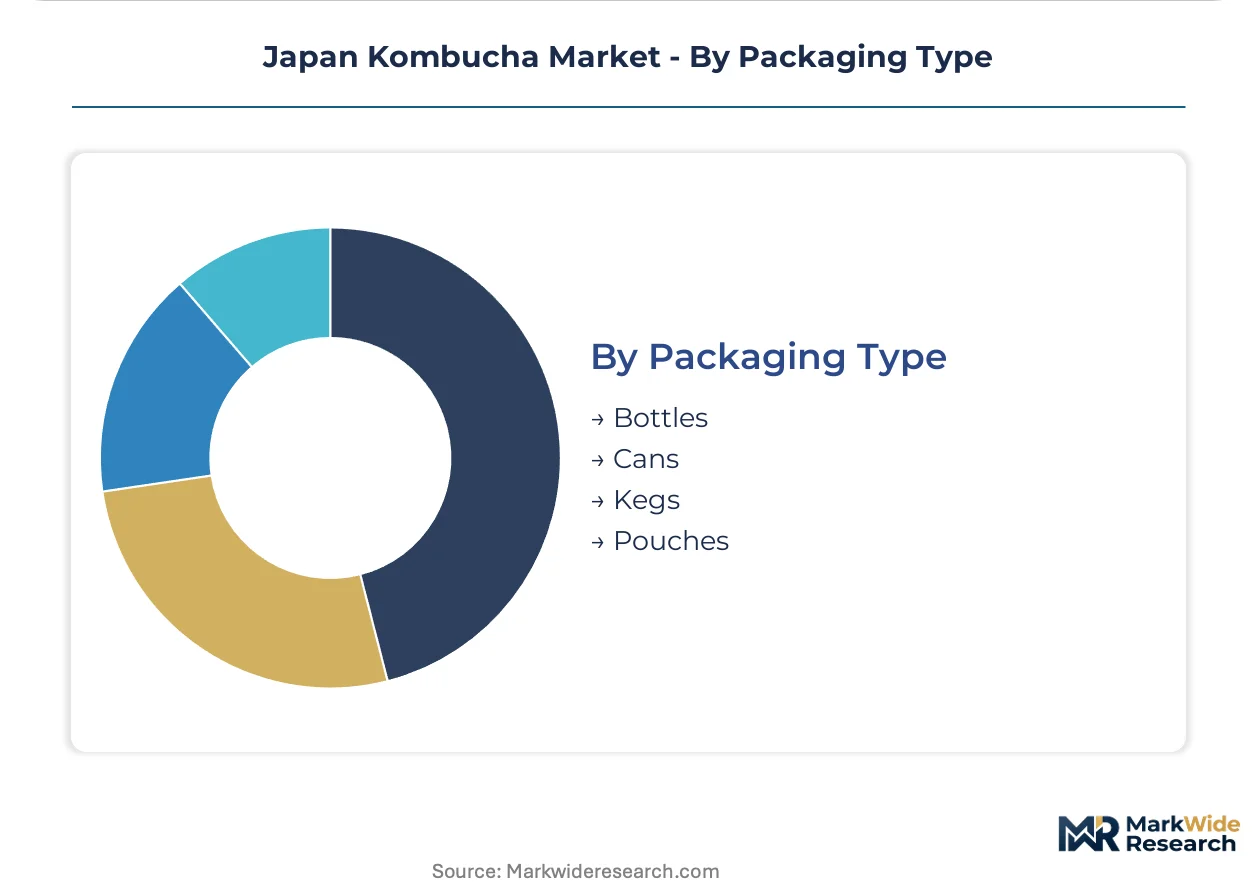
Packaging Type:
Container selection governs shelf stability, carbonation retention, and JIS compliance cost structures.
- Bottles:Glass and PET formats retain dominant market share despite energy-price volatility affecting domestic glassworks. JIS container integrity recertification timelines delay seasonal launches by 8-14 weeks, favoring established operators with regulatory documentation systems.
- Cans:Aluminum format growth accelerates in convenience-channel placements where portability and chill-speed matter. High-pressure processing compatibility enables extended shelf stability without thermal pasteurization.
- Kegs:On-premise draft dispensing serves cafe and hospitality segments with limited retail scalability.
- Pouches:Flexible format trials target outdoor and travel occasions with reduced shipping weight economics.
Installed base concentrates in Bottles; Can adoption climbs fastest in convenience-channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shizuoka tea plantations and Kyushu organic farms anchor domestic ingredient sourcing for Japan's kombucha producers. METI's regional revitalization grants channel technical documentation support toward prefectural fermentation startups. Freight volatility accelerates backward integration into domestic supply bases.
Kanto/Tokyo
Health-conscious urban density in Shibuya and Shinjuku wards sustains premium velocity for functional-positioned formats. PMDA's probiotic claim substantiation requirements concentrate technical compliance capacity in Tokyo's Minato-ku consulting clusters. Cold-chain logistics providers cluster around the Port of Tokyo to serve health store networks across the metropolitan corridor.
Kansai/Osaka
Osaka's merchant culture supports experiential cafe fermentation concepts with limited retail scale. METI's Kansai Bureau of Economy, Trade and Industry coordinates functional food labeling workshops for regional producers. Umeda and Namba health store districts command parallel premium placement to Tokyo equivalents.
Kyushu
Organic tea base cultivation in Kagoshima and Miyazaki prefectures reduces landed cost variability for domestic kombucha brands. The Ministry of Agriculture, Forestry and Fisheries' organic certification subsidies lower JAS compliance barriers for small-scale growers. Fukuoka's logistics hub status enables efficient distribution to Kansai and Kanto markets.
Chubu/Nagoya
Nagoya's manufacturing heritage supports packaging equipment suppliers serving kombucha bottling operations. Aichi Prefecture's industrial cluster hosts JIS container integrity testing laboratories that accelerate seasonal product certification timelines. Health store penetration lags coastal corridors, creating subscription-model capture opportunities.
Hokkaido
Underpenetrated health store networks in Sapporo and regional cities offer first-mover subscription potential. METI's Hokkaido Bureau promotes sustainable agriculture initiatives that align with corporate wellness procurement channels. Cold-climate logistics costs constrain conventional retail distribution economics.
Japan Kombucha Market Competitive Environment
Strategic partnerships dominate the current landscape as operators secure domestic ingredient supply and technical documentation capacity. The vendor base clusters into three tiers: multinational beverage conglomerates with functional food portfolios, domestic craft specialists leveraging regional provenance claims, and direct-to-consumer subscription platforms bypassing retail markups. Archetypes include premium health store anchors, local ingredient storytellers, and digital-native replenishment services. Competitive moves concentrate on backward integration into tea base sourcing and preemptive PMDA compliance investments.
Within the domestic craft tier, Culture and Leaf exemplifies regional provenance positioning through Kyushu and Shizuoka grower partnerships. Kombucha Ship occupies the direct-to-consumer archetype with subscription models that capture consumption-pattern data for flavor personalization. GT's Living Foods anchors the premium import segment in Tokyo health store channels. These three operators represent distinct strategic vectors: local supply chain control, digital channel economics, and established premium retail access.
| Leading Market Players |
|---|
| The Hain Celestial Group |
| Culture and Leaf |
| Kombucha Ship |
| Remedy Drinks |
| Wow Kombucha |
| GT's Living Foods |
| KeVita, Inc. |
| Red Bull GMBH |
| Buchi Kombucha |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fermentation specialists anchor supply-side discipline across Kyushu and Shizuoka prefectures, translating backward integration into tea base sourcing into sustained margin retention against freight-volatile import competitors. Their ownership concentration enables pricing power through JAS-certified provenance claims that command shelf premiums in Tokyo health stores.
Pricing Analysis
Warranty-equivalent service bundling separates premium functional-positioned lines from unbundled trial formats in Japanese kombucha retail. Three-tier pricing structure across premium, standard, and economy levels stratifies by PMDA claim substantiation depth and JAS certification tier. Pricing pressure stems from glass bottle energy cost volatility squeezing mid-tier operators. Health-conscious urban consumers show lowest price sensitivity; supermarket trial purchasers exhibit highest elasticity.
Supply Chain Analysis
Qualified fermentation microbiologists concentrate in Tokyo's Minato-ku consulting clusters and Fukuoka's emerging technical hubs, constraining SCOBY culture banking capacity for regional entrants. Domestic tea base sourcing draws from Kagoshima and Shizuoka growers while probiotic cultures rely on domestic strain banks and limited FSSCI-aligned imports. Single-source vulnerability sits with concentrated domestic glassworks for premium bottle formats. Distribution runs through cold-chain logistics clusters at the Port of Tokyo serving health store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's kombucha sector sits in a preservation-technology transition, with high-pressure processing displacing thermal pasteurization as the dominant live-culture stabilization method across premium health store and direct-to-consumer channels.
For Market Incumbents: To counter subscription-platform customer data capture, incumbents must preemptively invest in PMDA-compliant strain authentication documentation and secure preferential shelf placement through METI sustainability disclosure alignment. Channel control through health store exclusivity agreements represents the critical defensive lever against digital-native entrants. For New Entrants and Emerging Players: Technology-first subscription algorithms enabling flavor rotation personalization offer the most penetrable wedge into Hokkaido and Tohoku underpenetrated corridors. Direct-to-consumer replenishment models bypass legacy supermarket slotting fee structures entirely. White-space capture favors home-brew fermentation kits paired with digital coaching platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic craft specialists with captive Kyushu tea base supply and established JIS packaging documentation systems in Nagoya-adjacent testing corridors. Long-term viability hinges on technical compliance capacity rather than flavor portfolio breadth. The signal to watch is PMDA enforcement phase-in timing for probiotic health claim thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tea Base Sourcing | Kyushu and Shizuoka grower partnerships reduce freight exposure and satisfy METI sustainability requirements. |
| PMDA Functional Claim Substantiation Investment | Strain-specific clinical documentation secures premium shelf placement ahead of enforcement phase-in. |
| High-Pressure Processing Line Deployment | Cold-chain HPP technology extends shelf stability without colony-forming unit degradation for health store distribution. |
| Direct-to-Consumer Subscription Launch | Bypassing retail markups captures consumption-pattern data for flavor personalization in Kanto and Kansai corridors. |
| METI Carbon Footprint Certification | Early sustainability disclosure alignment unlocks preferential placement in government procurement and corporate wellness channels. |
Study Parameters
Independent corroboration across fermentation microbiologists, health store category buyers, PMDA regulatory consultants, and Kyushu tea base growers underwrites the qualitative findings in this study. Primary interviews with Tokyo-based functional food executives, Osaka merchant culture specialists, and Nagoya packaging equipment suppliers combined with secondary validation from METI disclosure filings, PMDA probiotic guidelines, JIS standard documentation, and customs tea import records. Bottom-up channel volume estimates and top-down market sizing triangulate to the figures presented.
Rate-of-change decomposition across product type, distribution channel, end user demographic, and packaging format dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level growth trajectory modeling incorporating PMDA regulatory timeline assumptions, cold-chain logistics density differentials between metropolitan and regional corridors, and subscription platform customer acquisition cost curves. Forecast inputs include SCOBY culture banking capacity constraints and glass bottle supply concentration at domestic energy-exposed glassworks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA enforcement acceleration or sustained energy price spikes affecting JIS container recertification timelines. Forecasts reflect documented assumptions regarding probiotic health claim substantiation pathways and freight volatility persistence. Material deviation in PMDA guideline finalization or METI sustainability disclosure mandate timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Bottled Water Processing Market
Beverages
Water Bottle Market
Beverages
United States Smoothie Market
Beverages
Powdered Soft Drinks Market
Beverages
Fruit Water Market
Beverages
Spring Water Market
Beverages
Fiber Fortified Beverages Market
Beverages
Still Drinks Market
Beverages
Caffeine Mint Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Electrolyte Mixes Market
Beverages
Coconut Water Market
Beverages
Carbonated Soft Drinks Market
Beverages
Direct Piping Water Dispenser Market