
 Low Fat Drinks Market | 2026-2036
Low Fat Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Drinks Market Foresight
Premium low-fat formulations with probiotic claims and clean-label credentials are diverging from commodity reduced-calorie sodas, and this split is realigning how manufacturers allocate R&D budgets and shelf-space negotiations. PepsiCo leverages its beverage science infrastructure to develop enzyme-modified milk proteins with sustained texture profiles. Danone anchors its portfolio in fermented low-fat dairy with live cultures, competing on gut-health positioning rather than calorie reduction alone. The Coca-Cola Company extends its reach through controlled distribution partnerships that prioritize chilled supply chains for perishable low-fat SKUs.
Low fat drinks are beverages formulated with reduced lipid content, typically achieved through centrifugal separation, enzymatic fat hydrolysis, or plant-base substitution, delivering under 2% milk fat equivalent or comparable thresholds for non-dairy alternatives while maintaining mouthfeel through hydrocolloid stabilizers or protein micelle restructuring. Their primary commercial purpose is to satisfy hydration and nutritional needs for consumers monitoring caloric intake, cardiovascular markers, or athletic body composition without sacrificing sensory acceptance. Flavored water and plant-based beverages capture the fastest expansion as sugar taxation and lactose intolerance reshape purchase patterns across demographics. Yogurt drinks retain concentrated margin pools in refrigerated dairy cases where cold-chain density supports premium pricing, while low fat milk occupies mature volume positions in institutional channels including school nutrition programs and hospital foodservice.
The FDA governs nutrient content claims including "low fat" thresholds and added-sugar disclosure on Nutrition Facts panels, directly constraining permissible marketing language and reformulation targets for domestic manufacturers. USDA school meal standards further dictate fat-content ceilings for competitive beverages sold in educational settings, creating a protected demand channel with strict procurement specifications. Forward-looking stakeholders must monitor evolving positions from the FTC on environmental and health claims enforcement, as greenwashing scrutiny intersects with functional beverage positioning to elevate compliance costs for emerging entrants.
Market Dynamics
Enzymatic fat hydrolysis and plant-base substitution technologies are redrawing competitive boundaries between dairy incumbents and alt-milk entrants, forcing simultaneous investment in bioprocessing capacity and clean-label formulation pipelines.
Growth Catalysts
- USDA School Meal Standards:Federal fat-content ceilings for competitive beverages in educational settings create a protected procurement channel with recurring volume commitments and strict specification compliance.
- Fermentation infrastructure:Live culture processing capabilities unlock gut-health positioning that commands refrigerated case premiums beyond commodity calorie-reduction plays.
- Chilled supply chain density:Cold-chain investments in urban clusters enable perishable SKU distribution that supports margin capture in functional beverage segments.
Market Restraints
- Hydrocolloid input volatility:Stabilizer costs for mouthfeel maintenance fluctuate with guar gum and pectin supply interruptions from South Asian agricultural zones.
- Protein micelle restructuring complexity:Technical limitations in enzyme-modified dairy proteins constrain texture parity with full-fat equivalents in ambient-stable formats.
- FDA added-sugar disclosure:Reformulation timelines compress as labeling requirements force simultaneous fat reduction and sugar repositioning without sensory trade-offs.
Strategic Opportunities
- Functional water white space:Electrolyte-enhanced, fat-free formulations target athletic recovery segments underserved by traditional sports drink sodium loads.
- Indian FSSAI alignment:Early compliance with India's food safety standards for low-fat claims opens distribution through modern trade expansion in tier-two cities.
- Direct-to-subscription channels:Chilled delivery models bypass retail slotting fees while capturing recurring revenue from wellness program participants.
Industry Challenges
- Bioprocessing talent scarcity:Fermentation science and enzyme engineering expertise concentrates in pharmaceutical and biofuel sectors, draining beverage R&D pipelines.
- Dual certification timelines:Organic plus low-fat claims require sequential USDA and FDA approvals that extend product launch windows by 8-14 months.
- Legacy dairy equipment retrofit costs:Centrifugal separation infrastructure requires capital-intensive modification to handle plant-based feedstocks with divergent viscosity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Drinks Market |
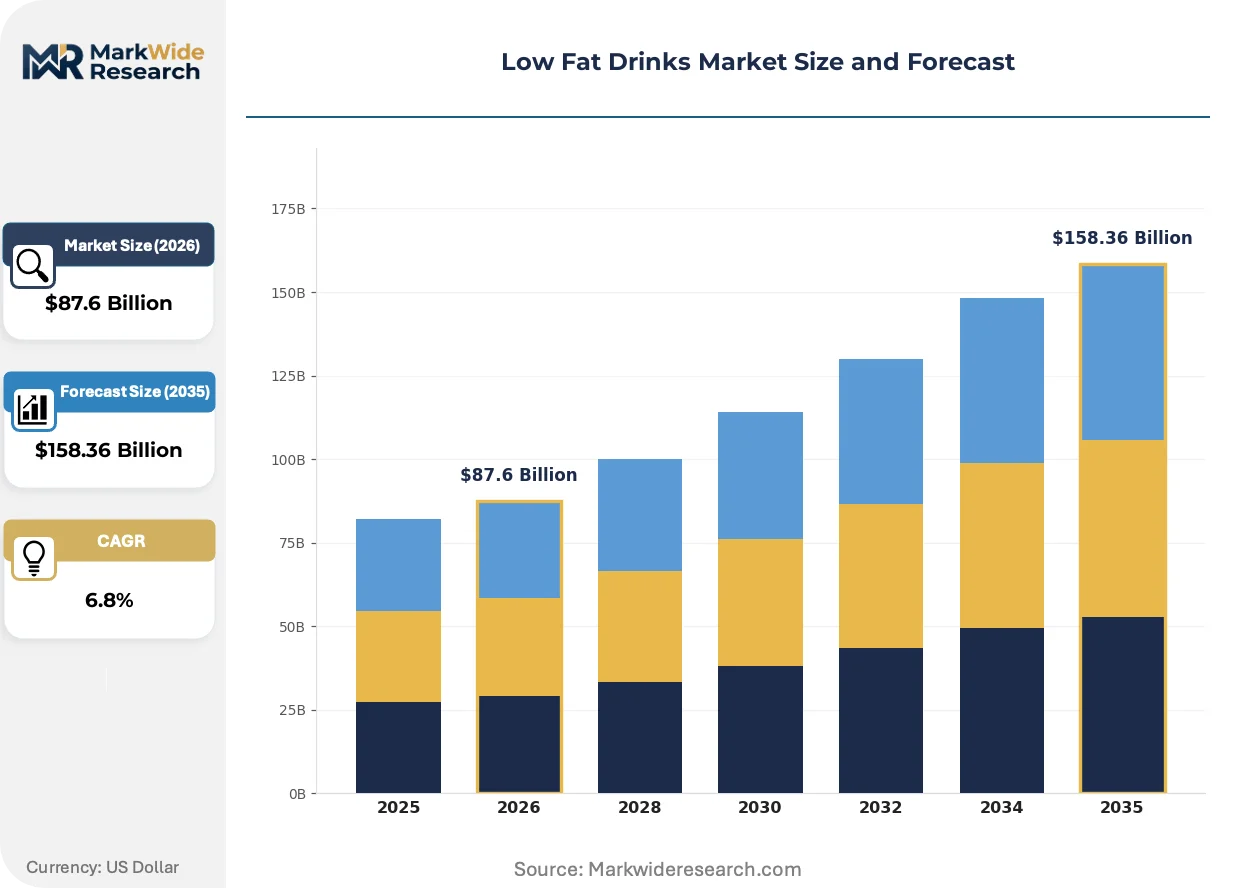
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Water, Low Fat Milk, Yogurt Drinks, Plant-Based Beverages Packaging Type: Cartons, Bottles, Pouches, Cans Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops End User: Health-Conscious Consumers, Athletes, Families, Weight Management Seekers |
| Companies Covered | PepsiCo, The Coca-Cola Company, Nestlé, Danone, Diageo, Bacardi Limited, Herbal Water, Inc., Keurig Dr Pepper, Arla Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Drinks Market Shifts & Advancements
Clean-label stabilization systems and precision fermentation are converging to eliminate the sensory compromise historically accepted in reduced-fat formulations. This convergence is redrawing R&D priorities across both dairy and plant-based portfolios.
Precision fermentation-derived proteins are expanding into low-fat beverage applications as startups and established dairy processors scale contract manufacturing capacity. Sports nutrition and clinical nutrition buyers are adopting these ingredients at accelerated procurement cycles compared to mainstream retail. The technology is expanding into texture-modification roles previously reserved for hydrocolloid blends, compressing ingredient supplier margins in the stabilizer category.
EU Green Deal packaging mandates are forcing beverage manufacturers to transition mono-material bottles and eliminate multi-layer barriers that protect oxygen-sensitive low-fat contents. Industrial consequence includes accelerated investment in aseptic filling lines and high-pressure processing equipment to compensate for reduced packaging protection. Refrigerated plant-based segments face the steepest compliance costs, driving consolidation among mid-sized European processors unable to absorb dual capex burdens.
Subscription-based replenishment models are displacing conventional retail discovery for functional low-fat SKUs as wellness app integrations enable automated reorder triggers tied to workout calendars. Direct-to-consumer channels capture increasing share from conventional grocery sets among urban professional demographics. This behavioral shift concentrates in United States coastal metropolitan markets where cold-chain logistics density supports reliable chilled delivery windows.
Low Fat Drinks Market Segmentation
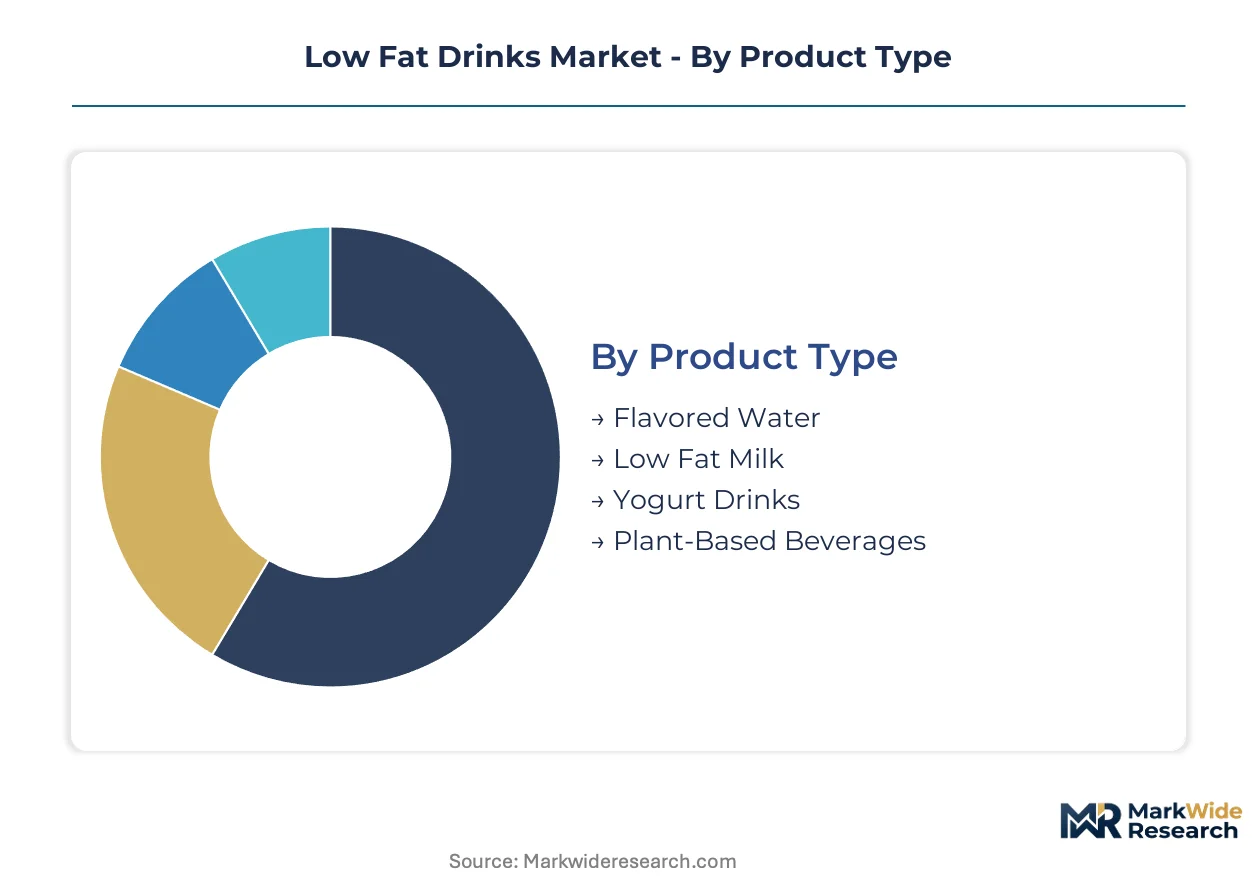
Low fat drinks manufacturers calibrate formulation, packaging, and channel strategies against divergent consumption occasions and buyer willingness to pay for functional claims. Segmentation reveals where refrigerated premium SKUs command margin versus where ambient-stable formats compete on price per liter.
Product Type:
Buyers differentiate by whether they prioritize protein delivery, gut-health functionality, or simple hydration without caloric load.
- Flavored Water:Electrolyte-infused, fat-free formulations target athletic recovery and daily hydration without sugar taxation exposure. Demand clusters in United States metropolitan fitness culture and European markets with sugar levy regimes. Expansion accelerates as sports nutrition buyers reject traditional sodium-heavy sports drinks.
- Low Fat Milk:Centrifugally separated to under 2% milk fat equivalent, this segment anchors institutional procurement through USDA school meal compliance and hospital foodservice contracts. Volume concentrates in North American educational channels with recurring specification-driven purchases.
- Yogurt Drinks:Fermented low-fat dairy with live cultures commands refrigerated case premiums through gut-health positioning rather than calorie reduction alone.
- Plant-Based Beverages:Enzymatic processing and plant-base substitution technologies enable lactose-free alternatives with hydrocolloid-stabilized mouthfeel.
Volume sits with low fat milk; growth tilts toward flavored water.
Packaging Type:
Packaging selection tracks cold-chain availability, shelf-life requirements, and EU Green Deal compliance timelines for mono-material transitions.
- Cartons:Aseptic cartons dominate ambient-stable low-fat milk distribution in institutional channels. Swedish and Finnish retail markets favor this format for plant-based alternatives.
- Bottles:Mono-material PET and rPET bottles capture flavored water and yogurt drink segments where chilled supply chains support perishable SKU distribution. EU packaging mandates are accelerating investment in recyclable barrier technologies.
- Pouches:Flexible pouches serve on-the-go consumption in Asian convenience retail and children's lunchbox occasions.
- Cans:Aluminum cans expand in sparkling flavored water segments competing against reduced-calorie sodas.
Cartons hold institutional volume; bottles capture the steepest expansion trajectory in functional chilled segments.
Distribution Channel:
Channel strategy separates mass-market penetration from premium positioning through cold-chain control and discovery mechanics.
- Supermarkets:Refrigerated dairy cases and beverage aisles deliver scale for low-fat milk and yogurt drinks with live cultures. Slotting fees and planogram negotiations favor established dairy processors with multi-SKU portfolios.
- Online Retail:Subscription-based replenishment models bypass retail intermediaries for functional low-fat SKUs integrated with wellness app ecosystems. United States coastal metropolitan markets show highest penetration.
- Convenience Stores:Ambient-stable flavored waters and single-serve plant-based beverages target impulse purchase occasions.
- Health Food Shops:Clean-label and organic-certified low-fat drinks command price premiums through educated buyer self-selection.
Supermarkets anchor volume throughput; online retail expands most quickly among wellness program participants.
End User:
User segmentation aligns functional claims with specific physiological goals and lifestyle integration patterns.
- Health-Conscious Consumers:Buyers monitoring cardiovascular markers and caloric intake drive clean-label adoption across flavored water and plant-based categories. FDA added-sugar disclosure requirements directly shape their purchase decisions.
- Athletes:Sports nutrition buyers prioritize electrolyte-enhanced, fat-free recovery formulations with precision fermentation-derived proteins. Procurement cycles accelerate compared to mainstream retail adoption curves.
- Families:USDA school meal standards and household lactose intolerance patterns shape multi-generational purchase baskets.
- Weight Management Seekers:Calorie reduction remains primary motivator, though gut-health positioning increasingly displaces simple low-fat claims.
Health-conscious consumers represent mature volume; athletes drive fastest adoption of precision fermentation ingredients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American low-fat beverage innovation through PepsiCo's beverage science infrastructure and the USDA's procurement headquarters proximity. Cold-chain density in this corridor supports refrigerated SKU distribution to institutional buyers.
United States
FDA added-sugar disclosure requirements and USDA school meal standards drive reformulation timelines for domestic manufacturers. The agency's Nutrition Facts labeling mandates force simultaneous fat reduction and sugar repositioning without sensory trade-offs. California's Bay Area wellness ecosystem accelerates precision fermentation adoption for sports nutrition applications.
Germany
EU Green Deal packaging mandates compel mono-material transitions that eliminate multi-layer barriers protecting oxygen-sensitive low-fat contents. EFSA's novel food regulations govern precision fermentation-derived protein approvals for beverage applications. Bavaria's dairy processing corridor retrofits centrifugal separation infrastructure for plant-based feedstock compatibility.
India
FSSAI alignment for low-fat claims opens distribution through modern trade expansion in tier-two cities as lactose intolerance reshapes purchase patterns. The regulator's evolving standards for functional beverage positioning intersect with clean-label preferences. Maharashtra's Mumbai-Pune industrial belt concentrates enzymatic processing capacity for plant-base substitution technologies.
Japan
METI's dual carbon goals accelerate chilled supply chain investments in urban clusters supporting perishable functional beverage distribution. PMDA's food with function claims system enables gut-health positioning beyond simple calorie reduction. Kanto's Tokyo metropolitan market captures subscription-based replenishment models integrated with wellness app ecosystems.
United Kingdom
Sugar taxation regimes reshape flavored water expansion as athletic recovery segments reject traditional sodium-heavy sports drinks. The FSA's enforcement of nutrition content claims constrains permissible marketing language for reduced-fat formulations. London's refrigerated logistics density enables direct-to-consumer chilled delivery windows for premium low-fat SKUs.
Low Fat Drinks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fermentation infrastructure and clean-label credentialing. Consolidated beverage conglomerates with multi-SKU portfolios negotiate favorable supermarket slotting fees, while mid-sized alt-milk entrants struggle with dual certification timelines. Three archetypes dominate: dairy incumbents retrofitting centrifugal separation for plant-based feedstocks, precision fermentation startups scaling contract manufacturing, and controlled-distribution specialists prioritizing chilled supply chains. M&A activity concentrates on bioprocessing capacity acquisition; strategic partnerships lock in exclusive enzyme-modified protein supply.
Among multinational beverage conglomerates, PepsiCo, The Coca-Cola Company, and Danone occupy positions across the premium-commodity spectrum. PepsiCo represents the beverage science infrastructure archetype with enzyme-modified milk protein capabilities. The Coca-Cola Company exemplifies controlled distribution partnership models for perishable SKU cold-chain management. Danone anchors the fermented dairy positioning archetype where live cultures command refrigerated case premiums beyond simple calorie reduction plays.
| Leading Market Players |
|---|
| PepsiCo |
| The Coca-Cola Company |
| Nestlé |
| Danone |
| Diageo |
| Bacardi Limited |
| Herbal Water, Inc. |
| Keurig Dr Pepper |
| Arla Foods |
| Others |
Supply & Pricing Matrix
USDA school nutrition program procurement concentrates demand among institutional buyers with recurring specification-driven contracts, anchoring the market in value-based pricing tied to compliance certification rather than commodity spot dynamics. This buyer archetype's volume commitments and strict fat-content ceilings create pricing power asymmetries that favor established processors with multi-SKU portfolios and cold-chain infrastructure.
Pricing Analysis
Value-based pricing anchored to gut-health outcomes and clean-label certification separates premium fermented SKUs from commodity reduced-calorie alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by live culture density, organic credentialing, and chilled versus ambient stability. Pricing pressure stems from hydrocolloid input volatility and dual certification timelines compressing margin capture. Institutional buyers in USDA-compliant channels exhibit highest price sensitivity, while sports nutrition segments absorb premiums for precision fermentation-derived proteins.
Supply Chain Analysis
Certification gating through FDA low-fat thresholds and USDA organic sequential approvals extends product launch windows and concentrates supplier qualification among incumbent dairy processors with established compliance infrastructure. Manufacturing capacity clusters in the United States, Germany, and India, with enzymatic processing feedstocks drawn from South Asian guar gum zones and European pectin suppliers. Single-source vulnerability in hydrocolloid stabilizers creates exposure to agricultural supply interruptions. Distribution runs through controlled chilled partnerships for perishable SKUs and aseptic carton networks for ambient-stable institutional formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU Green Deal packaging mandates and bioprocessing talent scarcity will force mid-sized alt-milk entrants into acquisition or exit, concentrating margin capture among fermentation-capable incumbents.
For Market Incumbents: Cement defensible positioning through backward integration into enzyme-modified protein production and captive fermentation capacity additions in cold-chain-dense metropolitan corridors. Precision fermentation startups threaten texture-parity claims; counter through exclusive supply partnerships with bioprocessing contract manufacturers and accelerated FSSAI alignment for Indian modern trade expansion. For New Entrants and Emerging Players: Capture white space in functional water segments targeting athletic recovery with electrolyte-enhanced, fat-free formulations that bypass sodium-heavy incumbent positioning. Direct-to-subscription channels integrated with wellness app ecosystems offer the most penetrable go-to-market angle, concentrating in United States coastal metropolitan markets with reliable chilled delivery density. For Investors and Strategic Acquirers: The window for entry favors precision fermentation startups with scaled contract manufacturing capacity and live culture processing capabilities. Long-term viability hinges on bioprocessing talent acquisition and dual certification completion speed. Monitor FSSAI low-fat claim standardization in Indian tier-two cities as inflection signal for geographic expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Contract manufacturing capacity unlocks texture-parity claims that compress hydrocolloid supplier margins. |
| Chilled Supply Chain Expansion | Urban cold-chain density investments enable perishable SKU distribution with premium pricing capture. |
| Dual Certification Investment | Sequential USDA organic and FDA low-fat approvals extend launch windows but lock out commodity competitors. |
| Direct-to-Subscription Launch | Wellness app integration bypasses retail slotting fees and captures recurring revenue from program participants. |
| FSSAI Compliance Alignment | Early adoption of India's low-fat claim standards opens modern trade distribution in tier-two cities. |
Research Methodology
Regulatory filings from the FDA, USDA, and FSSAI, alongside trade data from customs records and Nielsen retail audit databases, formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with beverage R&D directors, cold-chain logistics operators, supermarket category buyers, and fermentation science specialists provided forward-looking input on enzymatic processing adoption curves. Bottom-up SKU-level volume aggregation and top-down macroeconomic adjustment were triangulated to validate segment-level outputs.
Bottom-up modeling of flavored water, low fat milk, yogurt drinks, and plant-based beverage segments across packaging and channel dimensions anchored the analytical framework. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory intervention timing and cold-chain infrastructure investment cycles. Forecast inputs incorporated USDA school meal standard procurement commitments, EU Green Deal packaging compliance timelines, and precision fermentation capacity buildout announcements.
The model holds under stable regulatory enforcement and continued cold-chain investment; deviation in hydrocolloid supply interruptions or FSSAI claim standardization delays would shift volume trajectories. Stakeholders should weight assumptions against their own operating context and certification pipeline status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
US Bubble Tea Market
Beverages
South America Energy Drink Market
Beverages
Europe Bottled Water Market
Beverages
Indonesia Bottled Water Market
Beverages
Collagen Drinks Market
Beverages
Europe Coconut Water Market
Beverages
Fruit Beverages Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Soft Serve Premix Market
Beverages
United States and Australia Coconut Water Market
Beverages
Drinking Water Market
Beverages
Europe Fruits and Vegetables Juice Market
Beverages
US and Canada Premium Bottled Water Market
Beverages
Chocolate Malt Drink Market
Beverages
Root Beer Market
Beverages
Carbonate Drink Maker Market