
 United States Children's Snack Bar Market | 2026-2036
United States Children's Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
United States Children's Snack Bar Market Insights
Supermarket shelf reset strategies is reshaping how children's snack bars reach households, with retailers demanding cleaner ingredient panels and school-safe allergen certifications before granting premium placement. General Mills leverages its cereal aisle dominance to secure cross-category endcap positioning for its snack bar portfolio. Nestlé SA anchors its presence through refrigerated dairy-adjacent placements that blur the line between yogurt and bar formats. Sun-Maid Growers of California competes on fruit-forward positioning that aligns with USDA school snack guidelines.
Children's snack bars are formulated food products typically comprising grain bases, fruit purees, protein isolates, or nut butters bound through extrusion or cold-pressing and portioned into single-serve formats under 150 calories, designed to deliver micronutrient fortification within portable, shelf-stable packaging acceptable for school environments. Granola bars maintain the largest volume footprint though protein bars are capturing faster velocity as parents prioritize sustained satiety for active schedules. Organic ingredient sourcing commands price premiums at shelf while gluten-free formulations have transitioned from niche to baseline expectation in coastal metropolitan markets.
FDA nutrition labeling enforcement and USDA Smart Snacks in School standards collectively dictate permissible sodium, sugar, and fat thresholds that determine institutional eligibility and parental purchase permission. California's Proposition 65 warning requirements and emerging state-level legislation on synthetic food dyes add compliance layers that favor natural colorant suppliers and clean-label manufacturers. Stakeholders must monitor pending federal rulemakings on front-of-package labeling schemes that would instantly recalibrate competitive advantage toward brands with existing nutrient-density scores.
Market Dynamics
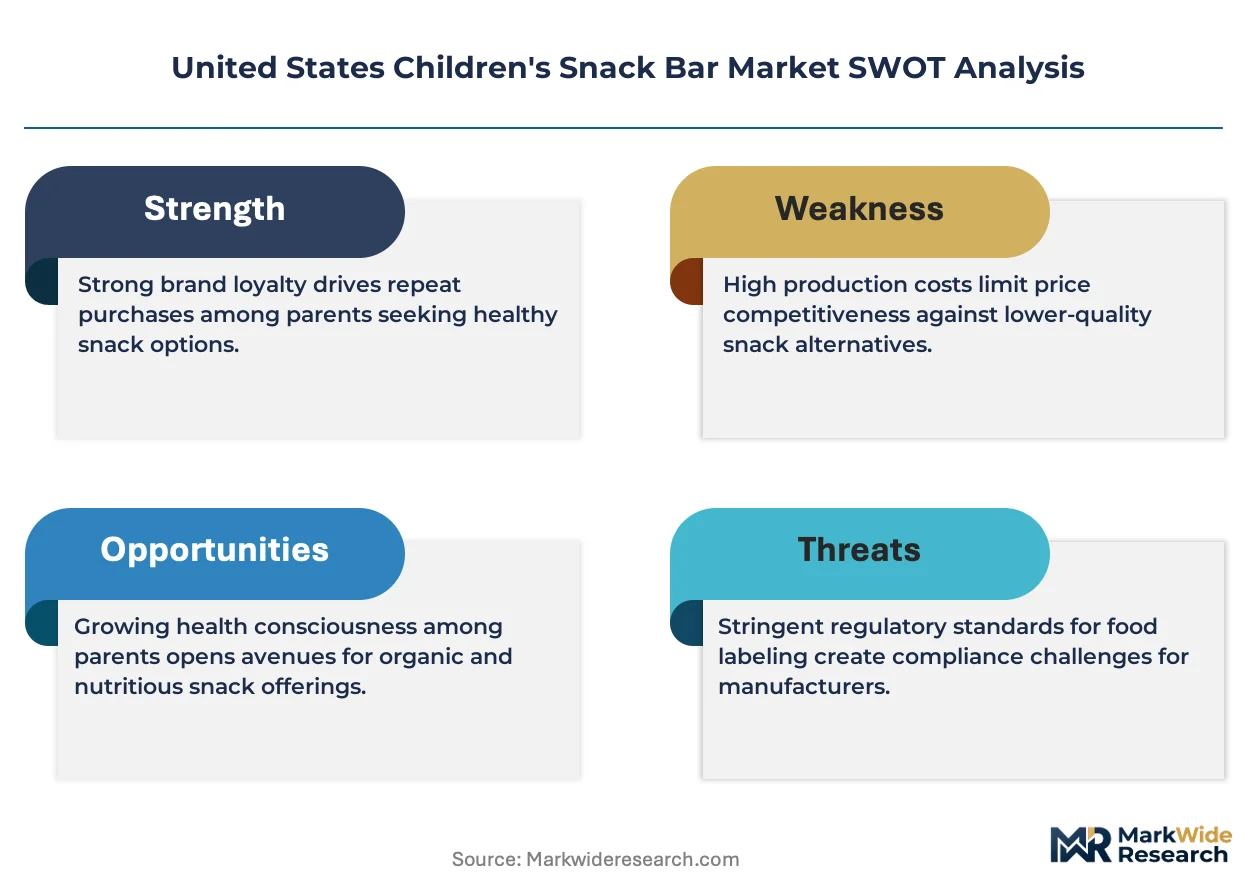
USDA Smart Snacks in School standards and FDA added-sugar disclosure mandates are compressing formulation margins while simultaneously opening institutional procurement channels for compliant manufacturers. The tension between clean-label reformulation costs and school foodservice volume commitments defines current competitive positioning.
Growth Catalysts
- USDA Smart Snacks in School:Federal nutrition thresholds create institutional purchase authorization for qualifying bars, unlocking bulk contracts with K-12 foodservice distributors.
- California urban household density:Concentrated coastal metros generate premium velocity for organic and allergen-free SKUs through specialty retail expansion.
- Cold-pressed binding technology:Lower-temperature processing preserves heat-sensitive micronutrients, enabling fortified positioning without synthetic additives.
Market Restraints
- Organic ingredient cost volatility:Certified grain and fruit puree supply concentrates in drought-exposed agricultural regions, squeezing margin stability.
- Prop 65 litigation exposure:California's warning-label enforcement creates liability risk for trace heavy metals in natural colorants and mineral fortifications.
- Protein isolate import dependency:Whey and pea protein supply chains anchor to limited processing facilities, creating concentration vulnerability.
Strategic Opportunities
- Texas suburban expansion:Rapid metro growth outside Dallas-Fort Worth and Houston creates underpenetrated distribution whitespace for school-safe portfolio extensions.
- Front-of-package labeling convergence:Pending FDA nutrient-density scoring systems would advantage brands with existing clean-label architectures.
- Direct-to-subscription channel:Recurring delivery models bypass slotting-fee barriers while capturing pantry-stocking behavior among dual-income households.
Industry Challenges
- Refrigerated dairy-adjacent placement complexity:Temperature-controlled retail integration demands parallel cold-chain logistics that strain capital deployment timelines.
- Allergen certification backlog:Third-party school-safe verification protocols create 90-120 day product launch delays during peak back-to-school procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Children's Snack Bar Market |
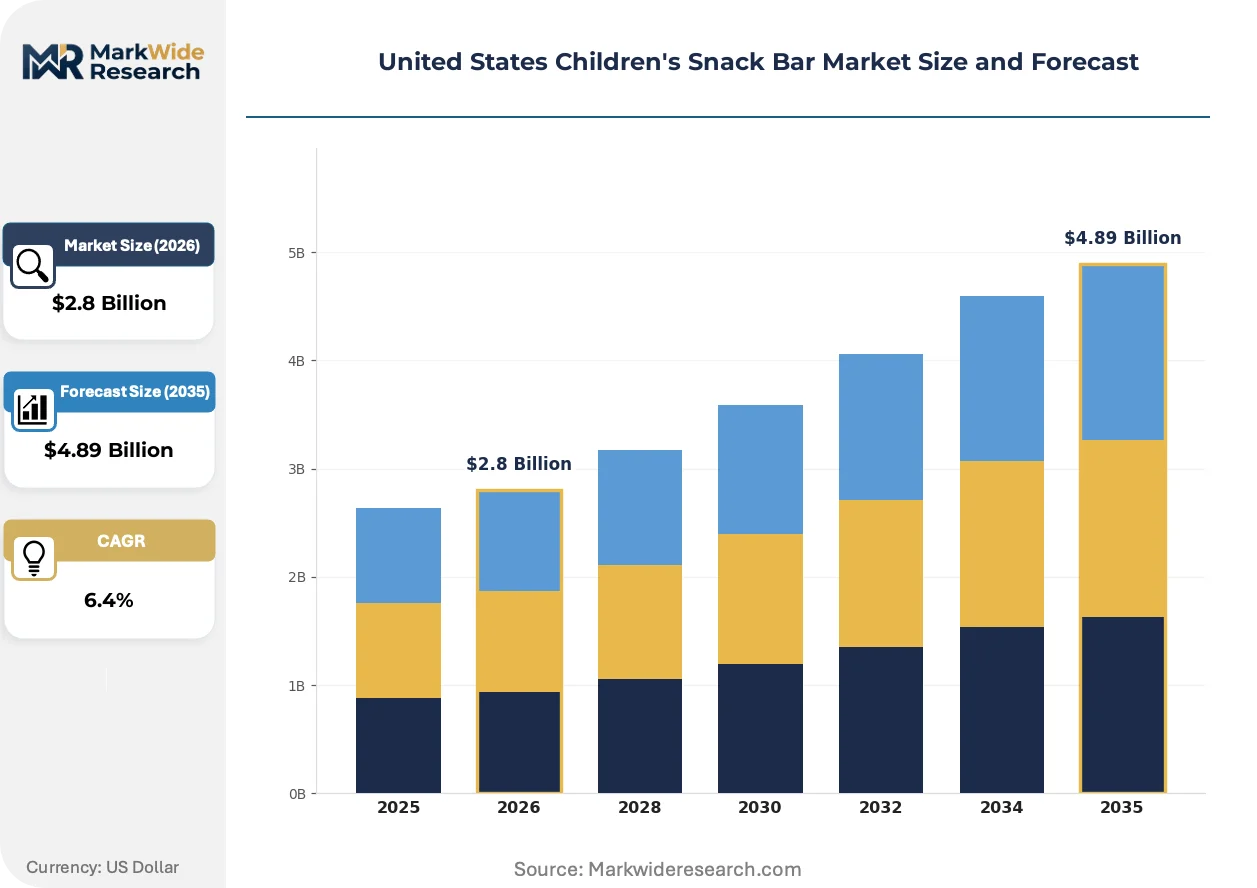
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Fruit Bars, Cookie Bars Ingredient Source: Organic, Non-GMO, Gluten-Free, Fortified Packaging Type: Box, Wrapper, Pouch, Bag Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores |
| Companies Covered | Danone SA, Nestlé SA, Mondelez International Inc, Mars Inc, The Hain Celestial Group Inc, Neptune Wellness Solutions Inc, General Mills Inc, Skout Organic, Sun-Maid Growers of California, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Children's Snack Bar Market Trends and Innovations
Extrusion and binding technologies are compressing traditional manufacturing cost curves while regulatory disclosure mandates accelerate transparency investments. These forces favor mid-scale manufacturers with flexible production footprints over legacy mass-production assets.
Novel enzymatic binding systems replace conventional sugar syrups and hydrogenated oils as primary adhesion mechanisms in granola-bar matrices. Early adopters among organic-focused contract manufacturers report 15-20% reduction in added-sugar content without texture degradation. This enzymatic shift is rendering obsolete thermal-dependent extrusion lines that require high carbohydrate loads for structural integrity.
FDA's updated Nutrition Facts labeling enforcement mandates single-package serving disclosure for multi-bar boxes, altering household purchase calculus. The rule compresses perceived value for economy-format SKUs while elevating single-serve premium positioning. Protein-fortified varieties face the steepest reformulation pressure as parents cross-reference gram-per-dollar metrics at shelf.
School lunchbox procurement is fragmenting from centralized district bidding toward parent-driven individual purchase through retail and subscription channels. Traditional broadline foodservice distributors lose share to direct-to-consumer platforms and specialty retail. This disintermediation concentrates in California and Texas metros where health-conscious retail density supports alternative fulfillment models.
United States Children's Snack Bar Market Segmentation
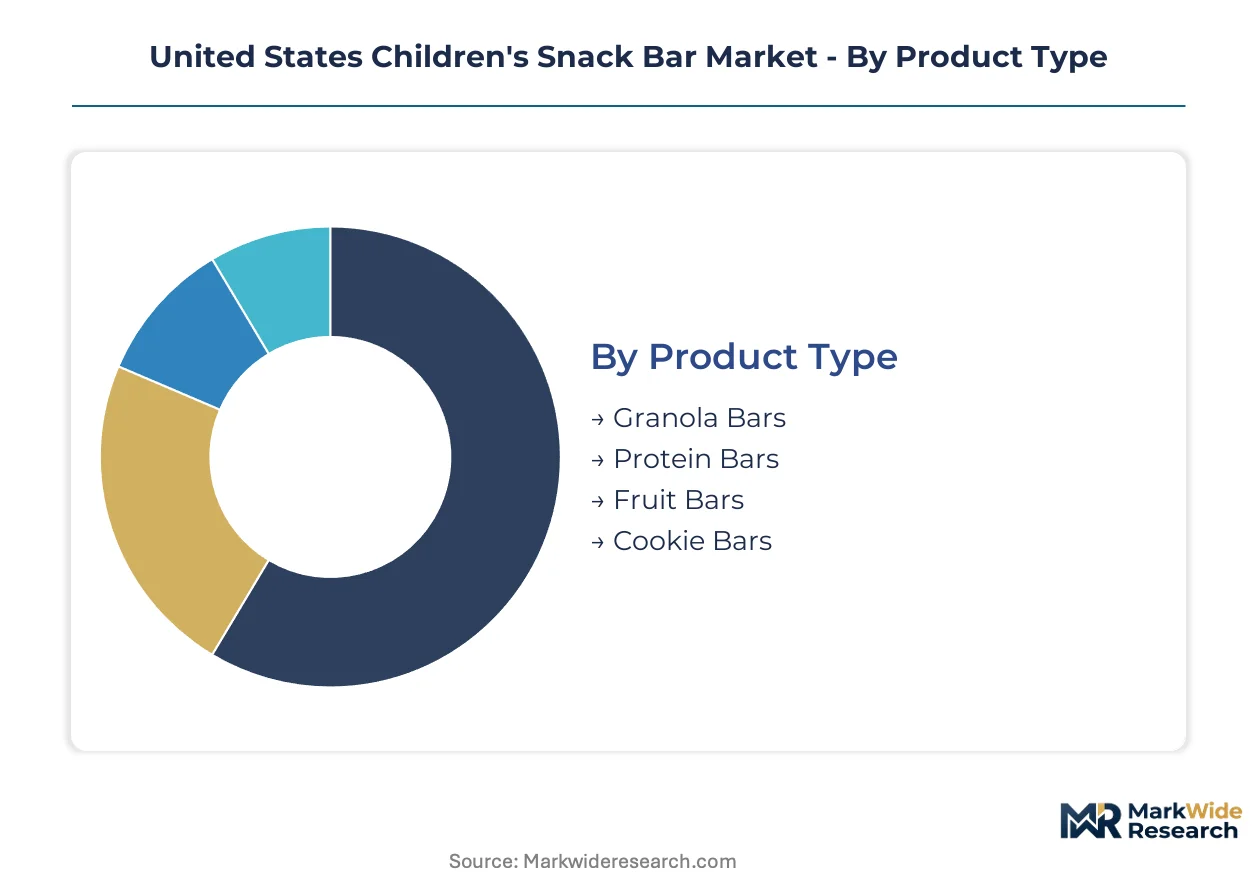
Segmentation in the United States children's snack bar market reveals distinct purchasing logics across product formats, ingredient sourcing, and channel access. Parents navigate trade-offs between convenience, nutritional credentials, and price points that vary systematically by household structure and geography.
Product Type:
After-sales intensity concentrates in protein-fortified variants where texture degradation and spoilage claims drive higher service touchpoints.
- Granola Bars:Oat and grain-based matrices bound with fruit purees or honey syrups, typically 100-130 calories per serving. California and Texas urban households generate concentrated velocity for school-safe, nut-free formulations as USDA Smart Snacks compliance becomes a baseline filter.
- Protein Bars:Whey, pea, or blended protein isolates combined with binding agents to achieve 8-12g protein per 150-calorie portion. Demand clusters among dual-income suburban households with active youth sports schedules prioritizing sustained satiety over pure caloric density.
- Fruit Bars:Compressed fruit purees with minimal grain content, often meeting USDA school snack guidelines without reformulation.
- Cookie Bars:Indulgence-positioned formats with higher sugar ceilings, typically excluded from institutional procurement channels.
Granola bars hold the largest share; momentum sits with protein bars.
Ingredient Source:
Cost tier stratification separates premium-positioned sourcing claims from baseline formulations competing on unit economics.
- Organic:Certified grain and fruit inputs commanding shelf price premiums of 30-50% above conventional equivalents. Supply concentrates in drought-exposed California Central Valley and Texas Panhandle growing regions, creating margin volatility during climate stress events.
- Non-GMO:Identity-preserved supply chains verified through third-party protocols, now standard in coastal metropolitan markets.
- Gluten-Free:Oat and alternative grain formulations processed in certified facilities, transitioned from niche positioning to baseline expectation in health-conscious retail channels.
- Fortified:Micronutrient-enhanced bars with added calcium, iron, or vitamin D targeting nutritional gap closure in school foodservice settings.
Organic commands the steepest price premiums; fortified formats are climbing the fastest as institutional procurement expands.
Packaging Type:
Volume throughput varies dramatically by format, with multi-serve boxes dominating pantry-stocking behavior and single-serve units capturing impulse and lunchbox occasions.
- Box:Multi-bar retail packaging, typically 5-6 count configurations. FDA's updated Nutrition Facts labeling mandates single-package serving disclosure, compressing perceived value for economy formats and elevating premium single-serve positioning.
- Wrapper:Individual film-wrapped bars constituting the dominant school lunchbox format. Demand concentrates in back-to-school procurement windows with strict allergen certification requirements.
- Pouch:Flexible resealable formats targeting toddler and preschool segments with softer bite textures.
- Bag:Bulk configurations for foodservice and institutional channels, requiring parallel distribution infrastructure separate from retail.
Wrapper formats dominate household purchase frequency; pouches are expanding most quickly in early childhood segments.
Distribution Channel:
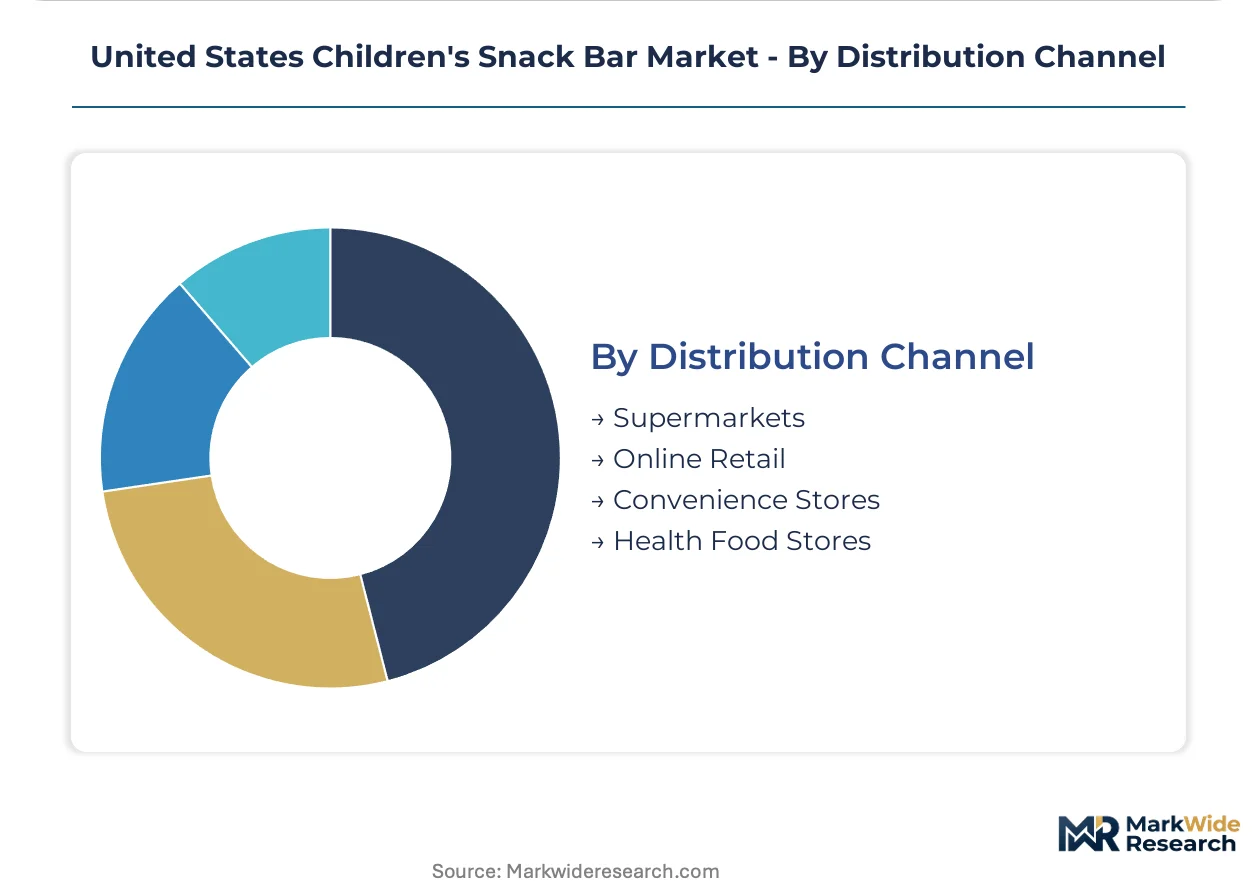
Customer type and purchase occasion fragment sharply across channels, with subscription and direct-to-consumer models bypassing traditional slotting-fee barriers.
- Supermarkets:Primary volume channel where shelf reset strategies and endcap positioning determine trial and velocity. Retailers demand cleaner ingredient panels and school-safe allergen certifications before granting premium placement.
- Online Retail:Subscription and direct-to-consumer platforms capturing pantry-stocking behavior among dual-income households. This channel fragments procurement from centralized district bidding toward parent-driven individual purchase.
- Convenience Stores:Impulse-oriented single-serve placement with limited SKU depth, typically excluding organic and allergen-free variants.
- Health Food Stores:Specialty retail concentrating in California and Texas metros where health-conscious household density supports premium velocity for organic and clean-label portfolios.
Supermarkets retain the largest volume footprint; online retail is gaining share fastest as subscription models lock in recurring purchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 5 freight corridor underwrites California's dominance in organic ingredient distribution, while the Union Pacific rail network anchors Texas processing capacity for allergen-free formulations. These infrastructure assets concentrate procurement gravity in coastal and southwestern metros where health-conscious household density supports premium velocity.
California
Los Angeles and San Francisco metros generate concentrated demand for organic and school-safe SKUs through specialty retail expansion. FDA's updated Nutrition Facts labeling enforcement and Proposition 65 warning requirements create compliance layers favoring natural colorant suppliers. The Central Valley agricultural belt supplies certified grain and fruit inputs, though drought exposure creates margin volatility during climate stress events.
Texas
Dallas-Fort Worth and Houston suburban corridors represent underpenetrated distribution whitespace for school-safe portfolio extensions. USDA Smart Snacks in School standards unlock institutional procurement channels for qualifying manufacturers. The Panhandle growing region anchors non-GMO oat and alternative grain supply chains serving national gluten-free formulation demand.
New York Metro
Dual-income households in Manhattan and Brooklyn drive subscription channel adoption for pantry-stocking convenience. State-level legislation on synthetic food dyes adds compliance complexity beyond federal baselines. The Port of Newark handles refrigerated dairy-adjacent imports that support yogurt-bar format innovation in regional retail.
Pacific Northwest
Seattle and Portland metros concentrate demand for cold-pressed binding technology and enzymatic adhesion systems. EPA water quality regulations influence processing facility siting decisions for organic-certified manufacturers. The Columbia River Gorge corridor hosts contract manufacturing capacity serving West Coast clean-label brands.
Southeast
Atlanta and Miami metros exhibit rising velocity for protein-fortified variants targeting active youth sports schedules. State procurement offices in Georgia and Florida administer bulk K-12 foodservice contracts tied to USDA nutritional thresholds. The I-75 distribution spine connects southeastern manufacturing to mid-Atlantic retail networks.
United States Children's Snack Bar Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and binding technology supply. The vendor base organizes around three archetypes: diversified food conglomerates with cereal aisle dominance, dairy-adjacent refrigerated players, and fruit-forward cooperatives with agricultural integration. Consolidation pressure intensifies as slotting-fee barriers and allergen certification requirements favor scaled balance sheets over emerging entrants. Dominant competitive moves include cross-category endcap positioning and refrigerated dairy-adjacent placement expansion.
Within the diversified conglomerate tier, General Mills Inc and Nestlé SA occupy positions leveraging existing retail relationships for snack bar portfolio distribution. Mondelez International Inc exemplifies the scale-driven snacking specialist archetype with biscuit and confectionery heritage. Sun-Maid Growers of California anchors the agricultural cooperative model with fruit-forward positioning aligned to USDA school snack guidelines.
| Leading Market Players |
|---|
| Danone SA |
| Nestlé SA |
| Mondelez International Inc |
| Mars Inc |
| The Hain Celestial Group Inc |
| Neptune Wellness Solutions Inc |
| General Mills Inc |
| Skout Organic |
| Sun-Maid Growers of California |
| Others |
Pricing and Supply Chain Analysis
California's Central Valley agricultural belt anchors certified organic grain and fruit puree supply, concentrating ingredient sourcing power among cooperatives with drought-exposed acreage. This geographic concentration translates directly into margin volatility that compresses pricing flexibility for downstream manufacturers reformulating toward USDA Smart Snacks compliance.
Pricing Analysis
Volume-discount tiering structures separate institutional foodservice contracts from premium retail SKUs, with three-tier pricing stratification across organic-certified, non-GMO verified, and conventional ingredient grades. Price differentiation hinges on certification depth and school-safe allergen protocols. Cost compression in conventional tiers intensifies as enzymatic binding technology reduces added-sugar requirements without texture loss. Mass-market retailers exhibit highest price sensitivity, while specialty health food channels absorb organic premiums with minimal volume elasticity.
Supply Chain Analysis
Tariff exposure between the United States and pea protein processing facilities in Canada and China dominates supply chain risk assessment for protein-fortified variants. Raw material dependencies center on certified oat groats from the Texas Panhandle, whey isolate from Upper Midwest dairy cooperatives, and natural colorants from California fruit processors. Single-source vulnerability concentrates in cold-pressed binding equipment manufacturers. Distribution runs through K-12 foodservice broadliners for institutional volume and direct-to-subscription platforms for recurring household replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment services represent a service-attach opportunity expanding faster than individual bar sales, as dual-income households prioritize pantry-stocking automation over retail trial.
For Market Incumbents: Build certification moats through accelerated USDA Smart Snacks pre-qualification and Prop 65 compliance documentation. Defend against emerging contract manufacturers with enzymatic binding capabilities by securing exclusive acreage contracts in drought-stressed California growing regions. Prioritize refrigerated dairy-adjacent placement expansion to blur format boundaries with yogurt alternatives. For New Entrants and Emerging Players: Establish a beachhead in Texas suburban corridors outside Dallas-Fort Worth and Houston where school-safe portfolio extensions face minimal incumbent saturation. Target protein-fortified variants for youth sports households seeking sustained satiety solutions. Deploy direct-to-subscription channel strategies to bypass supermarket slotting-fee barriers and capture recurring purchase behavior. For Investors and Strategic Acquirers: Long-term, this sits as a clean-label consolidation play because allergen certification backlogs and reformulation compliance costs favor scaled balance sheets over emerging entrants. Acquisition targets should display existing USDA institutional procurement relationships and flexible enzymatic production footprints. Monitor FDA front-of-package labeling rulemaking as the signal for competitive recalibration toward nutrient-density scoring advantages.| Strategic Initiative | Industry Significance |
|---|---|
| USDA Smart Snacks Pre-Qualification | Unlocks bulk K-12 foodservice contracts with district-level procurement authorization. |
| Enzymatic Binding Technology Adoption | Reduces added-sugar content 15-20% without synthetic additives or texture degradation. |
| Direct-to-Subscription Channel Launch | Bypasses retailer slotting fees while capturing recurring pantry-stocking behavior. |
| Refrigerated Dairy-Adjacent Placement | Blurs category boundaries with yogurt formats in temperature-controlled retail. |
| Prop 65 Compliance Documentation | Mitigates California litigation exposure for trace heavy metals in natural fortifications. |
Research Methodology
Desk research of FDA labeling guidance documents, USDA procurement databases, and California agricultural supply records preceded structured interviews with K-12 foodservice directors, retail category buyers, organic certification specialists, and contract manufacturing operations managers. Secondary validation drew from Nielsen retail audit data, customs import records for protein isolates, and SEC filings of diversified food conglomerates. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Assumptions held fixed include FDA enforcement timelines for front-of-package labeling and prevailing drought frequency in Central Valley growing regions; variables tested included enzymatic technology adoption curves and subscription channel penetration rates. The analytical framework modeled product type, ingredient source, packaging configuration, and distribution channel across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price tier concentration, with specific inputs for organic certification cost inflation and school lunchbox procurement fragmentation.
Sensitivities concentrate around FDA rulemaking acceleration, climate stress events in oat and fruit supply regions, and tariff adjustments affecting Canadian pea protein imports. Forecasts reflect documented assumptions subject to revision from regulatory, meteorological, or trade policy shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Fat Sweet Snacks Market
Snacks
South East Asia Snack Bar Market
Snacks
India Energy Bar Market
Snacks
Trail Mix Market
Snacks
Global Tortilla Chips Market
Snacks
Organic Snack Food Market
Snacks
Sweet Potato Fries Market
Snacks
North America Baked Chips Market
Snacks
Salty Puffed Snacks Market
Snacks
Dairy Protein Crisps Market
Snacks
Baked Chips Market
Snacks
Energy Balls Market
Snacks
Popcorn Market
Snacks
North America Snack Pellets Market
Snacks
South Africa Snack Bar Market
Snacks
United Kingdom Snack Bar Market