
 South America Energy Drink Market | 2026-2036
South America Energy Drink Market Size, Share, and Industry Trends Forecast 2026-2036
South America Energy Drink Market Analytics
Asset-light franchising and third-party co-packing arrangements is narrowing the capital barrier for regional challengers seeking shelf space against multinational incumbents. Monster Beverage Corp. leverages its diversified flavor portfolio to sustain pricing power in premium convenience channels. AJE Group anchors its position through deep backward integration into Andean botanical sourcing. Postobon S.A. competes on hyperlocal distribution density across Colombian tertiary cities.
South America energy drinks constitute caffeinated, often taurine-fortified functional beverages formulated with B-vitamin complexes and glucuronolactone, primarily manufactured through cold-fill aseptic processing to preserve volatile aromatic compounds. Carbonated variants dominate volume throughput in Brazil and Mexico due to established soft-drink infrastructure and consumer palate conditioning. Sugar-Free positioning captures the fastest margin expansion as ANVISA-aligned labeling mandates and professional-end-user demand converge. Supermarkets and convenience stores still control the bulk of physical distribution, though online retailers are capturing disproportionate growth in Argentina's inflation-stressed economy.
ANVISA governs caffeine ceiling limits and novel ingredient approval pathways in Brazil, while Argentina's national food safety authority enforces parallel additive disclosure protocols that fragment cross-border formulation standardization. The region's patchwork of sugar taxation regimes and front-of-pack warning label mandates directly steers R&D investment toward reduced-calorie and natural-extract formulations. Stakeholders must monitor pending Mercosur harmonization talks and preemptively adapt labeling and formulation specifications to avoid stranded inventory or market exclusion.
Market Dynamics
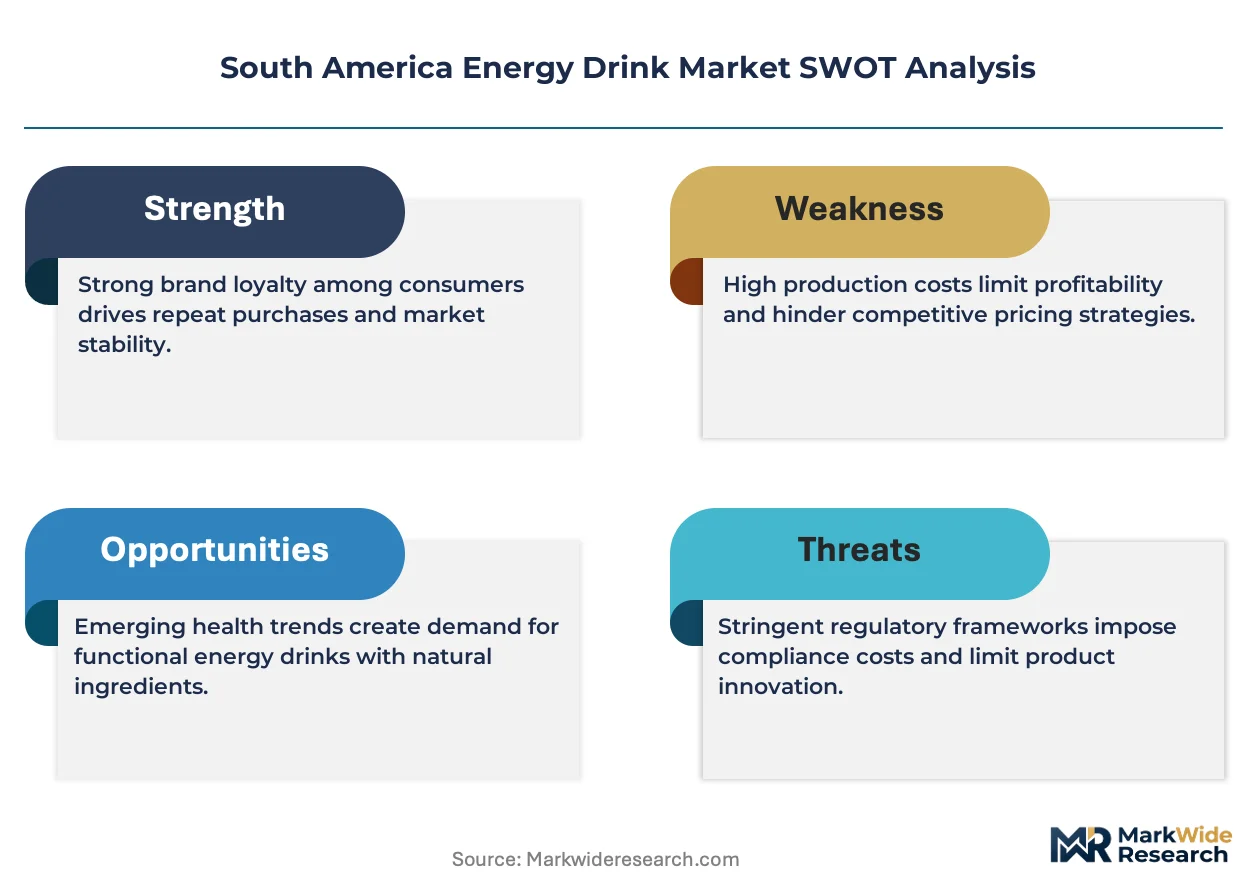
ANVISA's tightening caffeine disclosure mandates and sugar taxation frameworks are forcing reformulation investments across Brazilian manufacturing lines, compressing margins for standard-calorie portfolios while accelerating natural-extract R&D pipelines.
Growth Catalysts
- Professional End-User Demand:White-collar workers in São Paulo's financial district are adopting sugar-free variants as productivity tools, expanding the category beyond traditional sports and nightlife consumption.
- ANVISA Labeling Alignment:Brazil's front-of-pack caffeine disclosure requirements are creating regulatory clarity that reduces consumer hesitation and accelerates trial rates among risk-averse demographics.
- Cold-Fill Aseptic Processing:This manufacturing technology preserves volatile aromatic compounds in botanical extracts, enabling premium positioning for Andean-sourced formulations.
Market Restraints
- Caffeine Ceiling Limits:ANVISA's maximum caffeine thresholds constrain potency differentiation, preventing brands from competing on stimulant intensity.
- Sugar Input Volatility:Brazil's ethanol-sugar arbitrage swings disrupt sucrose pricing predictability, complicating cost planning for standard-calorie production runs.
- Cross-Border Formulation Fragmentation:Argentina's additive disclosure protocols diverge from Brazilian standards, forcing dual-SKU inventory strategies that raise working capital requirements.
Strategic Opportunities
- Colombian Tertiary Cities:Hyperlocal distribution density remains underdeveloped outside Bogotá and Medellín, creating whitespace for challenger brands with flexible logistics models.
- Mercosur Harmonization Talks:Pending regulatory convergence could eliminate stranded inventory risks and enable unified pan-Southern Cone product architectures.
- E-Commerce Channel Expansion:Argentina's inflation-stressed economy is pushing consumers toward online retailers for bulk purchasing and price transparency.
Industry Challenges
- Botanical Sourcing Certification:Securing organic and fair-trade credentials for Andean ingredient supply chains extends procurement timelines by 8-14 months.
- Co-Packer Capacity Constraints:Third-party manufacturing slots in Brazil's southeastern corridor face 6-month backlogs, delaying regional challenger market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Energy Drink Market |
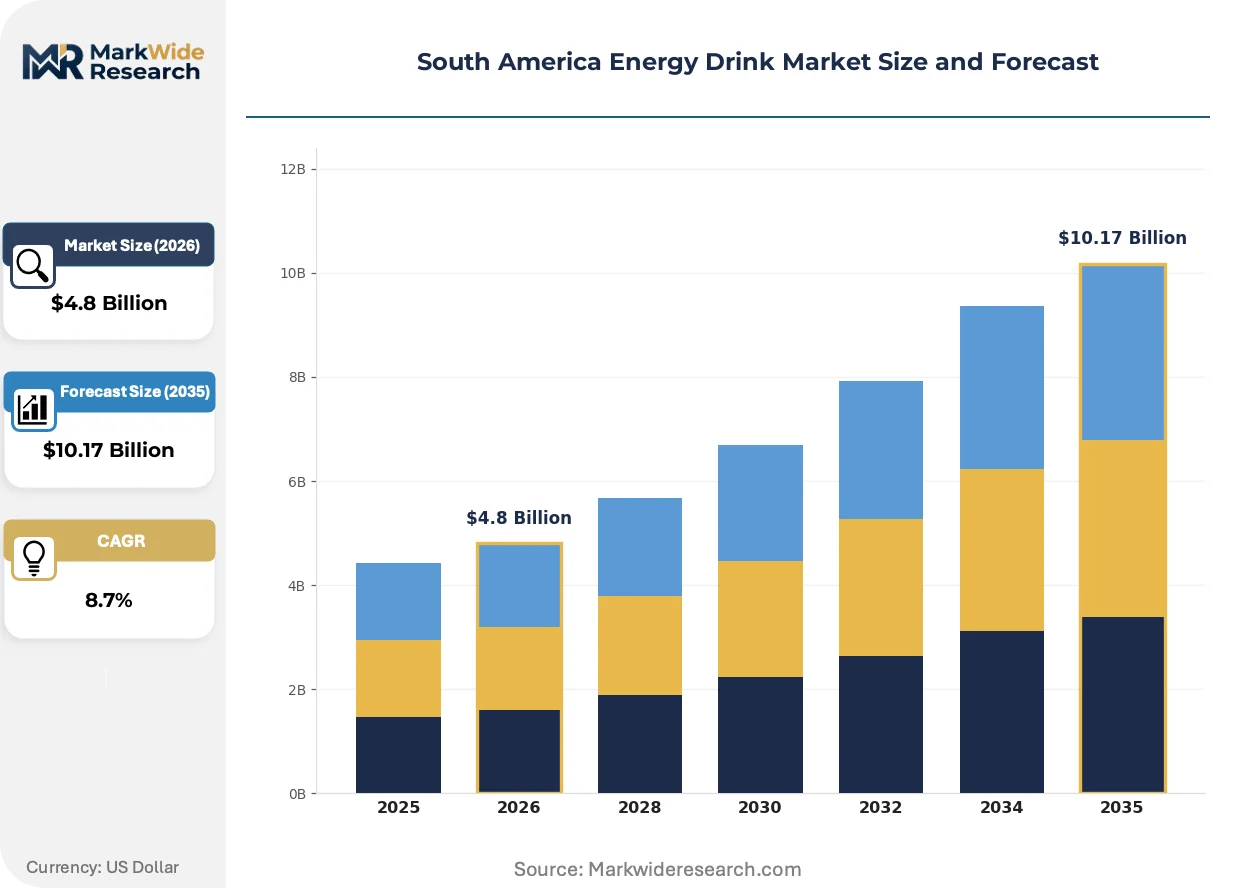
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Organic, Sugar-Free End User: Teenagers, Young Adults, Athletes, Professionals Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Health Stores Serving Size: 250ml, 500ml, 1L, 2L |
| Companies Covered | Red Bull GmbH, Monster Beverage Corp., The Coca-Cola Company, PepsiCo Inc., Anheuser-Busch InBev, AJE Group, Postobon S.A., Cervejaria Petropolis SA, Globalbev Bebidas e Alimentos SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Energy Drink Market Evolving Landscape
Reformulation priorities are pivoting toward natural caffeine matrices and reduced-glycemic sweeteners as regulatory pressure and professional end-user preferences converge on cleaner-label positioning.
Botanical caffeine extraction from guaraná and yerba mate is hybridizing with synthetic caffeine in hybrid formulations that deliver sustained-release energy profiles. Brazilian premium brands are adopting these matrices to satisfy ANVISA-aligned disclosure requirements while maintaining functional efficacy. The technology is compressing the performance gap between natural-positioned and conventional energy drinks.
ANVISA's novel ingredient approval pathways are extending pre-market authorization timelines for exotic adaptogens and nootropic additives. Manufacturers are redirecting innovation budgets toward GRAS-status botanicals with established safety dossiers. Sugar-free SKUs face the steepest compliance burden as sweetener blends require extensive stability documentation.
Convenience stores in Brazil's southeastern corridor are consolidating shelf-space negotiations into annual category reviews with centralized buyers. Independent regional brands are losing facings to multinational portfolios with unified trade spend commitments. This concentration is most visible in São Paulo's metropolitan retail networks where single distributors control multiple convenience banners.
South America Energy Drink Market Segmentation
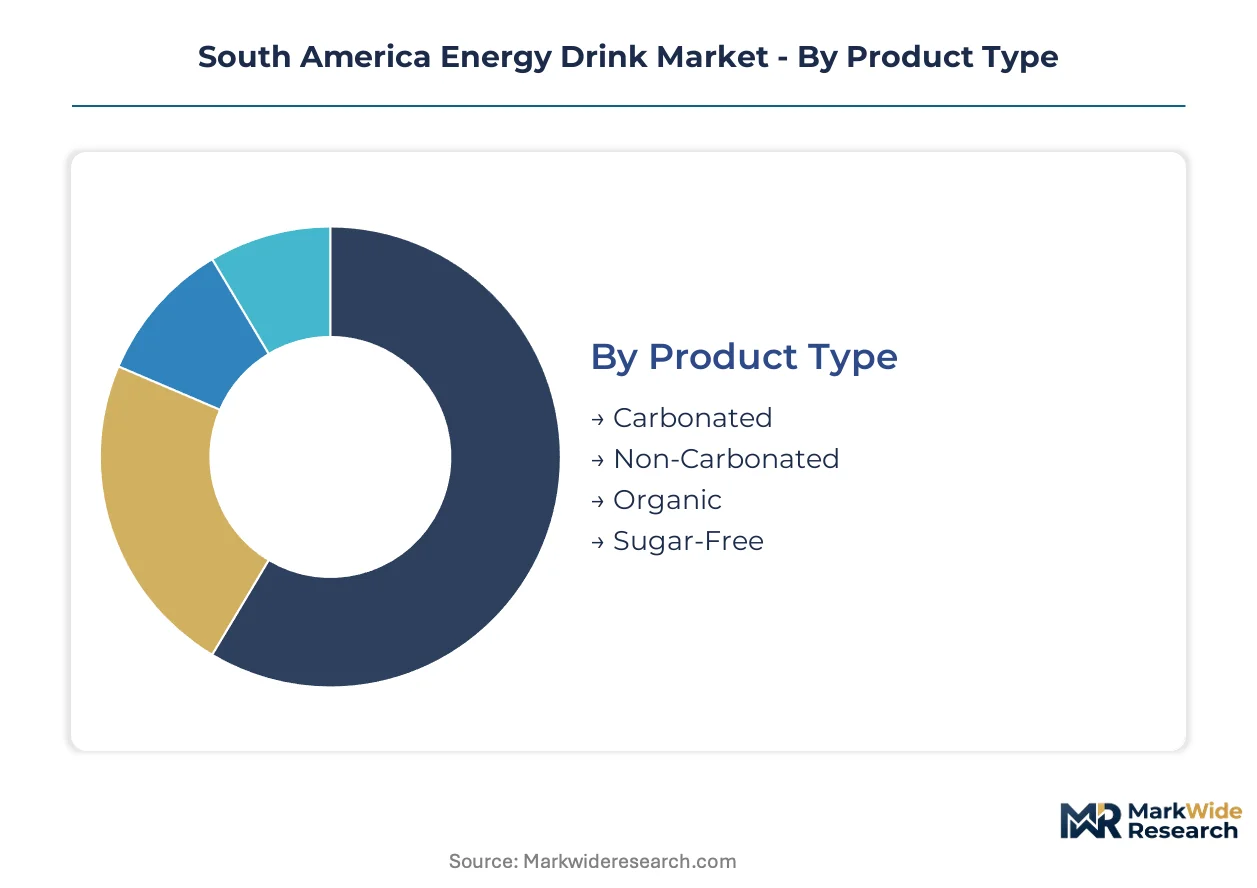
Energy drink segmentation in South America reflects divergent consumption contexts—from São Paulo's corporate towers to Colombia's tertiary cities. Each dimension captures distinct formulation priorities, channel economics, and regulatory exposure that shape portfolio architecture.
Product Type:
Cost tier differentiation separates commodity volume plays from premium extraction technologies and compliance-driven reformulations.
- Carbonated:Cold-fill aseptic processing preserves volatile aromatic compounds in these effervescent formulations. Brazilian southeastern corridor consumers drive volume, with established soft-drink infrastructure enabling cost-efficient distribution through centralized convenience store buyers.
- Sugar-Free:Reduced-glycemic sweetener blends face ANVISA's steepest stability documentation burdens. Professional end-users in São Paulo's financial district adopt these as productivity tools, expanding margins fastest as sugar taxation frameworks tighten.
- Non-Carbonated:Still formulations target health stores and botanical-positioned portfolios with yerba mate and guaraná matrices.
- Organic:Andean-sourced botanicals require 8-14 month procurement timelines for organic certification, constraining supply elasticity.
Carbonated holds installed capacity. Sugar-Free is rotating up the share rankings.
End User:
Application context determines caffeine matrix selection, with professional use cases demanding sustained-release profiles distinct from nightlife or sports consumption.
- Young Adults:Brazil and Argentina's fastest-expanding cohort drives trial rates and flavor rotation. ANVISA-aligned caffeine disclosure reduces purchase hesitation among risk-averse demographics entering the category.
- Professionals:White-collar workers adopt sugar-free variants as productivity infrastructure. Hybrid natural-synthetic caffeine formulations deliver sustained-release energy profiles suited to extended work sessions.
- Athletes:Taurine-fortified formulations with B-vitamin complexes target performance positioning in gym and sports club channels.
- Teenagers:ANVISA caffeine ceiling limits constrain potency targeting for this demographic, forcing brands toward flavor innovation rather than stimulant differentiation.
Young Adults command volume throughput. Professionals are climbing the fastest.
Distribution Channel:
Volume concentration varies sharply by geography, with inflation-stressed Argentina diverging from Brazil's consolidated retail networks.
- Supermarkets:Control bulk physical distribution across Brazil's southeastern corridor. Annual category reviews with centralized buyers increasingly favor multinational portfolios with unified trade spend commitments.
- Online Retailers:Capture disproportionate growth in Argentina's inflation-stressed economy through bulk purchasing and price transparency. E-commerce expansion creates whitespace for challenger brands with flexible logistics models.
- Convenience Stores:São Paulo metropolitan networks consolidate shelf-space negotiations, squeezing independent regional brands' facings.
- Health Stores:Organic and botanical-positioned SKUs find premium positioning outside mass retail price competition.
Supermarkets anchor volume infrastructure. Online Retailers are gaining share fastest.
Serving Size:
Customer type and consumption occasion dictate format economics, from single-serve impulse to multi-serve household inventory.
- 250ml:Standard impulse format for convenience channel single-serve purchase. ANVISA caffeine disclosure requirements apply per-unit, creating labeling cost efficiency.
- 500ml:Extended consumption format dominates professional end-use and gym channel placement. Sugar-free variants concentrate in this tier.
- 1L:Multi-serve household format emerging in online retail bulk purchasing patterns.
- 2L:Value-format concentrates in Colombian tertiary cities where hyperlocal distribution density remains underdeveloped.
250ml holds unit volume leadership. 500ml is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South America's energy drink trade flows reflect Brazil's manufacturing dominance against Argentina's import dependence amid currency volatility. Brazilian producers supply neighboring Mercosur markets while Colombian and Chilean markets absorb premium-priced imports. Cross-border formulation fragmentation complicates unified regional product strategies.
Brazil
São Paulo's metropolitan corridor concentrates 60% of national consumption, driven by white-collar professionals adopting sugar-free variants as productivity infrastructure. ANVISA's caffeine ceiling limits and front-of-pack disclosure mandates compress formulation flexibility while accelerating natural-extract R&D investment. The southeastern manufacturing belt around Rio de Janeiro hosts cold-fill aseptic processing capacity serving export markets.
Argentina
Inflation-stressed consumers pivot toward online retail bulk purchasing for price transparency, expanding e-commerce channel penetration faster than physical retail. The national food safety authority enforces additive disclosure protocols diverging from Brazilian standards, forcing dual-SKU inventory strategies. Buenos Aires anchors demand concentration while secondary cities remain underpenetrated by premium-positioned portfolios.
Colombia
Hyperlocal distribution density outside Bogotá and Medellín creates whitespace for challenger brands with flexible logistics models. Postobon S.A. leverages deep territorial coverage across tertiary cities to defend market position. Sugar taxation frameworks and front-of-pack warning labels steer innovation toward reduced-calorie formulations targeting professional end-users.
Chile
Santiago's concentrated urban population supports premium-channel development for botanical-positioned SKUs with Andean-sourced ingredients. The country's stringent food labeling regulations align with evolving Mercosur harmonization standards, reducing cross-border compliance friction. Northern mining regions generate distinct demand for high-potency formulations targeting shift-work consumption patterns.
Peru
AJE Group anchors supply chains through backward integration into Andean botanical sourcing, securing organic and fair-trade credentials for guaraná and yerba mate extracts. Lima's retail consolidation mirrors Brazilian patterns, with centralized buyers favoring multinational portfolios. Procurement timelines for certified ingredients extend 8-14 months, constraining rapid portfolio expansion.
South America Energy Drink Market Competitive Landscape
On the supply side, the industry is bifurcated between multinational beverage conglomerates with unified trade spend commitments and regional specialists leveraging hyperlocal distribution density or botanical supply chain control. Three strategic archetypes dominate: scale-driven multinationals commanding centralized retail negotiations, Andean-integrated regional players with captive ingredient sourcing, and asset-light challengers exploiting third-party co-packing and franchising to bypass capital barriers. Competitive intensity concentrates on shelf-space allocation through annual category reviews, reformulation speed to meet tightening ANVISA standards, and e-commerce logistics flexibility in inflation-stressed markets.
Among scale-driven multinationals, Red Bull GmbH, Monster Beverage Corp., and The Coca-Cola Company exemplify archetypes differentiated by portfolio breadth and channel positioning. Red Bull occupies a position synonymous with premium energy positioning across nightlife and sports consumption contexts. Monster Beverage represents diversified flavor portfolio strategies sustaining pricing power in convenience channels. The Coca-Cola Company anchors mass-market penetration through existing soft-drink infrastructure and retail relationships. Regional specialists including AJE Group and Postobon S.A. sit within a distinct tier defined by territorial density and backward integration advantages rather than multinational scale.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Monster Beverage Corp. |
| The Coca-Cola Company |
| PepsiCo Inc. |
| Anheuser-Busch InBev |
| AJE Group |
| Postobon S.A. |
| Cervejaria Petropolis SA |
| Globalbev Bebidas e Alimentos SA |
| Others |
Value Network & Pricing Analysis
Co-packer capacity constraints across Brazil's southeastern corridor signal undercapacity conditions that intensify pricing power for contracted manufacturing slots while forcing challenger brands toward premium positioning or extended cash conversion cycles.
Pricing Analysis
Professional end-users anchor pricing structure across the sugar-free segment, where ANVISA-aligned disclosure requirements and sustained-release caffeine matrices command premium positioning. Price differentiation separates certified organic botanical formulations from conventional synthetic caffeine variants, with volume scale and certification tier as primary drivers. Pricing pressure stems from sugar input volatility driven by Brazil's ethanol-sugar arbitrage swings, compressing margins for standard-calorie portfolios. Young adult consumers in Argentina's inflation-stressed economy exhibit highest price sensitivity, while white-collar professionals in São Paulo's financial district demonstrate lowest sensitivity due to productivity-tool positioning.
Supply Chain Analysis
Tariff exposure between Brazil and Argentina dominates supply chain risk planning as divergent additive disclosure protocols force dual-SKU inventory strategies. Manufacturing concentration centers on Brazil's southeastern corridor, with secondary bottling capacity in Colombia and Peru. Raw material dependencies include Andean-sourced guaraná and yerba mate extracts, synthetic caffeine inputs, and reduced-glycemic sweetener blends. Single-source vulnerability persists for certified organic botanical procurement, where 8-14 month certification timelines constrain supply elasticity. Distribution runs through supermarket centralized buyers in Brazil, online retail platforms in Argentina, and hyperlocal networks in Colombian tertiary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as professional end-user demand splinters the category beyond traditional sports and nightlife consumption, creating whitespace for positioning around sustained-release caffeine matrices and productivity infrastructure.
For Market Incumbents: Harden formulation flexibility through backward integration into Andean botanical sourcing, securing captive supply of certified guaraná and yerba mate extracts against procurement timeline extension. Deepen channel control by consolidating annual category review negotiations with São Paulo metropolitan convenience store distributors, squeezing facings for independent regional challengers. Prioritize R&D investment in hybrid natural-synthetic caffeine matrices that satisfy ANVISA disclosure requirements while maintaining functional efficacy against emerging premium botanical-positioned entrants. For New Entrants and Emerging Players: Establish a beachhead in Colombian tertiary cities outside Bogotá and Medellín, where Postobon S.A.'s hyperlocal density leaves whitespace for flexible logistics models targeting 2L value formats. Exploit Argentina's e-commerce channel expansion driven by inflation-stressed bulk purchasing patterns, leveraging online retail price transparency to bypass consolidated physical retail gatekeepers. Deploy asset-light franchising and third-party co-packing arrangements to narrow capital barriers against multinational trade spend commitments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across sugar-free SKU development as ANVISA stability documentation burdens shift R&D investment toward GRAS-status botanicals with established safety dossiers. Long-term viability favors acquisition targets with captive Andean ingredient supply chains and flexible logistics models serving inflation-stressed e-commerce channels. Monitor Mercosur harmonization talks as the critical inflection signal—regulatory convergence would eliminate stranded inventory risks and enable unified pan-Southern Cone product architectures, revaluing dual-SKU inventory strategies as stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Andean Botanical Sourcing | AJE Group's captive supply of certified guaraná extracts compresses procurement timelines by 8-14 months versus market sourcing. |
| Sugar-Free SKU Portfolio Expansion | ANVISA-aligned labeling mandates and professional end-user demand convergence accelerate margin expansion in reduced-calorie positioning. |
| E-Commerce Channel Development | Argentina's inflation-stressed economy pushes bulk purchasing toward online retailers with price transparency advantages. |
| Cold-Fill Aseptic Processing Capacity Addition | Brazil's southeastern corridor bottlenecks force 6-month co-packer backlogs, favoring owned manufacturing investments. |
| Mercosur Harmonization Pre-Positioning | Pending regulatory convergence would eliminate dual-SKU inventory requirements and stranded inventory risks across Brazil-Argentina trade flows. |
Research Methodology
The analysis maps carbonated, sugar-free, non-carbonated, and organic product sub-sectors, each validated through category buyers at supermarket chains, convenience store procurement heads, brand managers at multinational beverage portfolios, and supply planners at third-party co-packers. Primary interview insights combined with secondary validation from ANVISA regulatory filings, Brazilian customs trade data, Nielsen retail audit records, and SEC 10-K disclosures from listed beverage conglomerates. Bottom-up volume triangulation across distribution channels and top-down value reconciliation against macroeconomic consumption indicators anchored the analytical framework.
Assumptions held ANVISA caffeine ceiling limits and front-of-pack disclosure mandates constant across the projection horizon, while sugar taxation framework intensity and Mercosur harmonization progress were modeled as scenario variables. Segmentation dimensions included product type, end-user application context, distribution channel economics, and serving size format. CAGRs derived from regression analysis against historical consumption patterns, with forecast inputs incorporating professional end-user adoption curves and e-commerce penetration rates in inflation-stressed economies.
Stress conditions across ethanol-sugar arbitrage volatility, co-packer capacity utilization, and cross-border formulation standardization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with revision triggers tied to regulatory enforcement intensity and botanical certification timeline shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Premium Water Market
Beverages
Ready to Drink Premixes Market
Beverages
US and Canada Tonic Water Market
Beverages
Europe Probiotic Drinks Market
Beverages
United States Smoothie Market
Beverages
Low Fat Drinks Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
North America Cold Pressed Juices Market
Beverages
Collagen Drinks Market
Beverages
China Orange Juice Market
Beverages
United States Soy Beverages Market
Beverages
GCC Coconut Water Market
Beverages
Global Squash Drinks Market
Beverages
Indonesia Bottled Water Market
Beverages
Birch Water Market
Beverages
GCC Juice Market