
 GCC Sports and Energy Drinks Market | 2026-2036
GCC Sports and Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Sports and Energy Drinks Market Intelligence
Multi-can variety bundling is shifting buyer choice across the GCC, as retailers package isotonic and caffeinated variants together to capture trial-driven shoppers. Red Bull GmbH leverages its event-sponsorship infrastructure to sustain premium positioning in motorsport and esports circuits across Dubai and Riyadh. PepsiCo anchors its portfolio through deep convenience-store distribution networks that dominate Saudi Arabia's petrol-station retail channel. Monster Beverage Corporation competes by specializing in higher-caffeine formulations targeted at gaming and nightlife segments in Kuwait and Bahrain.
GCC sports and energy drinks comprise functional beverages formulated with electrolytes, carbohydrates, caffeine, taurine, and amino acids, manufactured through cold-fill aseptic processing to preserve active ingredient stability and designed to replenish fluids, enhance alertness, or support muscle recovery during or after physical exertion. The isotonic segment dominates volume due to its alignment with endurance sports and outdoor training conditions prevalent in Gulf climates, while the caffeinated category captures the highest margin pools from office professionals and night-shift workers seeking sustained alertness. Protein-infused variants represent the fastest-growing product type as gym culture proliferates among Saudi and Emirati consumers pursuing body-composition goals.
Saudi Food and Drug Authority caffeine caps and UAE Ministry of Economy labeling mandates are reshaping formulation transparency and import compliance across the six Gulf states. GSO standards for food additives create a harmonized technical baseline that simplifies cross-border distribution but raises barriers for uncertified entrants. Stakeholders must monitor how MOHAP Dubai's evolving sugar-tax thresholds and Qatar's upcoming front-of-pack warning label requirements will alter portfolio composition and pricing architecture.
Market Dynamics
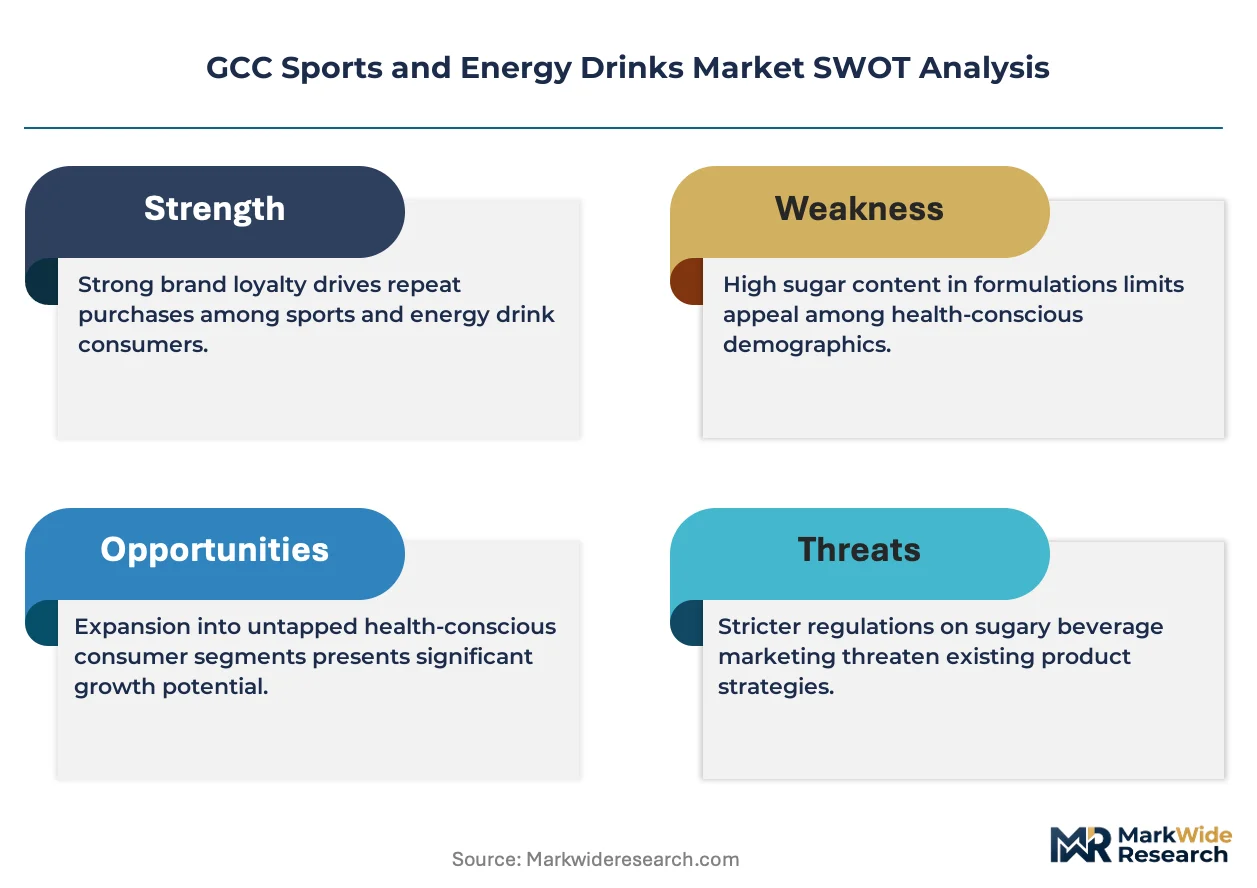
Saudi Food and Drug Authority caffeine caps and UAE Ministry of Economy labeling mandates are compressing formulation freedom across the six Gulf states, forcing manufacturers to rebuild portfolios around compliant ingredient thresholds.
Growth Catalysts
- Youth sports participation:Saudi government wellness initiatives and school athletics programs are expanding the addressable consumer base for isotonic and protein-infused variants.
- SFDA formulation standards:Harmonized technical baselines under GSO food additive standards simplify cross-border distribution and reduce regulatory fragmentation for certified entrants.
- Cold-fill aseptic processing:Advanced manufacturing techniques preserve active ingredient stability in extreme Gulf climates, extending shelf life and reducing spoilage rates.
Market Restraints
- Taurine and caffeine input volatility:Global supply concentration for synthetic caffeine and amino acid precursors exposes margins to petrochemical feedstock price swings.
- Import certification bottlenecks:Uncertified entrants face elevated barriers under GSO standards, consolidating procurement options around established regional distributors.
- Water scarcity premiums:Beverage production in arid Gulf climates carries structurally higher utility costs compared to manufacturing hubs with abundant freshwater access.
Strategic Opportunities
- Qatar front-of-pack labeling:Early compliance with upcoming warning label requirements positions portfolios for premium shelf placement before mandates take effect.
- Protein-infused variants:Gym culture proliferation among Saudi and Emirati consumers pursuing body-composition goals creates white space for functional recovery formulations.
- Petrol-station convenience retail:Deep distribution networks in Saudi Arabia's fuel retail channel enable impulse purchase capture from commuter and long-haul driver segments.
Industry Challenges
- Reformulation timeline compression:Accelerated SFDA compliance deadlines strain R&D capacity as manufacturers simultaneously adjust caffeine content and sugar profiles.
- Temperature-controlled logistics:Extreme ambient heat across Gulf summers degrades product quality during last-mile distribution, requiring capital-intensive cold-chain infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Sports and Energy Drinks Market |
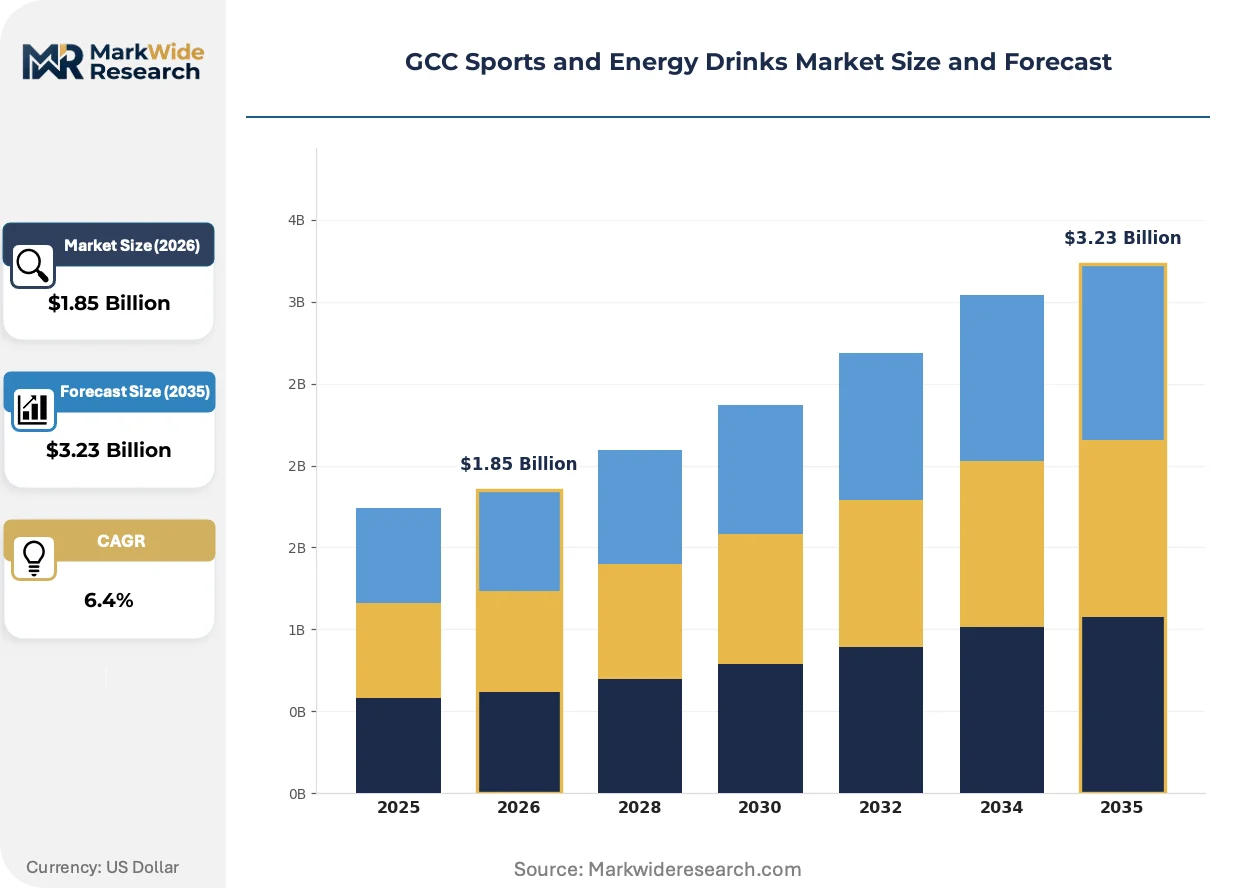
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic, Hypotonic, Caffeinated, Protein Customer Type: Athletes, Fitness Enthusiasts, Casual Consumers, Professionals Distribution Channel: Supermarkets, Online Retail, Gyms, Convenience Stores Flavor Profile: Citrus, Berry, Tropical, Herbal |
| Companies Covered | Red Bull GmbH, Monster Beverage Corporation, PepsiCo, The Coca-Cola Company, Power Horse Energy Drinks, Suntory Holdings, Amway, AJE Group, Britvic, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Sports and Energy Drinks Market Strategic Shifts & Innovations
Formulation transparency and functional specificity are displacing generic energy positioning across GCC retail shelves. Manufacturers now compete on ingredient provenance and physiological outcome claims rather than brand mythology alone.
Electrolyte optimization technology is overtaking standard sodium-potassium blends in isotonic formulations. Endurance athletes and outdoor trainers in Dubai and Riyadh are adopting precision-hydration products calibrated to individual sweat-rate profiles. This shift is compressing market share for one-size-fits-all sports drinks while rewarding brands with diagnostic partnerships and personalized formulation capabilities.
UAE Ministry of Economy sugar-tax thresholds are reshaping portfolio architecture across Emirates retail channels. Beverage manufacturers are accelerating zero-sugar line extensions to maintain price competitiveness as levy brackets tighten. The caffeinated energy segment is most affected, with reformulated variants now dominating Dubai convenience-store placements previously held by full-sugar originals.
Gym-floor vending and fitness-center direct distribution are fragmenting traditional retail dependence in Saudi Arabia. Premium health clubs in Jeddah and Riyadh are installing proprietary cooler networks stocked with protein-infused recovery drinks, bypassing supermarket intermediaries. This channel shift concentrates volume with contract-manufacturing partners capable of white-label production and just-in-time replenishment cycles.
GCC Sports and Energy Drinks Market Segmentation
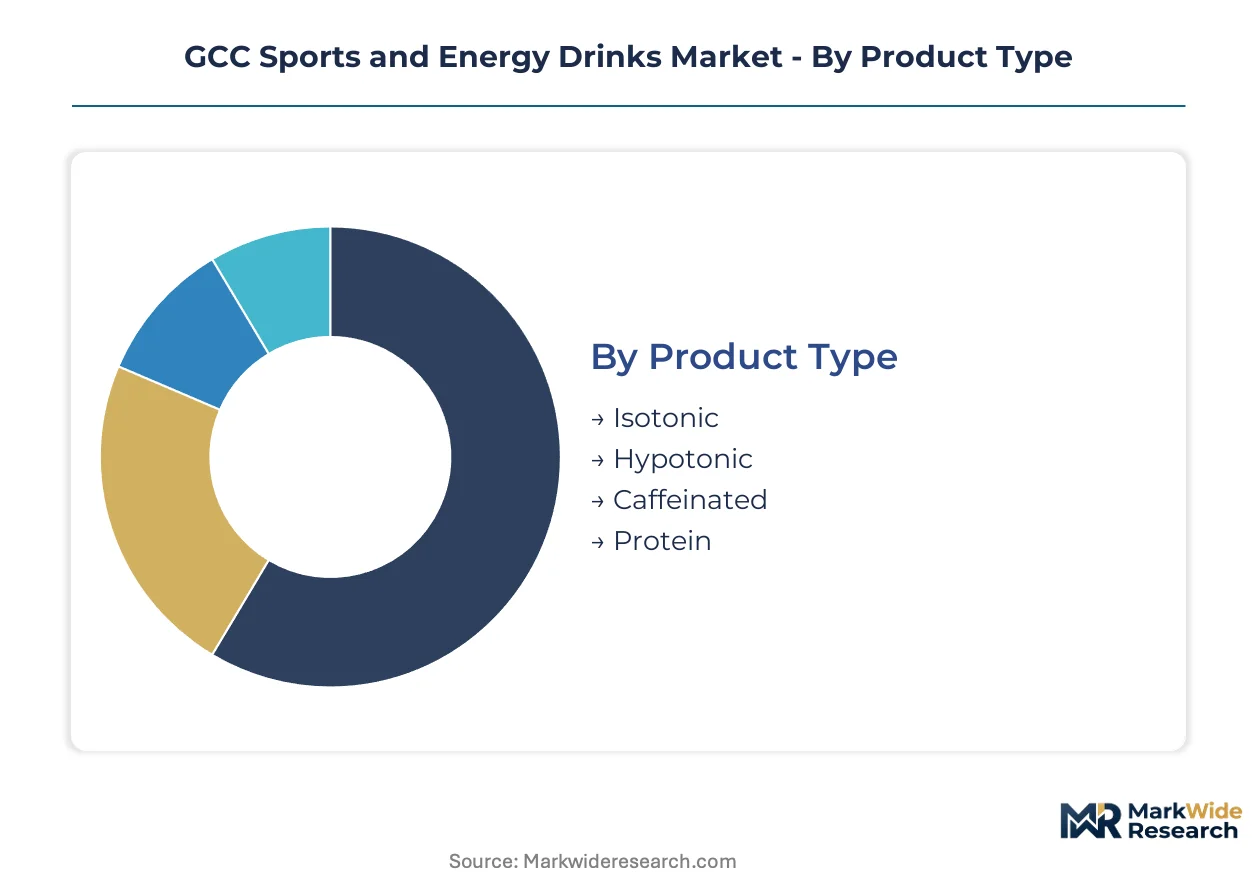
Segmentation in the GCC sports and energy drinks market reveals how hydration needs diverge across climate exposure, activity intensity, and purchase occasion. Manufacturers configure formulation portfolios and channel strategies around these fault lines to capture premium pricing in a region where ambient heat and youth athletic participation reshape consumption patterns.
Product Type:
Buyers differentiate primarily by physiological outcome sought—fluid replacement, alertness enhancement, or muscle recovery—rather than brand loyalty alone.
- Isotonic:Electrolyte-carbohydrate blends with 6-8% sugar concentration mirror plasma osmolality for rapid gastric emptying. Demand concentrates among endurance athletes training in Dubai and Riyadh outdoor conditions, where sweat rates exceed 2 liters hourly and sodium losses drive formulation specificity.
- Protein:Whey and plant-based amino acid infusions target post-workout muscle protein synthesis. Gym-floor distribution in Jeddah and Abu Dhabi premium health clubs accelerates trial, with Saudi body-composition goals pushing recovery-oriented purchasing fastest.
- Caffeinated:Taurine-adrenaline blends deliver alertness for night-shift workers and gaming segments.
- Hypotonic:Lower solute concentration prioritizes rapid hydration over energy delivery for short-duration exertion.
Volume sits with Isotonic; growth tilts toward Protein.
Customer Type:
Purchase frequency and price tolerance separate these groups more than demographic labels alone.
- Fitness Enthusiasts:Daily gym-goers with subscription-based supplement regimens and brand switching propensity. Saudi Arabia's proliferating fitness culture and government wellness subsidies expand this cohort fastest, with Riyadh and Jeddah club memberships driving recurring isotonic and protein volume.
- Professionals:Office workers and long-haul drivers seeking sustained alertness through caffeinated variants. Kuwait and Bahrain nightlife and esports venues concentrate demand for higher-caffeine formulations, with petrol-station retail capturing impulse commuter purchases.
- Athletes:Competitive and school-sports participants with coach-influenced brand selection.
- Casual Consumers:Occasional recreational users with low formulation literacy and price sensitivity.
Revenue concentrates with Professionals; expansion tilts most steeply toward Fitness Enthusiasts.
Distribution Channel:
Channel choice determines margin capture and brand positioning more than pure volume throughput.
- Convenience Stores:Petrol-station and urban corner-store networks dominate impulse caffeinated energy drink sales. Saudi Arabia's fuel retail channel, controlled by consolidated operators, grants shelf access to established portfolios while blocking smaller entrants.
- Gyms:Direct cooler placement and vending bypass supermarket intermediaries entirely. White-label contract manufacturing enables just-in-time replenishment for UAE and Saudi premium health clubs seeking proprietary recovery drink lines.
- Supermarkets:Multi-can bundling and promotional pricing capture household stock-up behavior.
- Online Retail:Subscription models and bulk purchasing attract price-sensitive repeat buyers.
Transaction density peaks at Convenience Stores; margin expansion shifts toward Gyms.
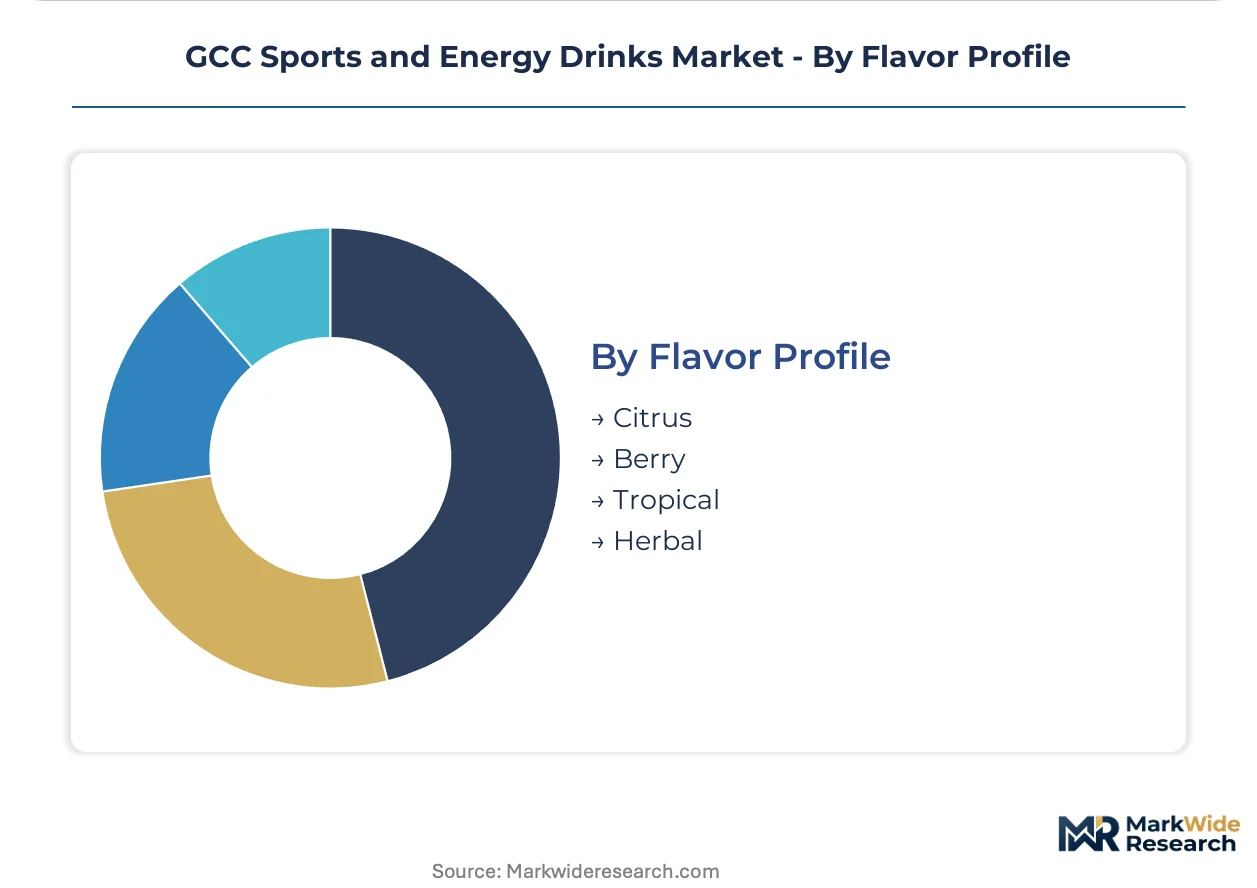
Flavor Profile:
Regional palate preference and perceived functional association drive selection more than novelty seeking.
- Citrus:Lemon-lime and orange variants dominate isotonic formulations due to established sports-drink association and thirst-quenching perception. UAE and Saudi retail shelf space allocation favors these SKUs for their cross-generational acceptance.
- Berry:Acai and mixed berry profiles align with antioxidant health claims and female-skewing purchasing. Bahrain and Qatar premium supermarket channels reward these variants with preferential placement.
- Tropical:Mango and pineapple formulations target expatriate demographics and seasonal limited editions.
- Herbal:Ginger and botanical infusions serve wellness-positioned niches seeking caffeine alternatives.
Baseline volume rests with Citrus; flavor innovation momentum gathers fastest around Berry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in the UAE and Saudi Arabia, yet consumption growth outpaces domestic production across every Gulf state. Import dependency for active ingredients and packaging materials shapes procurement strategies throughout the region.
Saudi Arabia
Youth sports participation and government wellness initiatives are expanding the addressable consumer base for isotonic and protein-infused variants. The Saudi Food and Drug Authority is tightening caffeine content caps and labeling requirements for all functional beverages. Riyadh and Jeddah health clubs are installing proprietary cooler networks stocked with recovery drinks, bypassing traditional retail intermediaries entirely.
United Arab Emirates
Office professionals and night-shift workers in Dubai sustain demand for higher-caffeine formulations targeting sustained alertness. The UAE Ministry of Economy sugar-tax thresholds are accelerating zero-sugar line extensions across Emirates retail channels. Dubai convenience-store placements now favor reformulated variants where full-sugar originals previously dominated shelf space.
Kuwait
Gaming and nightlife segments drive consumption of specialized higher-caffeine energy formulations. The country's national food safety regulator maintains alignment with GSO standards for food additives, simplifying import compliance for certified entrants. Kuwait City retail clusters concentrate volume for premium-positioned variants targeting expatriate demographics.
Qatar
Upcoming front-of-pack warning label requirements are reshaping portfolio composition ahead of mandate implementation. The national standards body enforces harmonized technical baselines that raise barriers for uncertified market entrants. Doha premium supermarket channels reward berry-profile variants with preferential placement due to antioxidant health claim alignment.
Bahrain
Petrol-station retail and urban convenience networks capture impulse commuter purchases from long-haul driver segments. The national food and drug regulator enforces labeling transparency mandates consistent with broader Gulf Cooperation Council harmonization. Manama retail corridors concentrate trial-driven shoppers responding to multi-can variety bundling of isotonic and caffeinated variants.
GCC Sports and Energy Drinks Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the GCC functional beverage space. Consolidated distribution networks in Saudi Arabia's fuel retail channel grant shelf access to established portfolios while blocking smaller entrants. Three archetypes dominate: beverage multinationals leveraging global brand equity, regional distributors controlling last-mile access, and contract manufacturers serving white-label gym-floor placements. Capacity expansion and portfolio diversification represent the dominant competitive moves as manufacturers rebuild formulations around tightening regulatory thresholds.
Among multinational beverage conglomerates, Red Bull GmbH and PepsiCo occupy anchor positions representing contrasting strategic postures. Monster Beverage Corporation exemplifies the pure-play energy specialist archetype competing through formulation intensity rather than portfolio breadth. These three entities collectively illustrate how global brand infrastructure, deep convenience-store distribution, and segment-specific targeting fragment competitive advantage across the Gulf states.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Monster Beverage Corporation |
| PepsiCo |
| The Coca-Cola Company |
| Power Horse Energy Drinks |
| Suntory Holdings |
| Amway |
| AJE Group |
| Britvic |
| Others |
Cost & Logistics Intelligence
Formulation chemist clusters in Switzerland and Germany command premium compensation that widens the spread between mass-market isotonic brands and precision-hydration specialists sold through Dubai premium fitness channels. Labor-cost differentials in active ingredient synthesis propagate directly into retail pricing tiers across Gulf Cooperation Council markets.
Pricing Analysis
Margin tightening in caffeinated energy variants reflects UAE Ministry of Economy sugar-tax thresholds forcing accelerated zero-sugar reformulation. Three-tier pricing structure across premium, standard, and economy levels separates diagnostic-partnership isotonic brands from commodity electrolyte blends and private-label petrol-station offerings. Price differentiation hinges on certification grade under GSO standards and cold-fill aseptic processing capability. Impulse purchasers at Saudi fuel retail channels exhibit highest price sensitivity; gym-floor subscribers in Riyadh premium health clubs show lowest elasticity.
Supply Chain Analysis
Temperature-controlled freight costs from European formulation centers to Jeddah and Dubai ports consume disproportionate working capital versus ambient-stable beverage categories. Synthetic caffeine production concentrates in China and India; taurine precursor synthesis anchors in Germany and Japan. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade amino acid inputs. Distribution runs through consolidated Saudi fuel-retail operators and UAE convenience-store networks that block uncertified entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC sports and energy drinks represent a consolidation play as SFDA caffeine caps and labeling mandates force subscale manufacturers toward exit or acquisition. Regulatory compliance timelines compress faster than R&D budgets can absorb.
For Market Incumbents: Anchor shelf position in Saudi petrol-station channels through exclusive cooler placement agreements with consolidated fuel-retail operators. Deepen backward integration into cold-fill aseptic processing capacity within the UAE to reduce freight exposure and capture margin from temperature-sensitive protein-infused variants. The threat of white-label contract manufacturers serving gym-floor direct distribution demands preemptive proprietary cooler network expansion in Riyadh and Jeddah premium health clubs. For New Entrants and Emerging Players: Qatar's upcoming front-of-pack warning label requirements open a window for early-compliant portfolios to secure premium supermarket placement before mandates take effect. Target protein-infused recovery formulations distributed through gym-floor vending in Saudi Arabia's proliferating fitness culture, where subscription-based replenishment cycles bypass entrenched retail intermediaries. Pursue white-label manufacturing partnerships with UAE contract facilities capable of just-in-time production for health club proprietary lines. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with GSO-certified cold-fill capacity and established relationships with Saudi fitness chains. Long-term viability rests on regulatory compliance infrastructure rather than brand equity alone. Monitor SFDA enforcement patterns on caffeine content caps as the inflection signal for portfolio restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Sugar Line Extension | UAE sugar-tax thresholds force reformulation to maintain price competitiveness in Dubai convenience channels. |
| Gym-Floor Direct Distribution | Proprietary cooler networks in Riyadh health clubs bypass supermarket intermediaries and capture subscription volume. |
| Backward Integration into Aseptic Processing | In-house cold-fill capacity reduces temperature-controlled logistics costs and extends shelf life in Gulf climates. |
| GSO Certification Investment | Harmonized standards compliance unlocks cross-border distribution across all six Gulf states from single production base. |
| Precision-Hydration Diagnostic Partnerships | Sweat-rate profiling technology differentiates isotonic offerings from commodity electrolyte blends in Dubai endurance segments. |
Research Approach
Document review covered customs records, GSO standards documentation, and SFDA regulatory filings, complemented by interviews with beverage formulation chemists, Saudi health club procurement managers, UAE convenience-store category buyers, and cold-chain logistics operators. Secondary validation drew from trade data, industry association reports, and retail audit databases. Bottom-up volume modeling triangulated against top-down market sizing from production capacity and import flows.
Historical consumption patterns cross-referenced against panel input from distribution channel partners informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, customer archetype, distribution channel, and flavor profile, with additional granularity on regulatory compliance tier. CAGRs derived from weighted average of trend extrapolation and driver-based elasticity modeling, incorporating gym membership growth rates and petrol-station retail expansion plans as industry-specific inputs.
The model assumes a particular technology adoption path for electrolyte optimization and personalized hydration diagnostics; alternative pathways for precision-hydration sensor integration would alter the outlook for isotonic segment growth. Forecasts reflect documented assumptions on regulatory enforcement timing and consumer formulation literacy evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Plant Based Protein Beverages Market
Beverages
Nitro-Infused Beverages Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Peanut Oil Market
Beverages
Asia Pacific Fermented Drinks Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Superfood Infused Beverages Market
Beverages
Fiber Fortified Beverages Market
Beverages
US and Canada Premium Bottled Water Market
Beverages
Global Vinegar Market
Beverages
Packaged Milkshake Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
Japan Kombucha Market
Beverages
Probiotic Beverage Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Health Drinks Market