
 Victorian Jars Market | 2026-2036
Victorian Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Victorian Jars Market Analytics
Aftermarket service revenue from jar lid replacement and seal refurbishment is tilting margin pools away from one-time product sales toward recurring consumables. The Glasshouse leverages its heritage positioning to command premium pricing in decorative jar segments. Victorian Glassworks sustains manufacturing scale through backward integration into raw glass production. Ball Corporation anchors North American distribution through deep channel relationships with mass retailers.
Victorian jars are cylindrical or square glass and ceramic containers with threaded necks designed for hermetic sealing, typically manufactured through blow-and-blow or press-and-blow forming with soda-lime silica composition and metal lug or continuous thread closures. Their primary purpose spans domestic food preservation, commercial condiment packaging, and apothecary storage where oxygen exclusion and visual product display prove essential. Sealed jars and food storage jars concentrate volume demand among households practicing home preservation, while decorative jars capture margin pools through giftware and hospitality styling applications. Airtight feature specifications are concentrating procurement attention as restaurants and catering services prioritize food safety compliance.
The EU F-Gas Regulation and REACH framework govern seal gasket materials and chemical composition transparency for glass containers entering European commerce, while FDA standards in the United States dictate lead-free certification for food-contact surfaces. These regulatory layers elevate compliance costs for ceramic producers but simultaneously create market access barriers that favor established manufacturers with in-house testing capabilities. Stakeholders must monitor evolving extended producer responsibility mandates that could reshape packaging recovery economics across key demand centers.
Market Dynamics
The Victorian jars market is experiencing structural pressure from extended producer responsibility mandates that are reconfiguring packaging recovery economics and elevating compliance costs for smaller ceramic producers.
Growth Catalysts
- EU F-Gas Regulation:REACH compliance requirements for seal gasket materials are creating market access barriers that favor established manufacturers with in-house testing capabilities.
- Home canning resurgence:Artisanal food preservation practices among households are expanding demand for reusable glass vessels with hermetic sealing performance.
- Germany's preserving culture:Traditional domestic food preservation intersects with premium kitchenware retail concentration, driving premium jar procurement.
Market Restraints
- Soda-lime silica input volatility:Raw glass production costs fluctuate with energy pricing, compressing margins for non-integrated manufacturers.
- Substitution by polymer containers:Lightweight plastic alternatives threaten volume demand in commercial condiment packaging applications.
- REACH certification friction:Chemical composition transparency requirements delay market entry for new ceramic producers.
Strategic Opportunities
- Restaurant food safety compliance:Airtight specification procurement from catering services creates premium pricing power for certified suppliers.
- Apothecary storage revival:Visual product display requirements in wellness retail are opening decorative jar segments.
- Seal refurbishment services:Aftermarket revenue from lid replacement is tilting margin pools toward recurring consumables.
Industry Challenges
- Blow-and-blow forming expertise scarcity:Skilled technician shortages constrain capacity expansion for heritage glasshouses.
- Dual certification timelines:Simultaneous FDA lead-free and EU REACH compliance extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Victorian Jars Market |
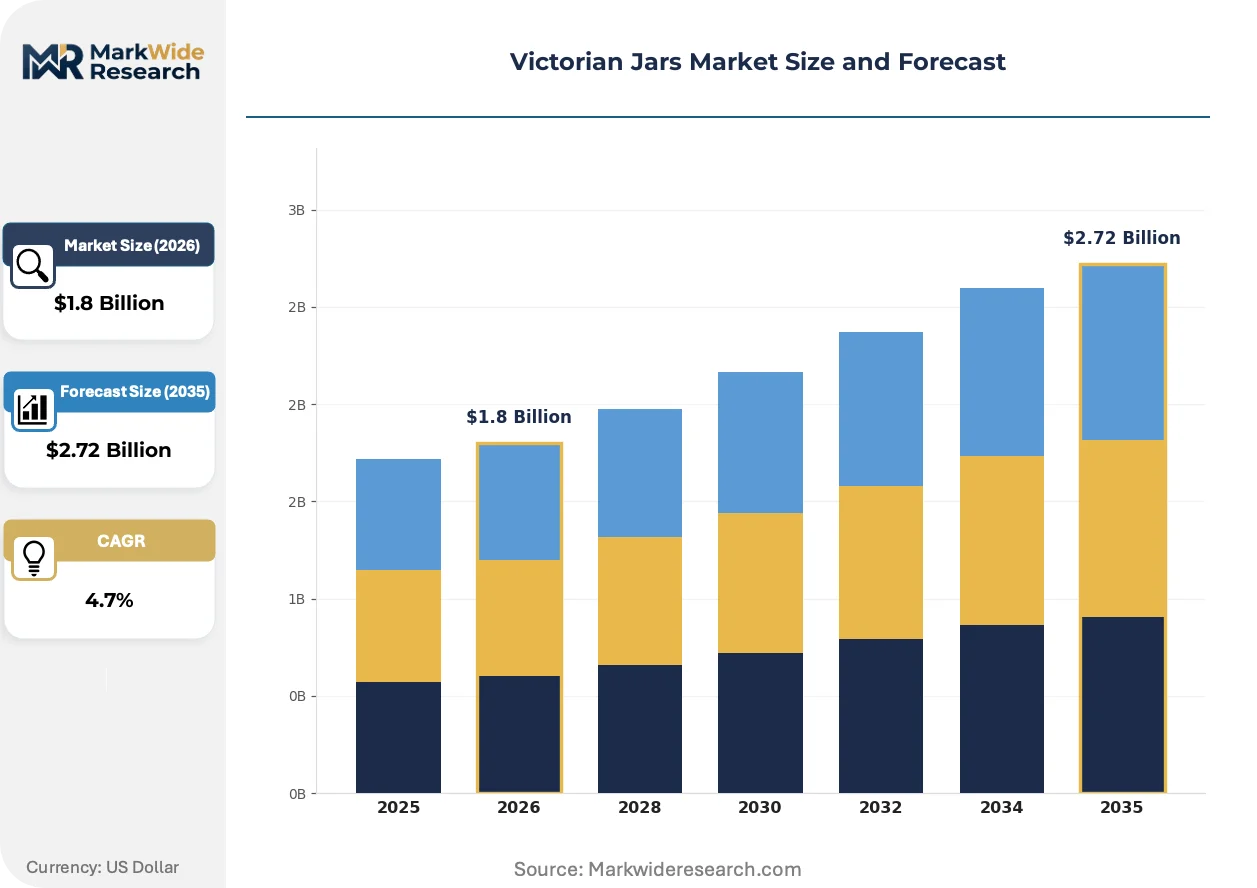
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealed Jars, Decorative Jars, Pharmaceutical Jars, Food Storage Jars Material: Glass, Ceramic, Plastic, Metal Feature: Lead-Free, Reusable, Stackable, Airtight End User: Households, Restaurants, Retail Stores, Catering Services |
| Companies Covered | The Glasshouse, Victorian Glassworks, Libbey, Anchor Hocking, Ball Corporation, PauPack, Bormioli Rocco, Tzanet, Einkochwelt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Victorian Jars Market Evolving Landscape
Material science advances and regulatory transparency mandates are reshaping how Victorian jar manufacturers compete on seal integrity and chemical safety credentials.
Metal lug closures are migrating from traditional tinplate toward stainless steel and coated aluminum alloys. Commercial condiment packagers are adopting these corrosion-resistant alternatives to extend shelf stability. The transition is compressing demand for conventional tin-based sealing systems while elevating raw material specifications across supplier networks.
REACH framework amendments are tightening disclosure requirements for per- and polyfluoroalkyl substances in seal gasket materials. European manufacturers must now document full chemical composition chains through extended supply tiers. Food-contact jar segments are responding by accelerating substitution toward silicone and natural rubber alternatives.
Restaurants and catering services are consolidating procurement around certified airtight specifications rather than decorative styling. Distributor relationships with hospitality supply chains are displacing traditional retail channels for volume jar purchases. Germany and France exhibit the most pronounced concentration of specification-driven buying.
Victorian Jars Market Segmentation
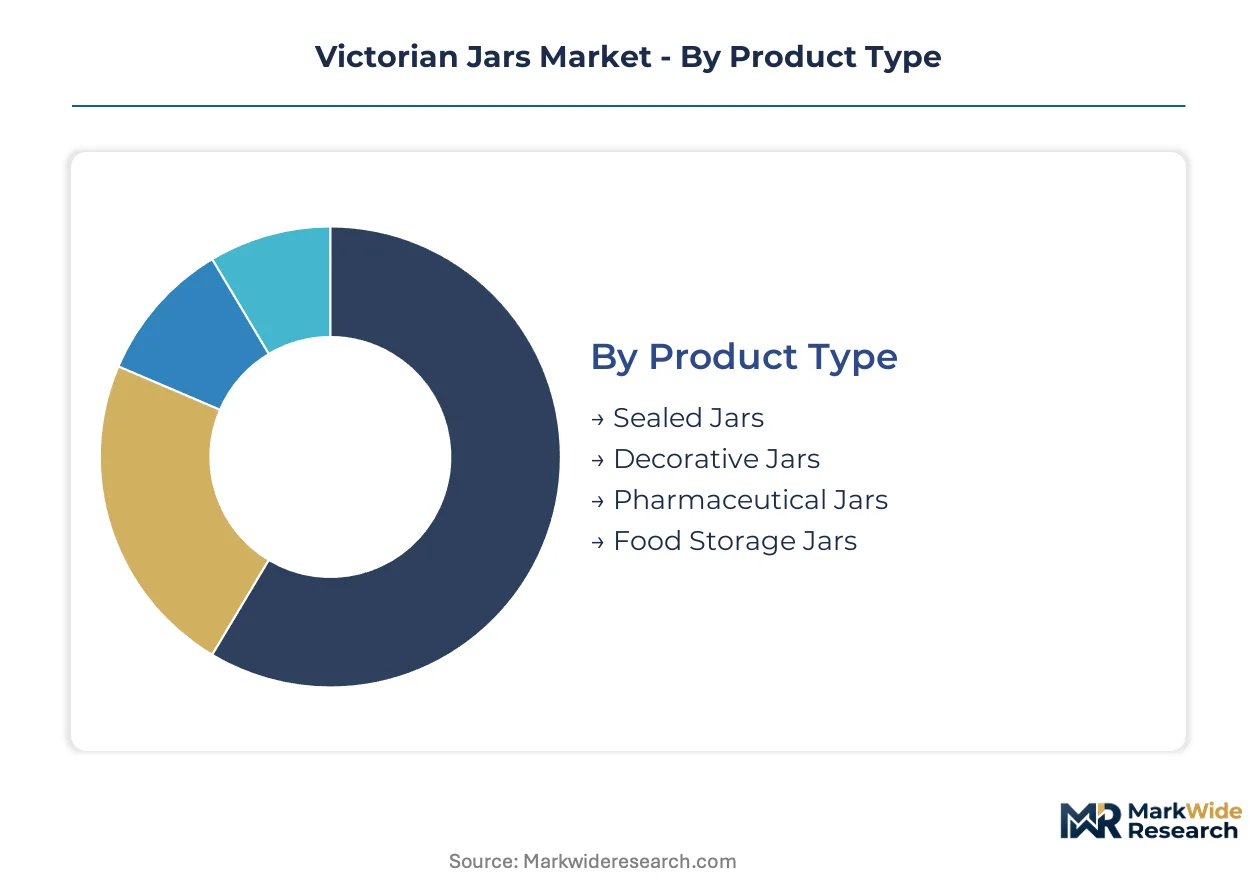
Victorian jar procurement patterns diverge sharply across use cases, with food preservation applications demanding hermetic performance while decorative segments prioritize visual aesthetics. Material selection and feature specifications create distinct margin tiers that reshape manufacturer portfolio strategies.
Product Type:
Replacement cycles vary from seasonal decorative refreshes to decade-long kitchen staples, creating divergent revenue recognition patterns across the portfolio.
- Sealed Jars:Engineered with continuous thread metal closures and soda-lime silica walls for vacuum-compatible hermetic sealing. Home canning households in Germany and Austria drive repeat procurement through lid wear and seasonal batch volumes.
- Decorative Jars:Ornamented glass with embossed patterns and colored tints prioritizes shelf presence over seal integrity. Hospitality styling budgets in France and boutique retail giftware channels concentrate demand for premium decorative specimens.
- Pharmaceutical Jars:Amber-tinted borosilicate with child-resistant closures meets apothecary storage protocols.
- Food Storage Jars:Wide-mouth configurations with silicone gasket systems serve commercial kitchen ingredient organization.
Sealed jars anchor the volume base while decorative jars gain share at the steepest rate.
Material:
Cost structures stratify sharply, with ceramic commanding premium positioning against commoditized polymer alternatives.
- Glass:Soda-lime silica dominates through blow-and-blow forming scalability, though borosilicate variants penetrate temperature-shock applications. EU F-Gas Regulation compliance costs favor integrated manufacturers with captive raw glass production.
- Ceramic:Glazed stoneware and porcelain command artisanal price premiums through heritage positioning. REACH certification friction delays market entry for new ceramic producers but protects incumbent margin pools.
- Plastic:Polypropylene and PET threaten glass volume in commercial condiment packaging through lightweight logistics economics.
- Metal:Tinplate and aluminum alloys serve specialized industrial containment with corrosion-resistant specifications.
Glass retains the dominant volume position while ceramic climbs fastest in value terms.
Feature:
Regulatory mandates and safety specifications are concentrating procurement attention on certified feature bundles rather than aesthetic differentiation.
- Lead-Free:FDA certification for food-contact surfaces and EU REACH compliance for chemical transparency create dual certification requirements. Restaurants and catering services in France now mandate lead-free documentation for all glassware procurement.
- Airtight:Silicone and natural rubber gasket systems with metal lug closures satisfy food safety compliance in hospitality supply chains. Germany's commercial kitchen equipment distributors specify airtight certification as a mandatory procurement filter.
- Reusable:Extended producer responsibility mandates elevate lifecycle value calculations in sustainability-conscious retail channels.
- Stackable:Modular geometry optimization serves space-constrained urban household storage and commercial kitchen organization.
Lead-free specifications dominate procurement volumes while airtight certification expands most quickly as a mandatory requirement.
End User:
Customer concentration patterns split between fragmented household demand and consolidated hospitality procurement with diverging price sensitivity profiles.
- Households:Seasonal home canning practitioners and kitchenware enthusiasts generate recurring demand through breakage replacement and collection expansion. Traditional preserving culture in rural Germany and Austria sustains above-average per-capita consumption.
- Restaurants:Front-of-house condiment presentation and back-of-house ingredient storage create dual specification requirements. Certified airtight procurement from hospitality supply chains is displacing traditional retail channels for volume jar purchases.
- Retail Stores:Private-label jar programs for preserves and sauces drive commercial condiment packaging volumes.
- Catering Services:Mobile food safety compliance demands stackable, hermetic transport containers with tamper-evident features.
Households anchor the volume base while restaurants gain share at the steepest rate through specification-driven consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household buyers in Germany absorb premium pricing with minimal elasticity, while commercial purchasers in France and the United States negotiate aggressively on volume contracts. This demand-side divergence shapes manufacturer pricing power across regional markets.
Germany
Traditional preserving culture in Bavaria and rural Baden-Württemberg sustains above-average per-capita consumption of hermetic glass vessels. The EU F-Gas Regulation and REACH framework govern seal gasket materials entering German commerce, elevating compliance costs for ceramic imports. Stuttgart's premium kitchenware retail cluster concentrates procurement of heritage-positioned jar collections.
France
Hospitality styling budgets in Paris and Provence-Alpes-Côte d'Azur drive decorative jar demand for boutique hotel amenities and restaurant condiment presentation. ANSM enforces chemical composition transparency for food-contact surfaces alongside EU REACH mandates. Lyon-based commercial kitchen equipment distributors now mandate airtight certification as a mandatory procurement filter.
United States
Seasonal home canning practitioners in the Midwest and Pacific Northwest generate recurring replacement demand through lid wear and breakage. FDA standards dictate lead-free certification for food-contact glass surfaces, creating dual compliance timelines with EU requirements. Ball Corporation anchors mass retail distribution through deep channel relationships with national grocery chains.
United Kingdom
Artisanal food preservation trends in London and the Southeast expand demand for reusable vessels with visual display appeal. The UK's post-Brexit chemical regulatory framework maintains REACH alignment for seal materials while adding domestic notification requirements. Cornwall's heritage glassworking tradition supports small-batch production of embossed decorative specimens.
Austria
Rural household preserving practices in Lower Austria and Styria mirror German consumption patterns with strong seasonal batch volumes. ECHA's extended supply chain disclosure rules for per- and polyfluoroalkyl substances accelerate substitution toward silicone gasket alternatives. Vienna's specialty retail corridor concentrates premium jar procurement for giftware and wedding registry segments.
Victorian Jars Market Competitive Landscape
Capability concentration sits with heritage glasshouses possessing blow-and-blow forming expertise; scale advantage sits with integrated manufacturers with captive raw glass production. The vendor base stratifies into three tiers: artisanal specialists commanding premium positioning, mid-scale regional fabricators serving private-label programs, and mass producers anchoring retail distribution. Dominant competitive moves include backward integration into soda-lime silica production and strategic partnerships with hospitality supply chains.
Within the heritage-positioned tier, The Glasshouse and Victorian Glassworks exemplify archetypes of premium pricing power through brand equity and manufacturing integration respectively. Ball Corporation occupies a position at the scale-driven end, representing mass-market distribution strength through retail channel depth. These three anchors illustrate how competitive positioning diverges between aesthetic differentiation and operational scale.
| Leading Market Players |
|---|
| The Glasshouse |
| Victorian Glassworks |
| Libbey |
| Anchor Hocking |
| Ball Corporation |
| PauPack |
| Bormioli Rocco |
| Tzanet |
| Einkochwelt |
| Others |
Value Network & Pricing Analysis
Stuttgart's premium kitchenware retail cluster anchors European glass jar manufacturing capacity, concentrating blow-and-blow forming expertise that commands 15-20% pricing premiums over mass-market alternatives. Energy-intensive soda-lime silica production in Germany's industrial corridor ties jar pricing directly to natural gas input volatility, compressing margins for non-integrated fabricators while rewarding Victorian Glassworks and Ball Corporation with captive raw glass supply.
Pricing Analysis
Aftermarket seal refurbishment and lid replacement revenue streams now drive lifetime customer value beyond initial vessel sales. Three-tier pricing structure across heritage artisanal, certified commercial, and economy private-label levels separates The Glasshouse's embossed decorative specimens from Einkochwelt's mass retail programs. Cost compression in economy tiers intensifies because polypropylene substitution threatens condiment packaging volumes. Restaurants and catering services exhibit lowest price sensitivity due to food safety compliance mandates, while seasonal household canning practitioners negotiate aggressively on volume.
Supply Chain Analysis
Extended payment terms from hospitality distributors now finance 60-90 day working capital cycles for mid-tier fabricators. Supply concentrates in Germany, France, and the United States through heritage glasshouses and integrated mass producers. Raw material dependencies center on soda-lime silica batch, stainless steel closure alloys, and silicone gasket formulations. Single-source vulnerability runs through Italian borosilicate specialty glass imports for pharmaceutical amber variants. Distribution runs through commercial kitchen equipment distributors in Lyon and Stuttgart, displacing traditional retail channels for certified airtight procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Victorian jars market sits at a high-growth inflection as EU REACH amendments on per- and polyfluoroalkyl substances force gasket material substitution toward silicone and natural rubber alternatives, disrupting incumbent seal chemistry supply relationships.
For Market Incumbents: Pre-empt polymer container substitution by accelerating backward integration into soda-lime silica production and securing exclusive hospitality supply chain partnerships in France and Germany. Defend margin pools through in-house REACH testing capabilities that delay new ceramic entrant market access. Prioritize certification investment in dual FDA-EU compliance to compress rival product launch timelines. For New Entrants and Emerging Players: Establish a beachhead in apothecary storage and wellness retail decorative segments where heritage brand equity carries weaker pricing power. Target Austria and the United Kingdom's post-Brexit notification requirements as regulatory friction protects early movers. Deploy direct-to-consumer channels for wedding registry and giftware segments to bypass consolidated distributor gatekeeping. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because extended producer responsibility mandates will reshape packaging recovery economics and eliminate sub-scale ceramic producers incapable of compliance cost absorption. Target acquisition profiles center on mid-scale regional fabricators with private-label relationships and captive testing infrastructure. Watch for EU F-Gas Regulation enforcement intensity as the signal indicating margin compression timing for non-integrated competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Glass Production | Victorian Glassworks captures margin pools through captive soda-lime silica supply against energy price volatility. |
| REACH Compliance Certification Investment | In-house testing capabilities create market access barriers protecting incumbent ceramic producers from new entrants. |
| Hospitality Supply Chain Partnership | Lyon-based distributors now mandate airtight certification, displacing traditional retail procurement channels. |
| Seal Refurbishment Service Launch | Recurring lid replacement revenue tilts margin pools away from one-time vessel sales toward consumables. |
| Silicone Gasket Material Transition | Substitution away from per- and polyfluoroalkyl substances satisfies EU framework amendments ahead of enforcement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with glasshouse production managers, premium kitchenware retail buyers, hospitality procurement officers, and seal gasket material suppliers; and secondary validation through EU ECHA substance databases, FDA food-contact surface filings, customs trade records for soda-lime silica batch imports, and hospitality supply chain distributor catalogs. Bottom-up vessel volume estimates triangulated against top-down market value reconstructions across product type, material grade, feature certification, and end-user segments.
Forecast inputs incorporated hermetic sealing performance requirements, extended producer responsibility mandate implementation timelines, and hospitality sector procurement consolidation patterns. Modeled dimensions spanned sealed versus decorative versus pharmaceutical jar categories, glass and ceramic material tiers, lead-free and airtight feature bundles, and household versus restaurant versus catering end-user splits. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and substitution elasticity parameters.
Stress conditions across natural gas input pricing, EU F-Gas Regulation enforcement intensity, and polymer container substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on preserving culture persistence in German-speaking markets and hospitality styling budget resilience. Macroeconomic contraction, accelerated REACH amendment timelines, or breakthrough biodegradable polymer alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Sparkling Water Machine Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Global Bottled Water Market
Beverages
Crystal Boba Market
Beverages
Chocolate Malt Drink Market
Beverages
Europe Bottled Water Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Double Valve Moka Pots Market
Beverages
Water Bottle Market
Beverages
Global Soda Maker Market
Beverages
NFC JUICE Market
Beverages
Spring Water Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
China Orange Juice Market