
 Caffeine Mint Market | 2026-2036
Caffeine Mint Market Size, Share, and Industry Trends Forecast 2026-2036
Caffeine Mint Market Insights
Aftermarket wellness subscription revenue is rewriting how mint brands monetize repeat usage. Viter Energy leverages direct-to-consumer bundling to sustain recurring purchase cycles. Neuro anchors its position through nootropic positioning that differentiates beyond conventional confectionery. Perfetti Van Melle competes through shelf-space dominance in mass retail channels across multiple continents.
Caffeine mints are compressed confectionery products typically containing synthetic or natural caffeine at dosages between 5 mg and 100 mg per unit, formulated with sugar alcohols or natural sweeteners to deliver rapid oral absorption and alertness enhancement without liquid consumption. Energy Mints command the dominant margin pool due to functional premium pricing, while Sugar-Free Mints attract health-conscious expansion through dental-friendly formulations. Online Retailers represent the fastest-growing distribution vector as subscription algorithms reduce customer acquisition costs for niche brands.
The FDA regulates caffeine content and labeling claims in the United States, while the EFSA sets maximum caffeine thresholds for food supplements in Europe, and Japan's Ministry of Health, Labour and Welfare monitors stimulant additive thresholds through Food Sanitation Act enforcement. These frameworks compel reformulation investments and restrict marketing language around cognitive enhancement. Stakeholders must monitor evolving caffeine limits in functional foods and anticipate which regulatory jurisdiction will next tighten novel delivery format classifications.
Market Dynamics
Functional confectionery is hybridizing with pharmaceutical-grade delivery systems as manufacturers compress caffeine absorption curves to compete with energy drinks and nootropic beverages. This convergence forces reformulation investments across synthetic caffeine, natural extract sourcing, and bioavailability enhancement technologies.
Growth Catalysts
- Remote work normalization:Home office professionals in Germany and Japan sustain demand for discrete alertness products that replace coffee rituals without equipment or spills.
- EFSA caffeine thresholds:European regulatory clarity on maximum dosages for food supplements enables standardized product development and cross-border distribution.
- Sugar alcohol innovation:Xylitol and erythritol formulations expand addressable markets to diabetic consumers and dental-conscious buyers seeking functional benefits without glycemic impact.
Market Restraints
- Synthetic caffeine supply concentration:Production of pharmaceutical-grade caffeine concentrates in Chinese and Indian chemical manufacturing clusters creates input vulnerability for formulated mint brands.
- FDA GRAS notification requirements:Novel delivery formats combining caffeine with L-theanine or other nootropics trigger extended safety review timelines before market entry.
- Energy drink substitution:Ready-to-drink functional beverages with established distribution infrastructure and flavor familiarity capture overlapping use cases in convenience retail.
Strategic Opportunities
- Brazilian urban corridors:São Paulo and Rio de Janeiro office density supports premium functional confectionery adoption with limited local specialized competition.
- Subscription algorithm optimization:Direct-to-consumer platforms leveraging consumption-pattern data reduce customer acquisition costs for repeat-purchase mint formulations.
- ISO 22000 certification:Food safety management system adoption enables entry into institutional procurement channels including corporate wellness programs and airline hospitality supply.
Industry Challenges
- Pharmaceutical-grade caffeine sourcing:Qualifying alternative suppliers to reduce concentration risk requires 18-24 month validation cycles including stability testing and impurity profiling.
- Cross-jurisdiction label compliance:Simultaneous adherence to FDA disclosure rules, EFSA health claim restrictions, and Japan Food Sanitation Act additive thresholds fragments packaging standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caffeine Mint Market |
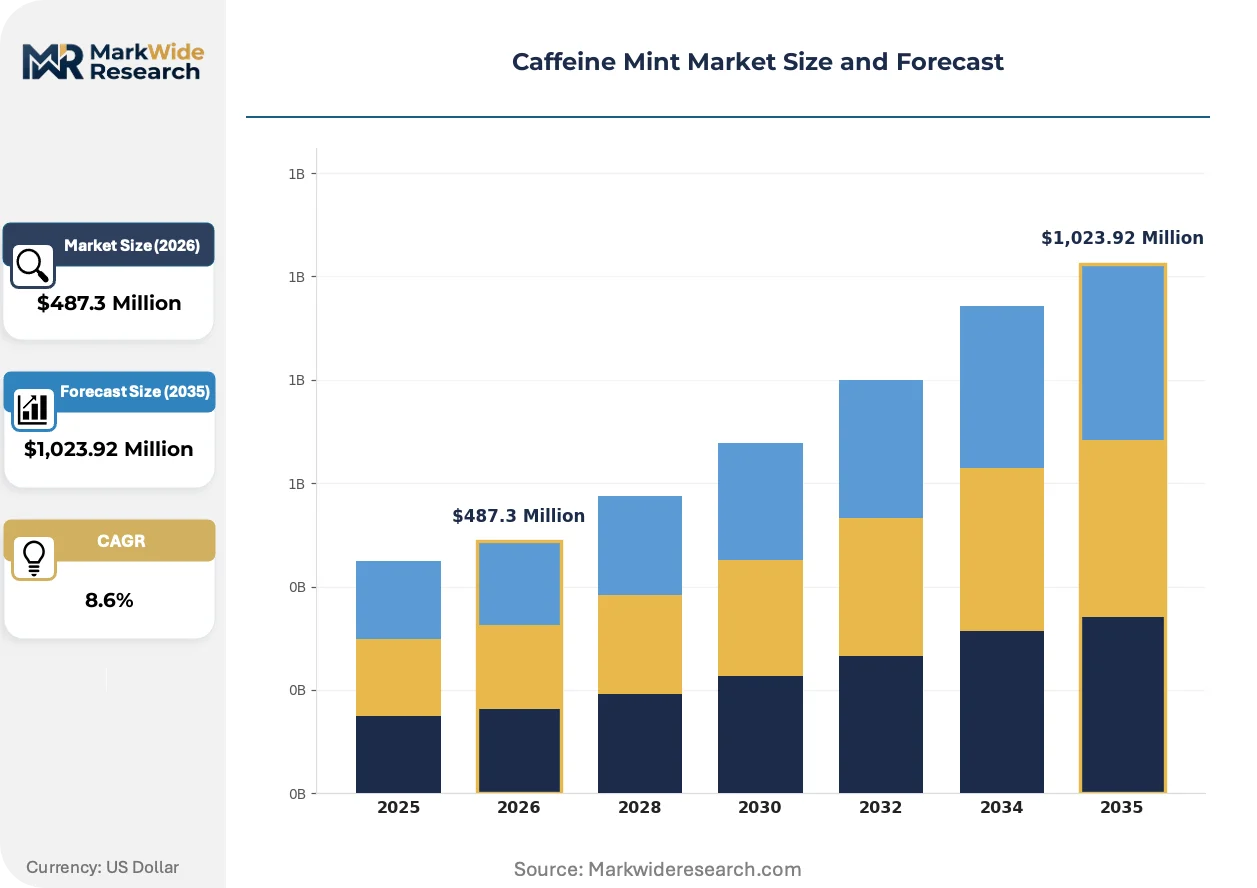
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breath Fresheners, Energy Mints, Chewing Mints, Sugar-Free Mints, Organic Mints Flavor Variety: Spearmint, Peppermint, Wintergreen, Citrus Blend, Herbal Mix Distribution Channel: Convenience Stores, Pharmacies, Online Retailers, Supermarkets, Specialty Boutiques Customer Segment: Young Adults, Working Professionals, Students, Fitness Enthusiasts, Travelers |
| Companies Covered | Viter Energy, Neuro, FOOSH Energy Mints, Rally Energy, Penguin Caffeinated Mints, Peppersmith, The Hershey Company, Mars, Perfetti Van Melle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caffeine Mint Market Trends and Innovations
Bioavailability engineering is compressing the functional onset window for oral caffeine delivery, enabling mint formats to challenge liquid energy products on speed-of-effect. Manufacturers are embedding pharmaceutical release technologies into confectionery price points.
Liposomal encapsulation technology is hybridizing with conventional compression manufacturing to create dual-layer mint structures that separate immediate-release caffeine from sustained-release B-vitamin complexes. Remote professionals and shift workers in urban Japan are adopting these formats at accelerating rates as workplace beverage consumption faces friction. This hybridization is compressing the addressable market for traditional energy shots by delivering comparable pharmacokinetics without liquid volume or refrigeration.
Japan's Ministry of Health, Labour and Welfare is tightening enforcement of Food Sanitation Act thresholds for stimulant additives in novel delivery formats, requiring pre-market notification for caffeine-nootropic combinations previously classified as conventional food. Domestic manufacturers are reformulating to stay beneath mandatory pharmaceutical classification thresholds. The functional mint segment is most affected, with brands pivoting toward single-ingredient caffeine positioning to avoid extended approval timelines.
Corporate procurement departments are consolidating wellness spend into curated vendor relationships that bundle caffeine mints with ergonomic assessments and mental health apps. Direct-to-consumer subscription platforms are displacing single-point retail purchases for knowledge worker segments in Germany and Brazil. This concentration is most visible in technology sector headquarters where facilities managers negotiate annual contracts covering all alertness and focus-related consumables.
Caffeine Mint Market Segmentation
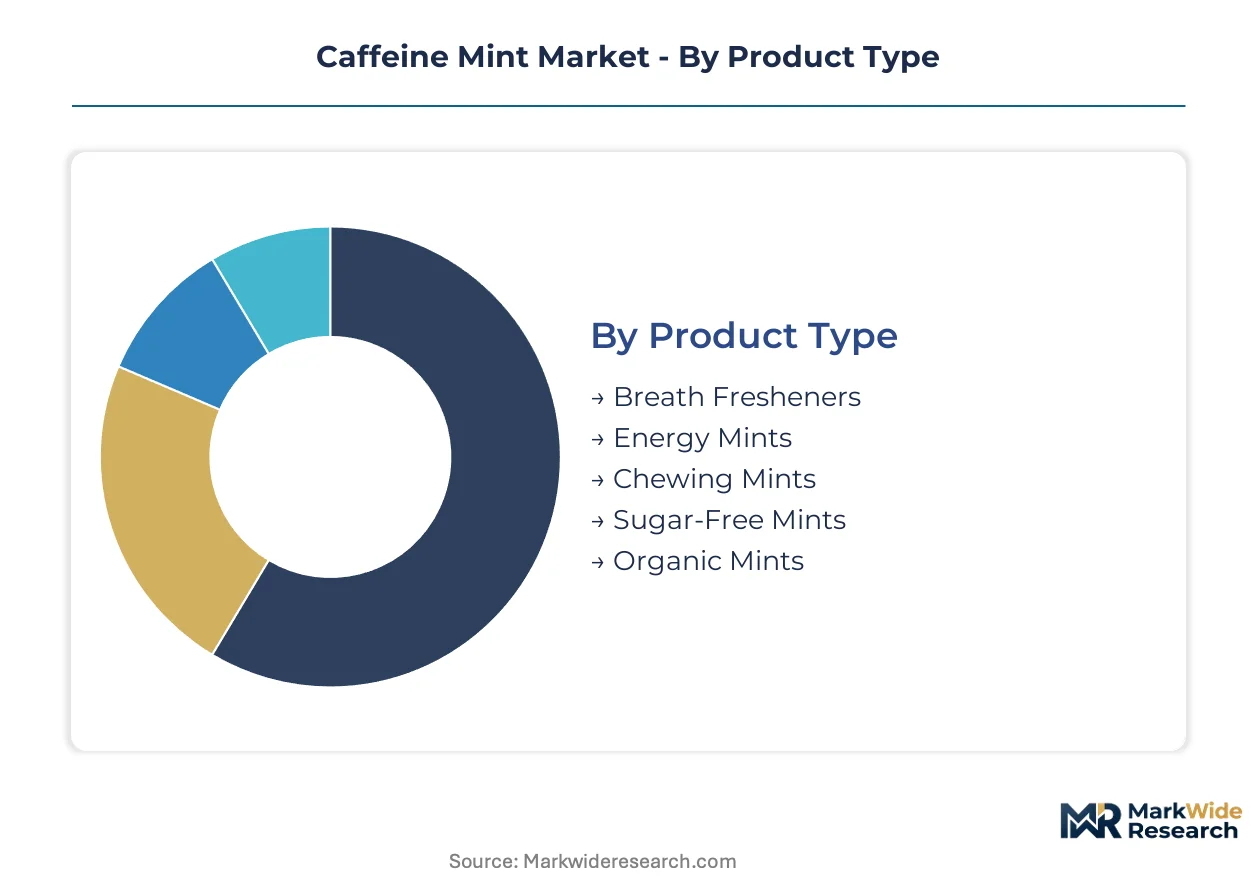
Segmentation in the caffeine mint market reveals how functional positioning, sensory preferences, and channel accessibility fragment demand across discrete buyer cohorts. Manufacturers must align formulation investments with specific consumption occasions rather than pursuing undifferentiated mass-market penetration.
Product Type:
Functional use-cases span alertness enhancement, oral hygiene, and discrete consumption across professional and social settings.
- Energy Mints:Compressed tablets delivering 50-100 mg caffeine per unit with rapid buccal absorption curves. Office workers in Germany and Japan sustain premium pricing for formats that replace coffee rituals without equipment or thermal preparation time.
- Sugar-Free Mints:Xylitol and erythritol formulations targeting diabetic consumers and dental-conscious buyers seeking functional benefits without glycemic impact. EFSA regulatory clarity on maximum caffeine thresholds for food supplements enables standardized cross-border distribution.
- Breath Fresheners:Lower-caffeine variants (5-20 mg) prioritizing oral hygiene with secondary alertness effects.
- Chewing Mints:Extended-release formats with sustained caffeine delivery for long-duration focus tasks.
- Organic Mints:Natural caffeine extracts from green tea or yerba mate appealing to clean-label preferences.
Established volume favors Energy Mints; emerging adoption favors Sugar-Free Mints.
Flavor Variety:
Regional taste preferences and functional ingredient compatibility constrain formulation choices.
- Peppermint:Dominant North American preference with proven masking properties for bitter caffeine aftertaste. Pharmacies in the United States stock this variant as the default functional confectionery option.
- Citrus Blend:Accelerating preference in Brazilian urban corridors where tropical flavor profiles align with established beverage preferences. São Paulo office density supports premium positioning for differentiated sensory experiences.
- Spearmint:Milder alternative for consumers sensitive to menthol intensity.
- Wintergreen:Niche appeal concentrated in specific demographic cohorts with heritage brand associations.
- Herbal Mix:Botanical combinations incorporating adaptogens or nootropic co-ingredients.
Peppermint commands shelf-space dominance; Citrus Blend is climbing the fastest.
Distribution Channel:
Channel selection determines customer acquisition economics and repeat purchase velocity.
- Online Retailers:Subscription algorithms leveraging consumption-pattern data reduce customer acquisition costs for niche brands. Direct-to-consumer bundling sustains recurring purchase cycles through automated replenishment.
- Convenience Stores:Impulse-driven transactions capturing immediate alertness needs without planning friction. Japan's Ministry of Health, Labour and Welfare enforcement of Food Sanitation Act thresholds shapes permissible product claims at point-of-sale.
- Supermarkets:Mass-market volume with limited SKU depth favoring established brand recognition.
- Pharmacies:Clinical positioning opportunities for products emphasizing precise caffeine dosing.
- Specialty Boutiques:Curated wellness retail with premium pricing for novel delivery formats.
Online Retailers are gaining share fastest; Convenience Stores retain transaction volume leadership.
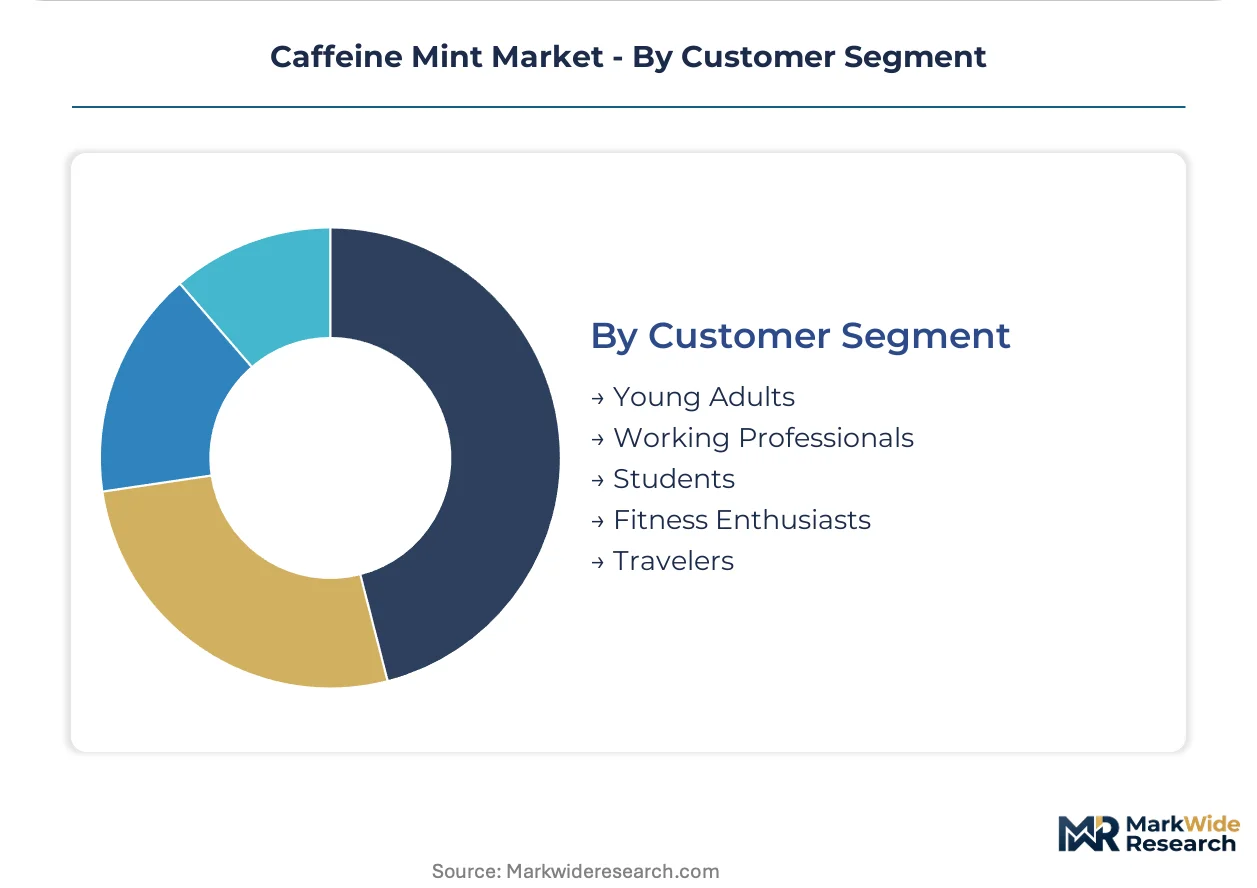
Customer Segment:
Occupational demands and lifestyle constraints differentiate purchasing behavior.
- Working Professionals:Remote and hybrid workers in technology sector headquarters where facilities managers negotiate annual contracts covering alertness consumables. Corporate procurement consolidation favors vendors with ISO 22000 certification for institutional channels.
- Students:Examination-period demand concentration with price sensitivity driving bulk-format purchases. Brazilian university corridors show accelerating adoption of functional confectionery as coffee alternatives.
- Young Adults:Experimental consumption with brand-switching behavior and social media-influenced trial.
- Fitness Enthusiasts:Pre-workout positioning competing with established sports nutrition formats.
- Travelers:Discrete portability for aviation and hospitality supply contracts.
Working Professionals anchor revenue stability; Students show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Brazilian students and young professionals exhibit acute price sensitivity, driving bulk-format purchases and private-label preference. German and Japanese office workers accept substantial premiums for precision-dosed, dental-friendly formulations that integrate into corporate wellness procurement.
United States
Remote work normalization sustains demand for discrete alertness products among technology sector headquarters in Seattle and Austin. FDA GRAS notification requirements for novel caffeine-nootropic combinations trigger extended safety review timelines that filter market entrants. Corporate procurement departments in San Francisco and New York Metro consolidate wellness spend into curated vendor relationships bundling functional confectionery with ergonomic assessments.
Germany
EFSA regulatory clarity on maximum caffeine thresholds for food supplements enables standardized product development and cross-border distribution. ISO 22000 certification opens institutional channels including corporate wellness programs and airline hospitality supply. Berlin and Munich office density supports premium positioning for sugar-alcohol formulations targeting dental-conscious buyers.
Japan
The Ministry of Health, Labour and Welfare tightens enforcement of Food Sanitation Act thresholds for stimulant additives in novel delivery formats. Domestic manufacturers in Tokyo and Osaka reformulate to stay beneath mandatory pharmaceutical classification thresholds. Shift workers and remote professionals adopt dual-layer mint structures with immediate-release caffeine and sustained-release B-vitamin complexes.
Brazil
São Paulo and Rio de Janeiro office density supports premium functional confectionery adoption with limited local specialized competition. University corridors show accelerating adoption of functional confectionery as coffee alternatives during examination periods. ANVISA oversight shapes permissible caffeine claims and labeling requirements for cross-border brands entering the market.
Caffeine Mint Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct player categories: direct-to-consumer specialists with subscription algorithm optimization, multinational confectionery conglomerates with shelf-space dominance across mass retail channels, and functional wellness brands with nootropic positioning. Consolidation pressure intensifies as pharmaceutical-grade delivery technologies demand reformulation investments beyond mid-cap reach. Dominant competitive moves include strategic partnerships for bioavailability engineering and geographic expansion into underpenetrated urban corridors.
Among direct-to-consumer specialists, Viter Energy leverages bundling infrastructure to sustain recurring purchase cycles, while Neuro anchors its position through nootropic differentiation beyond conventional confectionery. Perfetti Van Melle occupies the scale-driven tier, competing through established distribution relationships across multiple continents. These three exemplify the strategic archetypes reshaping competitive positioning: subscription-platform specialists, functional-positioning innovators, and mass-market incumbents with manufacturing depth.
| Leading Market Players |
|---|
| Viter Energy |
| Neuro |
| FOOSH Energy Mints |
| Rally Energy |
| Penguin Caffeinated Mints |
| Peppersmith |
| The Hershey Company |
| Mars |
| Perfetti Van Melle |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade caffeine production concentrates in Chinese and Indian chemical manufacturing clusters, anchoring input costs for formulated mint brands and compressing margin pools downstream toward subscription-platform specialists and mass-market incumbents with backward integration into compression manufacturing.
Pricing Analysis
Aftermarket wellness subscription revenue drives lifetime value as direct-to-consumer bundling replaces single-point transactions. Three-tier pricing structure across premium nootropic-positioned, standard functional, and economy private-label levels segments buyers by certification tier and dental-friendly formulation. Pricing pressure stems from energy drink substitution in convenience retail, where established beverage distribution infrastructure undercuts mint premiums. Brazilian students exhibit acute price sensitivity, while German corporate procurement accepts substantial premiums for ISO 22000-certified institutional supply.
Supply Chain Analysis
Tariff exposure between India and key export markets dominates supply chain risk assessment for synthetic caffeine sourcing. Active ingredient production draws from China, India, and domestic Japanese pharmaceutical manufacturers, with xylitol and erythritol sweetener supply anchored in European and North American biotech processing. Single-source vulnerability concentrates in pharmaceutical-grade caffeine qualification cycles requiring 18-24 month validation timelines. Distribution runs through direct-to-consumer subscription platforms, mass retail shelf-space agreements, and corporate wellness procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Energy drink and nootropic beverage substitution threatens incumbent positioning, requiring defensive moves that reinforce functional confectionery's discrete consumption advantage and rapid buccal absorption pharmacokinetics.
For Market Incumbents: Pre-empt subscription-platform displacement by acquiring direct-to-consumer bundling infrastructure and algorithmic replenishment capabilities. Defend against functional beverage encroachment through bioavailability engineering investments that compress onset windows below liquid energy product thresholds. Prioritize ISO 22000 certification to lock corporate wellness procurement relationships against mid-cap challengers.
For New Entrants and Emerging Players: Pursue white-space capture in Brazilian urban corridors where São Paulo and Rio de Janeiro office density supports premium positioning with limited specialized competition. Target student segments in university corridors with bulk-format, examination-period positioning. Anchor go-to-market through citrus-blend flavor differentiation aligned with established tropical beverage preferences.
For Investors and Strategic Acquirers: Capital is best deployed toward direct-to-consumer specialists with proven subscription algorithm optimization and nootropic-positioned functional wellness brands with pharmaceutical-grade delivery technology. Long-term viability hinges on regulatory navigation capabilities across FDA GRAS notification and EFSA caffeine threshold jurisdictions. Monitor Japan Ministry of Health, Labour and Welfare enforcement tightening as inflection indicator for reformulation cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioavailability Engineering Investment | Compresses functional onset windows to challenge liquid energy product speed-of-effect in Germany and Japan. |
| Direct-to-Consumer Subscription Launch | Reduces customer acquisition costs through algorithmic replenishment targeting remote professionals. |
| ISO 22000 Certification Program | Unlocks corporate wellness procurement and airline hospitality supply contracts in institutional channels. |
| Geographic Expansion into Brazilian Urban Corridors | Captures São Paulo and Rio de Janeiro office density with limited local specialized competition. |
| Nootropic Co-Ingredient Reformulation | Differentiates beyond conventional confectionery through L-theanine and B-vitamin complex positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, retail audit data, and trade flow records. Conversations with brand managers at functional confectionery specialists, category buyers at mass retail chains, supply planners at sweetener processors, and regulatory affairs leads at multinational conglomerates inform demand and compliance dynamics. Secondary validation draws from FDA GRAS notifications, EFSA scientific opinions, Japan Food Sanitation Act enforcement records, and customs documentation of caffeine raw material flows. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Forecast inputs span product type segmentation across energy, sugar-free, and nootropic-positioned formats; flavor variety including peppermint, citrus blend, and herbal mix; distribution channel dynamics across subscription platforms, convenience retail, and corporate procurement; and customer segment behavior among working professionals, students, and fitness enthusiasts. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory inflection points and substitution threat intensity. Cross-jurisdiction label compliance cost trajectories and bioavailability technology diffusion rates shape projection boundaries.
Macroeconomic conditions sit as an overlay; deviation in remote work normalization rates, corporate wellness budget allocations, or caffeine regulatory threshold tightening would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA threshold stability and FDA notification timeline consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Smoothies Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Tonic Water Market
Beverages
Dairy Based Beverages Market
Beverages
NFC JUICE Market
Beverages
India Soy Beverages Market
Beverages
Relaxation Beverages Market
Beverages
Asia-Pacific Juices Market
Beverages
Global Bottled Water Market
Beverages
Orange Juice Market
Beverages
United States Sports and Energy Drinks Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Collagen-Infused Water Market
Beverages
US and Canada Premium Bottled Water Market
Beverages
Europe Yerba Mate Market
Beverages
India Bottled Water Market