
 Superfood Infused Beverages Market | 2026-2036
Superfood Infused Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Superfood Infused Beverages Market Analytics
Premium organic certification is rotating through the superfood infused beverages category as the baseline expectation for shelf placement. REBBL leverages its coconut milk base and adaptogenic formulations to anchor the ethical sourcing tier. PepsiCo competes through scale advantages in bottling and mass retail distribution. Suja Life differentiates via cold-pressed juice specialization with high-pressure processing technology.
Superfood infused beverages combine plant-derived nutrient concentrates with functional bioactive compounds, typically processed through cold-pressing, high-pressure processing, or gentle pasteurization to preserve enzymatic activity and vitamin stability. These formulations serve commercial purposes spanning metabolic support, cognitive enhancement, and post-exercise recovery in convenience formats. Functional drinks lead volume contribution due to everyday consumption frequency, while matcha and turmeric within the key ingredient dimension command premium pricing through provenance storytelling and ceremonial-grade specifications. Bottles retain dominance in packaging type share though pouches represent the fastest-growing format for on-the-go athletic consumption.
FDA enforcement of updated Nutrition Facts labeling and added sugar disclosure directly shapes formulation decisions for brands targeting the United States market. EFSA health claims regulation governs permissible functional benefit communication across European Union member states, constraining marketing language around spirulina and chia seed efficacy. Organic certification requirements from USDA and equivalent EU bodies create tiered market access thresholds that smaller brands must navigate. Stakeholders should monitor evolving adaptogen classification debates and sugar reduction mandates as these regulatory vectors will determine which ingredient portfolios retain commercial viability.
Market Dynamics
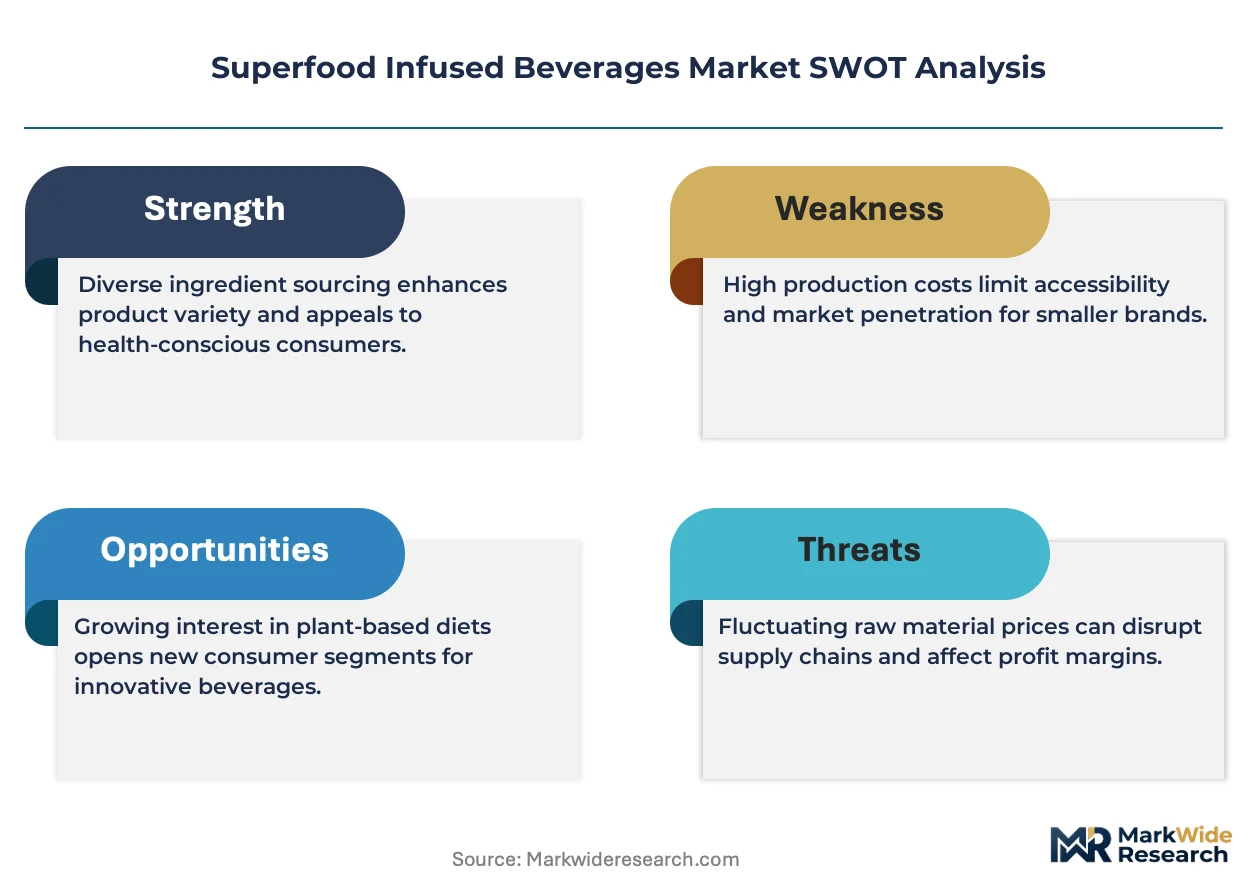
Clean-label mandates from the FDA and EFSA are compressing formulation timelines while forcing sugar reduction commitments across North American and European portfolios. This regulatory pressure is decomposing legacy beverage architectures and reallocating R&D budgets toward adaptogenic ingredient sourcing.
Growth Catalysts
- Adaptogen Classification Momentum:FDA draft guidance on botanical safety is creating pathway clarity for ashwagandha and reishi formulations. Functional beverage brands are accelerating clinical substantiation investments to preempt enforcement actions.
- High-Pressure Processing Scale-Up:Cold-press juice manufacturers are deploying HPP tunnel systems to extend shelf life without thermal degradation. Enzymatic activity retention is becoming a purchase trigger for premium urban consumers.
- Direct-to-Consumer Channel Maturation:Subscription models in the United States are capturing recurring revenue from wellness-focused millennials. Data-rich customer relationships enable rapid flavor iteration and inventory optimization.
Market Restraints
- Organic Certification Bottlenecks:USDA organic compliance timelines stretch 18-24 months for new ingredient suppliers. Small-batch producers face working capital constraints during audit periods.
- Spirulina Supply Concentration:Pond-based cultivation in specific subtropical zones creates climate vulnerability. Single-source dependencies expose brands to harvest volatility and price spikes.
- Turmeric Bioavailability Limits:Curcumin absorption rates without piperine enhancement remain below therapeutic thresholds. Formulation science gaps constrain functional claim substantiation.
Strategic Opportunities
- Athletic Recovery Positioning:Post-workout consumption occasions in the United States remain underdeveloped relative to pre-workout energy. Electrolyte-adaptogen hybrids can capture gym channel shelf space.
- Pouch Format Expansion:Flexible packaging for on-the-go athletic use is displacing rigid bottles in trail running and cycling segments. Material science advances are improving oxygen barrier performance.
- IRA-Aligned Sustainable Production:Renewable energy tax incentives support cold-chain infrastructure upgrades. Brands with verified carbon-negative sourcing can access ESG-mandated institutional procurement channels.
Industry Challenges
- Adaptogen Pharmacovigilance Expertise:Formulation teams lack toxicologists trained in herb-drug interaction assessment. FDA warning letters on unsubstantiated stress-reduction claims are rising.
- Legacy ERP Integration:Lot traceability requirements for organic certification collide with decades-old beverage manufacturing software. Custom middleware development is draining IT resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superfood Infused Beverages Market |
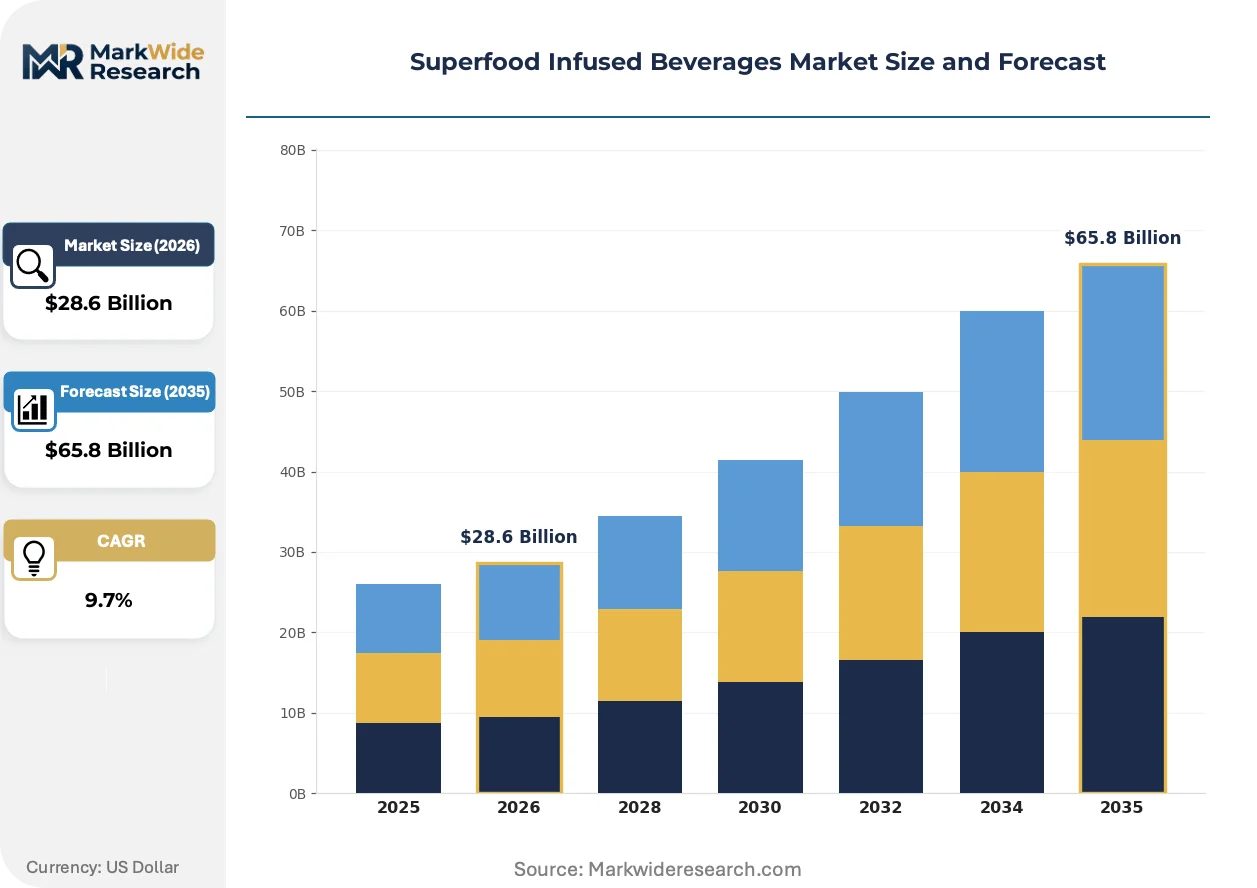
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $65.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Drinks, Smoothies, Juices, Herbal Teas Key Ingredient: Chia Seeds, Spirulina, Matcha, Turmeric Packaging Type: Bottles, Tetra Packs, Cans, Pouches End User: Health Enthusiasts, Athletes, Busy Professionals, Students |
| Companies Covered | REBBL, KeVita, PepsiCo, Bai, Naked Juice Company, The Coca-Cola Company, Vital Proteins, Kuli Kuli Foods, Suja Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superfood Infused Beverages Market Evolving Landscape
Biotechnology-enabled ingredient production is rewriting cost curves for high-value botanicals while precision fermentation platforms expand beyond proteins into bioactive compounds. These shifts are compressing traditional agriculture-dependent supply models.
Precision fermentation for rare adaptogens is decomposing the geographic monopoly of traditional cultivation regions. Biotech startups in California and the Netherlands are producing standardized reishi and chaga extracts at 40% below wild-harvested input costs. This technology is decomposing the premium pricing power of provenance-based storytelling that Japanese and Himalayan sourcing previously commanded.
EFSA health claims regulation is tightening evidentiary standards for gut microbiome benefits. Brands must now submit human intervention studies rather than in-vitro data for chia and flaxseed positioning. European functional beverage launches are retreating from digestive health claims toward safer antioxidant messaging.
Urban convenience stores are displacing natural grocery as the primary trial channel for new superfood entrants. Manhattan and Los Angeles bodega placements now determine velocity metrics that secure Whole Foods distribution. Younger demographics discover brands through refrigerated impulse purchases rather than curated online subscription.
Superfood Infused Beverages Market Segmentation
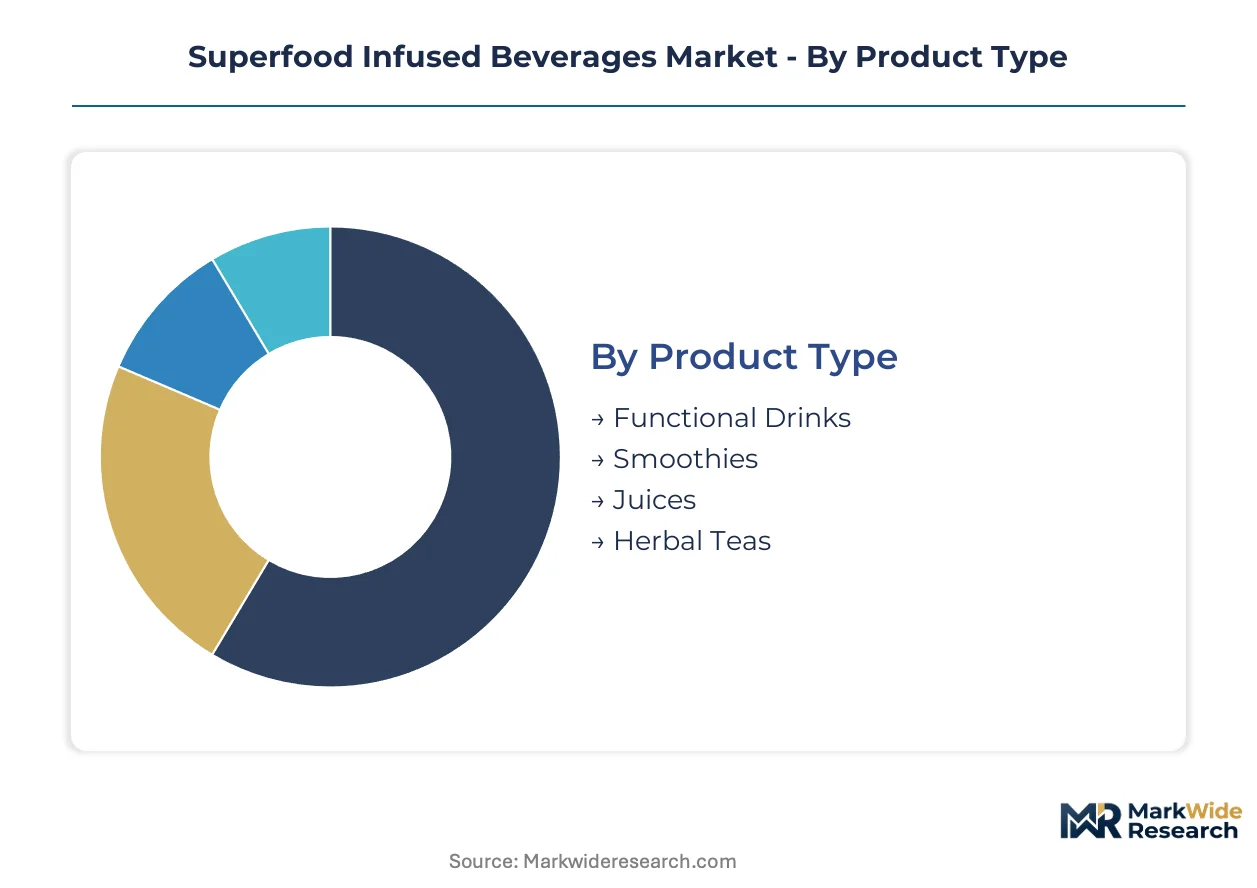
Segmentation in superfood infused beverages reveals how formulation priorities diverge across consumption contexts. Each dimension exposes distinct pressure points from regulatory scrutiny, ingredient sourcing constraints, and channel-specific packaging requirements.
Product Type:
Functional drinks face acute substitution pressure from conventional sports beverages and energy drinks that now incorporate basic vitamin fortification.
- Functional Drinks:These formulations integrate adaptogenic extracts with electrolyte bases for metabolic and cognitive support. Demand concentrates among urban millennials in the United States who prioritize daily consumption rituals over episodic wellness purchases. FDA added-sugar disclosure mandates are accelerating reformulation toward monk fruit and allulose sweeteners.
- Smoothies:Blended formats combine protein isolates with superfood concentrates for meal-replacement positioning. Athletes in California and New York metropolitan areas drive recurring subscription purchases through direct-to-consumer channels. High-pressure processing investments by manufacturers extend refrigerated shelf life without thermal degradation.
- Juices:Cold-pressed extraction preserves enzymatic activity in fruit-vegetable-superfood combinations.
- Herbal Teas:Steeped botanical formulations target relaxation and sleep support occasions.
Functional drinks retain volume leadership; smoothies hold the steepest expansion curve.
Key Ingredient:
Cost tier stratification separates ceremonial-grade botanicals from commodity-grade alternatives.
- Chia Seeds:These hydrophilic seeds deliver omega-3 fatty acids and soluble fiber in beverage suspensions. Health enthusiasts in Germany and the Netherlands favor chia for sustained energy without caffeine. EFSA digestive health claim restrictions have pushed marketers toward antioxidant positioning.
- Spirulina:This cyanobacterium provides complete protein and phycocyanin pigment for visual differentiation. Supply bottlenecks from pond-based cultivation in subtropical zones expose brands to climate-driven harvest volatility. Quality verification protocols from USDA organic auditors add 18-24 month certification timelines.
- Matcha:Shade-grown green tea powder commands premium pricing through Japanese provenance storytelling.
- Turmeric:Curcumin bioavailability challenges constrain functional claim substantiation without piperine enhancement.
Spirulina retains volume leadership; matcha holds the steepest expansion curve.
Packaging Type:
Volume-to-weight ratios determine logistics economics across ambient and cold-chain distribution networks.
- Bottles:PET and glass formats dominate refrigerated retail placement with established recycling infrastructure. Urban convenience stores in Manhattan and Los Angeles require compact bottle footprints for limited cooler space. Lightweighting initiatives reduce per-unit shipping costs for cross-country distribution.
- Pouches:Flexible films with oxygen barrier layers serve trail running and cycling segments. Material science advances from German packaging suppliers improve shelf stability without aluminum lamination. On-the-go athletic consumption occasions are displacing rigid formats in specialty outdoor retailers.
- Tetra Packs:Aseptic carton systems enable ambient distribution for herbal tea concentrates.
- Cans:Aluminum formats appeal to crossover consumers from craft beverage categories.
Bottles retain volume leadership; pouches are gaining share fastest.
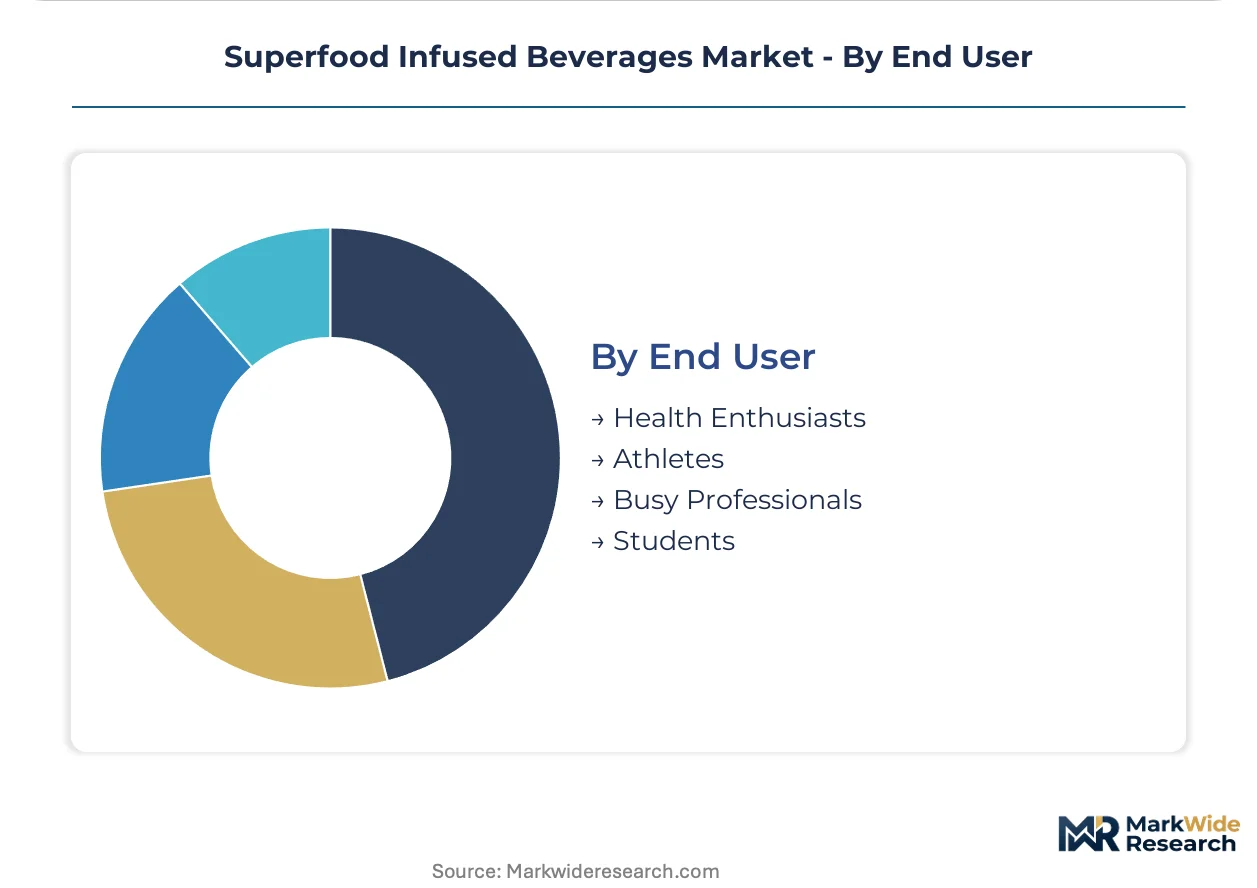
End User:
Customer type segmentation exposes divergent willingness-to-pay for organic certification and functional claim specificity.
- Health Enthusiasts:This cohort prioritizes clean-label transparency and adaptogenic ingredient density over price sensitivity. Subscription retention rates in the United States exceed those of episodic purchasers by significant margins. These consumers cross-reference USDA organic status with third-party heavy metal testing results.
- Athletes:Post-workout recovery positioning targets gym channel distribution with electrolyte-adaptogen hybrids. Protein-carbohydrate ratios and branched-chain amino acid content drive purchase decisions. Precision fermentation-derived ingredients are penetrating this segment through cost-competitive beta-alanine and citrulline.
- Busy Professionals:Convenience-oriented consumption favors ready-to-drink formats with minimal preparation.
- Students:Price-conscious demand concentrates in private-label offerings and promotional velocity periods.
Health enthusiasts retain volume leadership; athletes hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in superfood infused beverages tilt heavily toward net-importing developed markets, with raw ingredient sourcing concentrated in subtropical cultivation zones and finished product manufacturing clustering near premium consumption centers.
United States
Urban millennials in Manhattan and Los Angeles drive trial velocity through convenience store channels. FDA enforcement of updated Nutrition Facts labeling and added sugar disclosure compresses formulation timelines for brands targeting this market. Cold-press manufacturing clusters in California deploy high-pressure processing tunnel systems to extend shelf life without thermal degradation.
Germany
Health enthusiasts in Berlin and Munich favor chia-based formulations for sustained energy positioning. EFSA health claims regulation governs permissible functional benefit communication, constraining marketing language around spirulina efficacy. Bavarian packaging suppliers advance oxygen barrier films for flexible pouch formats serving athletic consumption occasions.
Japan
Ceremonial-grade matcha commands premium pricing through provenance storytelling in Tokyo and Osaka metropolitan markets. METI oversight of functional food standards creates compliance thresholds for adaptogenic ingredient introductions. Kansai region distributors specialize in temperature-controlled logistics for enzymatic activity retention.
Netherlands
Precision fermentation startups in the Randstad region produce standardized reishi extracts below wild-harvested input costs. EU Green Deal alignment requirements shape sustainable production investments for brands accessing ESG-mandated institutional procurement. Rotterdam cold-chain infrastructure supports cross-border distribution into German and Belgian retail channels.
Australia
Spirulina pond-based cultivation in subtropical Queensland creates climate vulnerability for global supply chains. TGA therapeutic goods classification debates influence adaptogen marketing permissions for stress-reduction positioning. Sydney and Melbourne direct-to-consumer subscription models capture recurring revenue from wellness-focused demographics.
Superfood Infused Beverages Market Competitive Landscape
Listed leaders compete with private specialists across formulation sophistication and channel access. The vendor base stratifies into three tiers: multinational beverage conglomerates with mass retail distribution, mid-scale organic specialists with direct-to-consumer platforms, and emerging biotech-enabled ingredient innovators. Competitive moves concentrate on portfolio diversification into adaptogenic formulations and strategic partnerships with precision fermentation suppliers.
Within the premium organic tier, REBBL and Suja Life exemplify ethical sourcing and cold-pressed specialization archetypes respectively. PepsiCo anchors the scale-driven conglomerate position. These three occupy distinct competitive spaces: coconut milk adaptogenic formulations, high-pressure processing technology deployment, and bottling infrastructure leverage across mass retail channels.
| Leading Market Players |
|---|
| REBBL |
| KeVita |
| PepsiCo |
| Bai |
| Naked Juice Company |
| The Coca-Cola Company |
| Vital Proteins |
| Kuli Kuli Foods |
| Suja Life |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with certified organic spirulina cultivators in subtropical Queensland lock in both supply access and price visibility for brands navigating FDA added-sugar disclosure mandates. These contracts insulate premium tier producers from spot market volatility while compressing margins for smaller players unable to meet USDA organic audit timelines.
Pricing Analysis
Health enthusiasts anchor premium pricing through subscription retention rates that exceed episodic purchasers significantly. Three-tier pricing structure across premium organic certification, standard clean-label, and economy private-label levels stratifies the market. Cost compression in the standard tier intensifies as conventional sports beverages incorporate basic vitamin fortification. Students exhibit highest price sensitivity, while health enthusiasts demonstrate lowest sensitivity to organic certification premiums.
Supply Chain Analysis
Spirulina pond-based cultivation concentration in subtropical Queensland, Japan's shade-grown matcha regions, and India's turmeric processing belts creates climate vulnerability exposure. Finished beverage manufacturing draws from high-pressure processing equipment in California, Bavarian oxygen barrier film suppliers, and Dutch precision fermentation platforms. Single-source dependencies on subtropical spirulina harvests present structural risk from extreme weather events. Distribution runs through direct-to-consumer subscription channels and urban convenience store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription revenue layers expand faster than single-unit retail, transforming superfood beverages into recurring-revenue service businesses with data-rich customer relationships enabling rapid flavor iteration.
For Market Incumbents: Compound subscription retention advantages through proprietary adaptogen formulation pipelines and exclusive precision fermentation partnerships. Defend against biotech-enabled ingredient innovators by accelerating clinical substantiation investments for stress-reduction claims. Prioritize backward integration into certified organic spirulina cultivation to secure supply access during climate-driven harvest volatility. For New Entrants and Emerging Players: Anchor in post-workout recovery positioning within United States gym channels, the most penetrable white-space relative to saturated pre-workout energy segments. Target athletic recovery occasions with electrolyte-adaptogen hybrids lacking incumbent saturation. Pursue pouch format specialization for trail running and cycling segments through German oxygen barrier film suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale organic specialists with direct-to-consumer platforms and verified carbon-negative sourcing credentials. Long-term viability over the projection horizon favors brands with ESG-mandated institutional procurement access through IRA-aligned renewable energy investments. Monitor FDA adaptogen classification guidance as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Biotech-derived reishi extracts from California and Netherlands platforms cut input costs below wild-harvested sources. |
| Direct-to-Consumer Subscription Launch | Data-rich relationships with urban millennials enable rapid inventory optimization and flavor iteration cycles. |
| Organic Certification Investment | USDA compliance timelines of 18-24 months create tiered market access thresholds smaller competitors cannot navigate. |
| Pouch Format Expansion | German oxygen barrier films improve shelf stability for trail running and cycling consumption occasions. |
| Post-Workout Recovery Positioning | Electrolyte-adaptogen hybrids capture underdeveloped gym channel shelf space relative to pre-workout energy. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at natural grocery and convenience retail channels, cold-press manufacturing plant managers, and precision fermentation R&D directors anchored the qualitative base. Secondary validation drew from FDA enforcement letters, EFSA health claims registers, USDA organic certification databases, and Nielsen retail audit data. Bottom-up volume estimates triangulated with top-down category spending analysis.
Sensitivity analysis tested forecast robustness across alternative regulatory scenarios and supply disruption events. Segmentation modeling incorporated product type, key ingredient, packaging format, and end user dimensions alongside regional regulatory cluster variations. CAGRs were derived from trend extrapolation adjusted for adaptogen classification momentum and sugar reduction mandate acceleration. Forecast inputs included high-pressure processing capacity expansion rates and precision fermentation cost curve trajectories.
Decision-makers should treat outputs as directional under base assumptions of continued FDA enforcement trajectory and stable subtropical cultivation climates; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA evidentiary standards and adaptogen pharmacovigilance requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Carbonated Beverages Market
Beverages
Hydrogen Water Bottle Market
Beverages
Detox Drinks Market
Beverages
Coconut Milk Beverages Market
Beverages
Blenders Market
Beverages
Bangladesh Energy Drinks Market
Beverages
Ready to Drink Premixes Market
Beverages
Low Calorie RTD Beverages Market
Beverages
South East Asia Bottled Water Market
Beverages
US Bubble Tea Market
Beverages
Beverage Multipacks Market
Beverages
GCC Juice Market
Beverages
Cold Pressed Juice Market
Beverages
Global Squash Drinks Market
Beverages
Popping Bobas Market
Beverages
North America Dairy Beverages Market