
 Global Functional Drinks Market | 2026-2036
Global Functional Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Functional Drinks Market Analysis
Registered dietitian shortages across North American and European markets is unwinding formulation capacity and slowing new product clearance timelines. PepsiCo leverages its bottling infrastructure to sustain shelf-space dominance in convenience channels. Monster Beverage Corp. competes through caffeine-delivery specialization and esports sponsorship density. Red Bull GmbH anchors premium pricing through event-ownership and content-studio assets.
Functional drinks are non-alcoholic beverages formulated with bioactive compounds including vitamins, minerals, amino acids, and herbal extracts, manufactured through cold-aseptic filling or hot-fill processes to preserve ingredient stability and deliver targeted physiological effects such as energy metabolism support, hydration optimization, or cognitive performance enhancement. Energy Drinks occupy the largest revenue pool but face margin compression from private-label entrants and regulatory caffeine caps, while Wellness Shots represent the fastest-growing structural segment as consumers trade volume for concentrated efficacy and cleaner label profiles. Nutritional Drinks sustain defensive positioning among aging demographics and clinical nutrition channels where reimbursement pathways create stickier demand than discretionary retail.
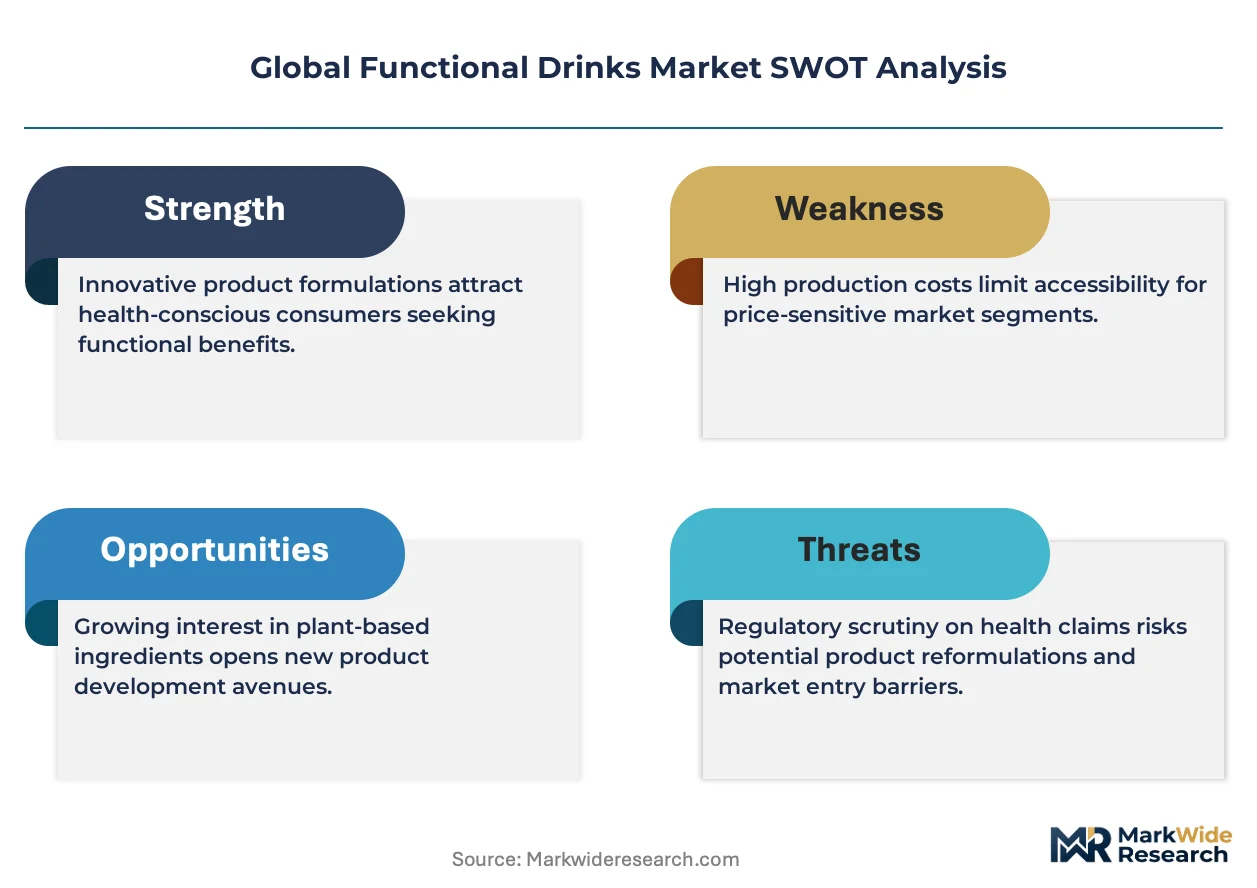
The FDA governs ingredient safety and health claim substantiation in the United States, while EFSA enforces stricter evidence thresholds for European functional claims, creating divergent product portfolios across Atlantic markets. China's SAMR implements formula registration requirements that filter out smaller importers and elevate compliance costs for botanical ingredient sourcing. Stakeholders must monitor evolving caffeine limits, sugar taxation regimes, and novel food ingredient approval pathways to anticipate which formulation architectures will retain market access.
Market Dynamics
Clean-label ingredient sourcing is compressing formulation timelines as brands race to replace synthetic additives with verified botanical extracts before EFSA and FDA substantiation deadlines.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:Harmonized claim substantiation across member states reduces fragmentation costs for pan-European launches, accelerating cross-border portfolio standardization.
- Urban Brazil wellness shot adoption:Health-conscious consumers in São Paulo and Rio de Janeiro drive probiotic penetration, creating template demand patterns for Latin American expansion.
- Cold-aseptic filling technology:Extended shelf stability without thermal degradation enables heat-sensitive bioactive incorporation, unlocking new functional benefit categories.
Market Restraints
- Registered dietitian shortages:North American and European formulation capacity constraints delay new product clearance timelines by 8-14 months on average.
- China SAMR formula registration:Botanical ingredient compliance costs filter smaller importers, concentrating market access among capitalized multinationals.
- Caffeine regulatory caps:Proposed ceiling reductions in multiple jurisdictions threaten energy drink margin structures optimized for high-stimulant formulations.
Strategic Opportunities
- India tier-two city penetration:Functional beverage consumption in Hyderabad, Pune, and Ahmedabad trails metro benchmarks by 60%, offering volume expansion headroom.
- Esports and gaming sponsorship channels:Caffeine-delivery specialization aligns with tournament viewership demographics, creating endemic marketing efficiency versus mass media.
- Japan METI functional foods framework:FOSHU and FNFC claim pathways provide regulatory clarity for ingredient-specific positioning, reducing substantiation risk for entrants.
Industry Challenges
- Dual carbon compliance integration:China's MEE emission targets and EU CSRD reporting requirements force simultaneous carbon accounting system overhauls without harmonized methodologies.
- Legacy hot-fill asset stranding:Existing production infrastructure lacks compatibility with emerging cold-aseptic standards, requiring write-downs or retrofit capex commitments.
- Botanical supply chain provenance verification:DNA authentication and blockchain traceability implementation demands strain quality assurance teams already stretched by multiple jurisdiction audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Functional Drinks Market |
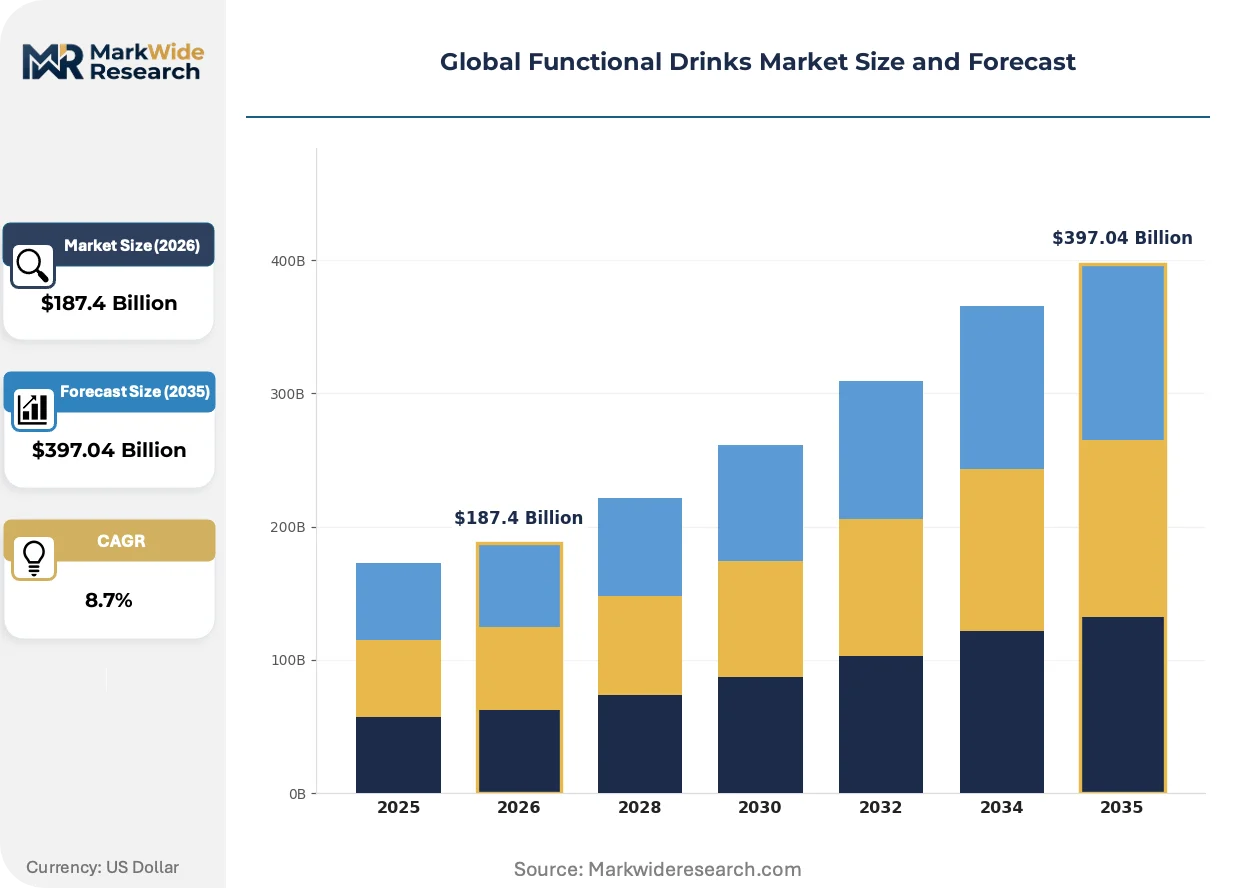
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Sports Beverages, Nutritional Drinks, Wellness Shots Ingredient Category: Vitamins, Minerals, Amino Acids, Herbal Extracts End User: Fitness Enthusiasts, Health-Conscious Consumers, Athletes, Busy Professionals Packaging Type: Bottles, Cans, Tetra Packs, Pouches |
| Companies Covered | Nestlé S.A., Danone S.A., PepsiCo Inc., Celsius Holdings Inc., Keurig Dr Pepper Inc., The Coca-Cola Company, Monster Beverage Corp., Fonterra Co-operative Group Limited, Red Bull GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Functional Drinks Market Emerging Trajectories
Formulation architectures are pivoting from volume-based consumption models toward concentrated efficacy delivery, compressing serving sizes while amplifying bioactive density per unit.
Microencapsulation technology using lipid-shell delivery systems protects probiotics and vitamins through gastric transit, improving bioavailability claims. Premium wellness shot producers in Germany and California adopt these systems at scale. The technology is supplanting traditional suspension-based formulations that suffered from ingredient degradation and inconsistent dosing.
EFSA's tightened health claim evidence thresholds now require human intervention studies for botanical substantiation, elevating R&D costs. European brands are reformulating around approved generic claims rather than proprietary ingredient stories. The wellness shot segment bears the heaviest compliance burden, with several SKUs withdrawn pending clinical data completion.
Chinese consumers in tier-one cities now prioritize functional efficacy over brand heritage, compressing loyalty cycles. Direct-to-subscription models via WeChat mini-programs displace traditional retail discovery for urban professionals. This behavioral shift concentrates demand capture in Shanghai, Beijing, and Shenzhen, where digital-native purchase journeys dominate.
Global Functional Drinks Market Segmentation
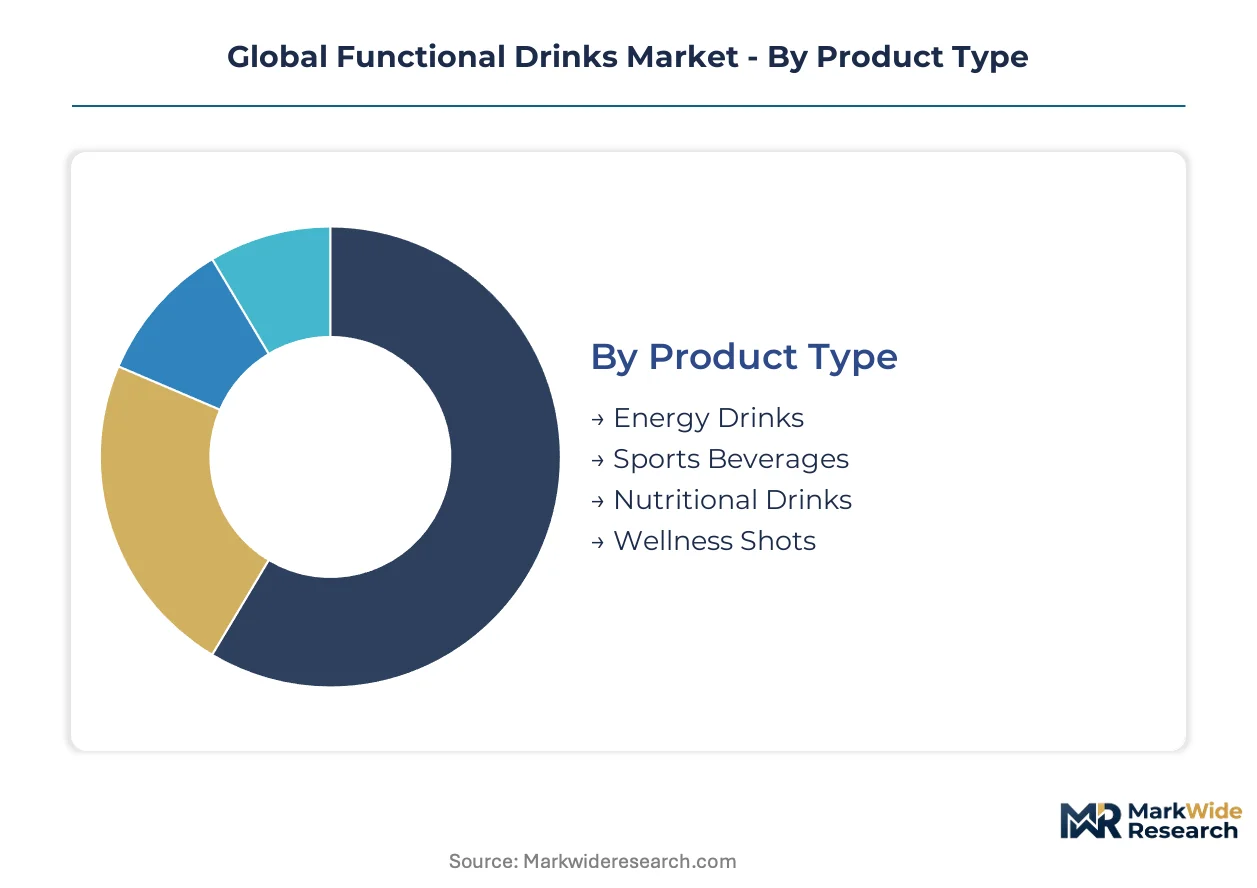
Functional drinks segment along four intersecting dimensions that determine formulation priorities, margin capture, and channel strategy. Product type and ingredient category together define the technical architecture, while end user and packaging type shape go-to-market economics.
Product Type:
Margin pools concentrate in concentrated-dose formats that command per-unit premiums over volume-based alternatives.
- Energy Drinks:Caffeine-forward formulations with taurine and B-vitamin complexes dominate convenience channel velocity. Demand clusters among esports participants and night-shift workers in São Paulo, Jakarta, and Manila where sustained alertness drives repeat purchase frequency. Regulatory caffeine caps in the EU and proposed limits in several US states threaten margin structures optimized for high-stimulant formulations.
- Wellness Shots:Cold-pressed concentrates delivering probiotics, adaptogens, or nootropics in 60ml servings. Urban professionals in Shanghai, Beijing, and Shenzhen trade volume for efficacy density, compressing loyalty cycles as functional benefits outweigh brand heritage. Microencapsulation technology protects heat-sensitive bioactives through gastric transit.
- Sports Beverages:Electrolyte-replenishment formulations targeting hydration optimization during exertion.
- Nutritional Drinks:Meal-replacement and clinical nutrition formats sustaining defensive positioning among aging demographics.
The dominant share belongs to Energy Drinks, while Wellness Shots is closing the gap fastest.
Ingredient Category:
Cost tier stratification runs from commodity vitamins to premium botanicals requiring provenance verification.
- Herbal Extracts:Standardized botanical concentrates from ashwagandha, ginseng, and turmeric root. EFSA's tightened evidence thresholds now demand human intervention studies for health claim substantiation, elevating R&D costs and forcing reformulation around approved generic claims. DNA authentication and blockchain traceability strain quality assurance teams already stretched by multi-jurisdiction audits.
- Amino Acids:Branched-chain and essential amino acid formulations supporting muscle protein synthesis and recovery. Fitness enthusiasts in Germany, California, and Australia's Gold Coast drive specification intensity, with clean-label sourcing compressing formulation timelines as brands race to replace synthetic additives with verified botanical extracts.
- Vitamins:Water-soluble and fat-soluble micronutrient fortification at commodity cost structures.
- Minerals:Electrolyte and trace element supplementation for hydration and metabolic support.
Herbal Extracts command the steepest price premiums, though Amino Acids is expanding most quickly in sports-positioned portfolios.
End User:
Application intensity varies sharply by usage occasion and reimbursement pathway access.
- Busy Professionals:Time-compressed consumption driving single-serve, on-premise purchase patterns. Direct-to-subscription models via WeChat mini-programs displace traditional retail discovery in China's tier-one cities. Caffeine-delivery specialization aligns with tournament viewership demographics, creating endemic marketing efficiency versus mass media.
- Health-Conscious Consumers:Label-literate buyers prioritizing clean ingredient decks and transparent supply chains. Probiotic wellness shot penetration in São Paulo and Rio de Janeiro creates template demand patterns for Latin American expansion, with cold-aseptic filling technology enabling heat-sensitive bioactive incorporation.
- Fitness Enthusiasts:Gym-adjacent consumption with performance-linked benefit expectations.
- Athletes:Clinical and elite-performance channels where reimbursement pathways create stickier demand than discretionary retail.
Busy Professionals generate the highest per-capita spend, yet Health-Conscious Consumers is gaining share fastest through wellness shot adoption.
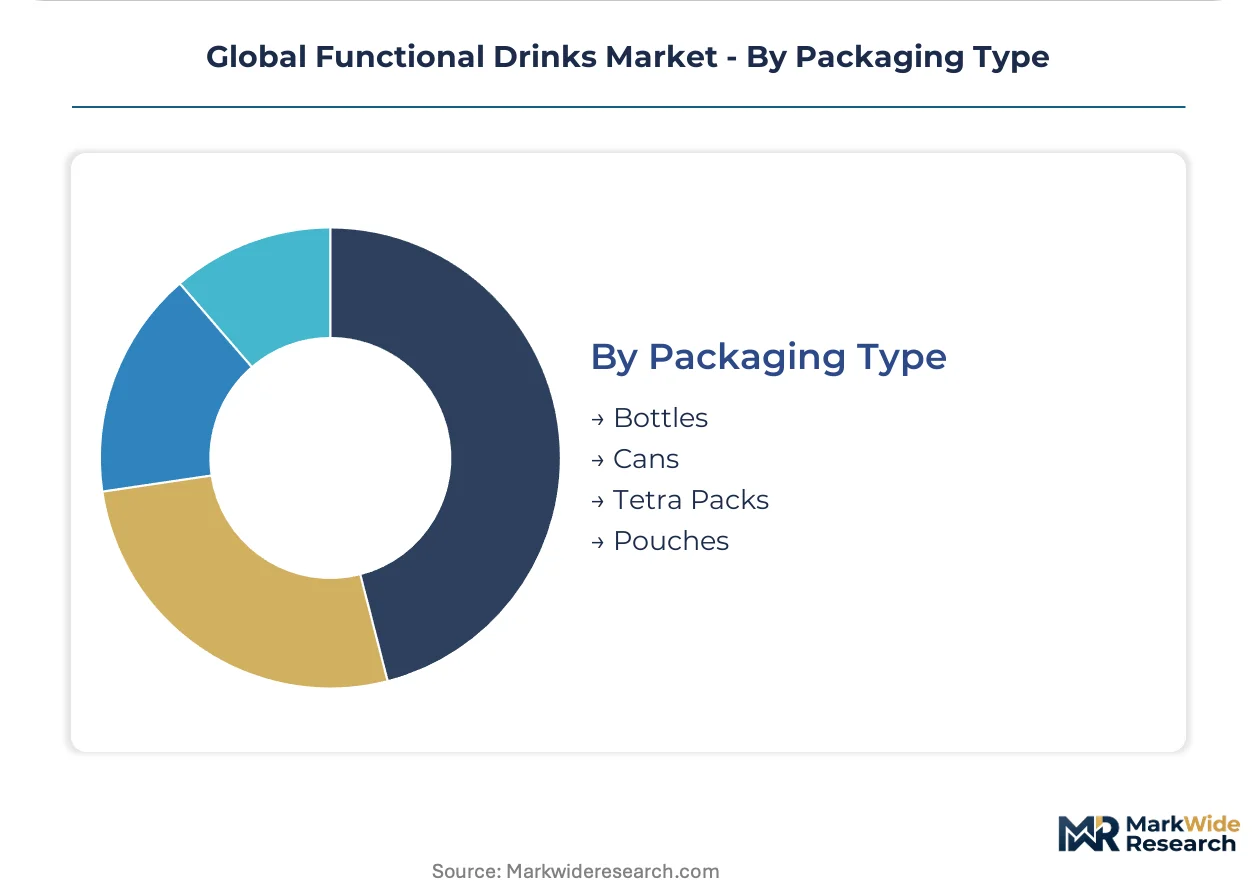
Packaging Type:
Volume scale and shelf stability requirements dictate material selection and line equipment investment.
- Cans:Aluminum formats dominating energy drink portfolios with superior chill speed and recyclability credentials. PepsiCo leverages bottling infrastructure to sustain shelf-space dominance in convenience channels across the US, Mexico, and UK. Legacy hot-fill asset stranding threatens existing production infrastructure lacking compatibility with emerging cold-aseptic standards.
- Bottles:PET and glass formats supporting premium positioning and resealability for extended consumption.
- Tetra Packs:Aseptic carton systems enabling ambient distribution for nutritional drinks in clinical channels.
- Pouches:Flexible formats for wellness shot portion control and reduced material intensity.
Cans retain the volume lead, though Bottles is climbing the fastest in premium wellness and sports beverage lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with Brazilian consumers favoring probiotic wellness shots while German buyers prioritize clinical nutrition formats and Chinese professionals drive subscription-based concentrated efficacy products.
United States
Energy drink velocity concentrates in convenience channels anchored by night-shift workers and esports participants. FDA ingredient safety reviews and health claim substantiation requirements shape formulation timelines. Greater Los Angeles and Houston metro areas sustain the highest per-capita functional beverage consumption rates.
Germany
EFSA's tightened evidence thresholds for botanical health claims drive reformulation toward approved generic positioning. Wellness shot producers in Bavaria adopt microencapsulation technology at commercial scale. Berlin and Munich clusters lead cold-aseptic filling infrastructure deployment.
China
SAMR formula registration requirements filter smaller importers and elevate compliance costs for botanical sourcing. Tier-one city professionals in Shanghai, Beijing, and Shenzhen prioritize functional efficacy over brand heritage. WeChat mini-program subscription models displace traditional retail discovery channels.
Brazil
Probiotic wellness shot penetration accelerates among health-conscious consumers in São Paulo and Rio de Janeiro. ANVISA governs novel food ingredient approvals and health claim substantiation standards. These demand patterns create template expansion frameworks for broader Latin American markets.
Japan
METI's FOSHU and FNFC claim pathways provide regulatory clarity for ingredient-specific positioning. Aging demographics sustain defensive demand for clinical nutrition and meal-replacement formats. Tokyo-Osaka corridor concentrates premium wellness shot innovation and manufacturing capacity.
Global Functional Drinks Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational beverage conglomerates leveraging bottling infrastructure against focused functional specialists competing through caffeine-delivery specialization and concentrated efficacy formats. The market structure rewards scale in convenience channel shelf-space negotiation while permitting margin capture among premium wellness shot producers with proven bioactive stability claims. Two dominant competitive moves are emerging: backward integration into cold-aseptic filling technology to replace stranded hot-fill assets, and geographic portfolio standardization to reduce cross-border regulatory fragmentation costs.
Within the integrated multinational tier, PepsiCo Inc. and The Coca-Cola Company exemplify scale-driven distribution leverage, while Monster Beverage Corp. occupies a specialist position anchored in caffeine-forward formulation expertise. Red Bull GmbH represents the premium-tier archetype through event-ownership and content-studio assets that sustain pricing power independent of ingredient cost structures.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| PepsiCo Inc. |
| Celsius Holdings Inc. |
| Keurig Dr Pepper Inc. |
| The Coca-Cola Company |
| Monster Beverage Corp. |
| Fonterra Co-operative Group Limited |
| Red Bull GmbH |
| Others |
Supply Flow & Price Mechanics
EFSA's tightened botanical health claim substantiation requirements gate both supplier qualification timelines and price differentiation across European functional drink portfolios, compressing margin capture for brands lacking clinical trial resources while rewarding capitalized multinationals with approved generic claim positioning.
Pricing Analysis
Long-term offtake contracts dominate premium botanical sourcing, with spot purchasing limited to commodity vitamin and mineral inputs. Three-tier pricing structure across premium, standard, and economy levels separates cold-aseptic wellness shots with microencapsulation technology from hot-fill energy drinks and private-label nutritional beverages. Price differentiation hinges on certification grade and provenance verification intensity. Cost compression in the energy drink tier is intensifying because private-label entrants and proposed caffeine regulatory caps erode branded pricing power. Health-conscious consumers in urban Brazil and China's tier-one cities demonstrate lowest price sensitivity, while convenience channel night-shift workers in Southeast Asia exhibit highest elasticity.
Supply Chain Analysis
China and India anchor botanical extract processing and raw ingredient refinement for global functional drink formulation. Germany and California concentrate cold-aseptic filling equipment manufacturing and microencapsulation technology deployment. Raw material dependencies center on ashwagandha root from India, ginseng from China and South Korea, and probiotic cultures from Danish and French fermentation facilities. Single-source vulnerability in heat-sensitive bioactive logistics threatens shelf-stability claims during temperature excursion events. Distribution runs through PepsiCo and Coca-Cola bottling infrastructure in convenience channels, with direct-to-subscription WeChat mini-programs displacing traditional retail in Chinese tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The functional drinks market is navigating a cyclical recovery driven by post-pandemic health premium persistence, as consumers retain elevated willingness-to-pay for concentrated efficacy formats despite discretionary budget normalization across broader beverage categories.
For Market Incumbents: Fortify cold-aseptic filling capacity through backward integration or exclusive equipment partnerships to replace stranded hot-fill assets before compliance deadlines. Deepen channel control in convenience retail through shelf-space negotiation leverage against private-label entrants. Prioritize R&D investment in microencapsulation stability claims to defend margin position against wellness shot commoditization.
For New Entrants and Emerging Players: Esports and gaming sponsorship service-layer gaps expose endemic marketing inefficiency among legacy energy drink brands fixated on mass media. India's tier-two cities of Hyderabad, Pune, and Ahmedabad present underpenetrated demand with 60% consumption gaps versus metro benchmarks. Pursue direct-to-subscription models via regional super-app integrations to bypass capital-intensive retail distribution buildouts.
For Investors and Strategic Acquirers: EFSA's pending botanical claim rulings reshape the acquisition landscape by elevating R&D cost thresholds and filtering subscale European brands. Target mid-cap wellness shot producers with completed human intervention studies and approved generic claim positioning. Watch for SAMR formula registration backlog resolution as signal for China market access normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Aseptic Filling Capacity Expansion | Enables heat-sensitive bioactive incorporation for wellness shot differentiation beyond hot-fill commodity formats. |
| Botanical Provenance Verification Program | DNA authentication and blockchain traceability satisfy EFSA evidence thresholds and ANVISA import requirements. |
| Esports Sponsorship Channel Concentration | Endemic marketing efficiency captures caffeine-delivery demand from tournament viewership demographics. |
| Direct-to-Subscription Platform Launch | WeChat mini-program models displace traditional retail discovery among Shanghai and Beijing urban professionals. |
| Regulatory Claim Standardization | Pan-European portfolio harmonization reduces fragmentation costs under EU Nutrition and Health Claims Regulation. |
Methodological Framework
Desk research of FDA GRAS notifications, EFSA health claim registers, and SAMR formula registration databases preceded structured interviews with functional drink brand managers, cold-aseptic equipment manufacturers, botanical extract procurement leads, and retail category buyers. Secondary validation drew from customs import records, Nielsen retail audit data, and company SEC filings. Bottom-up volume modeling triangulated against top-down category spend estimates.
Variance decomposition across product type, ingredient category, end user archetype, packaging format, and regional regulatory cluster shaped analytical framework construction throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation with macroeconomic consumption elasticity assumptions. Forecast inputs incorporated EFSA substantiation timeline probabilities and SAMR registration approval velocity.
Underlying assumptions cover sustained health premium willingness-to-pay and cold-aseptic technology adoption curves, with deviation risk concentrated in caffeine regulatory cap implementations and botanical supply chain climate disruptions. Recalibration cycles align with material shifts in EFSA claim rulings and SAMR policy updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Functional Water Market