
 Stereotactic Body Radiation Therapy Market | 2026-2036
Stereotactic Body Radiation Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Stereotactic Body Radiation Therapy Market Intelligence
Buyer concentration among academic research hospitals and specialty cancer clinics is recalibrating as outpatient oncology centers fragment the customer base with lower-cost hypofractionation services. Siemens Healthineers leverages its imaging-to-therapy platform integration to dominate integrated delivery networks. Elekta AB anchors Nordic and European markets with its linear accelerator specialization. Accuray Incorporated differentiates through robotic delivery systems that compete on motion-tracking precision.
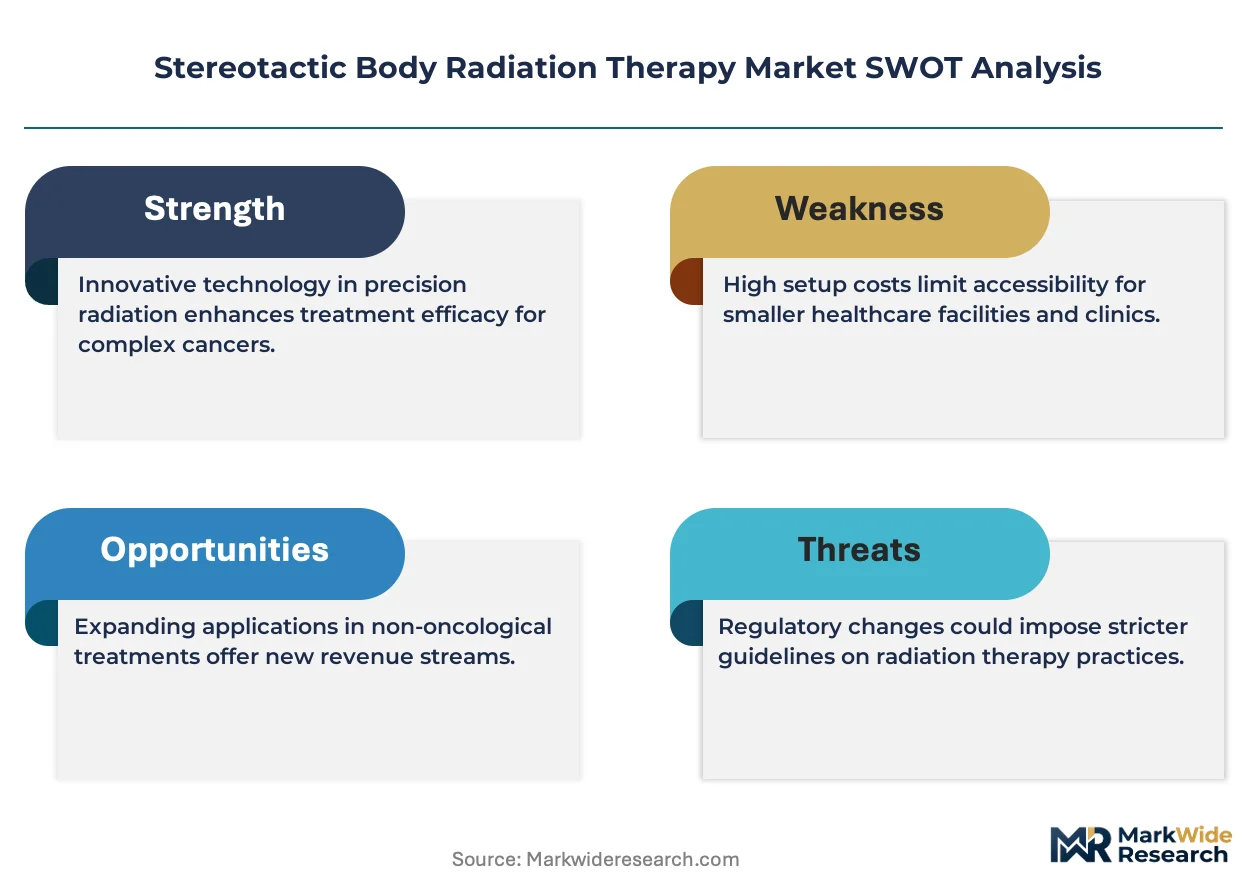
Stereotactic body radiation therapy delivers high-dose, precisely targeted radiation to extracranial tumors using image guidance and rigid immobilization, typically completing treatment in one to five fractions versus conventional six-to-eight-week courses. Its primary purpose is to achieve tumor control equivalent to surgery while sparing adjacent healthy tissue in patients with inoperable or metastatic disease. Linear accelerator systems occupy the largest installed base, while proton beam therapy captures the fastest-growing segment driven by pediatric and re-irradiation indications. Lung tumors and spinal metastases represent the deepest application margin pools where clinical evidence supports broad reimbursement.
FDA 510(k) and PMA pathways govern device clearance, while CMS national coverage determinations shape site-of-service economics for hospital versus freestanding delivery. The EU Medical Device Regulation imposes clinical evidence requirements that filter market access for CyberKnife and TomoTherapy platforms. Stakeholders must monitor evolving NCCN guideline incorporations of SBRT for pancreatic and kidney indications to anticipate coverage expansion decisions.
Market Dynamics
Hypofractionation protocols are compressing treatment timelines from weeks to days, forcing capital deployment decisions around single-session delivery systems versus conventional fractionation infrastructure.
Growth Catalysts
- CMS National Coverage Determinations:Expanded reimbursement for lung and spinal metastases indications validates site-of-service economics for freestanding oncology centers.
- Proton beam pediatric protocols:Re-irradiation tolerance advantages in young patients drive installation demand at major academic research hospitals.
- Linear accelerator versatility:Multi-modality platforms accommodate SBRT, VMAT, and conventional fractionation on single systems, protecting capital utilization rates.
Market Restraints
- Proton facility construction costs:$200 million-plus capital requirements and five-to-seven-year build timelines restrict market entry to institutional consortia.
- Isotope supply concentration:Molybdenum-99 production clusters around aging research reactors in the Netherlands, Canada, and South Africa, creating single-source vulnerability.
- EU MDR clinical evidence requirements:CyberKnife and TomoTherapy platforms face extended conformity assessment timelines that delay market access.
Strategic Opportunities
- India outpatient oncology expansion:PLI scheme incentives for medical device manufacturing align with rising cancer incidence and underpenetrated radiation therapy capacity.
- Artificial intelligence treatment planning:Automated contouring and dose optimization algorithms are integrating with existing linear accelerator workflows to compress planning time.
- Pancreatic SBRT protocols:NCCN guideline incorporation creates pathway for coverage expansion in an indication with limited surgical eligibility.
Industry Challenges
- Medical physics workforce scarcity:Specialized dosimetrist and physicist training programs produce insufficient graduates to staff expanding treatment volumes.
- Legacy PACS integration complexity:Image-guided systems require bidirectional data exchange with hospital information systems that lack standardized DICOM-RT interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stereotactic Body Radiation Therapy Market |
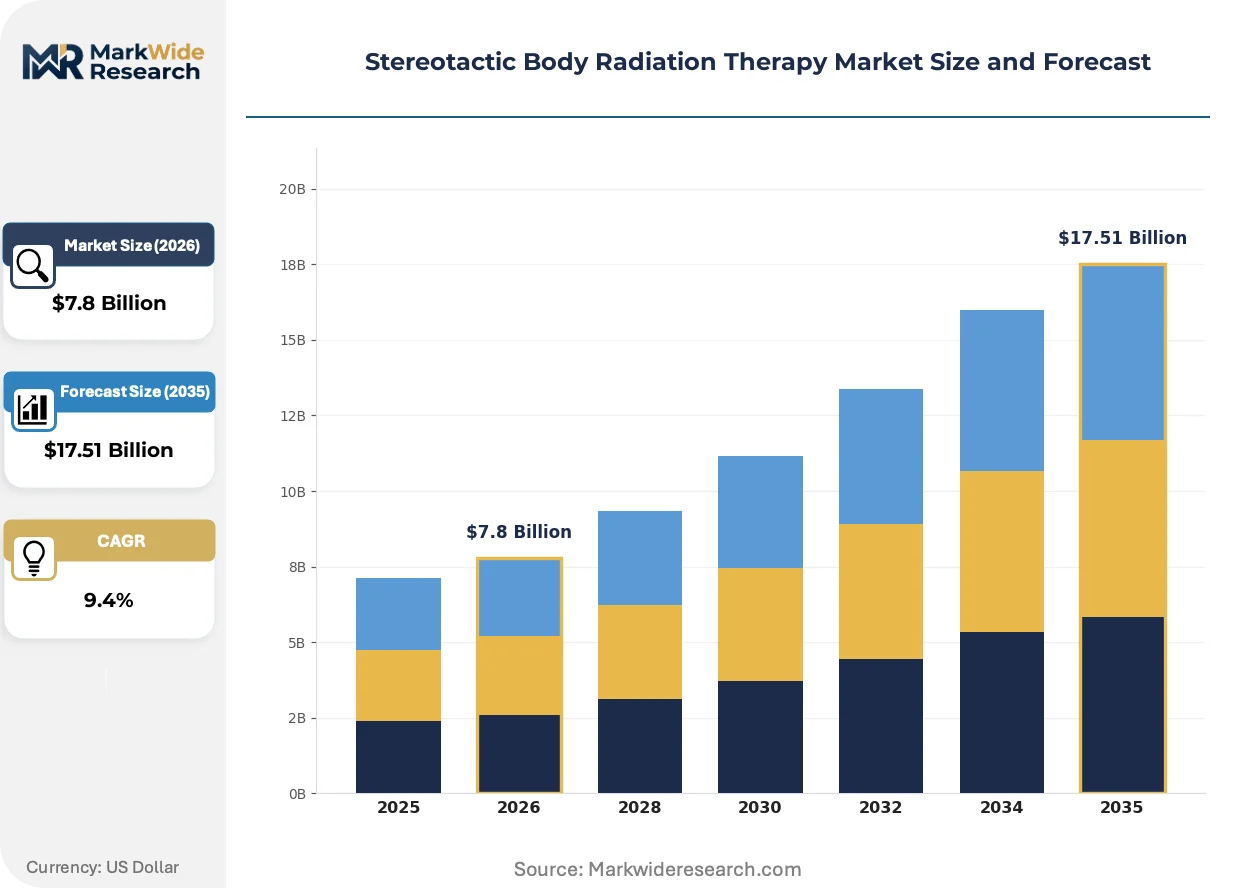
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CyberKnife, Gamma Knife, Proton Beam Therapy, Linear Accelerator, TomoTherapy Application: Lung Tumors, Liver Lesions, Spinal Metastases, Pancreatic Cancer, Kidney Tumors End User: Specialty Cancer Clinics, Academic Research Hospitals, Outpatient Oncology Centers, Community Hospitals Treatment Protocol: Hypofractionation, Conventional Fractionation, Dose Escalation, Image-Guided Therapy |
| Companies Covered | ViewRay Technologies, Inc., Mevion Medical Systems, Siemens Healthineers AG, Brainlab AG, Hitachi Ltd., Elekta AB, IBA Worldwide, GE Healthcare, Accuray Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stereotactic Body Radiation Therapy Market Strategic Shifts & Innovations
Real-time motion management and adaptive planning algorithms are collapsing the latency between imaging and dose delivery, redefining precision thresholds for extracranial targets.
Magnetic resonance-guided linear accelerators are integrating soft-tissue visualization directly into the treatment beam path. Academic research hospitals in Germany and the United States are deploying these hybrid systems for abdominal and pelvic indications where conventional CBCT contrast proves inadequate. The technology is integrating daily plan adaptation that was previously restricted to offline replanning workflows.
The EU Medical Device Regulation imposes clinical evidence requirements that filter market access for robotic delivery platforms. Manufacturers must generate post-market surveillance data comparable to pre-MDR PMA submissions, extending time-to-revenue for new indications. Nordic markets demonstrate accelerated conformity assessment through notified body specialization in radiotherapy devices.
Buyer committees are consolidating vendor relationships around single-source imaging-to-therapy platforms. Integrated delivery networks in the United States are displacing best-of-bread procurement with enterprise agreements that bundle simulation, planning, and delivery systems. This concentration is visible in multi-hospital systems negotiating five-to-seven-year managed service contracts with performance guarantees on machine uptime and planning turnaround.
Stereotactic Body Radiation Therapy Market Segmentation
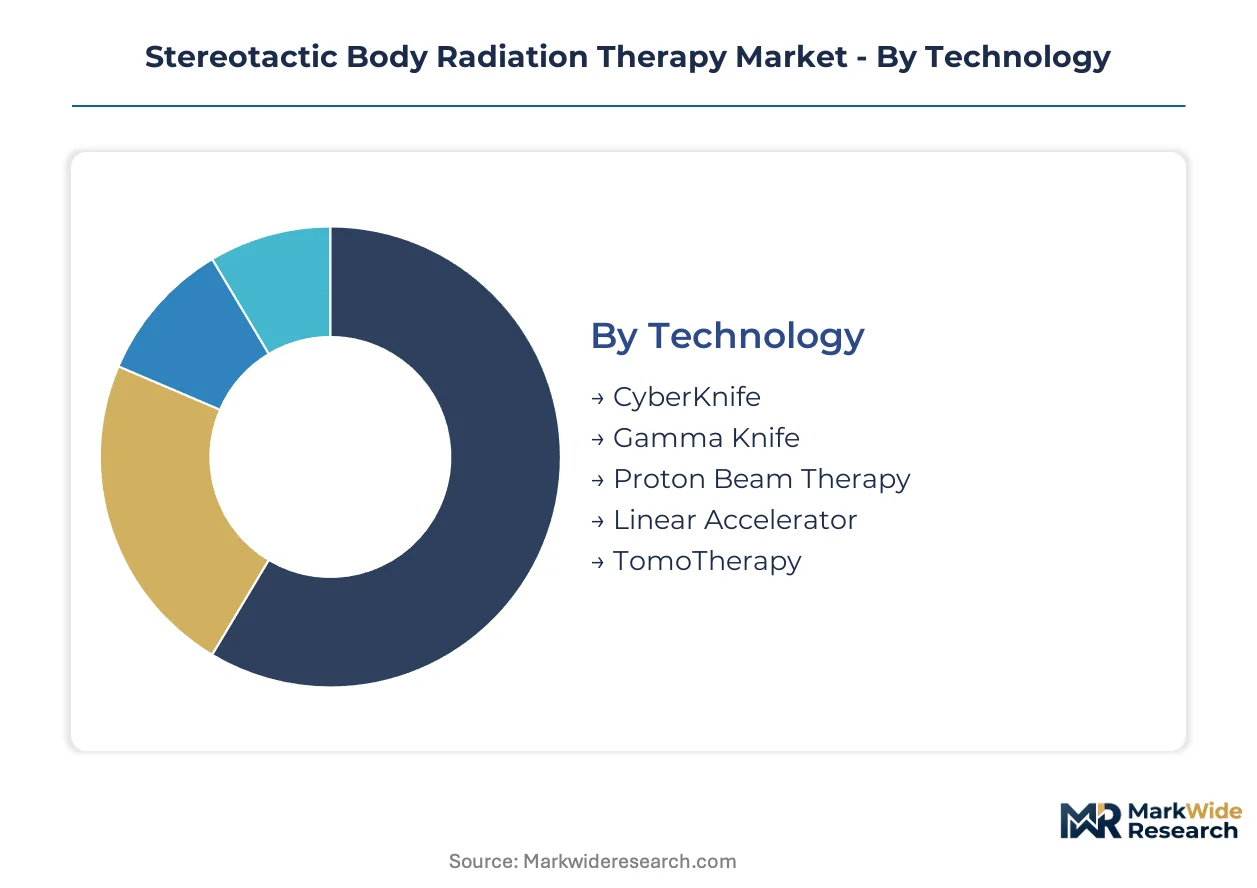
SBRT market segmentation reveals how capital deployment, clinical evidence, and reimbursement pathways interact to shape purchasing decisions. Technology choices determine facility construction economics, while application focus dictates site-of-service strategy and payer contracting leverage.
Technology:
Equipment replacement cycles are compressing as hypofractionation protocols demand real-time motion tracking and adaptive planning capabilities that legacy systems cannot retrofit.
- Linear Accelerator:Multi-modality platforms deliver SBRT, VMAT, and conventional fractionation through a single gantry system. Demand concentrates in Germany and Japan where university hospitals prioritize capital utilization rates across diverse tumor boards.
- Proton Beam Therapy:Bragg peak physics enables dose deposition with minimal exit radiation, critical for pediatric and re-irradiation cases. Academic research hospitals in the United States cluster installations around pediatric oncology centers and ocular melanoma programs.
- CyberKnife:Robotic delivery with real-time tumor tracking accommodates extracranial targets without rigid head frames.
- Gamma Knife:Cobalt-60 sources remain restricted to intracranial applications with limited SBRT crossover potential.
- TomoTherapy:Helical delivery geometry suits craniospinal and total marrow irradiation protocols with SBRT adjacency.
Linear Accelerator sits at the top of the volume ranking, with Proton Beam Therapy climbing the fastest.
Application:
Margin structures vary sharply by indication, with lung and spinal metastases commanding premium reimbursement while pancreatic and kidney protocols await definitive coverage determinations.
- Lung Tumors:Peripheral and central lung lesions represent the most mature reimbursement pathway, with CMS national coverage determinations validating site-of-service economics for freestanding centers. Academic research hospitals in the United States and Germany dominate clinical trial enrollment that shapes guideline incorporation.
- Spinal Metastases:Oligometastatic disease protocols compress treatment to single-fraction delivery, enabling throughput expansion at outpatient oncology centers. Japan's aging demographics concentrate demand for vertebral compression-sparing regimens.
- Liver Lesions:Motion management challenges from respiratory excursion limit adoption to centers with advanced tracking infrastructure.
- Pancreatic Cancer:Borderline resectable protocols show promise but await NCCN guideline elevation for coverage expansion.
- Kidney Tumors:Sparing renal function in solitary kidney patients drives niche demand at specialty cancer clinics.
Lung Tumors command the largest addressable patient population, with Spinal Metastases gaining share fastest as oligometastatic paradigms expand.
End User:
Customer concentration is fragmenting as outpatient oncology centers capture hypofractionation volumes that academic hospitals once monopolized.
- Academic Research Hospitals:Proton beam installations and clinical trial infrastructure anchor technology adoption curves. Centers in the United States, Germany, and Japan generate post-market surveillance data that satisfies EU MDR requirements for device manufacturers.
- Outpatient Oncology Centers:Lower fixed-cost structures enable competitive pricing for lung and spinal metastases protocols. Freestanding models in the United States exploit CMS reimbursement differentials between hospital and non-hospital settings.
- Specialty Cancer Clinics:Focused disease-specific expertise attracts complex case referrals with premium pricing power.
- Community Hospitals:Capital constraints and physics staffing shortages limit SBRT program development to shared-service arrangements.
Academic Research Hospitals retain the highest technology concentration, with Outpatient Oncology Centers expanding most quickly through lower-cost hypofractionation delivery.
Treatment Protocol:
Protocol selection determines staffing ratios, physics workload, and reimbursement coding complexity across delivery sites.
- Hypofractionation:One-to-five fraction regimens compress treatment timelines from weeks to days, demanding robust image guidance and motion management. Adoption concentrates in the United States where CMS reimbursement frameworks validate site economics.
- Image-Guided Therapy:Daily volumetric imaging enables plan adaptation for anatomical changes during treatment courses. German university hospitals pioneer MR-linac integration for soft-tissue visualization.
- Conventional Fractionation:Six-to-eight-week courses persist where hypofractionation evidence remains immature or reimbursement lags.
- Dose Escalation:Biologically equivalent dose intensification protocols require specialized normal tissue tolerance modeling.
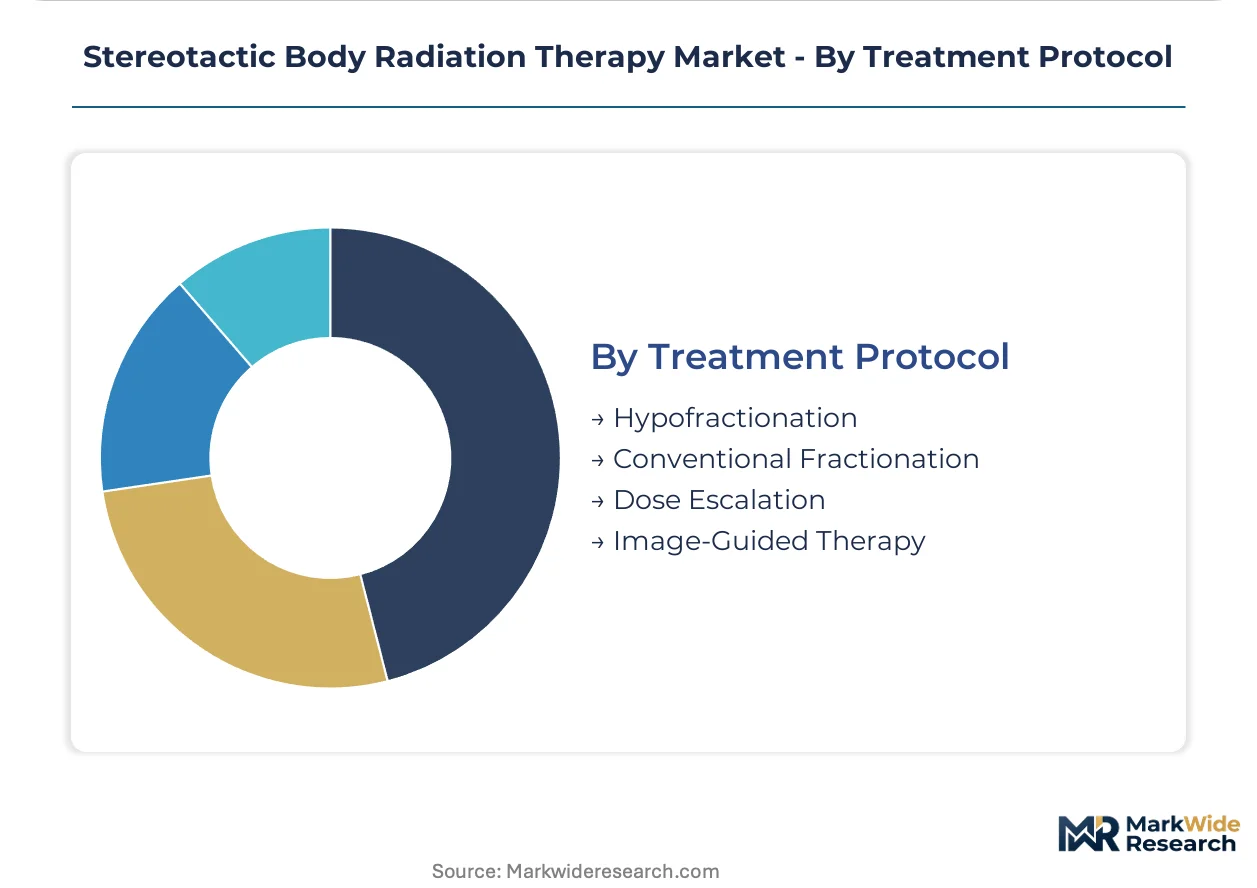
Hypofractionation dominates current protocol selection, with Image-Guided Therapy showing the steepest expansion trajectory as adaptive planning matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical physicist and dosimetrist talent clusters anchor SBRT deployment geography. United States, Germany, and Japan concentrate proton beam and CyberKnife installations around major academic research hospitals. CMS reimbursement frameworks and EU MDR compliance timelines shape capital deployment decisions across markets.
United States
FDA 510(k) and PMA pathways accelerate image-guided system clearances for lung and spinal metastases indications. CMS national coverage determinations validate site-of-service economics, enabling freestanding oncology centers to capture hypofractionation volumes. Major academic research hospitals in Boston, Houston, and Palo Alto cluster proton beam installations around pediatric oncology programs.
Germany
University hospitals prioritize capital utilization rates across multi-modality linear accelerator platforms serving diverse tumor boards. EU MDR clinical evidence requirements filter market access for robotic delivery systems, extending conformity assessment timelines. The Rhine-Ruhr and Munich metropolitan regions concentrate MR-linac deployments for abdominal and pelvic soft-tissue visualization.
Japan
Aging demographics concentrate demand for vertebral compression-sparing spinal metastases regimens delivered in single fractions. METI and PMDA oversight governs radiation therapy device approvals with emphasis on motion-tracking precision standards. Tokyo, Osaka, and Nagoya academic centers anchor CyberKnife and proton beam adoption curves for re-irradiation tolerance.
India
Underpenetrated radiation therapy capacity and rising cancer incidence drive outpatient oncology expansion. PLI scheme incentives for medical device manufacturing align with import substitution goals for linear accelerator components. Maharashtra and Karnataka states concentrate specialty cancer clinic development in Mumbai, Pune, and Bangalore metropolitan corridors.
United Kingdom
NHS England specialized commissioning frameworks determine proton beam therapy referral pathways for pediatric and complex adult indications. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining conformity assessment for established platforms. London, Manchester, and Birmingham academic trusts anchor clinical trial infrastructure generating post-market surveillance data.
Stereotactic Body Radiation Therapy Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the SBRT technology stack. The vendor base organizes around imaging-to-therapy platform integration, linear accelerator specialization, and robotic delivery precision. Three archetypes dominate: integrated health technology conglomerates bundling simulation through delivery, radiation therapy pure-plays optimizing gantry physics, and robotic surgery crossovers applying motion-tracking algorithms. Competitive moves concentrate on five-to-seven-year managed service contracts with uptime guarantees and AI treatment planning integration partnerships.
Among diversified health technology conglomerates, Siemens Healthineers AG and GE Healthcare occupy positions emphasizing imaging-to-therapy workflow integration. Elekta AB and Accuray Incorporated exemplify pure-play radiation therapy specialists competing on linear accelerator versatility and robotic delivery precision respectively. Brainlab AG sits within the surgical navigation crossover tier, applying cranial stereotaxy expertise to extracranial SBRT applications.
| Leading Market Players |
|---|
| ViewRay Technologies, Inc. |
| Mevion Medical Systems |
| Siemens Healthineers AG |
| Brainlab AG |
| Hitachi Ltd. |
| Elekta AB |
| IBA Worldwide |
| GE Healthcare |
| Accuray Incorporated |
| Others |
Cost & Logistics Intelligence
Proton beam versus linear accelerator cost bifurcation creates distinct procurement strata that reshape both capital deployment timelines and supplier-manufacturer relationships across delivery site archetypes. CMS reimbursement differentials between hospital and freestanding settings amplify this divergence, compressing price floors for conventional systems while insulating premium-tier proton installations at academic research hospitals.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for linear accelerator components as PLI scheme incentives attract contract manufacturers away from traditional European supply bases. Three-tier pricing structure across premium proton systems, standard linear accelerators, and economy refurbished platforms reflects FDA PMA tiering and installation complexity rather than hardware margins alone. Cost compression in the economy tier intensifies because refurbished CyberKnife and TomoTherapy units flood secondary markets from EU MDR compliance-driven fleet replacements. Community hospitals exhibit highest price sensitivity, while academic research hospitals absorb premium pricing for pediatric proton protocols and MR-linac integration.
Supply Chain Analysis
Regional distribution centers in the Netherlands, Canada, and South Africa anchor molybdenum-99 isotope flows through aging research reactor infrastructure with limited redundancy. Superconducting magnet assemblies for proton gantries draw from specialized German and Japanese precision manufacturing clusters, while linear accelerator waveguide components source from established North American and European electromechanical suppliers. Single-source vulnerability concentrates around isotope production, where reactor maintenance schedules create unpredictable supply interruptions. Distribution runs through institutional procurement consortia and GPO contracts rather than open-market channels, with major academic systems negotiating direct manufacturer relationships for proton facility construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-integrated treatment planning modules and managed service contracts that convert capital sales into recurring revenue streams. Physics workforce scarcity elevates automation premium capture for vendors solving staffing bottlenecks.
For Market Incumbents: Anticipate displacement from outpatient oncology centers capturing hypofractionation volumes through lower fixed-cost structures by embedding AI treatment planning into existing linear accelerator installed bases. Defend against pure-play software entrants by securing exclusive GPO contracts with performance guarantees on machine uptime and planning turnaround. Prioritize backward integration into superconducting magnet supply for proton system cost control. For New Entrants and Emerging Players: FDA 510(k) pathway streamlining for image-guided accessories in the United States opens a window for motion-tracking sensor and adaptive planning software specialists to penetrate without full system PMA burden. Target India's outpatient oncology expansion in Maharashtra and Karnataka corridors where PLI scheme manufacturing incentives align with radiation therapy capacity gaps. Pursue white-label AI contouring partnerships with established linear accelerator vendors lacking native software development. For Investors and Strategic Acquirers: Consolidation pressure builds where physics workforce scarcity constrains treatment volume expansion at mid-scale outpatient centers. Frame long-term viability around vendors solving staffing automation or securing proton beam pediatric protocol exclusivity. Acquisition target archetype: AI treatment planning pure-plays with FDA-cleared algorithms and hospital system validation data. Watch NCCN guideline elevation for pancreatic SBRT as inflection signal for coverage expansion and valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance for Motion-Tracking Accessories | Accelerates market entry for software-hardware hybrid entrants without full PMA burden. |
| AI Treatment Planning Integration Partnership | Compresses physics staffing requirements while capturing recurring SaaS revenue from linear accelerator installed base. |
| Managed Service Contract with Uptime Guarantees | Locks multi-hospital systems into five-to-seven-year relationships displacing best-of-breed procurement. |
| Proton Beam Pediatric Protocol Expansion | Secures premium pricing at academic research hospitals with re-irradiation tolerance advantages. |
| PLI Scheme Manufacturing Localization in India | Aligns with import substitution goals while capturing outpatient oncology center demand in underpenetrated regions. |
Research Approach
Multiple input streams — primary interviews with radiation oncologists and medical physicists, secondary validation through FDA 510(k) and PMA filings, and hospital procurement database analysis — were reconciled to construct segment-level demand estimates. Conversations with GPO contracts managers, biomedical engineers at academic research hospitals, and equipment planning officers at integrated delivery networks informed capital deployment timing assumptions. CMS national coverage determinations, EU MDR conformity assessment timelines, and METI device approval records provided regulatory pathway benchmarks. Bottom-up treatment volume modeling and top-down equipment replacement cycle analysis were triangulated against manufacturer shipment disclosures.
Data-stream reconciliation across technology, application, end user, and treatment protocol dimensions anchored the analytical framework over the projection horizon. Modeled segmentation captured linear accelerator versus proton beam versus robotic delivery technology choices, lung and spinal metastases versus pancreatic and kidney application maturity, and academic research hospital versus outpatient oncology center site-of-service economics. CAGRs were derived from equipment installation forecasts cross-referenced with hypofractionation protocol adoption curves and reimbursement expansion timelines. Physics workforce supply constraints and isotope production reactor maintenance schedules fed industry-specific sensitivity analyses.
Revisions become necessary when EU MDR conformity assessment timelines extend beyond baseline assumptions, when CMS national coverage determinations expand or contract for pancreatic and kidney indications, or when molybdenum-99 reactor outages disrupt isotope-dependent treatment planning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Nontuberculous Mycobacterium Treatment Market
Medical Treatment
Beta Thalassemia Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Tissue Repair Technologies Market