
 Global Plasma Therapy Market | 2026-2036
Global Plasma Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plasma Therapy Market Foresight
North American fractionation capacity is pivoting toward higher-yield immunoglobulin output as collection volumes expand across the United States and Canada. CSL Limited leverages its vertically integrated plasma collection network to sustain supply security across multiple therapy areas. Grifols, S.A. anchors European production capacity with major fractionation sites in Spain and the United States. Takeda Pharmaceutical Company Limited competes through specialized immunology portfolios and geographic diversification across Asia-Pacific and North American markets.
Plasma therapy comprises the therapeutic application of blood plasma components—primarily immunoglobulins, albumin, and clotting factors—extracted through large-scale fractionation of donated human plasma and administered to treat congenital or acquired protein deficiencies. The process relies on cold ethanol fractionation and chromatographic purification to isolate biologically active proteins with defined purity exceeding 95% for most licensed indications. Plasma-derived immunoglobulins command the dominant value share due to chronic replacement requirements in primary immunodeficiency and expanding off-label neurological applications. Coagulation factors represent the fastest-growing product category structurally, driven by prophylactic hemophilia regimens and extended half-life formulations that reduce infusion frequency.
The US FDA, the European Medicines Agency under MDR frameworks, and the WHO plasma quality guidelines collectively govern viral safety, donor traceability, and lot-release testing standards that determine market access timelines. Japan's PMDA maintains distinct batch-release requirements that extend registration timelines for foreign-sourced plasma products. Stakeholders must monitor regulatory divergence between FDA's evolving pathogen-reduction guidance and EMA's tightening donor-deferral criteria as these will reshape sourcing economics and fractionation investment priorities.
Market Dynamics
Fractionation economics are tightening as plasma collection costs outpace protein yield improvements, forcing operators to optimize every liter through advanced chromatographic recovery and continuous processing architectures.
Growth Catalysts
- Prophylactic hemophilia protocols:Extended half-life factor VIII and IX formulations now enable weekly or biweekly dosing, expanding addressable patient populations and treatment persistence in the United States and Germany.
- EU MDR pathway harmonization:The European Medicines Agency's consolidated plasma master file system accelerates multi-product registrations, reducing redundant viral safety studies for fractionators with established donor pools.
- Neurological immunoglobulin expansion:Chronic inflammatory demyelinating polyneuropathy and multifocal motor neuropathy indications drive off-label utilization in Japan's aging tertiary care centers.
Market Restraints
- Plasma protein supply concentration:Over sixty percent of collectible plasma originates from United States paid-donor centers, creating geopolitical and pandemic-disruption exposure for European and Asian fractionators.
- Albumin price compression:Synthetic colloid substitutes and recombinant albumin development in Chinese biopharma pipelines threaten volume pricing for plasma-derived equivalents.
- FDA donor deferral expansion:Revised vCJD geographic risk criteria disqualify donors from United Kingdom, France, and Ireland residence, constricting eligible donor bases without compensatory yield gains.
Strategic Opportunities
- India's immunodeficiency diagnosis gap:Underdetection of primary immunodeficiency disorders—estimated below fifteen percent of true prevalence—creates latent demand as CDSCO streamlines orphan drug pathways.
- Subcutaneous immunoglobulin home administration:Pump-enabled delivery systems bypass infusion center capacity constraints, opening reimbursement negotiations with United States commercial payers seeking site-of-care cost reduction.
- Pathogen-reduction technology integration:Solvent-detergent and nanofiltration convergence with standard fractionation enables FDA fast-track designation for next-generation viral safety claims.
Industry Challenges
- Plasma collection workforce scarcity:Phlebotomist turnover exceeds thirty percent annually at major United States collection networks, constraining volume growth despite capital-intensive center expansion.
- Lot-release testing backlog:PMDA's mandatory viral marker retesting for imported plasma products extends Japan market entry timelines by eight to fourteen months versus FDA or EMA pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plasma Therapy Market |
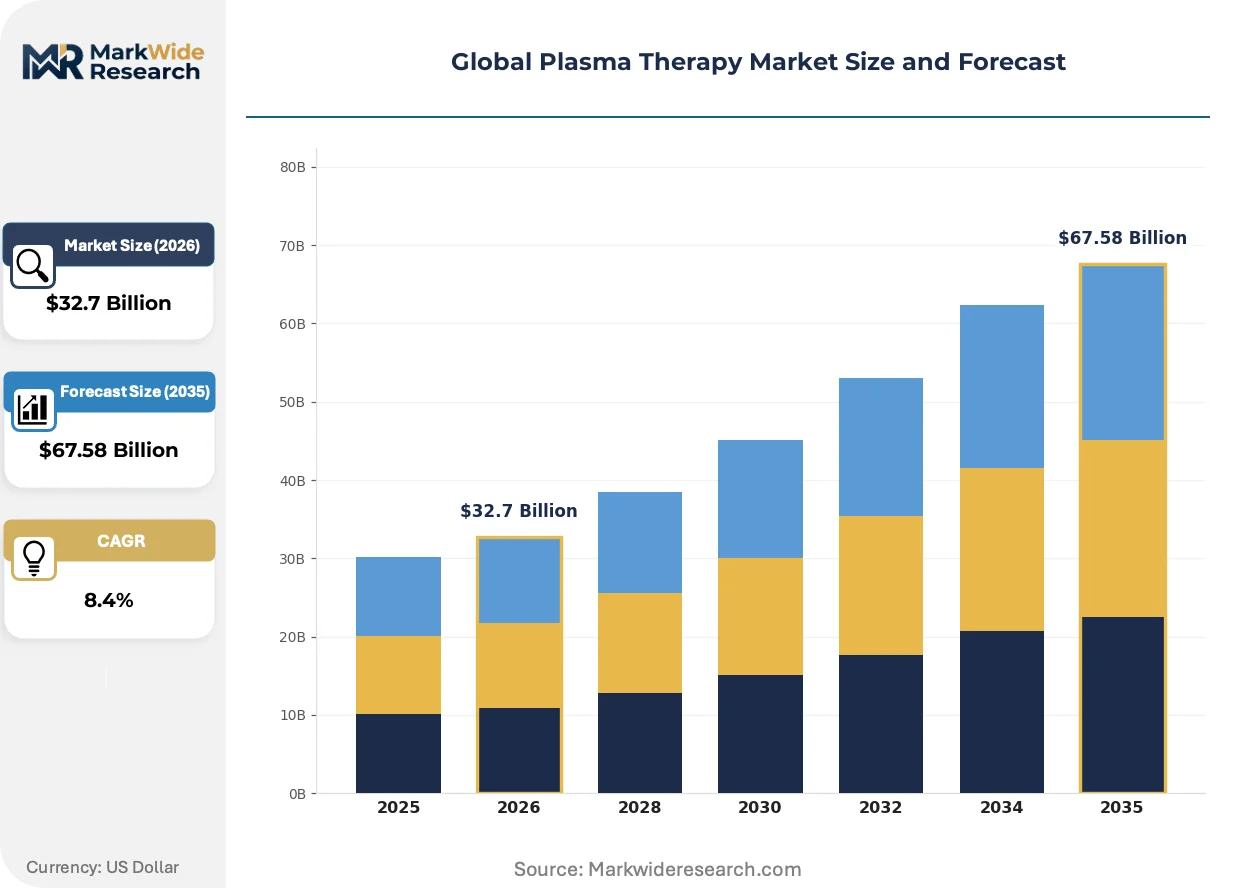
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $67.58 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Immunodeficiency Disorders, Hemophilia, Burns, Neurological Disorders, Autoimmune Diseases Product Type: Fresh Frozen Plasma, Cryoprecipitate, Plasma-Derived Immunoglobulins, Albumin, Coagulation Factors End User: Specialty Clinics, Blood Banks, Research Institutions, Plasma Donation Centers, Rehabilitation Centers Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Transdermal, Oral Supplements |
| Companies Covered | CSL Limited, Grifols, S.A., Takeda Pharmaceutical Company Limited, Octapharma AG, Kedrion S.p.A., Biotest AG, ADMA Biologics, Inc., Bio Products Laboratory Ltd., LFB Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plasma Therapy Market Shifts & Advancements
Digital donor management and continuous bioprocessing are converging to reshape plasma economics, compressing collection-to-release cycles while tightening viral safety margins beyond current pharmacopeial standards.
Automated plasmapheresis platforms equipped with real-time hematocrit monitoring and vein detection algorithms are automating donor throughput optimization at high-volume United States collection sites. CSL and Grifols have deployed these systems across their captive networks, reducing skilled phlebotomist dependency while increasing liters collected per chair-hour. This automation is compressing the labor-cost component of plasma acquisition, partially offsetting rising donor compensation rates.
EMA's tightened donor deferral criteria for Creutzfeldt-Jakob disease risk—mirroring FDA's 2022 geographic expansion—are forcing European fractionators to requalify plasma sourcing from Eastern European collection networks. The industrial consequence is accelerated investment in pathogen-reduction technologies that can demonstrate prion clearance equivalence to geographic exclusion. Plasma-derived medicinal product sponsors with existing solvent-detergent validation are filing supplemental indications to capture this regulatory arbitrage.
Hospital procurement committees in Germany and Japan are unbundling immunoglobulin purchasing from traditional group purchasing organization contracts, establishing direct relationships with fractionators for guaranteed supply allocation. This disintermediation responds to COVID-19-era allocation shortages and enables outcome-based contracting tied to infusion reaction rates and patient adherence metrics. The shift is most visible in German university hospital networks, where pharmacy directors now negotiate multi-year volume commitments independent of regional purchasing cooperatives.
Global Plasma Therapy Market Segmentation
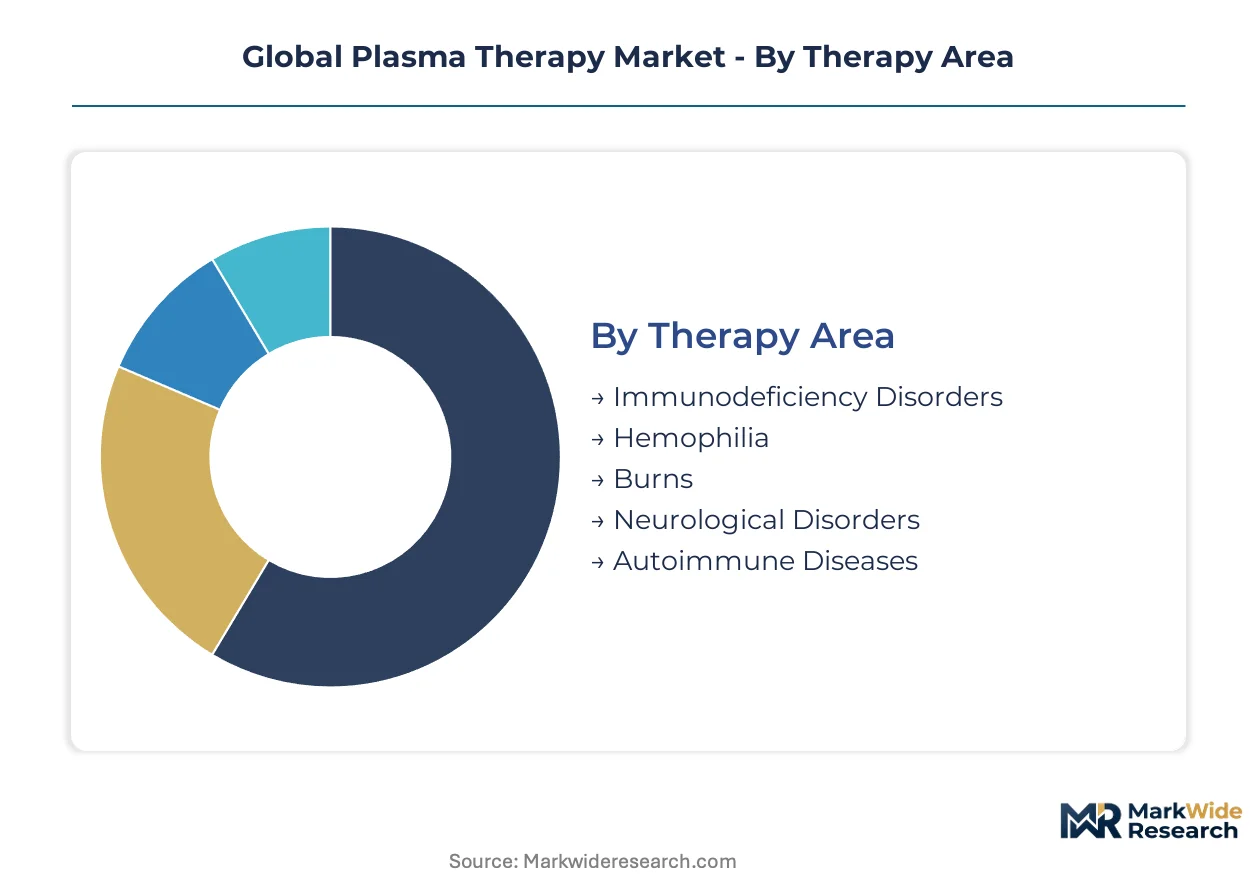
Plasma therapy segmentation reveals distinct procurement patterns across therapy areas and delivery modes. Hospital formularies prioritize immunoglobulin access while reimbursement frameworks shape subcutaneous adoption curves.
Therapy Area:
Standalone chronic replacement therapies dominate procurement budgets, while acute intervention segments embed within broader critical care protocols.
- Immunodeficiency Disorders:Primary and secondary antibody deficiencies require lifelong immunoglobulin replacement, with United States specialty clinics managing the largest treated populations under commercial insurance carve-outs. German hospital networks negotiate multi-year volume commitments to secure supply continuity amid allocation volatility.
- Hemophilia:Congenital factor VIII and IX deficiencies drive prophylactic regimens using extended half-life formulations, with Japanese hemophilia treatment centers adopting weekly dosing protocols to reduce joint deterioration outcomes.
- Burns:Acute fluid resuscitation using albumin and fresh frozen plasma supports thermal injury management in United States burn centers.
- Neurological Disorders:Chronic inflammatory demyelinating polyneuropathy and multifocal motor neuropathy represent off-label immunoglobulin expansion in tertiary neurology departments.
- Autoimmune Diseases:Immune thrombocytopenic purpura and Guillain-Barré syndrome drive episodic high-dose immunoglobulin pulses.
Immunodeficiency leads volumes today; neurological applications are gaining share fastest.
Product Type:
Margin structures diverge sharply between commodity albumin and specialty immunoglobulin fractions, with coagulation factors commanding premium pricing tied to half-life innovation.
- Plasma-Derived Immunoglobulins:Polyclonal antibody preparations from pooled plasma require chromatographic purification exceeding 95% purity standards, with German university hospitals unbundling procurement from group purchasing organizations to secure direct fractionator relationships.
- Coagulation Factors:Factor VIII and IX concentrates support hemophilia prophylaxis, with PMDA batch-release timelines in Japan extending market entry for next-generation extended half-life variants.
- Fresh Frozen Plasma:Unfractionated plasma supports massive transfusion protocols in United States trauma centers.
- Cryoprecipitate:Fibrinogen-rich precipitate enables surgical and obstetric bleeding management.
- Albumin:Human serum albumin faces synthetic colloid substitution pressure in Chinese hospital procurement.
Immunoglobulins dominate revenue concentration; coagulation factors show the steepest expansion trajectory.
End User:
Site-of-care economics reshape demand distribution, with infusion center capacity constraints pushing volume toward home administration channels.
- Specialty Clinics:Dedicated immunology and hematology centers manage chronic replacement therapy populations, with United States commercial payers negotiating site-of-care differentials to shift immunoglobulin administration from hospital outpatient departments.
- Blood Banks:Hospital-based transfusion services coordinate fresh frozen plasma and cryoprecipitate distribution for acute bleeding management.
- Research Institutions:Academic medical centers conduct investigator-initiated trials for novel immunoglobulin indications.
- Plasma Donation Centers:CSL and Grifols operate captive collection networks supplying fractionation feedstock.
- Rehabilitation Centers:Post-acute facilities manage neurological immunoglobulin continuation therapy.
Specialty clinics capture the highest patient volume; home-based administration channels are expanding most quickly.
Delivery Mode:
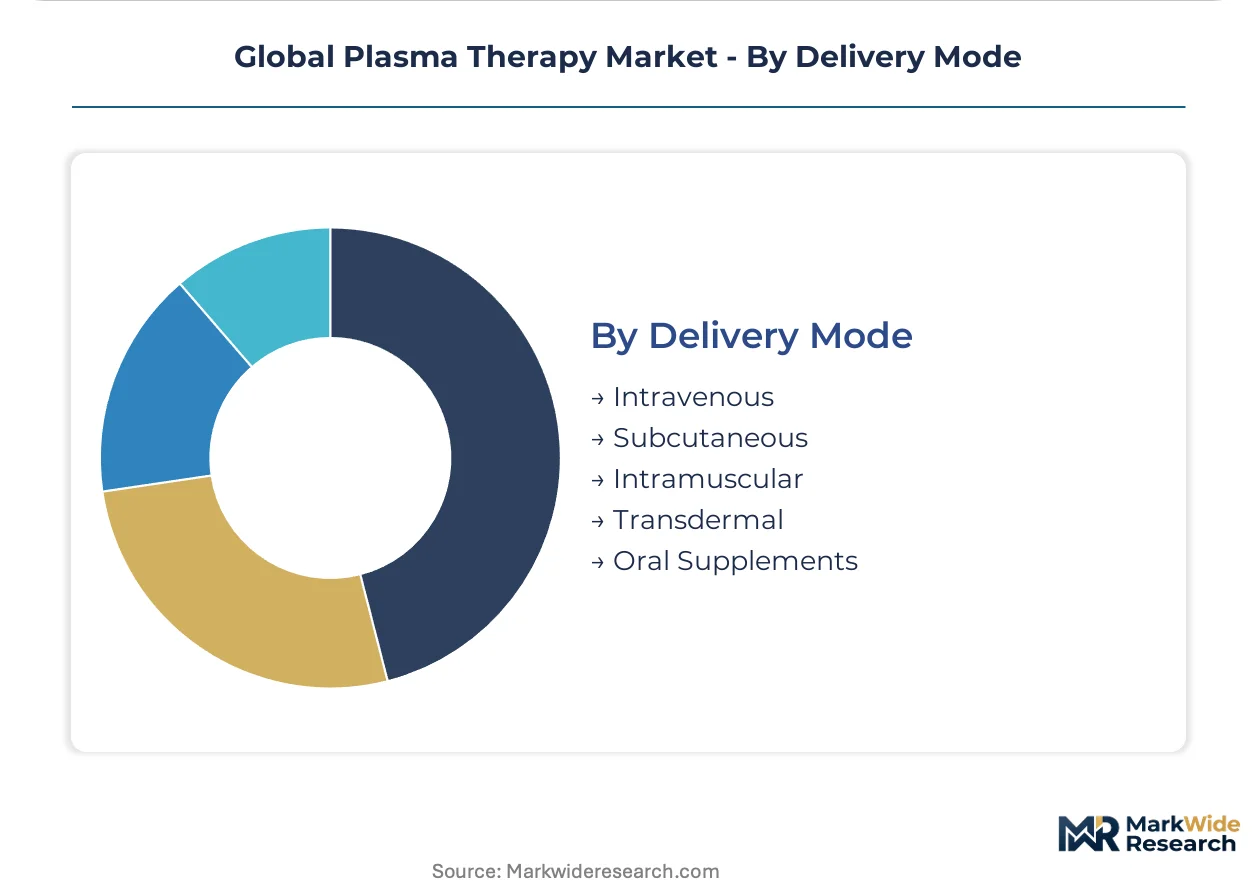
Patient preference and reimbursement alignment determine route selection, with pump technology enabling channel shift from institutional to domestic settings.
- Intravenous:Hospital and infusion center administration of immunoglobulins and coagulation factors requires skilled nursing supervision, with German clinic networks maintaining capacity for high-dose neurological protocols.
- Subcutaneous:Pump-enabled home delivery systems reduce site-of-care costs, with United States commercial payers approving reimbursement for patient-administered immunoglobulin to bypass infusion center bottlenecks.
- Intramuscular:Limited application for specific immunoglobulin formulations in prophylactic settings.
- Transdermal:Experimental delivery platforms remain outside standard of care.
- Oral Supplements:Plasma protein oral formulations lack bioequivalence for therapeutic indications.
Intravenous administration maintains volume leadership; subcutaneous delivery is climbing the fastest as home therapy expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States fractionation infrastructure processes substantially larger plasma volumes than German facilities, yet both markets face tightening donor eligibility criteria that reshape collection economics.
United States
Commercial payers drive site-of-care shifts toward home-based immunoglobulin administration, reducing hospital outpatient dependency. FDA donor deferral expansions for vCJD geographic risk now exclude donors with United Kingdom, France, and Ireland residence history. CSL Limited operates captive collection networks across high-volume centers in Texas, Florida, and California.
Germany
University hospital pharmacy directors negotiate multi-year immunoglobulin volume commitments independent of regional purchasing cooperatives. EMA's consolidated plasma master file system accelerates multi-product registrations for fractionators with established donor pools. Grifols, S.A. anchors European production capacity through major fractionation sites in Barcelona and Frankfurt-Rhine-Main clusters.
Japan
Aging tertiary care centers expand off-label immunoglobulin utilization for chronic inflammatory demyelinating polyneuropathy. PMDA mandatory viral marker retesting for imported plasma products extends market entry timelines by eight to fourteen months versus FDA pathways. Tokyo-Osaka hospital corridors concentrate hemophilia treatment center capacity for extended half-life factor adoption.
India
Underdetection of primary immunodeficiency disorders—estimated below fifteen percent of true prevalence—creates latent therapy demand. CDSCO streamlines orphan drug pathways for plasma-derived medicinal products. Mumbai-Pune pharmaceutical corridors attract fractionation joint ventures targeting domestic immunoglobulin supply security.
China
Domestic biopharma pipelines advance recombinant albumin development threatening plasma-derived volume pricing. NMPA strengthens viral safety batch-release requirements for imported immunoglobulin products. Shanghai-Beijing hospital procurement networks pilot outcome-based contracting for hemophilia prophylaxis regimens.
Global Plasma Therapy Market Competitive Landscape
United States producers anchor one tier; European specialists hold fractionation capacity advantages across immunoglobulin and coagulation factor portfolios. Market structure concentrates around vertically integrated plasma collectors with captive supply networks and regional fractionators dependent on third-party feedstock sourcing. Three archetypes dominate: integrated collector-fractionators, regional plasma product specialists, and emerging market joint venture platforms. Capacity expansion and pathogen-reduction technology licensing constitute the dominant competitive moves reshaping supply security claims.
Within the integrated tier, CSL Limited and Grifols, S.A. exemplify geographic diversification strategies spanning collection networks and fractionation assets across multiple continents. Takeda Pharmaceutical Company Limited occupies a specialized immunology position with Asia-Pacific and North American market presence. These three anchors represent distinct approaches to plasma supply security—captive collection infrastructure, European production scale, and therapeutic portfolio concentration—each responding to regulatory divergence between FDA pathogen-reduction guidance and EMA donor-deferral tightening.
| Leading Market Players |
|---|
| CSL Limited |
| Grifols, S.A. |
| Takeda Pharmaceutical Company Limited |
| Octapharma AG |
| Kedrion S.p.A. |
| Biotest AG |
| ADMA Biologics, Inc. |
| Bio Products Laboratory Ltd. |
| LFB Group |
| Others |
Supply & Pricing Matrix
Phlebotomist workforce concentration across Texas, Florida, and California collection networks creates labor-cost differentials that widen pricing-tier spreads between captive vertically integrated supply and third-party feedstock sourcing.
Pricing Analysis
Capacity additions in Spain and the United States are reshaping price floors for immunoglobulin fractions, compressing margins on standard-grade albumin while preserving premium capture for extended half-life coagulation factors. Three-tier pricing structure across premium, standard, and economy levels stratifies by viral safety certification grade and donor pool traceability depth. Pricing pressure stems from synthetic colloid substitution in Chinese hospital procurement, eroding volume pricing for plasma-derived albumin. Public hospital buyers in Germany and Japan exhibit highest price sensitivity due to fixed reimbursement schedules, while United States specialty clinics show lowest sensitivity under commercial insurance carve-outs.
Supply Chain Analysis
Direct-to-fractionator sourcing agreements now bypass traditional group purchasing organization intermediaries for immunoglobulin procurement in German university hospital networks. Geographic supply concentration in the United States, Germany, and Spain draws from paid-donor collection infrastructure and captive plasma center networks. Raw material dependencies center on source plasma volumes, chromatographic purification resins, and pathogen-reduction validation kits. Single-source vulnerability concentrates in United States paid-donor plasma, where over sixty percent of collectible global feedstock originates. Distribution runs through hospital pharmacy direct contracts, specialty clinic infusion centers, and emerging home administration channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, exploiting the eight-to-fourteen-month registration timeline gap between PMDA batch-release requirements and FDA pathways to capture margin in Japanese immunoglobulin supply.
For Market Incumbents: Anchor supply security through backward integration into Eastern European donor pools as EMA tightens Creutzfeldt-Jakob disease deferral criteria. Defend against recombinant albumin displacement by accelerating solvent-detergent pathogen-reduction validation for premium-tier positioning. Prioritize capacity expansion in Spain and Frankfurt-Rhine-Main clusters to secure European immunoglobulin allocation commitments. For New Entrants and Emerging Players: Begin with India's underdetected primary immunodeficiency population, where diagnosis rates sit below fifteen percent of true prevalence and CDSCO orphan drug pathways are streamlining. Target subcutaneous immunoglobulin home administration as the most penetrable delivery mode, bypassing infusion center capacity constraints through pump-enabled reimbursement negotiations with United States commercial payers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional plasma product specialists lacking captive collection networks but holding fractionation capacity in Eastern Europe or Asia-Pacific. Long-term viability hinges on pathogen-reduction technology licensing positions and regulatory arbitrage capabilities across FDA, EMA, and PMDA divergence. Monitor PMDA batch-release timeline compression as the critical inflection signal for Japanese market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| Pathogen-Reduction Technology Licensing | Enables prion clearance claims that satisfy EMA donor-deferral tightening without geographic exclusion. |
| Plasma Master File Consolidation | Accelerates multi-product EMA registrations for fractionators with established United States donor pools. |
| Subcutaneous Delivery Platform Development | Captures United States commercial payer site-of-care cost reduction mandates through home administration. |
| Eastern European Donor Network Expansion | Requalifies plasma sourcing as FDA and EMA geographic risk criteria disqualify Western European donors. |
| Direct Hospital Procurement Contracting | Bypasses German group purchasing organization intermediaries for guaranteed immunoglobulin supply allocation. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Fractionation operations directors, hospital pharmacy procurement managers, regulatory affairs specialists, and plasma center network operators contributed primary perspectives. Secondary sources include FDA guidance documents, EMA plasma master file submissions, PMDA batch-release protocols, and hospital procurement database extracts. Bottom-up plasma volume modeling triangulates against top-down therapy area demand estimates.
Granularity-level framing applies product-type, therapy-area, delivery-mode, and end-user dimensions at the country level across the analysis window. Immunoglobulin, coagulation factor, and albumin segments were modeled separately with distinct yield and purity assumptions. CAGRs derive from spline-interpolated annual growth rates anchored to reported collection volume trends and fractionation capacity utilization. Forecast inputs incorporate donor deferral expansion impacts, pathogen-reduction adoption curves, and subcutaneous delivery penetration rates.
Several conditions sit outside the modeled scope, including novel recombinant protein substitution timelines, synthetic colloid regulatory approvals, and pandemic-scale collection disruptions. Forecasts reflect documented assumptions about donor recruitment economics and viral safety validation costs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Spain Hair Transplant Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Mesenteric Penniculitis Treatment Market