
 Tissue Repair Technologies Market | 2026-2036
Tissue Repair Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Repair Technologies Market Analysis
Premium biologic grafts and commodity synthetic meshes is shifting into separate procurement channels as hospital value-analysis committees tighten spend controls. Stryker Corporation leverages its orthopedic implant footprint to bundle tissue repair with hardware placements. Arthrex, Inc. anchors its position through surgeon education programs and sports medicine specialization. Smith & Nephew Plc differentiates via advanced wound management portfolios that span acute and post-acute settings.
Tissue repair technologies encompass biomaterial platforms engineered to restore structural integrity across damaged musculoskeletal, cardiovascular, or dermal tissue, typically incorporating collagen matrices, synthetic polymers, or autologous cellular components with porosity specifications ranging from 50 to 500 microns to enable vascular infiltration. These systems serve to reduce reoperation rates, accelerate functional recovery, and lower total episode costs in procedural medicine. Orthopedic applications dominate current volume as joint preservation procedures expand, while regenerative medicine platforms capture expanding margin pools through cell-laden scaffold combinations. Hospitals remain the primary site of care, though clinic-based administration of gel and membrane formats grows fastest as ambulatory surgical migration accelerates.
FDA 510(k) and EU MDR frameworks govern biocompatibility validation and post-market surveillance, extending development timelines but elevating barriers against lower-grade competitors. Japan's PMDA imposes additional clinical data requirements for novel stem cell constructs, channeling investment toward established technology platforms. Stakeholders must monitor reimbursement recalibration for outpatient biologic delivery as site-of-service differentials reshape commercial strategy.
Market Dynamics
Orthopedic surgical centers are consolidating purchasing power through value-analysis committees, forcing biologic graft suppliers to demonstrate episode-cost reductions alongside clinical efficacy. This procurement compression is splitting premium regenerative products from commodity synthetic meshes into separate contracting channels.
Growth Catalysts
- EU MDR compliance frameworks:Elevated biocompatibility validation standards are filtering out lower-grade competitors, creating margin expansion for validated scaffold manufacturers serving European orthopedic networks.
- Joint preservation procedures:Expanding volumes of cartilage restoration surgeries in ambulatory settings are driving demand for cell-laden matrix combinations that accelerate functional recovery timelines.
- Japan's PMDA stem cell pathways:Novel construct approval requirements are channeling R&D investment toward established collagen platform technologies with proven vascular infiltration profiles.
Market Restraints
- Reimbursement recalibration lag:Site-of-service payment differentials between hospital outpatient departments and ambulatory surgical centers create commercial uncertainty for biologic delivery formats.
- Porcine-derived collagen supply concentration:Raw material sourcing clusters in specific agricultural regions expose manufacturers to zoonotic disease transmission risks and export restriction volatility.
- Synthetic polymer degradation variability:Batch-to-batch molecular weight inconsistencies in polylactic acid scaffolds compromise predictive healing timelines, limiting adoption in load-bearing applications.
Strategic Opportunities
- Clinic-based gel administration:Migration of membrane and injectable formats to physician office settings opens direct-to-provider distribution bypassing hospital value committees.
- FDA 510(k) predicate expansion:Leveraging existing collagen matrix clearances for cardiovascular patch indications accelerates regulatory pathways for thoracic surgery applications.
- Germany's Diagnosis-Related Group refinements:Outpatient biologic delivery reimbursement improvements are incentivizing same-day discharge protocols for sports medicine procedures.
Industry Challenges
- Cellular component handling protocols:Cold chain logistics for autologous constructs require specialized infrastructure that ambulatory centers lack, complicating site expansion strategies.
- Post-market surveillance data collection:EU MDR vigilance requirements demand longitudinal patient tracking systems that smaller manufacturers struggle to operationalize cost-effectively.
- Surgeon training standardization:Heterogeneous implantation techniques across orthopedic subspecialties fragment clinical evidence generation and complicate payer negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Repair Technologies Market |
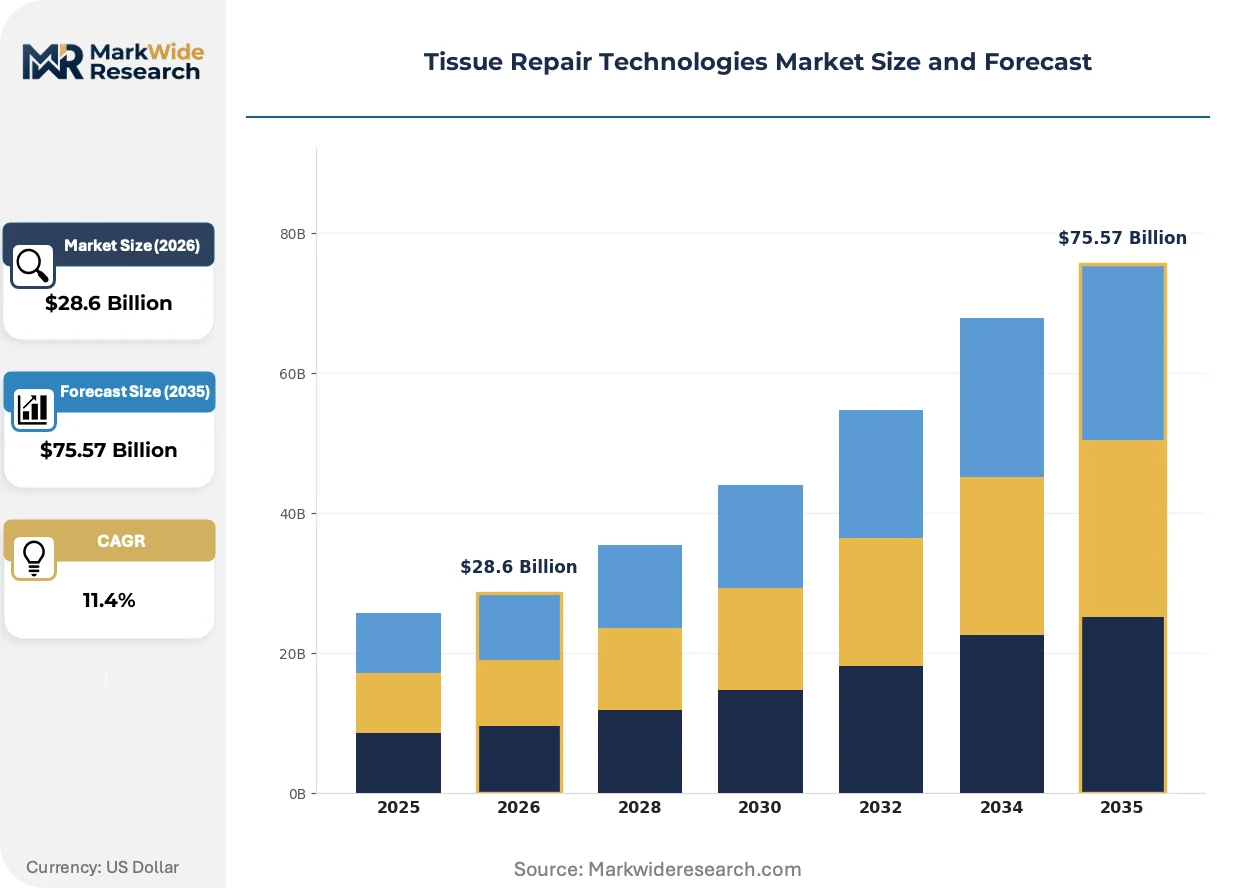
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scaffolds, Gels, Membranes, Adhesives Application: Orthopedics, Cardiology, Dermatology, Neuroprotection End User: Hospitals, Clinics, Research Labs, Rehabilitation Centers Technology: 3D Bioprinting, Stem Cell Therapy, Nanotechnology, Regenerative Medicine |
| Companies Covered | Stryker Corporation, Arthrex, Inc., Smith & Nephew Plc, Integra LifeSciences Corporation, Johnson & Johnson, Medtronic Plc, Becton, Dickinson and Company, Zimmer Biomet Holdings, Inc., Baxter International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Repair Technologies Market Emerging Trajectories
Biomaterial science convergence with digital surgical planning is compressing product development cycles while elevating performance benchmarks for structural integrity restoration. These forces are simultaneously enabling premium pricing for validated platforms and eroding margins for undifferentiated synthetic alternatives.
Electrospun nanofiber collagen matrices with sub-micron porosity gradients are rewriting vascular infiltration kinetics in dermal regeneration applications. Burn centers and plastic surgery units are adopting these constructs for full-thickness wound coverage at accelerating rates. The technology is rewriting competitive positioning by collapsing healing timelines from weeks to days for complex trauma cases.
EU MDR Article 10 technical documentation requirements are extending conformity assessment durations for novel scaffold geometries by twelve to eighteen months. Manufacturers are responding by prioritizing predicate device strategies over breakthrough designations to preserve revenue continuity. Small-cap entrants without established quality management systems face exclusion from European orthopedic supply chains.
Hospital value-analysis committees now mandate total episode cost modeling before biologic graft approval, displacing surgeon preference as the primary purchasing determinant. This behavioral shift is restructuring sales force deployment toward health economics evidence generation rather than clinical education alone. The transformation is most visible in United States integrated delivery networks where orthopedic spend consolidation has centralized procurement authority.
Tissue Repair Technologies Market Segmentation
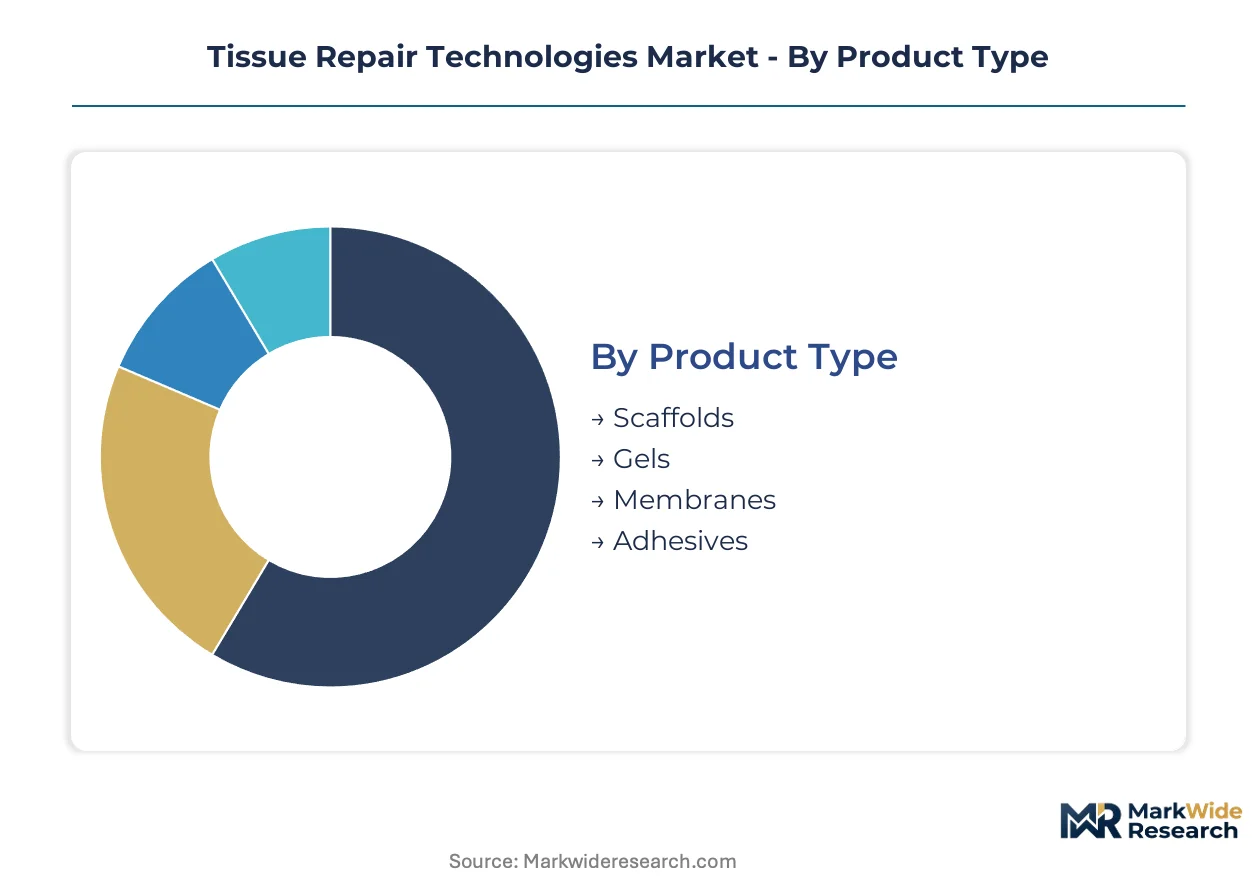
Tissue repair technologies fragment across multiple technical and commercial axes, each carrying distinct margin profiles and regulatory pathways. Understanding these divisions reveals where procurement power concentrates and which innovation vectors command premium positioning.
Product Type:
Porosity specifications and structural load-bearing capacity differentiate commercial viability across implantable formats.
- Scaffolds:Collagen and synthetic polymer matrices with 50-500 micron pore architectures enable vascular infiltration in load-bearing orthopedic applications. Demand clusters in United States ambulatory surgical centers where joint preservation procedures are migrating from inpatient settings, though batch-to-batch molecular weight inconsistencies in polylactic acid variants limit adoption in high-stress reconstructions.
- Gels:Injectable hyaluronic acid and fibrin-based formulations facilitate minimally soft tissue augmentation and wound bed preparation. Clinic-based administration in Germany is expanding fastest as Diagnosis-Related Group refinements incentivize same-day discharge protocols, bypassing hospital value-analysis committee procurement friction.
- Membranes:Barrier functions for guided tissue regeneration in periodontal and orthopedic indications.
- Adhesives:Synthetic and biologic sealants for hemostasis and tissue approximation in cardiovascular and general surgery.
Mature deployment sits with scaffolds in orthopedic hardware bundles. Newer deployment is concentrated in gel formats for clinic-based sports medicine delivery.
Application:
Procedural volume and reimbursement density determine addressable market per therapeutic area.
- Orthopedics:Cartilage restoration, tendon repair, and spinal fusion applications dominate current procedural volumes. Stryker Corporation bundles biologic grafts with implant hardware in United States integrated delivery networks, while Arthrex surgeon education programs drive sports medicine adoption in ambulatory settings.
- Cardiology:Cardiovascular patches and pericardial substitutes require extended biocompatibility validation under FDA 510(k) pathways. Predicate device strategies leveraging existing collagen matrix clearances are accelerating thoracic surgery applications, though EU MDR Article 10 technical documentation requirements extend conformity assessments.
- Dermatology:Full-thickness wound coverage and burn reconstruction utilizing electrospun nanofiber matrices.
- Neuroprotection:Dural substitutes and nerve conduit applications with specialized handling protocols.
Volume leadership resides in orthopedics. Steepest expansion trajectory is emerging in cardiology as predicate pathways compress development timelines.
End User:
Site-of-service economics and infrastructure requirements reshape distribution channel priorities.
- Hospitals:Inpatient and outpatient surgical departments with centralized procurement authority through value-analysis committees. Smith & Nephew Plc positions advanced wound management portfolios across acute and post-acute settings, though reimbursement recalibration lags between hospital outpatient departments and ambulatory centers create commercial uncertainty.
- Clinics:Physician office-based surgical and injection procedures with direct-to-provider distribution potential. Cold chain logistics limitations for autologous constructs constrain cellular therapy expansion, but gel and membrane formats are migrating fastest as infrastructure requirements remain minimal.
- Research Labs:Preclinical and clinical trial supply for novel construct development.
- Rehabilitation Centers:Post-acute tissue repair support and functional recovery monitoring.
Procurement authority concentrates in hospitals. Patient volume is shifting fastest toward clinics as site-of-service differentials reshape commercial strategy.
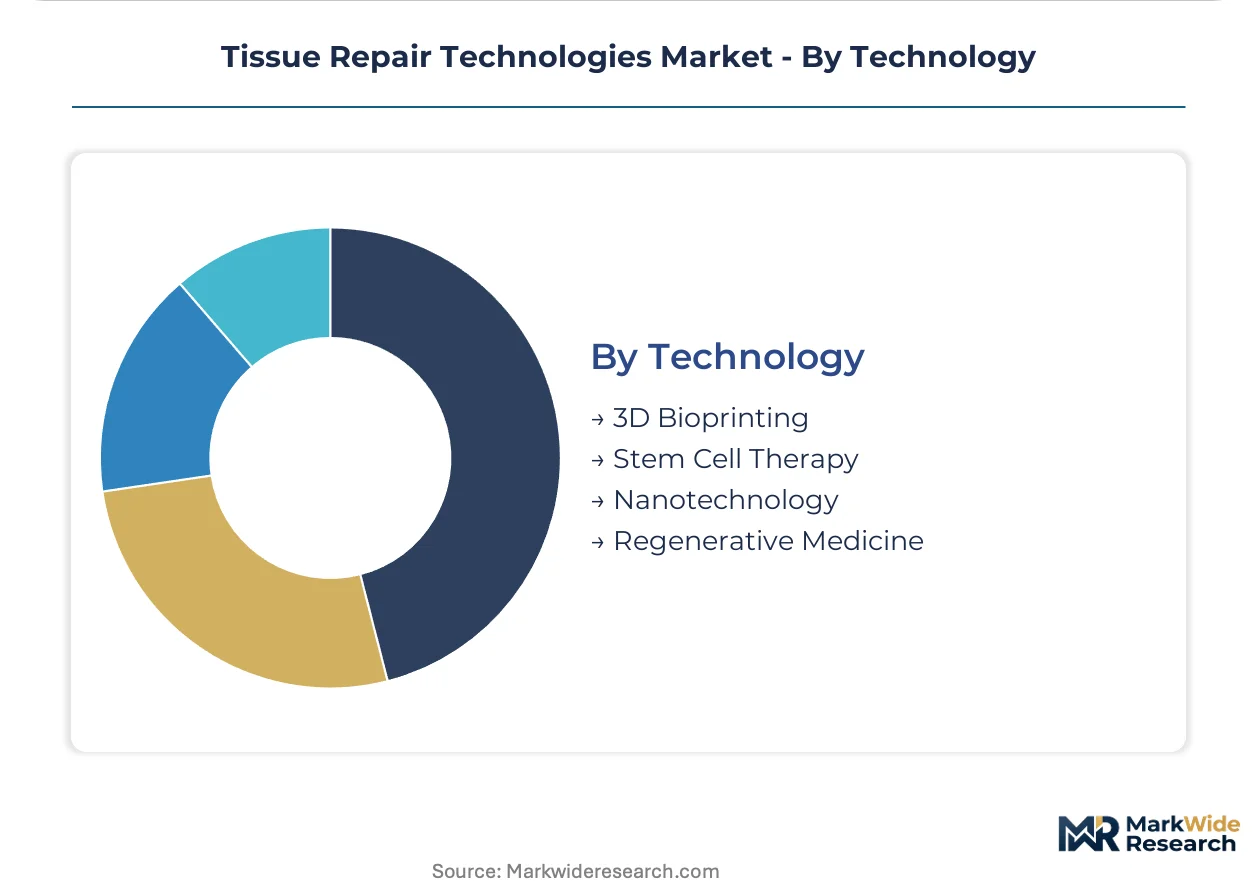
Technology:
Platform maturity and regulatory validation depth separate investable opportunities from speculative development.
- 3D Bioprinting:Layer-by-layer fabrication of cell-laden constructs with patient-specific geometries. Japan's PMDA imposes additional clinical data requirements for novel stem cell constructs, channeling investment toward established collagen platform technologies with proven vascular infiltration profiles rather than unvalidated bioprinted architectures.
- Stem Cell Therapy:Autologous and allogeneic cellular constructs with regenerative potential. EU MDR vigilance requirements demand longitudinal patient tracking systems that smaller manufacturers struggle to operationalize cost-effectively, elevating barriers against lower-grade competitors.
- Nanotechnology:Electrospun matrices and nanoparticle delivery systems for enhanced bioactivity.
- Regenerative Medicine:Convergent platforms integrating scaffolds, cells, and signaling molecules.
Established revenue flows through regenerative medicine platforms. Regulatory investment is concentrating in stem cell therapy as PMDA and FDA pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Route 128 corridor anchors regenerative medicine R&D concentration, with orthopedic surgical centers in Massachusetts General Hospital and Brigham and Women's Hospital driving clinical adoption of advanced scaffold technologies. Germany's Rhine-Main biotechnology cluster and Japan's Kansai medical device manufacturing belt complete the triad of tissue repair innovation gravity.
United States
Integrated delivery networks in Texas and Florida are consolidating orthopedic procurement through value-analysis committees, demanding episode-cost evidence for biologic graft adoption. FDA 510(k) clearance pathways enable rapid predicate device expansion for cardiovascular patch applications. The Greater Boston area hosts electrospun nanofiber research facilities translating academic scaffold innovations into commercial burn center deployments.
Germany
Diagnosis-Related Group refinements in Bavaria and North Rhine-Westphalia are incentivizing same-day discharge protocols for sports medicine procedures, accelerating clinic-based gel administration. EU MDR compliance frameworks filter lower-grade competitors from European orthopedic supply chains. The Rhine-Main biotechnology cluster concentrates collagen matrix manufacturing for thoracic surgery patch applications.
Japan
PMDA stem cell construct requirements channel R&D investment toward established collagen platforms with proven vascular infiltration profiles in Osaka and Nagoya manufacturing zones. Joint preservation procedures in Tokyo ambulatory centers drive demand for cell-laden matrix combinations. The Kansai medical device belt specializes in autologous construct cold chain logistics for cellular therapy distribution.
United Kingdom
NHS England procurement frameworks are tightening spend controls on premium biologic grafts, splitting regenerative products from commodity synthetic meshes into separate contracting channels. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment timelines. London's Imperial College and Cambridge biomedical clusters advance 3D bioprinting research for patient-specific scaffold geometries.
Switzerland
Swissmedic vigilance requirements for novel scaffold geometries elevate barriers against undifferentiated synthetic alternatives in Zurich and Basel manufacturing corridors. Private clinic networks in Geneva and Lausanne bypass hospital value committees through direct-to-provider gel distribution. The Swiss orthopedic research consortium advances electrospun matrix applications for full-thickness wound reconstruction.
Tissue Repair Technologies Market Vendor Landscape
Premium-margin players sit above commodity-margin players across biocompatibility validation depth and predicate device portfolio breadth. Orthopedic surgical centers consolidate purchasing power through value-analysis committees, forcing suppliers to demonstrate episode-cost reductions alongside clinical efficacy. Three strategic archetypes dominate: diversified medical device conglomerates with orthopedic hardware bundling capabilities, sports medicine specialists with surgeon education platforms, and advanced wound management portfolio operators spanning acute and post-acute settings. M&A activity targets cellular therapy cold chain logistics capabilities, while strategic partnerships concentrate on health economics evidence generation for payer negotiations.
Within the diversified conglomerate tier, Stryker Corporation and Johnson & Johnson occupy positions enabling orthopedic implant footprint leverage for tissue repair bundling. Among sports medicine specialists, Arthrex, Inc. exemplifies surgeon education program anchoring for ambulatory procedural volume capture. Smith & Nephew Plc represents the advanced wound management archetype with portfolio spanning acute hospital and post-acute settings. These three entities illustrate how regulatory validation depth and site-of-service commercial strategy separate margin tiers in procurement-compressed markets.
| Leading Market Players |
|---|
| Stryker Corporation |
| Arthrex, Inc. |
| Smith & Nephew Plc |
| Integra LifeSciences Corporation |
| Johnson & Johnson |
| Medtronic Plc |
| Becton, Dickinson and Company |
| Zimmer Biomet Holdings, Inc. |
| Baxter International, Inc. |
| Others |
Supply Flow & Price Mechanics
EU MDR Article 10 technical documentation requirements gate qualified supply access and premium-tier pricing power by elevating biocompatibility validation costs beyond smaller manufacturer reach. Hospital value-analysis committees exploit this regulatory filtering to compress episode-cost modeling for biologic graft procurement, forcing suppliers to demonstrate total cost reductions alongside clinical efficacy.
Pricing Analysis
Outcome-linked pricing anchors biologic graft valuations to reoperation rate reductions and functional recovery acceleration metrics. Three-tier pricing structure across premium regenerative, validated standard, and commodity synthetic tiers differentiates by FDA 510(k) predicate depth and EU MDR certification status. Cost compression in synthetic polymer scaffolds intensifies due to batch-to-batch molecular weight inconsistencies that compromise predictive healing timelines. Ambulatory surgical centers exhibit highest price sensitivity as site-of-service payment differentials create procurement uncertainty, while integrated delivery networks with centralized value-analysis authority negotiate least sensitive contract terms.
Supply Chain Analysis
Regional distribution centers in Massachusetts, Bavaria, and Osaka coordinate hub-and-spoke patterns for temperature-sensitive cellular constructs and ambient-stable matrix formats. Raw material sourcing draws from United States porcine collagen processing, German synthetic polymer synthesis, and Japanese autologous cell handling infrastructure. Single-source vulnerability concentrates in porcine-derived collagen supply clusters exposed to zoonotic disease transmission risks and agricultural export restrictions. Distribution runs through orthopedic surgical center networks for implantable scaffolds and direct-to-provider channels for clinic-based gel administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue repair technologies market constitutes a vertical-integration race where backward control over porcine collagen processing and cold chain logistics for autologous constructs separates margin tiers. Incumbents and entrants alike must secure upstream raw material assurance and downstream site-of-service channel access to defend positioning.
For Market Incumbents: Hedge against synthetic polymer degradation variability by securing captive collagen matrix supply through agricultural processing partnerships or acquisition. Expand EU MDR-certified manufacturing footprint in Rhine-Main biotechnology cluster to filter lower-grade competitors from European orthopedic supply chains. Prioritize health economics evidence generation for value-analysis committee negotiations over clinical education alone. For New Entrants and Emerging Players: Begin with clinic-based gel administration in Germany where Diagnosis-Related Group refinements incentivize same-day discharge protocols and bypass hospital procurement friction. Target ambulatory sports medicine settings with injectable hyaluronic acid formulations requiring minimal cold chain infrastructure. Pursue direct-to-provider distribution partnerships rather than centralized hospital value-committee engagement. For Investors and Strategic Acquirers: FDA 510(k) predicate expansion announcements for cardiovascular patch indications signal accelerating thoracic surgery platform viability. Long-term positioning favors established collagen platform technologies with proven vascular infiltration profiles over unvalidated 3D bioprinted architectures. Acquisition focus should center on cellular therapy cold chain logistics capabilities and electrospun nanofiber manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Article 10 technical documentation elevates barriers against undifferentiated synthetic competitors in European orthopedic networks. |
| Porcine Collagen Supply Integration | Backward control over agricultural processing insulates against zoonotic disease transmission export restrictions. |
| Clinic-Based Distribution Buildout | Direct-to-provider gel administration in Germany bypasses hospital value-analysis committee procurement compression. |
| Health Economics Evidence Generation | Episode-cost modeling satisfies integrated delivery network value-analysis requirements for biologic graft adoption. |
| Electrospun Nanofiber Scale-Up | Sub-micron porosity gradient manufacturing accelerates burn center and plastic surgery unit adoption timelines. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this tissue repair technologies assessment. Primary interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with FDA 510(k) clearance databases, EU MDR technical documentation registries, and hospital procurement spend analytics. Bottom-up scaffold and gel volume modeling triangulated against top-down regenerative medicine market sizing.
Segment-level granularity modeled product type across scaffolds, gels, membranes, and adhesives; application across orthopedics, cardiology, dermatology, and neuroprotection; and end user across hospitals, clinics, research labs, and rehabilitation centers. CAGRs derived from procedure volume migration trends and reimbursement recalibration trajectories across the analysis window. Forecast inputs incorporated joint preservation procedure expansion rates and site-of-service differential evolution.
Underlying measurement precision varies by segment; orthopedic scaffolds and cardiology patches carry tighter precision than emerging 3D bioprinted constructs due to predicate device availability and regulatory pathway maturity. Forecasts reflect assumptions regarding EU MDR compliance timeline stability, porcine collagen supply continuity, and ambulatory surgical migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Cleft Lip Surgery Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Lyme Disease Treatment Market