
 Nontuberculous Mycobacterium Treatment Market | 2026-2036
Nontuberculous Mycobacterium Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Nontuberculous Mycobacterium Treatment Market Analytics
Combination therapy bundling is repositioning how hospital formularies evaluate NTM treatment protocols. Insmed leverages its inhaled liposomal amikacin platform to anchor respiratory delivery leadership among specialty clinics. Teva Pharmaceuticals competes through generic macrolide manufacturing scale that sustains cost advantages across broad-spectrum mycobacterial indications. Cipla differentiates via geographic dominance in emerging markets where oral rifamycin access remains constrained by supply chain fragmentation.
Nontuberculous mycobacterium treatment encompasses antimicrobial regimens targeting environmental mycobacterial species such as Mycobacterium avium complex and Mycobacterium abscessus, typically involving prolonged multi-drug courses of macrolides, rifamycins, and aminoglycosides administered over 12–18 months to achieve culture conversion in immunocompromised and structural lung disease patients. Macrolides occupy the largest therapeutic share due to clarithromycin's established efficacy against MAC, while inhalation delivery modes represent the fastest-expanding configuration as nebulized formulations bypass systemic toxicity thresholds associated with intravenous aminoglycoside exposure. The chronic lung disease therapy area generates the deepest margin pools because treatment durations extend across years and require sustained monitoring through specialty pulmonary networks.
The FDA governs antimicrobial efficacy endpoints and inhaled drug device combinations, while the EMA's MDR framework imposes post-market surveillance obligations on European sponsors of novel mycobacterial therapies. These dual regulatory tracks elevate clinical trial costs but simultaneously protect innovators that secure orphan drug designations for refractory NTM strains. Stakeholders must monitor how CMS reimbursement reclassification of inhaled antibiotics affects site-of-care migration from hospital infusion centers to home administration models.
Market Dynamics
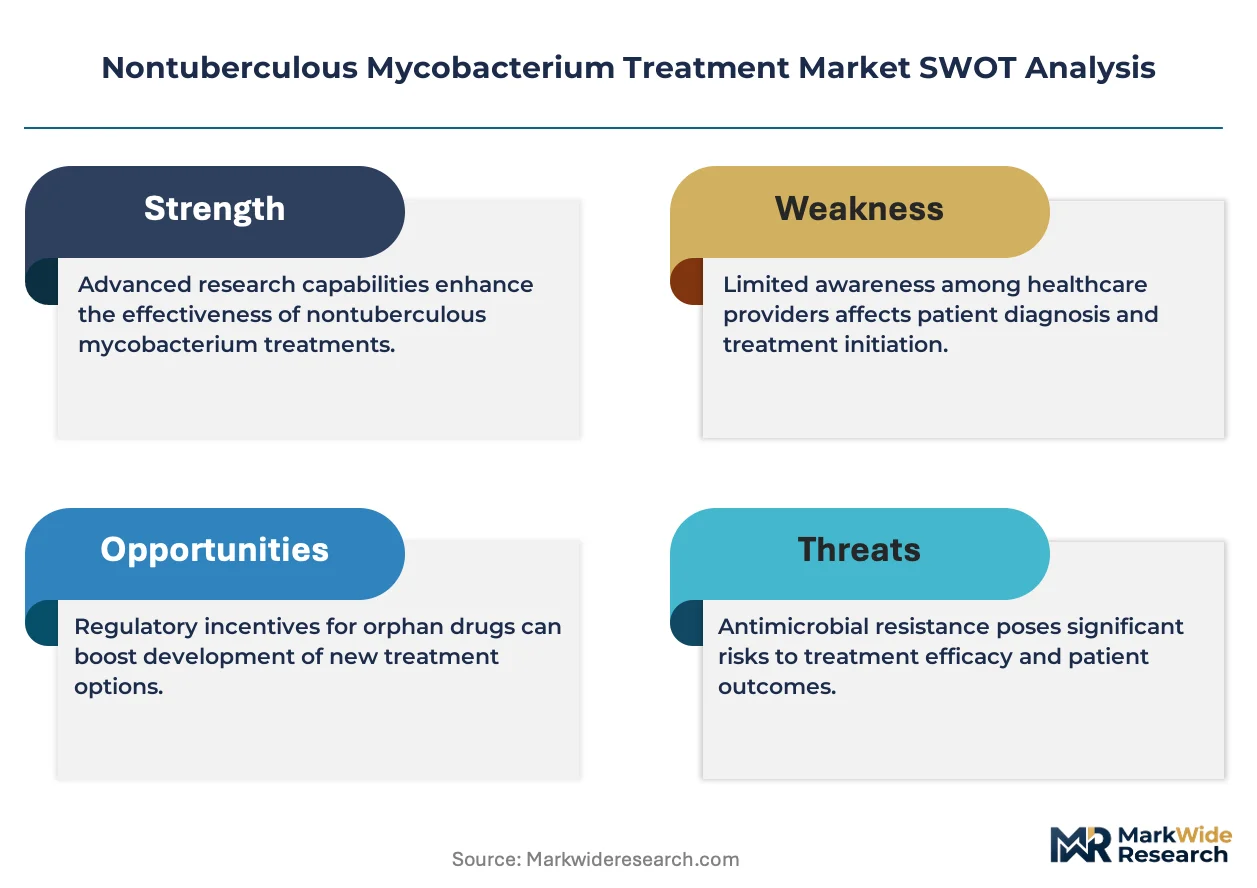
Hospital procurement of combination macrolide-rifamycin regimens is consolidating treatment protocols as pulmonologists seek streamlined administration pathways. The FDA's updated guidance on inhaled antimicrobial formulations is reshaping how manufacturers prioritize bronchiectasis populations in their development pipelines.
Growth Catalysts
- Medicare Reimbursement Pathways:Mature reimbursement frameworks for chronic NTM lung disease management in the United States are accelerating site-of-care migration toward outpatient specialty clinics.
- Inhalation Delivery Technology:Nebulized liposomal formulations are bypassing systemic toxicity thresholds that previously limited intravenous aminoglycoside exposure duration.
- Orphan Drug Designations:EMA's MDR framework protections for refractory NTM strains are incentivizing sponsors to pursue novel mycobacterial therapies through accelerated regulatory channels.
Market Restraints
- Prolonged Treatment Duration:Standard 12–18 month multi-drug courses create substantial adherence barriers and monitoring burdens for immunocompromised patient populations.
- Supply Chain Fragmentation:Oral rifamycin access remains constrained in emerging markets where distribution networks lack cold-chain integrity for temperature-sensitive formulations.
- Clinical Trial Cost Escalation:Dual FDA-EMA regulatory tracks impose redundant efficacy endpoint requirements that elevate development expenditures for antimicrobial sponsors.
Strategic Opportunities
- Home Administration Models:CMS reimbursement reclassification of inhaled antibiotics is enabling patient migration from hospital infusion centers to residential care settings.
- Chronic Lung Disease Networks:Specialty pulmonary monitoring infrastructure represents underutilized channels for sustained therapy management and adherence optimization.
- Combination Therapy Bundling:Hospital formulary evaluation protocols are creating procurement advantages for integrated macrolide-rifamycin regimen suppliers.
Industry Challenges
- Culture Conversion Monitoring:Microbiological laboratory capacity shortages delay treatment response assessment and regimen adjustment decisions.
- Multi-Drug Resistance Surveillance:Mycobacterium abscessus strain tracking requires specialized reference laboratory networks that remain geographically sparse.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nontuberculous Mycobacterium Treatment Market |
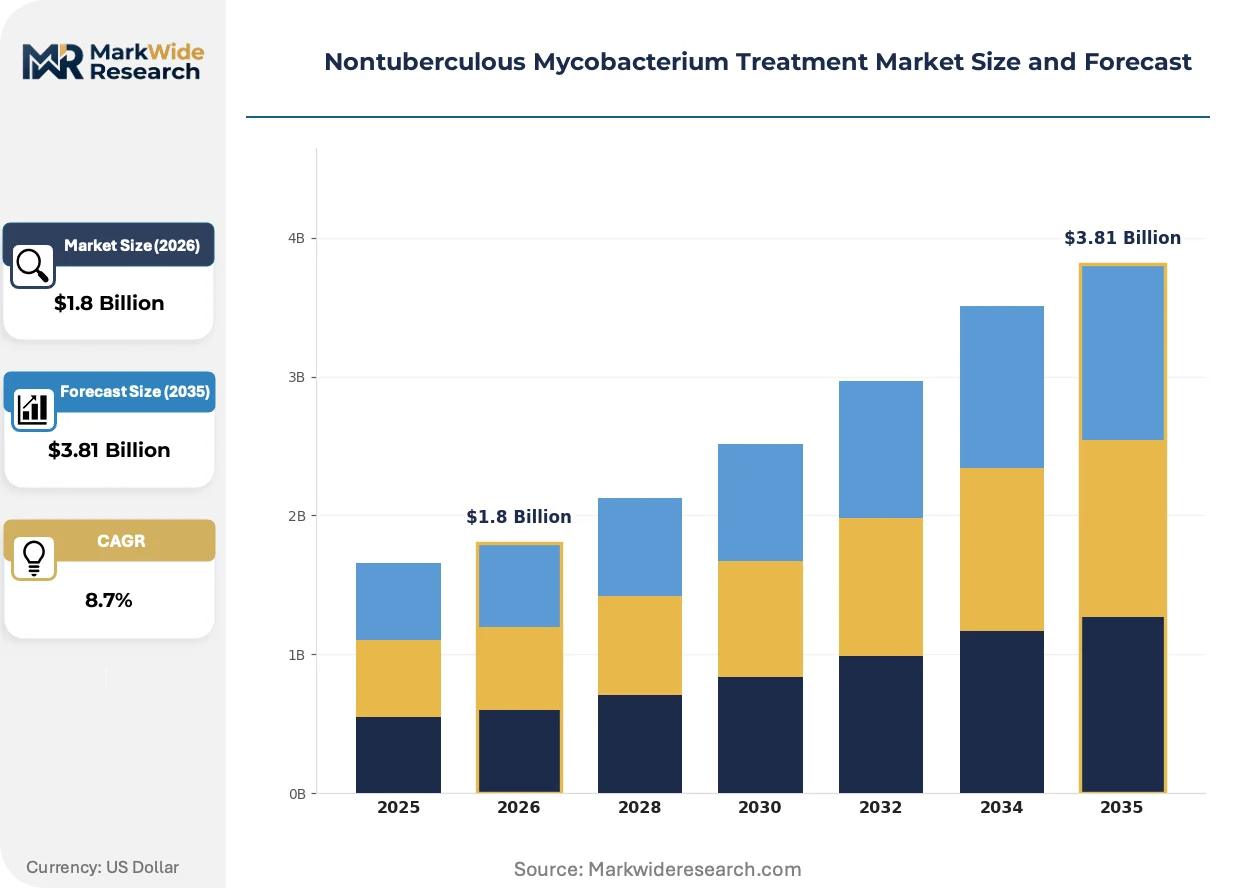
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Macrolides, Rifamycins, Aminoglycosides, Ethambutol Therapy Area: Chronic Lung Disease, Skin Infections, Bone Infections, Gastrointestinal Disorders End User: Hospitals, Home Care Settings, Specialty Clinics, Research Laboratories Delivery Mode: Oral, Intravenous, Inhalation, Topical |
| Companies Covered | Paratek Therapeutics, Teva Pharmaceuticals, Insmed, Cipla, MannKind, Pfizer, Novartis, Dr. Reddy's Laboratories, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nontuberculous Mycobacterium Treatment Market Evolving Landscape
Respiratory delivery modalities are displacing systemic administration as the dominant configuration for aminoglycoside therapy. Three convergent forces are restructuring how antimicrobial regimens reach bronchiectasis populations.
Liposomal encapsulation technology is consolidating nebulized amikacin as the preferred delivery mechanism for refractory NTM infections. Specialty pulmonary clinics are adopting these formulations to reduce nephrotoxicity monitoring requirements. The structural consequence is compressing hospital infusion center utilization while expanding home-based therapy eligibility.
EMA's Medical Device Regulation framework is imposing post-market surveillance obligations on European sponsors of novel mycobacterial therapies. Device-drug combination products now face extended clinical follow-up requirements that delay market access timelines. Inhaled antibiotic manufacturers are responding by front-loading pharmacovigilance infrastructure to preempt regulatory friction.
Site-of-care economics are driving hospital procurement officers to unbundle infusion services from drug acquisition costs. Pulmonary networks are negotiating direct-to-clinic distribution contracts that bypass wholesale intermediaries. This channel compression is most visible in United States Medicare Advantage populations where capitated payment models reward outpatient therapy completion.
Nontuberculous Mycobacterium Treatment Market Segmentation
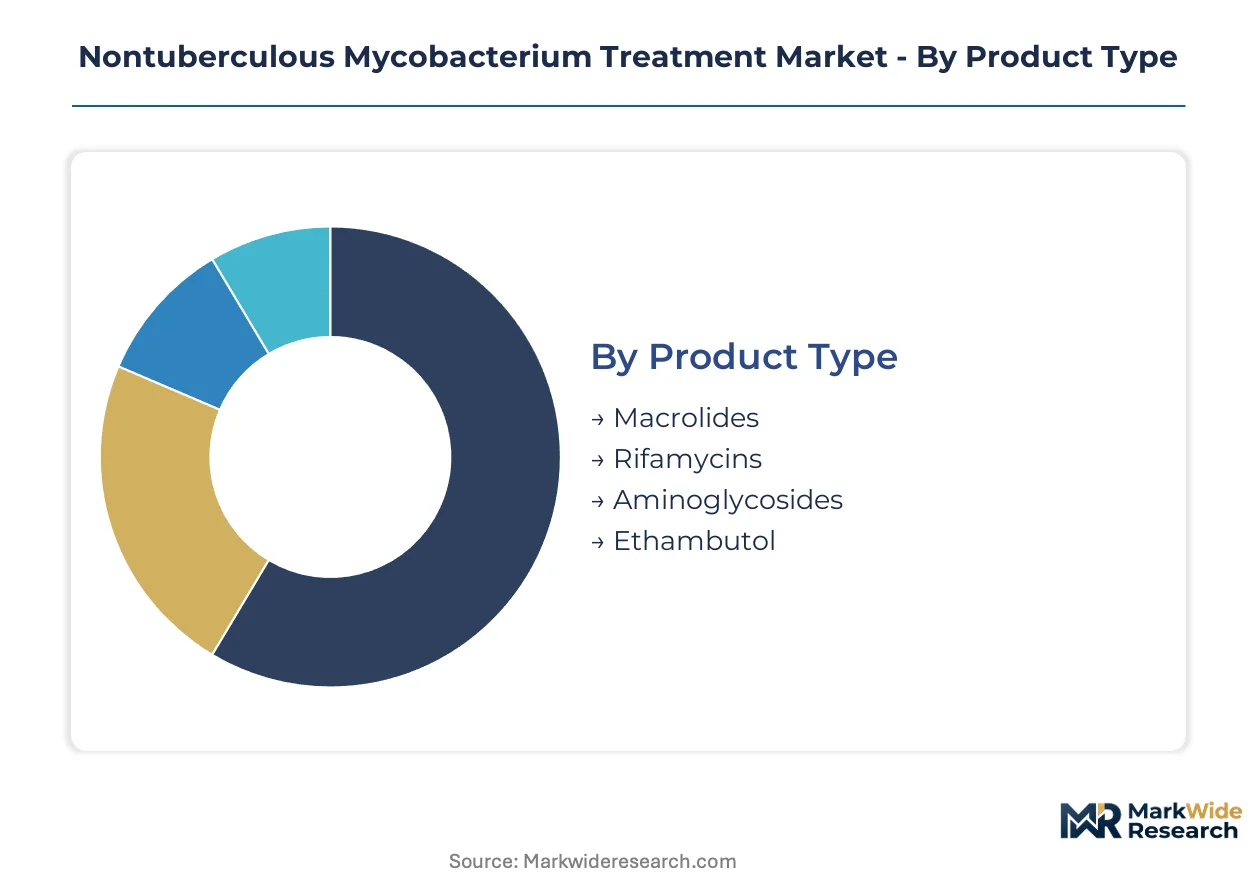
NTM treatment protocols fragment across antimicrobial classes, anatomical targets, and care delivery sites. Supply chain concentration varies dramatically by segment, with inhaled formulations consolidating around single-source liposomal technologies while oral generics disperse across multiple manufacturers.
Product Type:
Supply concentration tilts toward macrolide manufacturing hubs in India and China, where API production scales dominate global procurement.
- Macrolides:Clarithromycin and azithromycin formulations anchor first-line MAC therapy through bacteriostatic protein synthesis inhibition. Demand concentrates in United States Medicare Advantage networks where pulmonologists prioritize oral bioavailability for outpatient adherence. The 12–18 month treatment courses required for culture conversion sustain recurring prescription volumes.
- Rifamycins:Rifabutin and rifampin serve as companion agents in combination regimens, penetrating mycobacterial cell walls to amplify macrolide efficacy. Procurement clusters in European hospital systems where EMA orphan drug pathways accelerate refractory strain approvals. Cold-chain distribution requirements constrain emerging market access.
- Aminoglycosides:Intravenous amikacin retains niche positioning for Mycobacterium abscessus cases failing macrolide-based protocols.
- Ethambutol:This companion agent disrupts arabinogalactan synthesis in mycobacterial cell walls, typically deployed in triple-therapy combinations.
Today's leader: Macrolides. Tomorrow's challenger: Aminoglycosides.
Therapy Area:
Margin pools deepen proportionally with treatment duration, creating structural incentives for chronic disease management infrastructure.
- Chronic Lung Disease:Bronchiectasis and COPD-associated NTM infections generate the longest therapeutic arcs, with patients requiring 2–3 years of sustained antimicrobial exposure. Specialty pulmonary clinics in the United States capture the deepest reimbursement through CMS chronic care management codes.
- Skin Infections:Post-surgical and traumatic wound colonization by rapidly growing mycobacteria demands shorter but intensive multidrug courses. Dermatology networks in Germany and France drive European demand through structured wound care protocols.
- Bone Infections:Osteomyelitis from Mycobacterium marinum or M. fortuitum requires surgical debridement combined with prolonged antimicrobial suppression.
- Gastrointestinal Disorders:MAC enteritis in immunocompromised patients, particularly advanced HIV populations, responds to macrolide-based regimens.
Chronic Lung Disease commands current revenue concentration. Skin Infections are gaining share fastest through ambulatory surgery center expansion.
End User:
Site-of-care migration is redistributing procurement authority from hospital pharmacy directors to outpatient specialty networks.
- Hospitals:Inpatient infusion centers retain dominance for aminoglycoside initiation and toxicity monitoring, particularly in Japan where PMDA guidelines mandate supervised nephrotoxicity surveillance. Bundled payment models in United States Medicare are compressing length-of-stay economics.
- Home Care Settings:Nebulized liposomal amikacin and oral macrolide combinations enable residential therapy completion, with United States home health agencies capturing CMS reimbursement reclassification benefits.
- Specialty Clinics:Pulmonary and infectious disease networks concentrate culture conversion monitoring and regimen adjustment decisions.
- Research Laboratories:Reference microbiology facilities perform species identification and drug susceptibility testing for refractory cases.
Specialty Clinics anchor current volume. Home Care Settings represent the steepest expansion trajectory.
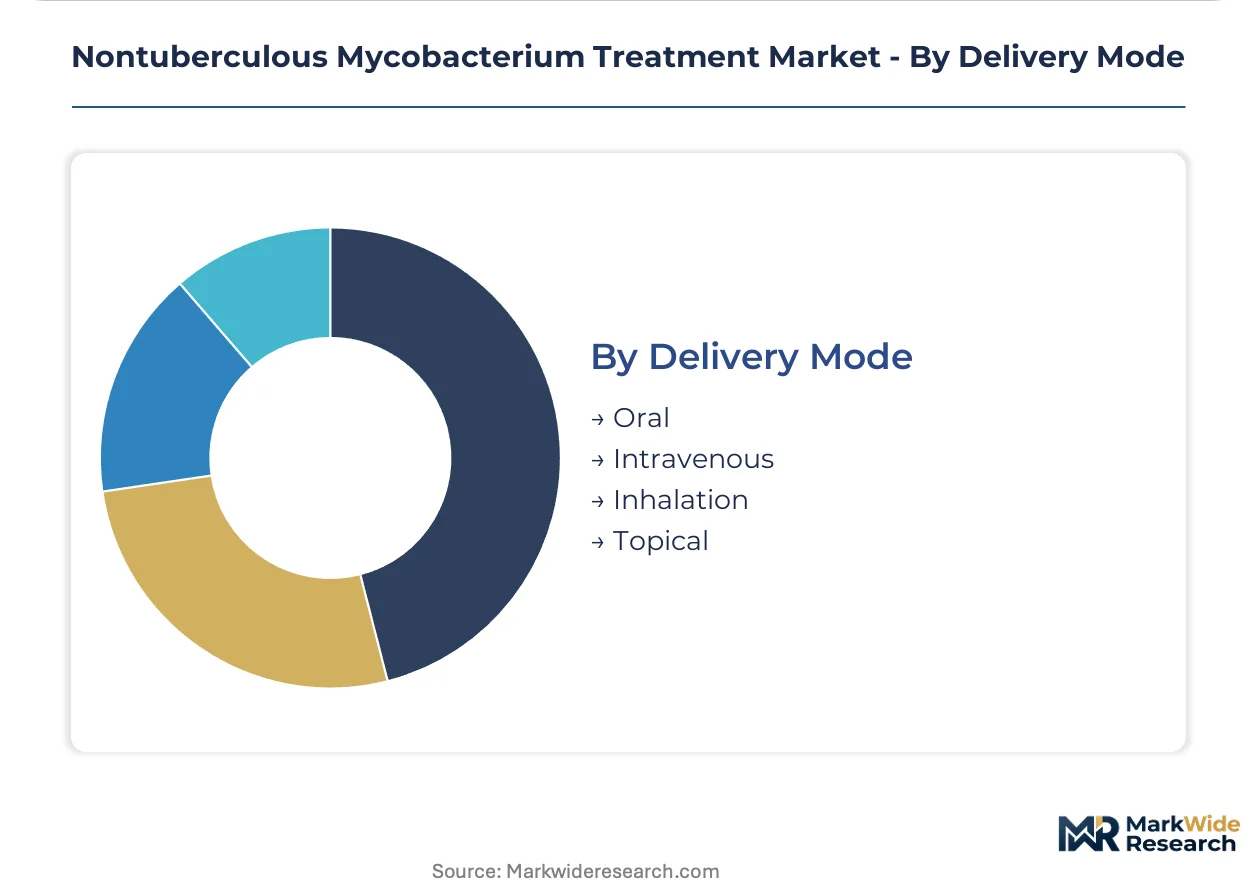
Delivery Mode:
Technology licensing agreements determine competitive access, with liposomal encapsulation patents creating manufacturing moats around inhaled configurations.
- Oral:Macrolide and rifamycin tablets dominate first-line prescribing through convenience and cost structures. Generic manufacturing scale in India sustains lowest-unit-cost supply for government procurement programs.
- Inhalation:Nebulized liposomal amikacin bypasses systemic toxicity thresholds that previously limited intravenous exposure duration. FDA device-drug combination approvals for bronchiectasis populations are reshaping manufacturer development priorities.
- Intravenous:Hospital infusion centers retain this mode for aminoglycoside loading doses and severe disseminated disease.
- Topical:Limited to localized skin and soft tissue infections from M. marinum or M. ulcerans exposure.
Oral formulations maintain volume leadership. Inhalation delivery is climbing the fastest through respiratory technology licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NTM treatment protocols first achieved clinical standardization in United States academic medical centers during the 1990s, establishing the multi-drug regimen frameworks now adopted worldwide. Medicare reimbursement maturation and pulmonary specialty network expansion have since concentrated commercial activity in North American and Western European markets.
United States
Specialty pulmonary clinics in metropolitan centers drive demand for nebulized liposomal formulations and oral macrolide combinations. FDA device-drug combination approvals for inhaled antibiotics have accelerated site-of-care migration from hospital infusion centers to home administration models. Boston and New York harbor dense concentrations of bronchiectasis referral networks that anchor culture conversion monitoring infrastructure.
Germany
Structured wound care protocols in dermatology networks generate demand for topical and oral rifamycin regimens targeting post-surgical mycobacterial colonization. EMA orphan drug designations under the MDR framework protect innovators pursuing refractory strain therapies through accelerated regulatory channels. The Rhine-Ruhr industrial corridor hosts reference microbiology laboratories specializing in Mycobacterium abscessus drug susceptibility testing.
Japan
PMDA guidelines mandate supervised nephrotoxicity surveillance for aminoglycoside initiation, preserving hospital infusion center dominance for severe disseminated disease cases. Aging-related bronchiectasis prevalence expands the addressable patient pool for prolonged antimicrobial therapy. Tokyo and Osaka academic medical centers coordinate species identification networks for rapidly growing mycobacteria.
India
Generic macrolide manufacturing scale in Gujarat and Maharashtra sustains lowest-unit-cost supply for government procurement programs targeting immunocompromised populations. CDSCO regulatory pathways for fixed-dose combination therapies streamline formulary access in public hospital systems. Hyderabad and Bangalore harbor API production clusters that feed global rifamycin supply chains.
United Kingdom
NHS England specialized commissioning frameworks concentrate refractory NTM case management in designated supra-regional centers. MHRA post-market surveillance requirements align with EMA MDR obligations for device-drug combination products. London and Manchester pulmonary networks coordinate multicenter trials for novel inhaled antimicrobial formulations.
Nontuberculous Mycobacterium Treatment Market Competitive Landscape
The competitive structure tilts toward technology-differentiated specialists rather than broad-spectrum pharmaceutical conglomerates. Inhaled delivery platform ownership and liposomal encapsulation patents create manufacturing moats that resist generic substitution. Three archetypes dominate: respiratory-focused biotechs with device-drug integration capabilities, scaled generic manufacturers capturing oral macrolide and rifamycin volume, and specialty pharmaceutical firms leveraging orphan drug exclusivities. Competitive dynamics center on technology licensing negotiations and CMS reimbursement reclassification strategies that enable home administration model expansion.
Within the respiratory delivery specialist tier, Insmed anchors inhaled liposomal amikacin positioning through nebulized platform development. Teva Pharmaceuticals exemplifies generic manufacturing scale advantages across oral macrolide supply. Cipla occupies a position bridging emerging market access expansion with API production integration.
| Leading Market Players |
|---|
| Paratek Therapeutics |
| Teva Pharmaceuticals |
| Insmed |
| Cipla |
| MannKind |
| Pfizer |
| Novartis |
| Dr. Reddy's Laboratories |
| AbbVie |
| Others |
Value Network & Pricing Analysis
API commodity indices for macrolide and rifamycin active pharmaceutical ingredients cascade through multi-tier pricing structures, with Gujarat and Maharashtra manufacturing clusters feeding cost advantages into government procurement programs while liposomal encapsulation patents sustain premium tiers for respiratory delivery platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates liposomal inhalation therapies from oral generic macrolides and institutional tender supplies. Price differentiation hinges on FDA device-drug combination certification and cold-chain distribution capability. Cost compression in oral generic tiers is intensifying because Indian API manufacturers are scaling clarithromycin production for government tenders. Hospital pharmacy directors exhibit highest price sensitivity, while specialty pulmonary clinics prioritize nephrotoxicity reduction over unit cost.
Supply Chain Analysis
Amikacin API supply rests on fermentation capacity concentrated in China, India, and South Korea, with liposomal encapsulation technology drawing from Italian and Swiss specialty chemical producers. Raw material dependencies include fermentation-grade dextrose, specialized phospholipids, and nebulizer device components. Single-source vulnerability around liposomal formulation patents creates procurement bottlenecks for European hospital systems. Distribution runs through direct-to-clinic contracts that bypass wholesale intermediaries in United States Medicare Advantage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nontuberculous Mycobacterium Treatment Market represents a late-cycle quality story where demand is migrating toward nebulized liposomal formulations that command sustained margin premiums through toxicity reduction profiles.
For Market Incumbents: Acquire home infusion service networks to anchor patient retention against site-of-care migration. Secure liposomal encapsulation technology licenses before EMA MDR surveillance obligations tighten manufacturing qualifications. Threat of generic macrolide commoditization demands backward integration into API production to defend cost position in oral therapy tiers. For New Entrants and Emerging Players: Underserved home health agencies in United States rural markets present white-space entry points where CMS reimbursement reclassification has enabled residential therapy completion. Target Japanese hospital infusion centers where PMDA nephrotoxicity surveillance mandates preserve supervised administration dominance. Go-to-market leverage centers on nebulizer device compatibility bundling with existing pulmonary clinic workflows. For Investors and Strategic Acquirers: Asymmetric upside sits with respiratory delivery platform specialists possessing FDA device-drug combination approvals. Long-term viability across the next decade depends on culture conversion monitoring infrastructure integration. Watch FDA guidance evolution on inhaled antimicrobial endpoints as the signal for portfolio rebalancing toward nebulized formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA device-drug combination submissions for bronchiectasis populations reshape development priorities. |
| Manufacturing Scale-Up | Liposomal encapsulation capacity expansion in European contract manufacturing organizations addresses EMA MDR compliance. |
| Hospital System Partnership | Direct-to-clinic distribution contracts with United States specialty pulmonary networks compress channel costs. |
| Reimbursement Strategy | CMS chronic care management code optimization captures deepest margin pools in Medicare Advantage populations. |
| Pipeline Diversification | Fixed-dose macrolide-rifamycin combinations streamline hospital formulary evaluation protocols. |
Research Methodology
Direct dialogue with pulmonologists, hospital pharmacy directors, formulary committee chairs, and home health agency administrators grounded qualitative insights, validated against FDA filings, EMA MDR submission databases, ClinicalTrials.gov entries, and CMS Medicare reimbursement data. Bottom-up prescription volume modeling triangulated with top-down manufacturer revenue estimates across antimicrobial classes and delivery modes.
Segment-level value outputs across the projection horizon reflect treatment duration assumptions, culture conversion rates by species, and site-of-care migration velocity. Segmentation dimensions modeled include antimicrobial class, therapy area, end-user setting, and delivery mode. CAGRs were derived from patient prevalence projections, regimen completion rates, and reimbursement pathway maturation trajectories.
Underlying measurement precision varies by segment; oral macrolide volumes carry tighter precision than emerging liposomal inhalation therapies. Forecasts reflect assumptions around FDA guidance stability and EMA MDR implementation timelines. Regulatory reclassification of inhaled antibiotics and PMDA surveillance guideline revisions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Tennis Elbow Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Motion Sickness Treatment Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market