
 Uterine Fibroid Treatment Drugs Market | 2026-2036
Uterine Fibroid Treatment Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Uterine Fibroid Treatment Drugs Market Intelligence
The FDA's breakthrough therapy designation is expanding the cost-of-entry calculus for developers of non-surgical uterine fibroid therapies. AbbVie Inc. leverages its endocrinology infrastructure to sustain commercial reach across gynecology networks. Pfizer Inc. anchors its position through manufacturing scale in hormonal therapy production. Bayer AG differentiates via its heritage in women's health pharmaceuticals and established channel relationships with hospital systems.
Uterine fibroid treatment drugs comprise pharmacological agents designed to modulate hormonal pathways, reduce bleeding, or shrink fibroid tissue through mechanisms such as GnRH receptor suppression or progesterone modulation. These therapeutics serve as alternatives or adjuncts to hysterectomy and myomectomy, targeting symptom relief and fertility preservation in premenopausal women. GnRH Agonists occupy the largest revenue pool due to established clinical efficacy in volume reduction, while Hormonal Intrauterine Devices represent the fastest-growing delivery innovation as outpatient placement expands. The Oral delivery mode dominates prescription volumes for maintenance therapy, though Injectable formulations command premium positioning in acute intervention settings.
The FDA's Risk Evaluation and Mitigation Strategy requirements shape bone-density monitoring protocols for prolonged GnRH agonist use, directly influencing prescribing patterns and patient eligibility criteria. EMA's pharmacovigilance frameworks for hormonal therapies enforce post-market surveillance obligations that elevate compliance investments for European market access. Stakeholders must monitor evolving reimbursement criteria for fertility-preserving pharmacological options as healthcare systems recalibrate surgical versus medical management incentives.
Market Dynamics
FDA's Risk Evaluation and Mitigation Strategy for GnRH agonists is compressing prescribing windows and forcing developers toward bone-sparing formulations as a prerequisite for chronic use authorization.
Growth Catalysts
- EMA Pharmacovigilance Frameworks:Post-market surveillance obligations for hormonal therapies in Europe are elevating compliance investments that filter out marginal competitors, concentrating revenue among established pharmaceutical manufacturers with dedicated safety infrastructure.
- Gynecology Clinic Expansion:Outpatient pharmacological protocols are displacing surgical referrals in premenopausal patient populations across the United States, creating dedicated channel capacity for non-invasive fibroid management.
- Selective Progesterone Receptor Modulators:Oral SPRM mechanisms are capturing maintenance therapy prescriptions previously reserved for surgical consultation, enabling fertility-preserving treatment continuity.
Market Restraints
- Input Cost Volatility in Peptide Synthesis:GnRH agonist manufacturing depends on specialized amino acid precursors with concentrated supply from Chinese fine-chemical producers, exposing margin stability to tariff and logistics disruptions.
- FDA REMS Bone Density Monitoring:Mandatory dual-energy x-ray absorptiometry protocols for prolonged GnRH agonist use create patient eligibility friction and prescribing hesitation in primary care settings.
- Hysterectomy Substitution Threat:Minimally invasive surgical techniques with reduced recovery windows retain preference among patients with completed fertility, limiting addressable market expansion for pharmaceutical alternatives.
Strategic Opportunities
- Underpenetrated Rural United States:Specialist access gaps in non-metropolitan counties create whitespace for telemedicine-enabled hormonal therapy initiation and remote monitoring protocols.
- Convergence of Oral SPRMs with Digital Adherence Tracking:Integration of pharmacological treatment with smartphone-based symptom logging and refill prompting is unifying therapeutic efficacy with real-world evidence generation for payor negotiations.
- IRA Drug Pricing Provisions:Medicare negotiation timelines for established hormonal therapies are accelerating developer interest in novel mechanisms with extended exclusivity windows.
Industry Challenges
- Reproductive Endocrinology Talent Scarcity:Fellowship pipeline constraints limit the specialist prescriber base capable of managing complex hormonal regimens and fertility counseling simultaneously.
- Legacy Electronic Health Record Integration:Fibroid-specific outcome tracking modules remain absent from dominant ambulatory EHR platforms, fragmenting longitudinal data capture across gynecology networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uterine Fibroid Treatment Drugs Market |
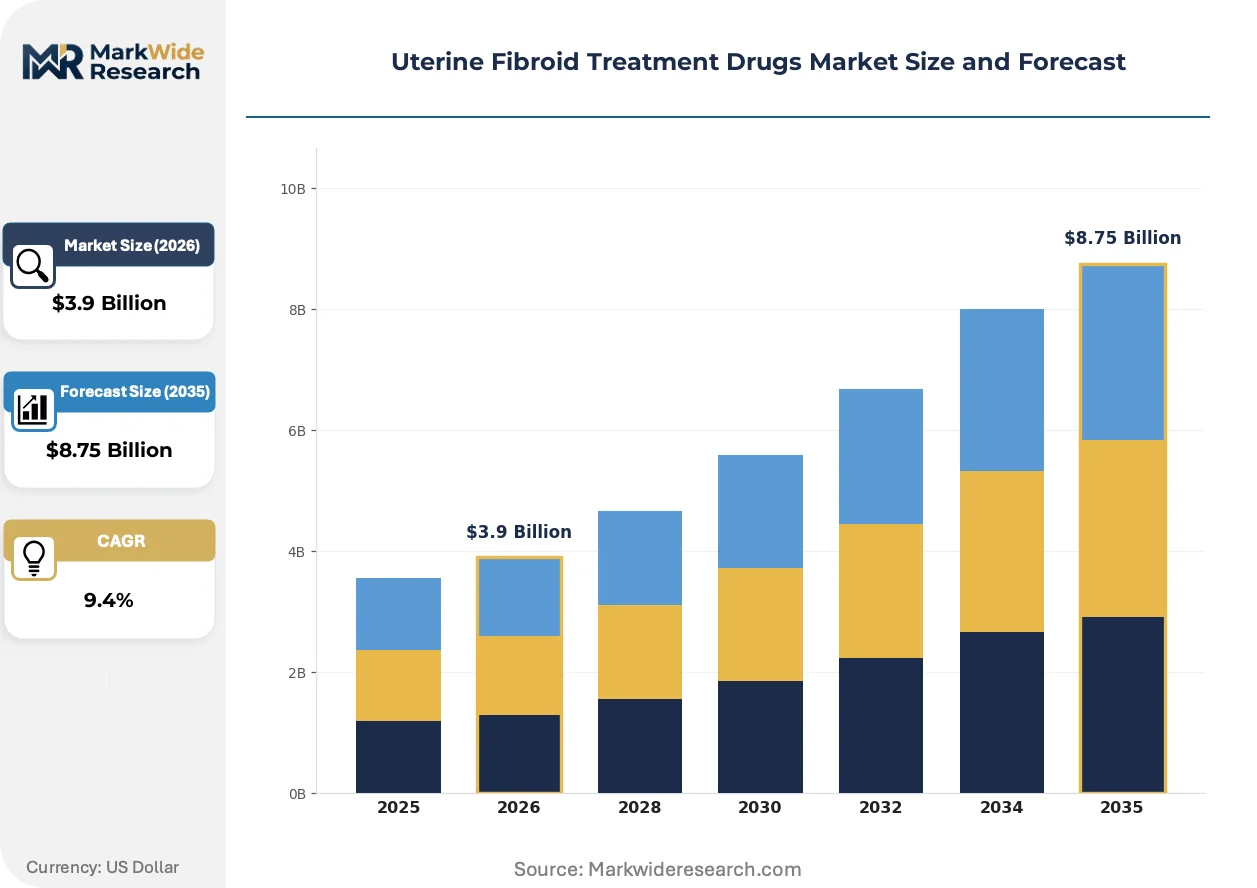
| Market Size in 2026 | $3.9 Billion |
| Market Size in 2035 | $8.75 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GnRH Agonists, Progestins, Antifibrinolytics, Hormonal Intrauterine Devices Therapy Area: Menorrhagia, Pain Management, Surgical Intervention, Fertility Preservation Delivery Mode: Oral, Injectable, Intrauterine, Transdermal End User: Hospitals, Gynecology Clinics, Ambulatory Surgery Centers, Home Care |
| Companies Covered | AstraZeneca Plc, Ferring B.V., Pfizer Inc., Takeda Pharmaceutical Company Ltd, Kissei Pharmaceutical Co Ltd, AbbVie Inc., Myovant Sciences GmbH, Neurocrine Biosciences Inc., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uterine Fibroid Treatment Drugs Market Strategic Shifts & Innovations
Pharmaceutical delivery mechanisms and regulatory data requirements are converging to reshape how uterine fibroid therapies reach patients and demonstrate value to payors.
Oral selective progesterone receptor modulators are unifying acute symptom relief with chronic maintenance in single-agent protocols, compressing the traditional GnRH agonist-to-surgery treatment cascade. Community gynecology practices are adopting these agents at accelerated pace where hysterectomy referral capacity is constrained. The technology is unifying previously segmented acute and chronic prescription pools into continuous therapy relationships.
REACH authorization requirements for endocrine-disrupting chemical classification are compelling European manufacturers to reformulate excipient compositions and resubmit stability data. Industrial consequence includes extended regulatory timelines for generic hormonal entrants. Hospital system procurement in Germany and France is responding by consolidating supplier relationships with entities possessing established ECHA compliance documentation.
Patient-directed pharmacy selection through fertility-preservation counseling is fragmenting traditional physician-controlled dispensing channels. Gynecology clinics are disintermediating hospital outpatient pharmacies through direct partnership with specialty mail-order distributors. This pattern concentrates in the United States where high-deductible health plans amplify out-of-pocket cost sensitivity for chronic hormonal therapy.
Uterine Fibroid Treatment Drugs Market Segmentation
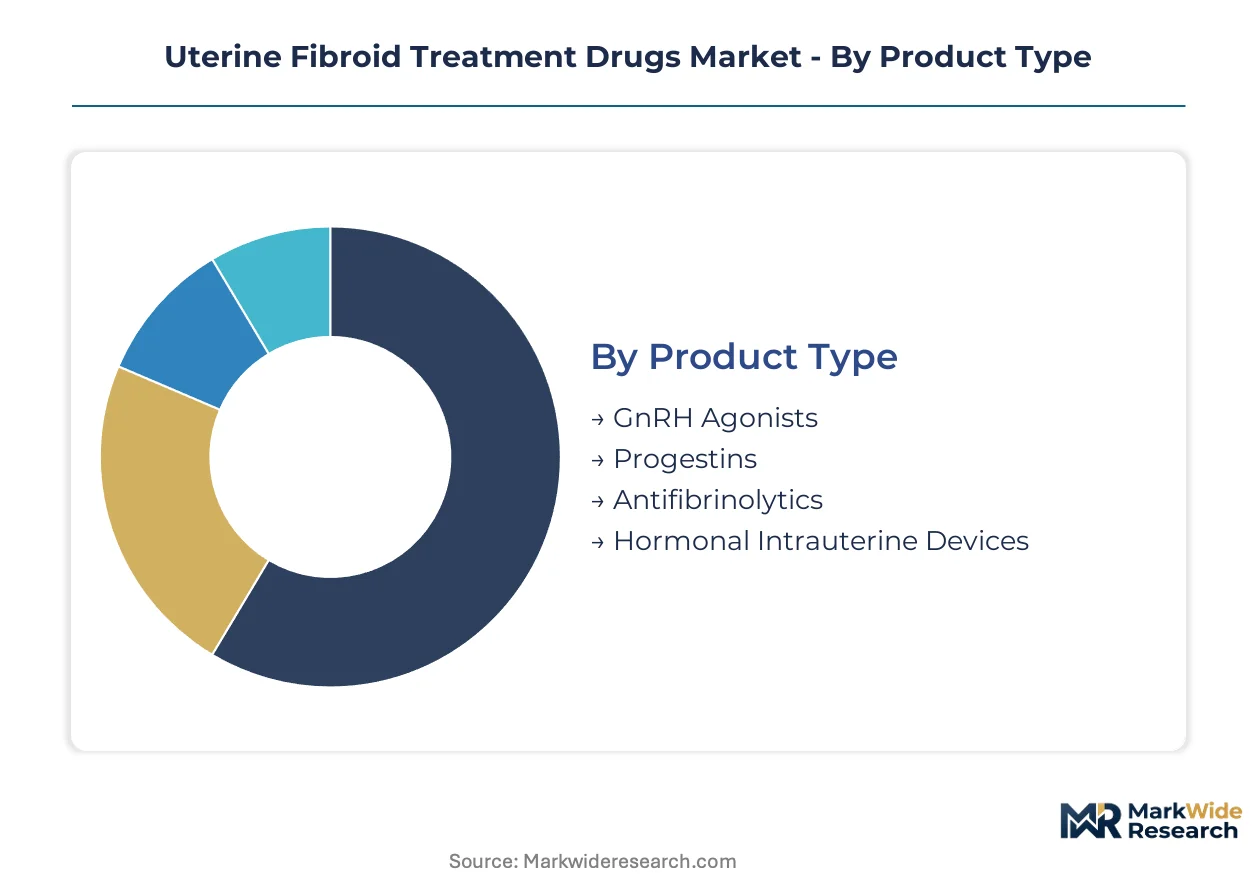
Pharmacological segmentation in uterine fibroid treatment reflects divergent clinical objectives: acute symptom suppression versus fertility preservation, inpatient intervention versus outpatient maintenance. Each product and delivery category carries distinct reimbursement profiles, prescriber specialization requirements, and patient adherence dynamics that shape commercial strategy.
Product Type:
Mechanism of action determines prescriber confidence, treatment duration limits, and bone safety monitoring obligations.
- GnRH Agonists:Synthetic decapeptide analogs suppress pituitary gonadotropin secretion, inducing reversible medical menopause and fibroid volume reduction. Demand concentrates in United States academic medical centers where REproductive Endocrinology specialists manage bone-density surveillance protocols under FDA REMS requirements.
- Hormonal Intrauterine Devices:Levonorgestrel-releasing systems deliver localized progestin to the endometrium, reducing menstrual bleeding without systemic hormonal suppression. Outpatient placement is expanding fastest in United States community gynecology practices seeking alternatives to hysterectomy referral.
- Progestins:Oral or injectable synthetic progesterone derivatives modulate endometrial proliferation and bleeding patterns.
- Antifibrinolytics:Tranexamic acid formulations inhibit plasminogen activation, reducing menstrual blood loss through hemostatic mechanisms.
Mature deployment sits with GnRH Agonists. Newer deployment is concentrated in Hormonal Intrauterine Devices.
Therapy Area:
Clinical indication segmentation separates acute intervention markets from chronic maintenance prescriptions with divergent pricing power.
- Menorrhagia:Heavy menstrual bleeding represents the dominant symptomatic complaint driving pharmacological first-line therapy, with antifibrinolytics and hormonal IUDs capturing initial prescriptions before surgical escalation.
- Fertility Preservation:Treatment protocols in premenopausal women seeking future conception favor SPRMs and short-course GnRH agonists over permanent surgical options, creating recurring revenue pools in reproductive endocrinology practices.
- Pain Management:NSAID-refractory dysmenorrhea and pelvic pressure symptoms drive demand for hormonal suppression therapies.
- Surgical Intervention:Preoperative GnRH agonist use reduces fibroid volume and intraoperative bleeding, serving as adjunct rather than alternative to myomectomy.
Volume concentration rests with Menorrhagia. Margin expansion is concentrated in Fertility Preservation.
Delivery Mode:
Route of administration shapes patient autonomy, adherence surveillance requirements, and pharmacy dispensing channel economics.
- Oral:Tablet and capsule formulations dominate maintenance therapy volumes due to patient self-administration and broad primary care prescriber comfort, though gastrointestinal absorption variability affects efficacy consistency.
- Injectable:Depot formulations command premium positioning in acute intervention settings where guaranteed compliance and sustained plasma levels override cost considerations, particularly in Medicaid populations with adherence challenges.
- Intrauterine:Device placement requires procedural infrastructure but eliminates daily adherence requirements.
- Transdermal:Patch and gel delivery systems remain limited in fibroid-specific applications due to variable skin permeability and higher manufacturing costs.
Prescription volume leadership sits with Oral. Steepest expansion trajectory is concentrated in Intrauterine.
End User:
Care setting segmentation determines reimbursement rates, formulary access, and prescriber specialization requirements.
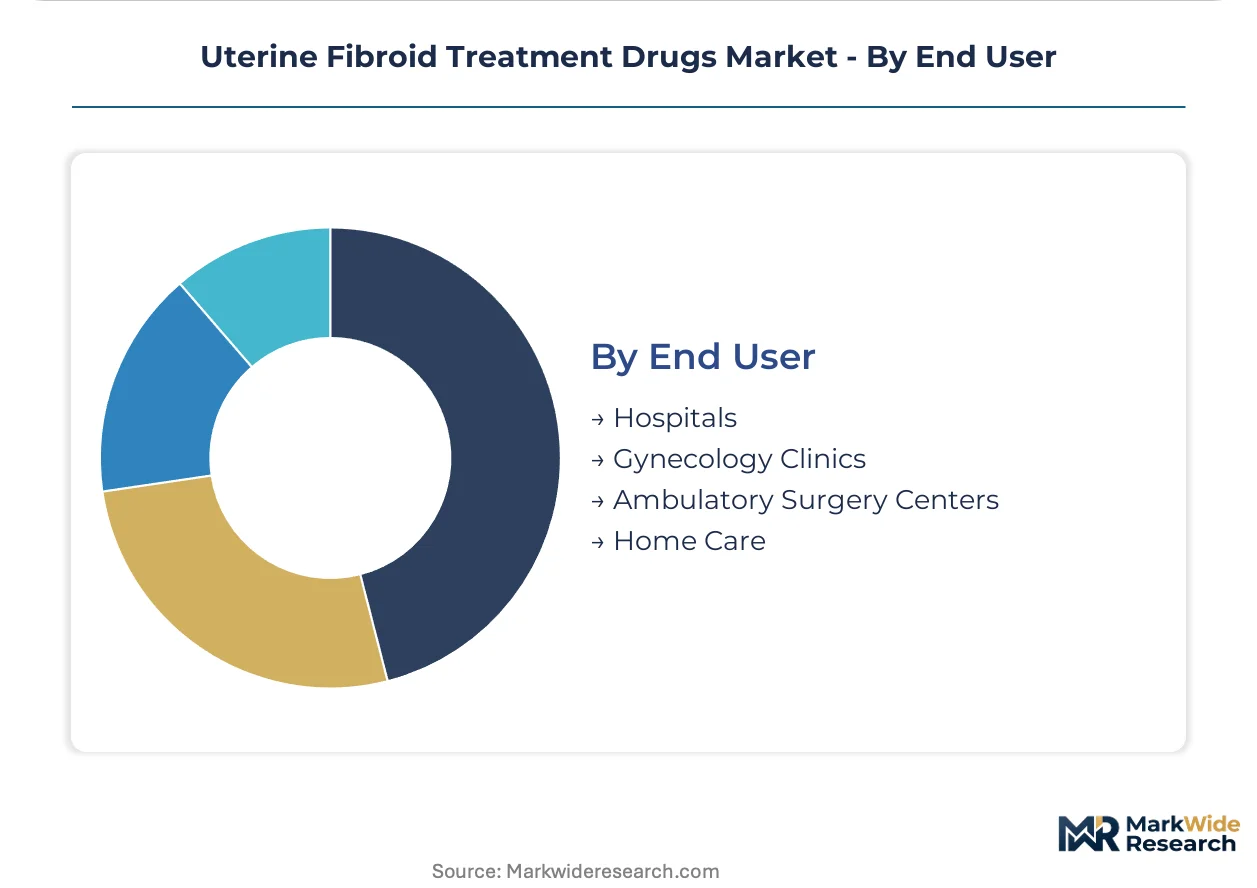
- Gynecology Clinics:Outpatient women's health practices are displacing hospital-based consultation for initial pharmacological management, capturing revenue from extended therapy relationships and fertility counseling services.
- Hospitals:Inpatient and emergency departments manage acute hemorrhage episodes requiring intravenous antifibrinolytics or urgent GnRH agonist initiation, with 340B pricing programs affecting net revenue realization.
- Ambulatory Surgery Centers:Preoperative GnRH agonist protocols and same-day IUD placement procedures concentrate in United States freestanding surgical facilities with gynecology service lines.
- Home Care:Self-administered oral and transdermal therapies with remote monitoring support are emerging in value-based care contracts seeking to reduce specialist visit burden.
Revenue concentration sits with Hospitals. Channel growth is concentrated in Gynecology Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient awareness campaigns and specialist access patterns concentrate demand in the United States, while reimbursement frameworks in Germany and Japan shape pharmaceutical access differently. Regulatory divergence between FDA REMS protocols and EMA pharmacovigilance requirements creates distinct commercialization pathways across major markets.
United States
Fertility-preservation counseling drives prescription volumes for oral SPRMs in premenopausal populations across metropolitan gynecology networks. FDA Risk Evaluation and Mitigation Strategy mandates for GnRH agonists enforce bone-density monitoring that shapes prescribing patterns in community practices. The Boston-Cambridge corridor anchors reproductive endocrinology research clusters where academic medical centers pilot digital adherence tracking integration.
Germany
Hospital system procurement consolidation favors established manufacturers with REACH-compliant documentation for hormonal excipients. ECHA endocrine-disruptor classification requirements extend regulatory timelines for generic entrants, concentrating market access among incumbents. The Rhine-Ruhr industrial basin hosts pharmaceutical manufacturing infrastructure serving Central European distribution networks.
Japan
Aging demographics and delayed childbearing expand the addressable population for fertility-preserving pharmacological options in urban prefectures. PMDA post-market surveillance obligations for hormonal therapies elevate compliance investments required for sustained market presence. The Kanto region surrounding Tokyo concentrates gynecology specialist practices and hospital pharmacy procurement decision-making.
United Kingdom
NICE technology appraisal processes for uterine fibroid therapies create evidence-generation requirements that filter market access for novel mechanisms. NHS England's specialized commissioning frameworks concentrate high-cost hormonal therapy prescriptions in designated tertiary centers. The Greater Manchester health innovation cluster pilots value-based contracting models for chronic gynecological conditions.
India
Expanding private hospital networks in metropolitan areas create channel capacity for branded hormonal therapies beyond public sector formularies. CDSCO accelerated approval pathways for gynecological indications are shortening development-to-commercialization timelines for domestic manufacturers. The Mumbai-Pune pharmaceutical corridor anchors active pharmaceutical ingredient synthesis and formulation capabilities serving domestic and export markets.
Uterine Fibroid Treatment Drugs Market Key Industry Players
United States-based pharmaceutical conglomerates anchor the premium-tier revenue pool; European specialists hold compliance-intensive positions in regulated markets. The vendor base stratifies across three archetypes: diversified endocrinology platforms with gynecology cross-selling infrastructure, women's health pure-plays with heritage channel relationships, and emerging biotechs with novel mechanism assets. Consolidation momentum concentrates around bone-sparing formulation technologies and digital therapeutic adjacencies.
Among diversified pharmaceutical manufacturers, Pfizer Inc. and AbbVie Inc. occupy positions leveraging manufacturing scale and endocrinology infrastructure respectively. Bayer AG exemplifies the women's health heritage archetype through established hospital system relationships. These three entities represent distinct competitive vectors: scale-driven supply security, therapeutic category cross-leverage, and channel-specific commercial depth.
| Leading Market Players |
|---|
| AstraZeneca Plc |
| Ferring B.V. |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Ltd |
| Kissei Pharmaceutical Co Ltd |
| AbbVie Inc. |
| Myovant Sciences GmbH |
| Neurocrine Biosciences Inc. |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap pharmaceutical manufacturers in India and China anchor the active pharmaceutical ingredient supply base, translating concentrated upstream ownership into asymmetric pricing power for GnRH agonist peptide precursors. This ownership pattern feeds directly into cost-plus contracting structures that pharmaceutical developers face when securing long-term supply commitments for hormonal therapy manufacturing.
Pricing Analysis
Short lead-time premiums of twenty to thirty percent above contract baselines apply to spot purchases of specialized amino acid precursors for peptide synthesis. Pricing stratifies across premium, standard, and economy tiers based on purity certification from FDA-inspected facilities versus regional GMP equivalents. Cost compression in standard-grade hormonal APIs is intensifying because Chinese fine-chemical producers are expanding fermentation capacity. Medicaid-enrolled patient populations exhibit the highest price sensitivity due to out-of-pocket exposure under high-deductible plan structures, while academic medical centers with 340B pricing programs demonstrate the least.
Supply Chain Analysis
Domestic-content mandates in India's Production Linked Incentive scheme for pharmaceuticals are reshaping sourcing patterns for formulation-stage manufacturing, pushing multinational developers toward joint-venture structures with local partners. Peptide precursor supply concentrates in China, India, and Switzerland, with the latter hosting specialized GMP finishing capabilities for European market access. Manufacturing draws from L-histidine, L-tryptophan, and protected amino acid derivatives as critical inputs. Single-source vulnerability in Chinese fine-chemical hubs poses structural risk given tariff exposure and logistics chokepoints through Shanghai port infrastructure. Distribution runs through specialty pharmaceutical wholesalers with cold-chain capabilities, consolidating toward three national distributors in the United States market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist prescriber scarcity in reproductive endocrinology functions as the binding capacity constraint, propping pricing power for manufacturers with established gynecology clinic relationships and bone-sparing formulation portfolios.
For Market Incumbents: To counter the erosion of GnRH agonist prescribing windows under FDA REMS protocols, AbbVie Inc. and Pfizer Inc. should deepen backward integration into peptide precursor synthesis to secure margin stability against Chinese supply volatility. Parallel investment in oral SPRM delivery technologies captures maintenance therapy prescriptions displacing surgical referrals in community gynecology practices. For New Entrants and Emerging Players: Telemedicine-enabled hormonal therapy initiation represents the most penetrable route for bypassing specialist access gaps in rural United States counties. Targeting non-metropolitan markets with remote monitoring protocols and direct-to-patient pharmacy partnerships unlocks whitespace where hysterectomy referral capacity is constrained. A fertility-preservation counseling positioning differentiates against incumbent surgical-alternative messaging. For Investors and Strategic Acquirers: Distressed-cycle entries favor bone-sparing formulation specialists with Phase III-ready assets in the United States regulatory pathway. Long-term viability across a five-to-ten year window hinges on Medicare negotiation resilience through novel mechanism exclusivity. The signal to watch is FDA breakthrough therapy designation velocity for non-hormonal fibroid volume reduction candidates.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III readouts for oral SPRMs in fertility preservation indications reshape prescriber confidence in non-surgical alternatives. |
| Regulatory Approval Pathway | FDA breakthrough therapy designations compress development timelines and accelerate formulary access negotiations with national payors. |
| Backward Integration | In-house production of peptide precursors insulates margin stability from Chinese fine-chemical tariff and logistics disruptions. |
| Licensing Agreement | Digital adherence platform partnerships unify pharmacological efficacy with real-world evidence generation for payor negotiations. |
| Reimbursement Strategy | Value-based contracts with CMS innovation center pilots align chronic hormonal therapy outcomes with total cost-of-care reductions. |
Research Approach
Independent corroboration across reproductive endocrinology specialists, formulary directors at national payors, and gynecology clinic administrators underwrites the qualitative findings on prescribing pattern shifts. Primary interviews with drug development executives at hormonal therapy manufacturers, regulatory affairs leads navigating FDA REMS protocols, and hospital procurement managers managing 340B program participation were cross-referenced against secondary validation from FDA filings, ClinicalTrials.gov, EMA pharmacovigilance databases, and CMS Medicare Part D utilization data. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation were reconciled across the analysis window.
Rate-of-change decomposition across mechanism of action, delivery mode, therapy area, and regional regulatory cluster dimensions structures the quantitative framework. CAGRs were derived from segmented volume projections calibrated to historical prescription audit data and forward-looking specialist capacity expansion assumptions. Patient population aging dynamics and fertility-preservation counseling penetration rates serve as industry-specific forecast inputs alongside generic substitution timelines for hormonal therapies.
Inputs from FDA advisory committee transcripts and EMA public assessment reports were available through the study window; gaps in real-world adherence data for oral SPRM therapies introduce uncertainty bands around maintenance therapy persistence assumptions. Forecasts reflect documented assumptions regarding specialist workforce growth and reimbursement policy stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Ascites Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Scoliosis Management Market