
 Global Visceral Pain Treatment Market | 2026-2036
Global Visceral Pain Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Visceral Pain Treatment Market Intelligence
Purchasing power for visceral pain treatments is consolidating within large hospital networks and integrated delivery systems. These large buyers prioritize efficacy data and supply chain reliability when selecting vendors. Pfizer leverages its extensive clinical trial portfolio to secure formulary placements, while AbbVie Inc. differentiates its offerings for complex gastrointestinal disorder therapies.
Visceral pain treatment encompasses pharmacological interventions designed to mitigate pain signals originating from internal organs like the gut, bladder, or uterus. These therapies function by modulating specific neurotransmitter pathways or blocking nociceptive inputs to the central nervous system. Within therapy areas, gastrointestinal disorders constitute the largest application segment due to the high prevalence rates of conditions like IBS. The product landscape shows analgesics as a mature category, while neuromodulators represent a high-growth frontier due to their targeted mechanisms of action.
Regulatory oversight from bodies like the US FDA and the European Medicines Agency (EMA) dictates market access through stringent clinical trial requirements for new drug approvals. These agencies' standards for efficacy and safety data directly influence pharmaceutical development timelines and investment costs. Consequently, navigating the complex reimbursement landscapes and patient access programs in key markets like the United States and Germany becomes a critical determinant of commercial success.
Market Dynamics
The market's central dynamic is the clinical and commercial pressure to develop non-opioid analgesics. This stems from the public health crisis surrounding opioid addiction, forcing a pivot toward therapies with novel mechanisms and improved safety profiles.
Growth Catalysts
- Aging Demographics:Growing elderly populations in countries like Japan and Germany, which have a higher incidence of chronic visceral pain conditions, create sustained demand for effective and safe long-term treatment options.
- Novel Neuromodulators:The development of targeted neuromodulators that offer higher specificity and fewer systemic side effects compared to traditional analgesics provides a significant therapeutic advance for complex, chronic visceral pain syndromes.
- Expedited Regulatory Pathways:The US FDA's provision of fast-track and breakthrough therapy designations for non-addictive pain medications encourages investment and accelerates the development pipeline for innovative visceral pain treatments.
Market Restraints
- Restrictive Reimbursement Policies:Payers in markets like the United States often require step-therapy protocols, mandating the failure of cheaper generics before approving novel, higher-cost treatments, which delays patient access to innovation.
- Stringent Efficacy Hurdles:Regulatory bodies like the EMA demand robust, long-term data to prove superiority over existing treatments, a high bar given the significant placebo effect observed in visceral pain clinical trials.
- Generic Drug Competition:The widespread availability and low cost of generic drugs, such as NSAIDs and antispasmodics, present a persistent substitution threat for branded therapies, particularly for mild-to-moderate symptoms.
Strategic Opportunities
- Underserved Pain Conditions:A significant opportunity exists in developing therapies specifically for non-gastrointestinal visceral pain, such as endometriosis and interstitial cystitis, which have historically lacked dedicated and effective pharmacological options.
- Digital Therapeutics Integration:Combining pharmacological agents with digital therapeutic platforms for patient monitoring, adherence tracking, and cognitive behavioral therapy can create comprehensive pain management solutions and improve clinical outcomes.
- Market Entry in Brazil:As Brazil's healthcare system expands and its regulatory body, ANVISA, modernizes, there is a growing opportunity to introduce advanced visceral pain treatments to a large, previously underpenetrated patient population.
Industry Challenges
- Lack of Objective Biomarkers:The absence of reliable biomarkers to diagnose and stratify visceral pain conditions complicates patient selection for clinical trials and hinders the development of personalized medicine approaches.
- Demonstrating Pharmacoeconomic Value:Convincing large hospital purchasing groups and national health systems of the long-term cost-effectiveness of premium-priced neuromodulators and biologics over cheaper, established drugs requires extensive and compelling real-world evidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Visceral Pain Treatment Market |
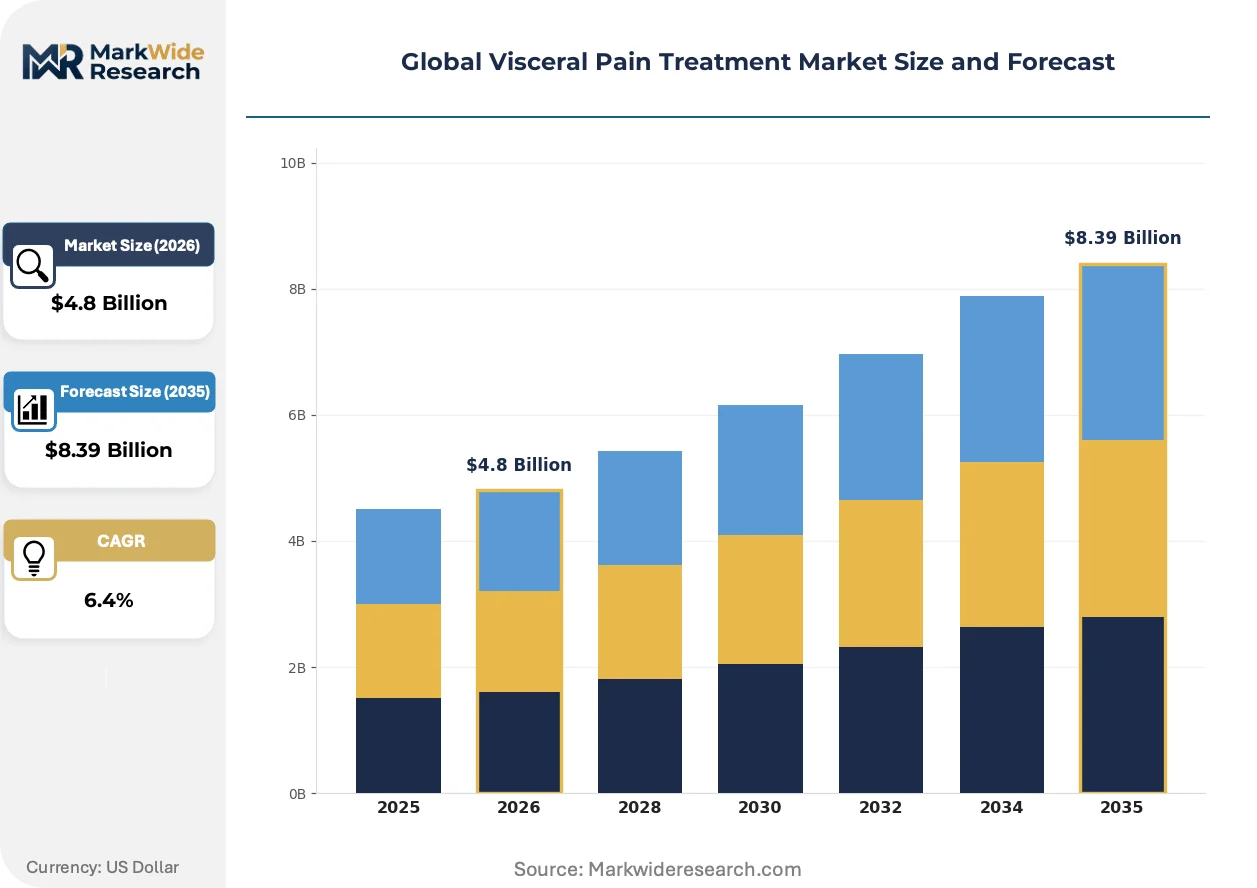
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antispasmodics, Opioids, Neuromodulators, Muscle Relaxants Therapy Area: Gastrointestinal Disorders, Urological Conditions, Gynecological Pain, Cardiovascular Pain, Neuropathic Pain End User: Specialty Clinics, Rehabilitation Centers, Pain Management Units, Ambulatory Surgical Centers Delivery Mode: Oral, Injectable, Transdermal, Rectal, Nasal Spray |
| Companies Covered | Pfizer Inc., Johnson & Johnson, AbbVie Inc., AstraZeneca, Takeda Pharmaceutical Company, Astellas Pharma Inc., Novartis AG, Sanofi SA, Grünenthal GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Visceral Pain Treatment Market Strategic Shifts & Innovations
Mechanism-based treatment is displacing broad-spectrum analgesia as the core principle in visceral pain therapy. This shift prioritizes targeting specific neural pathways, moving away from generalized symptom suppression toward precision medicine.
Targeted neuromodulation therapies apply direct electrical stimulation to nerves like the sacral nerve, interrupting pain signals. Specialized Pain Management Units adopt these systems for patients refractory to pharmacological treatments. This targeted approach is electrifying the treatment paradigm for chronic conditions like overactive bladder and certain pelvic pain syndromes.
The US FDA's Breakthrough Therapy Designation and similar expedited programs from the EMA are accelerating the review of novel non-opioid analgesics. This regulatory tailwind reduces development risk and shortens the time to market for promising drug candidates. The gastrointestinal disorders segment is most impacted, with a focus on developing safer, non-addictive alternatives for chronic conditions like IBS.
A clear shift toward value-based agreements is evident in purchasing by large hospital networks. These contracts move away from per-unit pricing, linking payment for visceral pain therapies to demonstrated patient outcomes, such as reduced pain scores or lower readmission rates. This pattern is most advanced in the United States and Germany, where integrated care models incentivize long-term efficacy.
Global Visceral Pain Treatment Market Segmentation
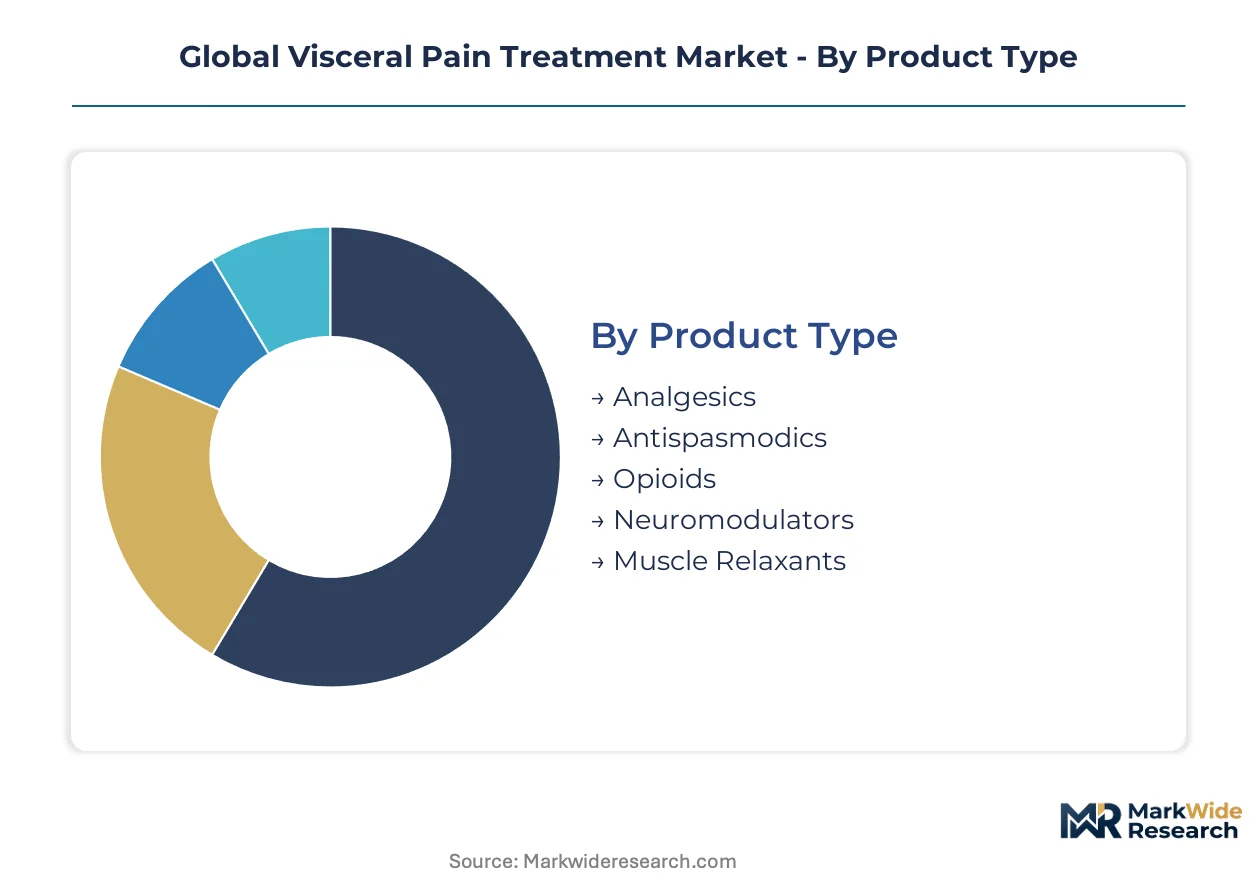
The global visceral pain treatment market segments reflect diverse therapeutic approaches and patient needs across various organ systems. Understanding these distinct segments allows stakeholders to identify areas of high investment, specific clinical challenges, and opportunities for targeted innovation.
Product Type:
The capital-intensity of developing novel visceral pain treatments varies significantly across product types, with neuromodulators requiring substantial R&D investment for device engineering and clinical validation.
- Neuromodulators:These advanced therapies involve devices or pharmacological agents that modulate nerve activity to alleviate pain signals. Their development often entails significant clinical trials to demonstrate efficacy for conditions like chronic pelvic pain and overactive bladder.
- Opioids:Potent analgesics derived from opium poppies or synthetic equivalents, opioids act on opioid receptors in the brain and spinal cord to reduce pain perception. Regulatory bodies like the US FDA and European Medicines Agency impose strict guidelines on their prescription due to addiction risks.
- Analgesics:This broad category includes over-the-counter and prescription medications primarily designed to relieve pain without causing loss of consciousness. They encompass NSAIDs and acetaminophen, commonly used for mild to moderate visceral discomfort.
- Antispasmodics:These drugs reduce muscle spasms in the gastrointestinal tract and other organs, providing relief from conditions like irritable bowel syndrome.
- Muscle Relaxants:Medications that decrease muscle tone and alleviate spasms, often prescribed for musculoskeletal pain but also used for visceral pain associated with muscle tension.
Analgesics absorb the bulk of installed capacity; Neuromodulators are expanding most quickly.
Therapy Area:
Visceral pain treatments are highly specialized by therapy area, reflecting the distinct physiological mechanisms and clinical presentations of pain originating from different internal organs.
- Gastrointestinal Disorders:This segment addresses pain arising from conditions affecting the digestive system, such as irritable bowel syndrome (IBS), inflammatory bowel disease (IBD), and functional dyspepsia. High prevalence rates of these conditions drive substantial demand for effective pain management.
- Neuropathic Pain:This category encompasses visceral pain resulting from nerve damage or dysfunction, presenting complex diagnostic and treatment challenges. Conditions like diabetic neuropathy affecting the bladder or post-herpetic neuralgia impacting internal organs fall into this segment.
- Urological Conditions:Treatments for pain associated with the urinary tract and reproductive organs, including interstitial cystitis, bladder pain syndrome, and chronic prostatitis. These conditions often require specialized pharmacological and interventional therapies.
- Gynecological Pain:This segment includes therapies for chronic pelvic pain, endometriosis, dysmenorrhea, and other pain conditions specific to the female reproductive system.
- Cardiovascular Pain:Treatments for pain related to heart conditions, such as angina pectoris or pericarditis, where the pain originates from the cardiovascular system.
Gastrointestinal Disorders hold the largest application share; Neuropathic Pain treatments are experiencing significant growth.
End User:
The end-user landscape for visceral pain treatments is characterized by varying levels of specialization and patient volume, influencing procurement patterns and service delivery models.
- Pain Management Units:These specialized healthcare facilities focus exclusively on diagnosing and treating chronic pain conditions, including complex visceral pain syndromes. They often adopt advanced interventional procedures and neuromodulation therapies.
- Specialty Clinics:Clinics dedicated to specific medical disciplines, such as gastroenterology, urology, or gynecology, frequently manage visceral pain as a symptom of underlying conditions. These clinics often integrate pharmacological and lifestyle interventions.
- Rehabilitation Centers:Facilities that provide comprehensive rehabilitation services, including physical therapy and pain management, for patients recovering from illness or injury. They often address chronic pain through a multidisciplinary approach.
- Ambulatory Surgical Centers:Outpatient facilities where surgical procedures not requiring overnight hospitalization are performed. They might administer short-term pain interventions or implantable devices.
Pain Management Units drive specialized care; Ambulatory Surgical Centers are expanding their scope.
Delivery Mode:
The maturity of various delivery modes impacts patient convenience, adherence, and the speed of therapeutic action for visceral pain treatments.
- Oral:Medications administered by mouth, representing the most common and convenient delivery method for many visceral pain treatments. This mode is suitable for long-term management of chronic conditions.
- Injectable:Therapies delivered via injection (intravenous, intramuscular, subcutaneous) for rapid action or when oral administration is not feasible. This mode is often used for acute pain or specific targeted therapies.
- Transdermal:Medications delivered through the skin, typically via patches, allowing for sustained release and systemic absorption. This method offers continuous pain relief and bypasses first-pass metabolism.
- Rectal:Medications administered rectally, often for localized effect in the lower gastrointestinal tract or when oral intake is difficult.
- Nasal Spray:Medications delivered via nasal spray, offering rapid absorption into the bloodstream, particularly useful for acute pain episodes.
Oral delivery dominates market volume; Injectable delivery modes are gaining traction for specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for visceral pain treatments is particularly acute in developed economies with aging populations and robust healthcare infrastructure. These regions often lead in adopting advanced therapies and navigating complex reimbursement landscapes. Emerging markets also present significant growth opportunities as healthcare access expands.
United States
The United States market exhibits significant demand for non-opioid analgesics and neuromodulators due to the public health crisis surrounding opioid addiction. The US FDA's provision of fast-track and breakthrough therapy designations accelerates development for innovative pain treatments. Biotech hubs in regions like Boston and San Francisco are centers for pharmaceutical innovation, driving new therapeutic avenues.
Germany
German demand for visceral pain treatments is driven by an aging demographic with a higher incidence of chronic conditions. The European Medicines Agency (EMA) sets stringent efficacy and safety standards for market access, influencing pharmaceutical development. Integrated care models in regions like Bavaria and Hesse incentivize long-term efficacy and value-based agreements for therapies.
Japan
Japan's aging population creates sustained demand for effective and safe long-term treatment options for chronic visceral pain. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates drug approvals, emphasizing safety profiles for new medications. Pharmaceutical research and development clusters in Tokyo and Osaka are actively pursuing novel pain management solutions.
Brazil
Brazil presents a growing opportunity for advanced visceral pain treatments as its healthcare system expands and modernizes. The national health surveillance agency, ANVISA, is streamlining regulatory processes, facilitating market entry for innovative therapies. Major urban centers like São Paulo and Rio de Janeiro are developing healthcare infrastructure to serve a large, previously underpenetrated patient population.
China
Chinese demand for visceral pain treatment is increasing due to a large patient base and evolving healthcare access. The National Medical Products Administration (NMPA) oversees drug approvals, with a focus on addressing unmet medical needs. Pharmaceutical manufacturing and R&D parks in Shanghai and Beijing are expanding capabilities for domestic and international drug development.
Global Visceral Pain Treatment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue novel therapeutic modalities, particularly in neuromodulation and non-opioid analgesia. The market structure features a mix of large pharmaceutical conglomerates and specialized biotechnology firms. Strategic archetypes include diversified pharmaceutical giants, focused pain management specialists, and innovative device manufacturers. Key competitive moves involve extensive clinical trial investment to secure formulary placements and strategic partnerships for digital therapeutic integration.
Specialists in complex gastrointestinal disorder therapies, such as AbbVie Inc., exemplify a focused approach to specific visceral pain segments. Diversified pharmaceutical companies like Pfizer Inc. leverage extensive clinical trial portfolios to maintain broad market presence across various pain indications. European pharmaceutical firms, including Grünenthal GmbH, occupy positions in the pain management sector, often with a strong emphasis on research and development for novel analgesics.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| AbbVie Inc. |
| AstraZeneca |
| Takeda Pharmaceutical Company |
| Astellas Pharma Inc. |
| Novartis AG |
| Sanofi SA |
| Grünenthal GmbH |
| Others |
Cost & Logistics Intelligence
Specialized medical professional concentrations in biotech hubs like Boston and San Francisco influence pricing-tier spreads for advanced visceral pain treatments. These regions command premium pricing due to high R&D investment and access to specialized talent for novel therapeutic development.
Pricing Analysis
Volume-driven generic analgesics maintain lower margins, while novel neuromodulators achieve premium pricing due to their targeted mechanisms and R&D intensity. Value-based agreements are becoming the dominant pricing model for high-cost therapies in large hospital networks. Price differentiation stems from demonstrated clinical efficacy and regulatory approvals from bodies like the US FDA and EMA. Pricing pressure stems from restrictive reimbursement policies in markets like the United States. Payers in the United States exhibit high price sensitivity for established drug classes, while specialized pain management units prioritize efficacy for advanced treatments.
Supply Chain Analysis
Integrated delivery systems and large hospital networks manage procurement for visceral pain treatments, ensuring supply chain reliability. Geographic supply concentration for R&D and manufacturing centers on biotech hubs in the United States, Germany, and Japan. Raw material dependencies include pharmaceutical APIs and specialized device components for neuromodulation. Regulatory approval timelines represent a structural supply chain risk, impacting market entry and product availability. Distribution runs through specialized pharmaceutical distributors and direct channels to large healthcare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play, as stringent efficacy hurdles and high R&D investment force out smaller, less capitalized players.
For Market Incumbents:Hedge against generic drug competition by accelerating investment in novel non-opioid analgesics and targeted neuromodulators. Leverage extensive clinical trial portfolios to secure formulary placements within integrated delivery systems. Reinforce supply chain reliability and demonstrate pharmacoeconomic value to counter restrictive reimbursement policies. Strategic partnerships for digital therapeutic integration can enhance patient outcomes and differentiate offerings.
For New Entrants and Emerging Players:Launch innovative therapies via expedited regulatory pathways, targeting underserved pain conditions like endometriosis and interstitial cystitis. Focus on developing therapies with clear superiority over existing treatments, addressing the lack of objective biomarkers. Penetrate the Brazilian market as its healthcare system expands, offering advanced visceral pain treatments to a previously underpenetrated patient population. Go-to-market strategies should emphasize targeted mechanisms of action and improved safety profiles.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized biotechnology firms given the shift towards precision medicine and non-opioid solutions. Long-term viability is strong for companies developing targeted neuromodulators and digital therapeutics that integrate with pharmacological agents. Acquisition targets should possess robust R&D pipelines for non-gastrointestinal visceral pain. A key signal to watch is the successful completion of Phase 3 clinical trials for novel non-addictive pain medications.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel non-opioid analgesics addressing the public health crisis. |
| Regulatory Approval Pathway | Secures expedited FDA and EMA designations for promising breakthrough therapies. |
| Strategic Partnership | Integrates digital therapeutic platforms to enhance patient monitoring and adherence. |
| Pipeline Diversification | Addresses underserved pain conditions like endometriosis, expanding therapeutic reach. |
| Market Entry Strategy | Penetrates high-growth emerging markets such as Brazil with advanced treatments. |
Research Approach
Independent corroboration across US FDA filings, EMA submissions, and ClinicalTrials.gov underwrites the qualitative findings of this analysis. Primary research involved interviews with pain management specialists, pharmaceutical R&D executives, hospital procurement managers, and regulatory affairs leads. This approach combined bottom-up market sizing with top-down validation, integrating diverse data points.
The rate-of-change decomposition framework projects market expansion across the analysis window. Segmentation dimensions modeled include product type, therapy area, end user, delivery mode, and regional regulatory clusters. Compound annual growth rates (CAGRs) derive from historical trends and projected shifts in treatment paradigms. Key forecast inputs include the incidence rates of chronic visceral pain conditions and R&D pipeline success rates for non-opioid therapies.
The model assumes a particular technology adoption path; alternative pathways for neuromodulators would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and clinical trial outcomes. Unforeseen shifts in reimbursement policies or major clinical trial failures represent specific risk factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Cold Pain Therapy Market
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
Painkillers Market
Pain Management
Pain Patches Market
Pain Management
Palliative Care Market
Pain Management
Postoperative Pain Market
Pain Management
Visceral Pain Market
Pain Management
Neuropathic Pain Market
Pain Management
Global Morphine Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Asia-Pacific Tattoo Numbing Cream Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Dyspareunia Market
Pain Management
Arthralgia Management Market