
 Secondary Hyperparathyroidism Treatment Market | 2026-2036
Secondary Hyperparathyroidism Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Hyperparathyroidism Treatment Market Analytics
North American biopharmaceutical manufacturing is consolidating around specialized nephrology therapeutics. Amgen Inc. leverages its established cinacalcet franchise to sustain leadership in calcimimetic production. AbbVie Inc. competes through its paricalcitol portfolio, which anchors vitamin D analogue supply for dialysis-dependent patients. OPKO Health Inc. differentiates via extended-release calcifediol formulations that occupy a distinct pharmacokinetic niche.
Secondary hyperparathyroidism treatment encompasses pharmaceutical interventions that modulate parathyroid hormone secretion through calcium-sensing receptor activation, vitamin D receptor agonism, or phosphate load reduction, primarily serving patients with mineral and bone disorders arising from chronic kidney disease. The injectable delivery mode dominates institutional settings where intravenous cinacalcet and paricalcitol administration accompanies hemodialysis sessions. Calcimimetics represent the fastest-expanding product category as oral alternatives broaden access beyond dialysis centers. Dialysis centers command the deepest margin pools due to bundled reimbursement structures that incentivize protocol adherence.
FDA renal impairment guidance and EMA's nephrology scientific advice framework jointly shape clinical trial endpoints and label expansion pathways for novel mineral metabolism therapies. The IRA's Medicare drug price negotiation provisions are forcing portfolio prioritization decisions among manufacturers with overlapping nephrology assets. Stakeholders must monitor emerging biosimilar competition in calcimimetic and vitamin D analogue categories while evaluating homecare infusion infrastructure investments.
Market Dynamics
The IRA's Medicare drug price negotiation provisions are forcing manufacturers to restructure nephrology portfolios around protected therapeutic categories, while dialysis center consolidation accelerates demand for protocol-compatible therapies.
Growth Catalysts
- Bundled Reimbursement Models:Dialysis centers in the United States capture margin efficiencies through integrated mineral and bone disorder protocols that align calcimimetic and vitamin D analogue administration with dialysis sessions.
- EMA Nephrology Scientific Advice Framework:Streamlined European regulatory pathways for novel mineral metabolism therapies compress clinical trial design timelines and reduce development uncertainty.
- Extended-Release Formulations:Oral calcifediol alternatives are expanding into homecare settings, broadening patient access beyond institutional dialysis environments.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of complex vitamin D analogues depends on specialized contract manufacturers concentrated in India and China, creating supply vulnerability.
- Calcimimetic Biosimilar Pipeline:Pending FDA abbreviated approval pathways for cinacalcet alternatives threaten originator pricing power and portfolio returns.
- Phosphate Binder Substitution:Non-calcium phosphate binders compete for mineral metabolism management budgets, diverting prescriber attention from parathyroid hormone modulation therapies.
Strategic Opportunities
- Peritoneal Dialysis Expansion:Home-based renal replacement therapy growth in Germany and Japan creates demand for patient-administered oral calcimimetics outside traditional hemodialysis centers.
- Pediatric Mineral and Bone Disorder Indications:FDA pediatric study requirements and orphan drug incentives open label expansion pathways for existing calcimimetic assets.
- Integrated Digital Therapeutics:Remote patient monitoring platforms combined with medication adherence tools address phosphate control compliance gaps in chronic kidney disease populations.
Industry Challenges
- Specialized Nephrology Clinical Trial Infrastructure:Recruitment of dialysis-dependent patients for mineral metabolism studies requires site networks with vascular access capabilities and protocol adherence track records.
- Legacy Formulation Manufacturing Retooling:Transition from intravenous to oral dominance demands capital deployment into high-potency containment facilities and modified release technology platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Hyperparathyroidism Treatment Market |
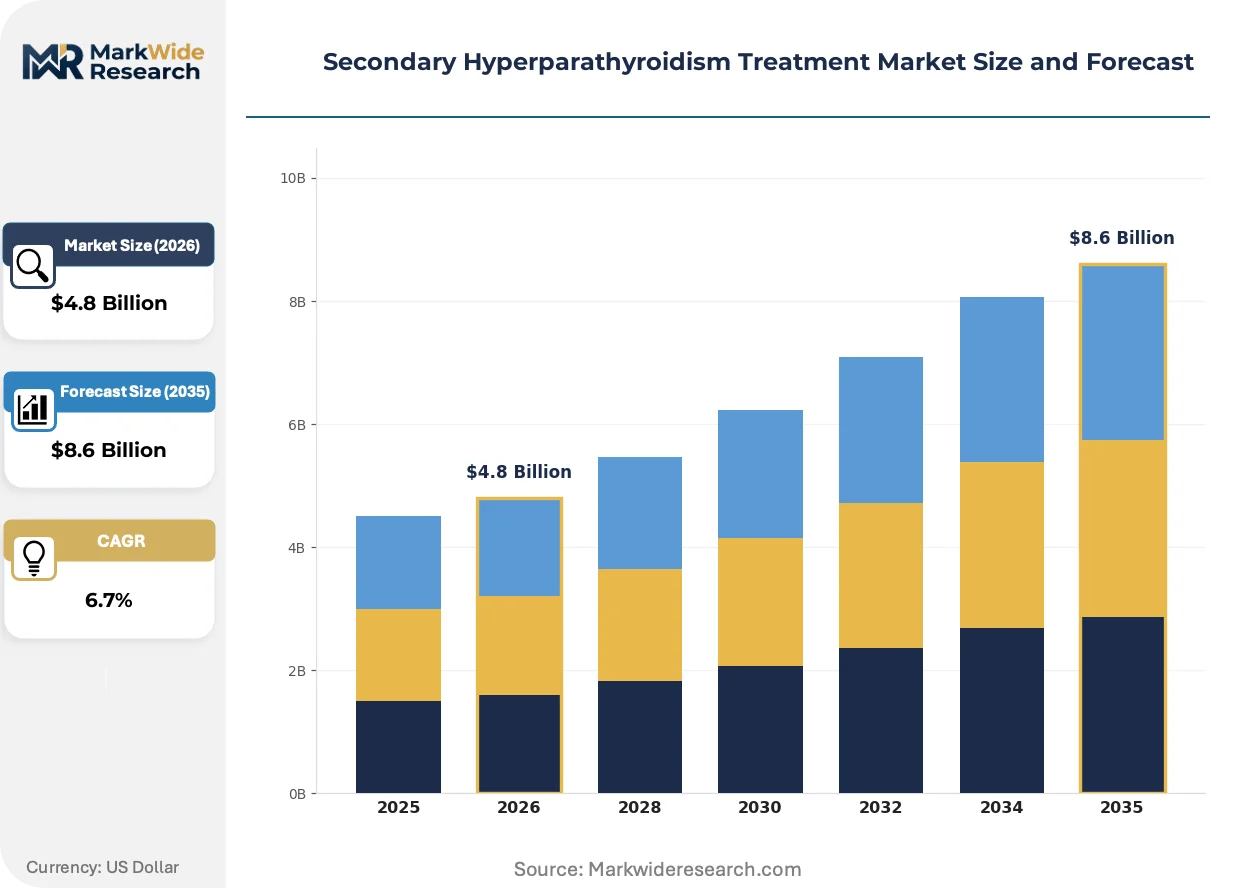
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcimimetics, Vitamin D Supplements, Phosphate Binders, Hormone Replacement Therapy Area: Chronic Kidney Disease, End-Stage Renal Disease, Osteoporosis, Vitamin D Deficiency End User: Hospitals, Clinics, Homecare Settings, Dialysis Centers Delivery Mode: Oral, Injectable, Intravenous, Transdermal |
| Companies Covered | Amgen Inc., AbbVie Inc., OPKO Health Inc., Sanofi S.A., Fresenius Medical Care AG & Co. KGaA, Kyowa Kirin Co. Ltd., Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche AG, Astellas Pharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Hyperparathyroidism Treatment Market Evolving Landscape
Product development trajectories in secondary hyperparathyroidism treatment are converging around patient-centered delivery models that reduce institutional dependency while preserving therapeutic efficacy.
Extended-release calcifediol formulations are expanding into homecare channels, enabling once-daily oral administration that eliminates the need for intravenous supplementation during dialysis. Nephrology practices in the United States and Western Europe are adopting these alternatives for peritoneal dialysis patients and pre-dialysis chronic kidney disease populations. This shift is compressing the traditional institutional revenue capture model and redistributing margin pools toward retail pharmacy and specialty distributor networks.
REACH authorization requirements for pharmaceutical manufacturing are tightening impurity control standards for vitamin D analogue synthesis across European supply chains. EMA's evolving quality guidelines now mandate enhanced analytical characterization of secosteroid-related substances, forcing contract manufacturers to upgrade chromatography infrastructure. Small-molecule nephrology therapeutics face extended validation timelines as a result, with multi-source vitamin D portfolios experiencing the most significant compliance burden.
Home infusion services are displacing traditional dialysis center medication administration for select calcimimetic regimens, particularly among patients with established vascular access for other therapies. Specialty pharmacy providers are capturing patient relationships previously held by institutional pharmacies, restructuring prescriber referral patterns. This channel migration is most visible in Medicare Advantage populations where capitated arrangements incentivize site-of-care optimization.
Secondary Hyperparathyroidism Treatment Market Segmentation
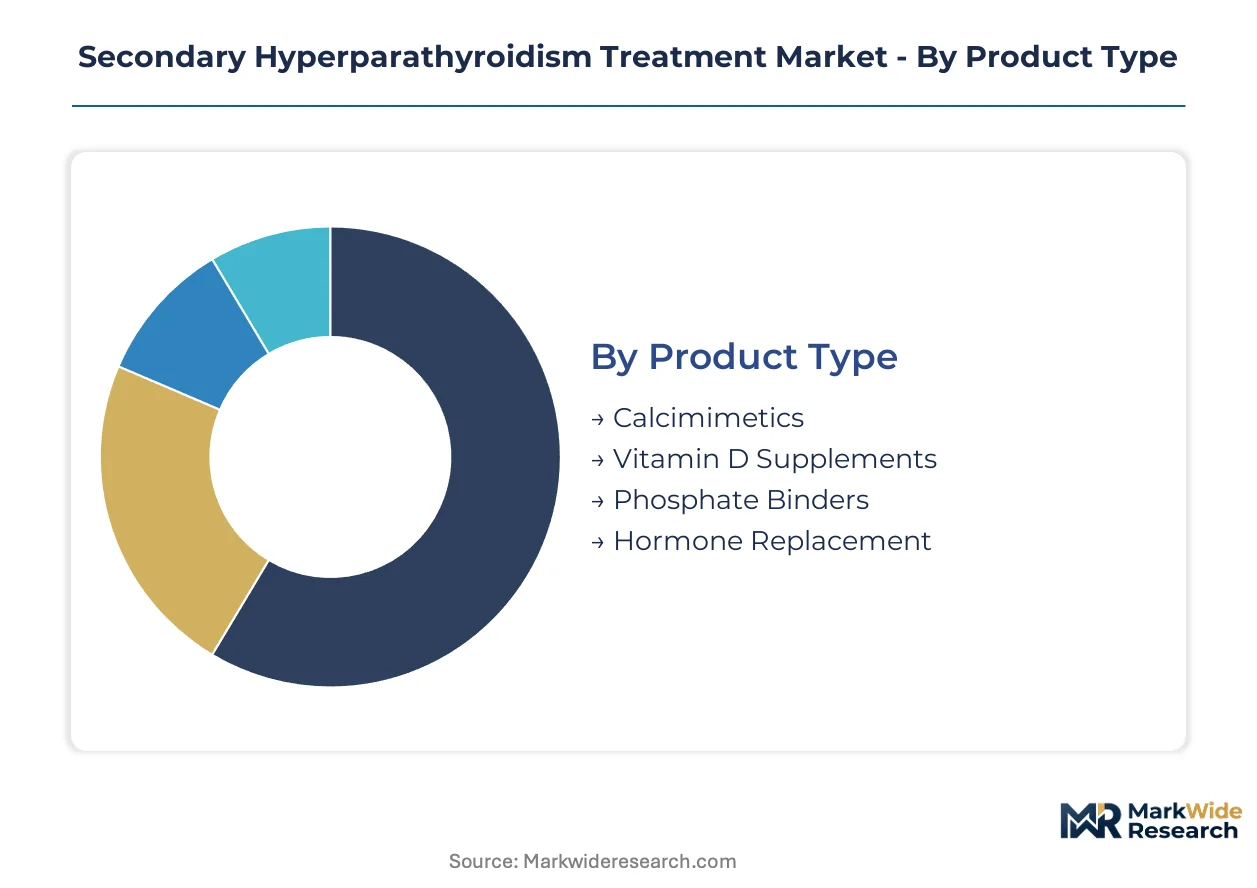
Secondary hyperparathyroidism treatment segmentation reveals how regulatory pathways, reimbursement structures, and patient acuity reshape commercial priorities across therapeutic categories. Each dimension carries distinct FDA and EMA certification burdens that determine market access timelines and portfolio investment decisions.
Product Type:
FDA's renal impairment guidance and EMA's nephrology scientific advice framework impose divergent approval requirements across these therapeutic classes, with calcimimetics facing the most intensive cardiovascular safety surveillance.
- Calcimimetics:Calcium-sensing receptor agonists including cinacalcet modulate parathyroid hormone secretion through allosteric receptor activation. Demand concentrates in United States dialysis centers where bundled reimbursement incentivizes protocol integration with hemodialysis sessions.
- Vitamin D Supplements:Secosteroid analogues such as paricalcitol and doxercalciferol activate vitamin D receptors to suppress PTH synthesis while managing mineral metabolism. REACH authorization requirements in Europe now mandate enhanced analytical characterization of related substances, extending validation timelines for multi-source portfolios.
- Phosphate Binders:Calcium-based and non-calcium agents reduce phosphate load to indirectly suppress parathyroid hormone secretion. The category competes for mineral metabolism management budgets against direct PTH modulators.
- Hormone Replacement:Synthetic parathyroid hormone formulations address severe hypoparathyroidism complications in select renal populations. Applications remain narrow due to black-box warnings and restricted distribution requirements.
Leading the category by volume: Vitamin D Supplements. Growing fastest: Calcimimetics.
Therapy Area:
Patient population severity determines prescriber specialty, site of care, and therapy intensity across these clinical indications.
- Chronic Kidney Disease:Pre-dialysis populations with estimated glomerular filtration rates below 60 mL/min/1.73m² drive oral calcimimetic and extended-release calcifediol demand outside institutional settings.
- End-Stage Renal Disease:Dialysis-dependent patients requiring intensive mineral and bone disorder management generate the deepest revenue pools through intravenous cinacalcet and paricalcitol administration.
- Osteoporosis:Bone mineral density complications in renal populations create adjacency opportunities for anabolic agents combined with PTH modulation therapy.
- Vitamin D Deficiency:Nutritional insufficiency states in early CKD populations support preventive supplementation protocols ahead of secondary hyperparathyroidism onset.
End-Stage Renal Disease commands the largest addressable population. Chronic Kidney Disease demonstrates the steepest expansion trajectory as oral alternatives penetrate pre-dialysis care.
End User:
Site-of-care economics and reimbursement mechanics fragment purchasing authority across institutional and ambulatory channels.
- Hospitals:Acute care settings manage hyperparathyroidism complications including severe hypercalcemia and bone fractures requiring inpatient intervention.
- Clinics:Nephrology practices coordinate pre-dialysis mineral metabolism monitoring and oral therapy initiation for progressive CKD patients.
- Homecare Settings:Peritoneal dialysis expansion in Germany and Japan creates demand for patient-administered oral calcimimetics outside traditional hemodialysis infrastructure.
- Dialysis Centers:United States bundled reimbursement models capture margin efficiencies through integrated mineral and bone disorder protocols aligned with dialysis sessions.
Dialysis Centers generate the highest revenue concentration. Homecare Settings are climbing the fastest as oral formulations displace intravenous administration.
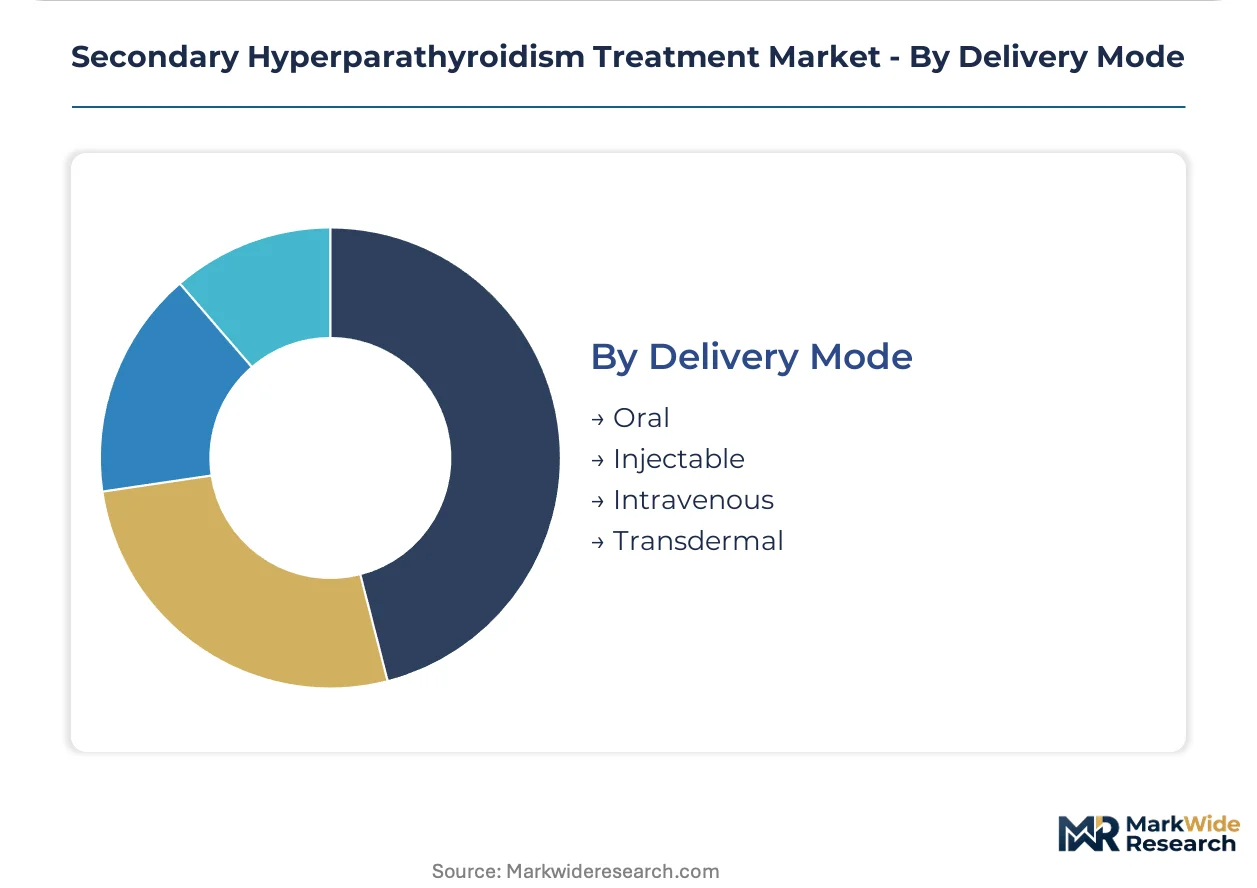
Delivery Mode:
Formulation technology determines patient autonomy, compliance profiles, and channel economics across administration routes.
- Oral:Extended-release calcifediol and immediate-release cinacalcet tablets enable home administration for peritoneal dialysis and pre-dialysis populations.
- Injectable:Subcutaneous calcimimetic formulations suit patients with established vascular access for other therapies, displacing some intravenous administration.
- Intravenous:Cinacalcet and paricalcitol infusion during hemodialysis sessions dominates institutional revenue capture in United States dialysis centers.
- Transdermal:Novel delivery systems remain developmental, targeting compliance improvement in populations with swallowing difficulties or injection aversion.
Intravenous administration retains the largest volume share. Oral delivery is gaining share fastest as formulation innovation expands patient eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized vitamin D analogue synthesis clusters in Hyderabad and Shanghai anchor the pharmaceutical supply base for secondary hyperparathyroidism therapeutics. These manufacturing concentrations determine API availability and REACH compliance costs across downstream formulation markets.
United States
Dialysis center consolidation in Texas and Florida drives bundled reimbursement optimization for intravenous cinacalcet protocols. The IRA's Medicare drug price negotiation provisions force manufacturers to prioritize calcimimetic assets outside the negotiation schedule. Nephrology practices in the Southeast are adopting extended-release calcifediol for pre-dialysis CKD populations.
Germany
Peritoneal dialysis expansion in Bavaria and North Rhine-Westphalia creates demand for patient-administered oral calcimimetics outside hemodialysis infrastructure. EMA nephrology scientific advice frameworks streamline approval pathways for novel mineral metabolism therapies. REACH authorization requirements mandate enhanced analytical characterization of secosteroid-related substances from contract manufacturers.
Japan
Aging CKD demographics in the Kanto region sustain high treatment volumes for vitamin D receptor agonists. PMDA guidance on cardiovascular safety endpoints shapes clinical trial design for calcimimetic candidates. Home-based renal replacement therapy growth in Osaka-Kyoto corridor drives oral formulation demand.
China
Domestic NMPA approvals for cinacalcet generics accelerate price competition in dialysis center procurement. Yangtze River Delta biopharmaceutical clusters specialize in high-potency vitamin D analogue contract manufacturing. Sichuan-Chongqing hospital networks pilot integrated mineral and bone disorder protocols.
India
Hyderabad and Ahmedabad API manufacturers supply complex secosteroid intermediates to global formulation houses. CDSCO streamlined approval pathways for nephrology therapeutics reduce time-to-market for domestic calcimimetic producers. Dialysis center chains in Maharashtra expand bundled service models.
Secondary Hyperparathyroidism Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue extended-release oral formulations and pediatric indication expansions. The vendor base stratifies across calcimimetic originators, vitamin D analogue specialists, and integrated dialysis service providers. Three archetypes dominate: large-cap biopharmaceuticals with nephrology franchises, mid-cap endocrine specialists, and vertically integrated dialysis operators. Competitive moves concentrate on M&A for pipeline assets and strategic partnerships for homecare channel access.
Among US-based biopharmaceuticals, Amgen Inc. and AbbVie Inc. occupy positions representing calcimimetic and vitamin D analogue archetypes respectively. OPKO Health Inc. exemplifies the extended-release formulation specialist tier. Sanofi S.A. and Fresenius Medical Care AG & Co. KGaA anchor the European competitive set, with the latter representing vertical integration into dialysis service delivery. Kyowa Kirin Co. Ltd. and Astellas Pharma Inc. sit within the Asia-Pacific originator group.
| Leading Market Players |
|---|
| Amgen Inc. |
| AbbVie Inc. |
| OPKO Health Inc. |
| Sanofi S.A. |
| Fresenius Medical Care AG & Co. KGaA |
| Kyowa Kirin Co. Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche AG |
| Astellas Pharma Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up dialysis center networks in Texas and Florida enforce procurement discipline through bundled reimbursement contracts, compressing manufacturer margins while concentrating purchasing power across integrated mineral and bone disorder protocols. This ownership pattern tightens pricing discipline for intravenous cinacalcet and paricalcitol, forcing suppliers to absorb cost compression or cede volume to contract manufacturers in India and China.
Pricing Analysis
Warranty and service bundling separates originator calcimimetics from emerging biosimilar alternatives, with Amgen's cinacalcet franchise commanding premium positioning through protocol integration support and site-of-care training. Three-tier pricing structure across premium originator, authorized generic, and economy biosimilar levels reflects FDA approval tier and cardiovascular safety surveillance burden. Price erosion runs through the economy tier as Indian and Chinese contract manufacturers scale secosteroid API output. Dialysis center procurement committees demonstrate highest price sensitivity, while hospital formularies retain modest brand loyalty for inpatient hypercalcemia management.
Supply Chain Analysis
Single-source vulnerability sits with Hyderabad and Shanghai API manufacturers for complex vitamin D analogue synthesis, where REACH authorization requirements and enhanced analytical characterization mandates have extended validation timelines. Active pharmaceutical ingredient production draws from India, China, and limited European specialist facilities, with secosteroid intermediates and high-potency containment equipment serving as critical inputs. Tariff exposure on Chinese-manufactured calcifediol precursors threatens margin stability for multi-source vitamin D portfolios. Distribution runs through specialty pharmacy networks and dialysis center captive pharmacies, with homecare channel migration accelerating in Medicare Advantage populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secondary hyperparathyroidism treatment is consolidating around calcimimetic originators with cardiovascular safety databases and vertically integrated dialysis operators, as the IRA's Medicare drug price negotiation provisions force portfolio prioritization decisions that marginalize single-asset nephrology players.
For Market Incumbents: Deepen backward integration into high-potency vitamin D analogue manufacturing to offset REACH compliance cost inflation and secure API supply continuity. Lock in long-term offtake agreements with Hyderabad and Shanghai contract manufacturers before biosimilar competition intensifies. Cinacalcet originators must defend formulary position through pediatric indication expansion and homecare channel partnerships that preserve patient relationships outside dialysis center consolidation. For New Entrants and Emerging Players: CDSCO streamlined approval pathways in India open a window for domestic calcimimetic producers to capture share in Maharashtra dialysis center chains before multinational originators establish local manufacturing. Target peritoneal dialysis populations in Germany and Japan with patient-administered oral formulations that bypass institutional procurement gatekeepers. Go-to-market execution should anchor on specialty pharmacy partnerships and remote patient monitoring platform integration to demonstrate adherence outcomes that justify reimbursement. For Investors and Strategic Acquirers: Distressed-cycle entries favor extended-release formulation specialists with distinct pharmacokinetic patents and homecare channel infrastructure in the United States. Long-term viability hinges on regulatory moats around cardiovascular safety databases and pediatric orphan indications that resist biosimilar substitution. Watch for FDA abbreviated approval pathway decisions on cinacalcet biosimilars as the inflection signal for originator pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA nephrology scientific advice compresses clinical trial design timelines for novel mineral metabolism therapies. |
| Manufacturing Scale-Up | High-potency containment facility investment enables oral calcifediol production for homecare channel expansion. |
| Pipeline Diversification | Pediatric mineral and bone disorder indications open orphan drug exclusivity extensions for existing calcimimetic assets. |
| Strategic Partnership | Specialty pharmacy alliances capture patient relationships migrating from dialysis center captive pharmacies. |
| Geographic Expansion | Peritoneal dialysis growth in Bavaria and Osaka-Kyoto corridor creates demand for patient-administered oral therapies. |
Research Methodology
Document review covered FDA renal impairment guidance, EMA nephrology scientific advice frameworks, ClinicalTrials.gov mineral metabolism study registrations, and dialysis center bundled reimbursement documentation, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from CMS Medicare data, GPO contracts, and SEC 10-K nephrology segment disclosures. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Segmentation outputs across product type, therapy area, end user, and delivery mode dimensions were calibrated against historical approval timelines and reimbursement mechanics throughout the projection horizon. CAGRs were derived from patient volume trajectories in chronic kidney disease and end-stage renal disease populations, adjusted for oral formulation penetration rates and dialysis center consolidation patterns. Forecast inputs incorporated PMDA cardiovascular safety guidance, IRA negotiation schedule impacts, and REACH authorization timeline extensions.
Caveats apply where FDA biosimilar approval pathway decisions, EMA quality guideline revisions, or Medicare Advantage capitation rate changes could materially shift the outlook. Forecasts reflect assumptions around bundled reimbursement sustainability and API supply continuity that may require revision. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Ascites Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market