
 US Magnetic Resonance Imaging Coils Market | 2026-2036
US Magnetic Resonance Imaging Coils Market Size, Share, and Industry Trends Forecast 2026-2036
US Magnetic Resonance Imaging Coils Market Insights
Outpatient clinics is repositioning coil procurement toward flexible, multi-purpose arrays that serve diverse anatomical protocols without dedicated hardware swaps. GE Healthcare leverages its installed base of MRI systems to sustain aftermarket coil attach rates across hospital networks. Siemens Healthineers anchors its US position through R&D intensity in high-channel neurovascular arrays. Canon Medical Systems competes on manufacturing scale for extremity coils serving orthopedic specialist chains.
Magnetic resonance imaging coils are radiofrequency antenna assemblies, typically constructed from copper or superconducting elements arranged in phased arrays, that transmit excitation pulses and receive signal return from targeted anatomical regions to enable tomographic image reconstruction. Their primary commercial purpose is to optimize signal-to-noise ratio and spatial resolution across varying field strengths and patient positioning requirements. Head coils and neurovascular arrays command premium positioning due to the technical complexity of brain and spine imaging protocols that demand high element counts. Surface coils occupy the fastest-expanding margin pool as ambulatory settings prioritize lightweight, disposable-compatible designs for point-of-care musculoskeletal diagnostics.
FDA 510(k) premarket notification requirements govern coil safety and electromagnetic compatibility, while NHTSA-influenced MRI suite siting standards affect hospital infrastructure investment cycles that include coil procurement. The FDA's ongoing software-as-medical-device guidance for AI-reconstruction-integrated coils is reshaping validation requirements for manufacturers seeking clearance. State-level certificate-of-need regulations in New York, Illinois, and Washington directly constrain MRI scanner—and by extension coil—capacity expansion in concentrated metropolitan markets. Stakeholders must monitor whether CMS diagnostic imaging fee schedule adjustments for multi-parametric sequences will incentivize coil upgrades or extend replacement cycles.
Market Dynamics
Health system consolidation across Texas, California, and Florida is compressing procurement timelines and favoring coil vendors capable of delivering high-channel-count arrays through centralized purchasing agreements rather than fragmented site-by-site sales.
Growth Catalysts
- Diagnostic center expansion:Same-day imaging protocols are expanding coil inventories at outpatient facilities, driving replacement cycles for multi-purpose arrays.
- FDA 510(k) pathway efficiency:Streamlined premarket notification processes for multi-channel arrays are shortening time-to-market for domestic manufacturers.
- Superconducting element advancement:Phased array architectures incorporating advanced copper configurations are optimizing signal-to-noise ratios across 1.5T and 3T field strengths.
Market Restraints
- Certificate-of-need barriers:New York, Illinois, and Washington state regulations directly constrain MRI scanner capacity expansion, limiting coil demand growth in concentrated metropolitan markets.
- High-channel array cost structure:Neurovascular and head coil systems require specialized manufacturing processes that elevate unit economics beyond ambulatory budget thresholds.
- Electromagnetic compatibility validation:FDA electromagnetic compatibility testing requirements extend development timelines and increase regulatory compliance expenditure for novel coil geometries.
Strategic Opportunities
- Surface coil point-of-care penetration:Lightweight, disposable-compatible designs are capturing musculoskeletal diagnostic volume in orthopedic specialist chains and urgent care networks.
- AI-reconstruction integration:FDA software-as-medical-device guidance for machine learning-integrated coils is creating first-mover advantages for vendors with validated algorithm pipelines.
- CMS fee schedule positioning:Multi-parametric sequence reimbursement adjustments may incentivize coil upgrade cycles at hospital networks seeking enhanced diagnostic throughput.
Industry Challenges
- RF engineer talent scarcity:Specialized expertise in phased array design and electromagnetic field modeling is concentrating at established OEMs, constraining startup innovation velocity.
- Legacy system integration complexity:Backward compatibility requirements with installed MRI system bases complicate coil architecture decisions and extend validation protocols.
- Multi-site standardization friction:Consolidated health systems struggle to harmonize coil protocols across acquired facilities with heterogeneous scanner vintages and manufacturer ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Magnetic Resonance Imaging Coils Market |
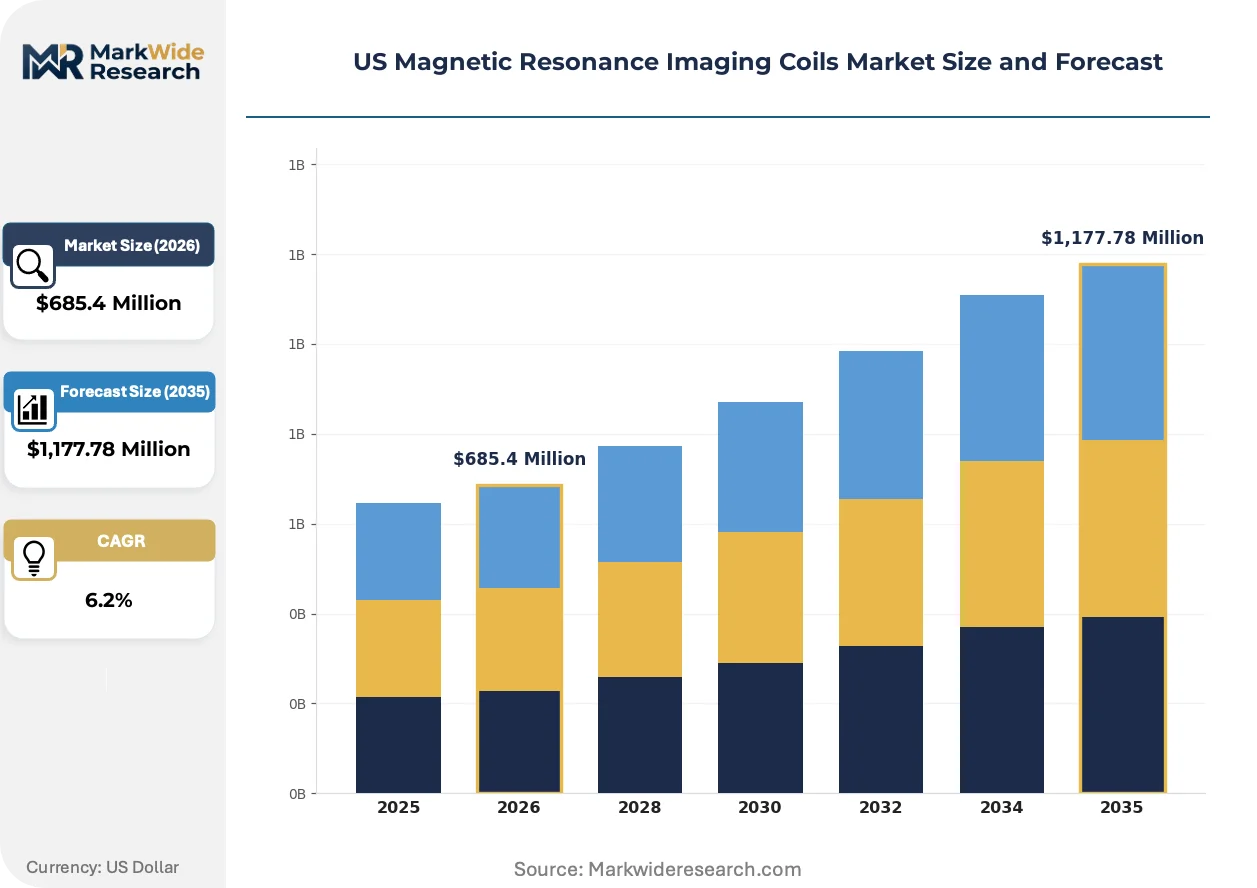
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head Coils, Body Coils, Extremity Coils, Surface Coils End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Clinics Technology: High-Field, Low-Field, Open MRI, Closed MRI Application: Oncology, Neurology, Cardiology, Musculoskeletal |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, Esaote S.p.A., MR Instruments, Inc. (MRIi), Rapid MR International, LLC., ScanMed, LLC., Noras MRI Products GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Magnetic Resonance Imaging Coils Market Trends and Innovations
Coil architecture is converging toward flexible, anatomically adaptive platforms that reduce hardware swap frequency while accommodating expanding diagnostic protocol complexity across outpatient and inpatient settings.
Digital coil technology is unifying signal processing and transmission functions within single integrated assemblies. Academic medical centers and large hospital networks are adopting these platforms at accelerated cadences to streamline workflow standardization. This unification is compressing the traditional separation between premium neurovascular arrays and general-purpose surface coils, enabling vendors to serve broader clinical indications with fewer discrete SKUs.
FDA software-as-medical-device guidance for AI-reconstruction-integrated coils is reshaping validation requirements and submission documentation. Manufacturers must now demonstrate algorithm performance across diverse patient populations and imaging scenarios prior to 510(k) clearance. Neurovascular and cardiac coil segments are most affected, with vendors restructuring quality management systems to accommodate continuous learning model updates.
Hospital procurement departments are consolidating coil purchasing through centralized capital equipment committees rather than radiology department autonomy. Group purchasing organizations and health system supply chain offices are displacing traditional distributor relationships in Texas, California, and Florida markets. This concentration is most visible at multi-hospital networks executing standardized coil specifications across twenty-plus imaging sites.
US Magnetic Resonance Imaging Coils Market Segmentation
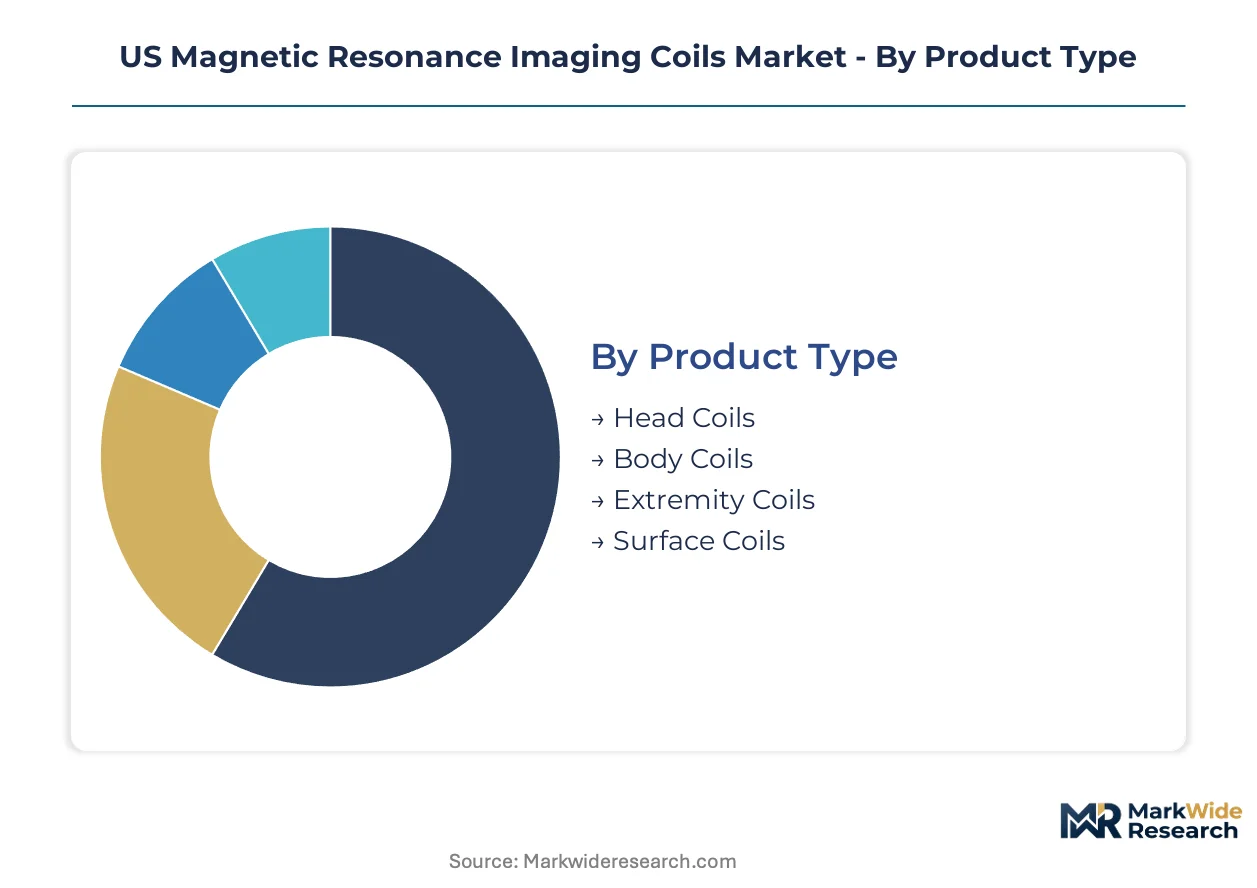
Coil segmentation in the US market determines procurement priorities across consolidated health systems and independent imaging centers. Upgrade cycles and replacement timelines vary sharply by product architecture, end-user budget authority, and field strength requirements.
Product Type:
Replacement cycles accelerate for coils serving high-throughput anatomical protocols where signal fidelity directly impacts diagnostic reimbursement.
- Head Coils:Phased arrays with 32+ channel configurations dominate neurovascular imaging at academic medical centers. Texas and California health systems prioritize these arrays for stroke protocol standardization across consolidated networks.
- Surface Coils:Lightweight, flexible copper assemblies enable point-of-care musculoskeletal diagnostics. Orthopedic specialist chains in Florida and ambulatory surgery centers drive procurement of disposable-compatible designs for same-day imaging workflows.
- Body Coils:Integrated torso arrays serve abdominal and pelvic protocols at hospital-based imaging departments.
- Extremity Coils:Dedicated knee, shoulder, and wrist configurations target sports medicine practices and urgent care networks.
Head coils sit at the top of the volume ranking, with surface coils climbing the fastest.
End User:
Procurement authority concentrates at health system supply chain offices rather than individual radiology departments, reshaping vendor engagement models.
- Hospitals:Centralized capital committees at multi-hospital networks in Texas, California, and Florida negotiate high-channel-count coil sets across twenty-plus imaging sites. FDA 510(k) clearance efficiency influences vendor selection for standardized deployments.
- Diagnostic Centers:Same-day imaging protocols expand coil inventories at outpatient facilities. These centers prioritize flexible, multi-purpose arrays that reduce hardware swap frequency across diverse anatomical indications.
- Outpatient Clinics:Budget constraints favor surface coil configurations for point-of-care musculoskeletal diagnostics.
- Research Institutes:Specialized high-field arrays support clinical trial imaging and protocol development.
Hospitals command the largest installed base, while diagnostic centers are expanding most quickly.
Technology:
Field strength selection dictates coil element density, thermal management requirements, and electromagnetic compatibility validation scope.
- High-Field:3T systems with specialized cryogenic or advanced copper phased arrays optimize signal-to-noise ratio for neurovascular and oncologic protocols. Academic medical centers and large hospital networks drive adoption where diagnostic specificity supports reimbursement.
- Closed MRI:Cylindrical bore configurations with integrated coil systems dominate hospital-based imaging for cardiac and abdominal applications.
- Low-Field:Open or permanent magnet designs accommodate claustrophobic patients and interventional guidance.
- Open MRI:Vertical field configurations with specialized surface coils serve bariatric and pediatric populations.
High-field technology leads deployment volume, with closed MRI systems gaining share fastest in consolidated health networks.
Application:
Clinical indication determines coil channel count requirements, protocol complexity, and reimbursement positioning under CMS fee schedules.
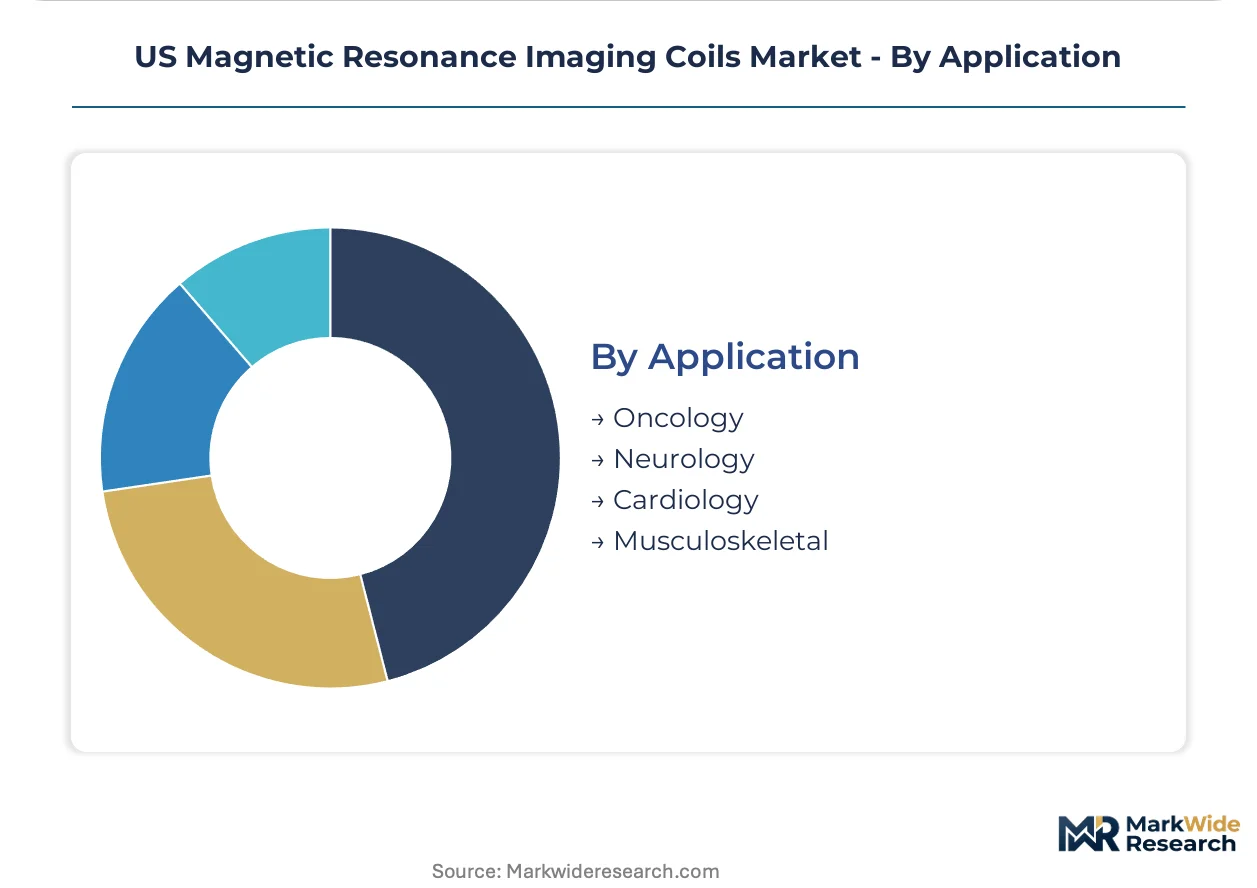
- Neurology:Brain and spine imaging demands 32-64 channel neurovascular arrays with specialized element geometries. Texas stroke centers and California academic networks drive premium coil procurement for rapid sequence protocols.
- Musculoskeletal:Extremity and joint imaging favors flexible surface coils at orthopedic specialist chains. Florida sports medicine practices and ambulatory surgery centers prioritize lightweight, rapid-positioning designs.
- Oncology:Multi-parametric body imaging requires integrated torso arrays for lesion characterization and treatment monitoring.
- Cardiology:Cardiac gating and perfusion imaging demand specialized phased arrays with high temporal resolution.
Neurology commands the highest coil channel density, with musculoskeletal applications showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in MRI coil manufacturing favor jurisdictions with streamlined electromagnetic compatibility validation and shorter FDA 510(k) clearance pathways. Production and procurement decisions concentrate where health system consolidation creates centralized purchasing power and certificate-of-need barriers are absent.
Texas
Health system consolidation across Dallas-Fort Worth and Houston drives centralized procurement of high-channel-count coil sets for stroke protocol standardization. Texas operates without certificate-of-need restrictions, enabling rapid MRI scanner capacity expansion and associated coil demand. The Texas Medical Center anchors neurovascular array adoption at academic medical centers.
California
Academic medical centers in Los Angeles and San Francisco Bay Area prioritize 32-64 channel neurovascular arrays for rapid sequence protocols. California's Office of Statewide Health Planning and Development enforces facility licensing requirements that shape MRI suite siting decisions. Silicon Valley technology partnerships accelerate AI-reconstruction-integrated coil validation.
Florida
Orthopedic specialist chains and ambulatory surgery centers in Miami and Tampa drive surface coil procurement for same-day musculoskeletal imaging workflows. Florida's certificate-of-need program expired in 2019, removing capacity constraints on outpatient imaging expansion. The I-4 corridor concentrates sports medicine practice clusters demanding lightweight extremity coils.
New York
Certificate-of-need regulations through the New York State Department of Health directly constrain MRI scanner capacity expansion in New York City metropolitan markets. Academic medical centers in Manhattan and Buffalo maintain premium coil inventories despite procurement friction. Upstate health systems face fewer regulatory barriers, enabling modest coil upgrade cycles.
Illinois
Health Facilities and Services Review Board certificate-of-need requirements limit MRI capacity growth in Chicago metropolitan statistical areas. Northwestern Medicine and University of Chicago academic networks maintain existing high-channel array deployments. Downstate Illinois markets experience relatively unencumbered diagnostic center expansion supporting surface coil demand.
US Magnetic Resonance Imaging Coils Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system OEMs commanding aftermarket attach rates and independent coil houses capturing ambulatory point-of-care volume. The vendor structure consolidates around three tiers: integrated imaging system manufacturers with captive coil portfolios, dedicated RF coil specialists with multi-platform compatibility, and regional fabricators serving replacement part demand. Strategic archetypes include high-channel array innovators, flexible surface coil commoditizers, and legacy system compatibility specialists. Competitive moves concentrate on centralized purchasing agreement capture and AI-reconstruction software integration.
Within the integrated-system tier, GE Healthcare leverages its installed base of MRI systems to sustain aftermarket coil attach rates across hospital networks. Siemens Healthineers anchors its position through R&D intensity in high-channel neurovascular arrays. Canon Medical Systems competes on manufacturing scale for extremity coils serving orthopedic specialist chains.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Esaote S.p.A. |
| MR Instruments, Inc. (MRIi) |
| Rapid MR International, LLC. |
| ScanMed, LLC. |
| Noras MRI Products GmbH |
| Others |
Pricing and Supply Chain Analysis
RF engineer concentration in Boston and Minneapolis-St. Paul metropolitan clusters creates labor-cost differentials that widen pricing-tier spreads between premium neurovascular arrays and commoditized surface coil alternatives.
Pricing Analysis
Distributor margin compression at group purchasing organizations shapes three-tier pricing structure across premium, standard, and economy levels. FDA 510(k) clearance tier and channel bundling with MRI system contracts differentiate price bands. Pricing pressure stems from consolidated health system procurement committees demanding volume discounts for multi-site standardization. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers prioritize channel density over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese superconducting wire suppliers and German precision machining houses for phased array substrates. Copper coil fabrication concentrates in Mexico, China, and domestic US Midwest facilities. Cryogenic component sourcing draws from South Korean and Japanese specialty manufacturers. Tariff exposure on Chinese-sourced copper assemblies elevates landed costs for economy-tier arrays. Distribution runs through OEM captive channels and independent RF coil specialists serving replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on AI-reconstruction software licensing attach rates that transform hardware coils into recurring revenue platforms.
For Market Incumbents: Anchor defensive positioning through backward integration into superconducting wire supply and exclusive GPO contract lock-ups at Texas and Florida health systems. GE Healthcare and Siemens Healthineers must preempt AI-reconstruction startup encroachment by accelerating FDA software-as-medical-device validation pipelines. Channel control through installed-base MRI system tethering remains the critical lever against independent coil house disruption. For New Entrants and Emerging Players: FDA 510(k) pathway efficiency for multi-channel arrays opens a window for point-of-care surface coil penetration at Florida orthopedic chains and Texas ambulatory networks. Target disposable-compatible musculoskeletal designs where incumbent OEMs maintain weak service infrastructure. White-space sits in AI-reconstruction algorithm licensing to second-tier MRI manufacturers seeking competitive parity. For Investors and Strategic Acquirers: Valuations sit cheapest among independent RF coil houses with multi-platform compatibility and FDA 510(k) cleared portfolios. Long-term viability favors acquisition targets with validated AI-reconstruction pipelines and established GPO relationships. Monitor CMS diagnostic imaging fee schedule adjustments for multi-parametric sequences as the inflection signal for coil upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Submission | Accelerates AI-reconstruction coil clearance timelines ahead of competitor validation cycles. |
| Hospital System Partnership | Locks multi-site standardization contracts across Texas and California consolidated networks. |
| Backward Integration into Superconducting Wire | Reduces Japanese supplier dependency and compresses neurovascular array unit economics. |
| Software Companion Development | Transforms hardware coils into recurring revenue platforms via algorithm licensing fees. |
| Reimbursement Strategy | Positions multi-parametric sequence coils for CMS fee schedule premium capture. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers and hospital purchasing committees, GPO contract database analysis, FDA 510(k) filing review — were reconciled against secondary validation from CMS Medicare reimbursement data and SEC equipment manufacturer disclosures. Bottom-up coil shipment estimates triangulated with top-down MRI system install-base modeling. Stakeholder roles included radiology department heads, supply chain officers at consolidated health systems, and RF coil engineering specialists.
Data-stream reconciliation across product type, end user, field strength technology, and clinical application segmentation anchored volume and value outputs. CAGRs derived from replacement cycle analysis and capacity expansion trajectories through the projection horizon. Forecast inputs incorporated certificate-of-need regulatory constraints in New York and Illinois, and AI-reconstruction software adoption curves at academic medical centers.
Revisions become necessary when FDA software-as-medical-device guidance shifts validation requirements, or when CMS diagnostic imaging fee schedule adjustments alter coil upgrade incentives. Forecasts reflect assumptions about health system consolidation velocity and electromagnetic compatibility testing timeline stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
Global Dental Radiology and Dental Imaging Devices Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Global Micro-Ultrasound Systems Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
AI in Diagnostic Imaging Market