
 Intra Abdominal Infection Market | 2026-2036
Intra Abdominal Infection Market Size, Share, and Industry Trends Forecast 2026-2036
Intra Abdominal Infection Market Foresight
The pricing and clinical positioning of intra abdominal infection therapies is rebalancing between premium branded agents and commodity generic antibiotics. Pfizer Inc leverages its broad-spectrum portfolio to sustain hospital formulary dominance across North American and European markets. Merck & Co anchors its competitive stance through differentiated carbapenem offerings that command specialist preference in complicated intra-abdominal cases.
Intra abdominal infection refers to polymicrobial inflammatory processes involving organs within the peritoneal cavity, typically requiring empiric broad-spectrum antibiotic coverage targeting gram-negative aerobes, gram-positive cocci, and anaerobes, with source control via percutaneous drainage or laparotomy serving as the cornerstone of definitive management. The antibiotics segment occupies the largest revenue pool due to mandatory perioperative prophylaxis and prolonged therapeutic courses in complicated cases, while the intravenous delivery mode dominates acute inpatient settings where bioavailability and rapid attainment of therapeutic concentrations govern protocol design. Hospitals command the primary end-user channel, though emergency care settings are capturing incremental volume as triage protocols accelerate time-to-antibiotic administration.
The FDA antimicrobial stewardship requirements and EMA's evolving guidance on novel antibacterial development pathways are tightening clinical evidence standards for new entrants while reinforcing demand for agents with documented resistance profiles. JIS standards and PMDA reviews in Japan further shape product registration requirements across Asia-Pacific markets. Stakeholders must monitor how regulatory pressure on resistance mitigation reshapes R&D prioritization and reimbursement thresholds for next-generation combination therapies.
Market Dynamics
FDA antimicrobial stewardship mandates are compressing prescriber autonomy and forcing hospital formularies toward narrow-spectrum agents with documented resistance profiles, fundamentally altering how pharmaceutical portfolios compete for perioperative protocol placement.
Growth Catalysts
- Post-operative infection control infrastructure:Hospital surgical departments in the United States, Germany, and Japan are deepening investment in combination antimicrobial protocols that reduce readmission penalties and improve patient throughput metrics.
- EMA antibacterial development pathways:Evolving guidance on novel agent evidence standards is channeling R&D investment toward agents with differentiated resistance profiles, accelerating specialist preference formation in complicated cases.
- Carbapenem differentiation:Specialist antibiotic stewardship committees are elevating agents with anaerobic coverage and gram-negative stability into first-line empiric protocols for perforated viscus and post-surgical sepsis.
Market Restraints
- Generic antibiotic commoditization:Patent-expired broad-spectrum agents from Indian and Chinese API manufacturers are collapsing price floors for uncomplicated intra-abdominal infection therapy, compressing branded agent margins.
- Carbapenem resistance surveillance:CDC and ECDC tracking of carbapenem-resistant Enterobacteriaceae is triggering formulary restrictions that limit high-value agent deployment to documented resistant infections.
- Source control prioritization:Surgical societies are emphasizing percutaneous drainage and laparotomy over prolonged antibiotic courses, shortening therapeutic duration and reducing total drug consumption per episode.
Strategic Opportunities
- Japanese PMDA fast-track pathways:Japan's priority review system for antibacterial agents addressing unmet resistance needs offers accelerated market entry for novel combination therapies targeting MDR gram-negative pathogens.
- Emergency department triage protocols:Time-to-antibiotic quality metrics are creating new channel access points for rapid-infusion intravenous formulations before inpatient admission decisions.
- β-lactam/β-lactamase inhibitor convergence:Fixed-dose combinations pairing established cephalosporin backbones with novel inhibitor moieties are opening spectrum expansion opportunities without de novo development timelines.
Industry Challenges
- Antimicrobial stewardship compliance:Hospital pharmacy and therapeutics committees require extensive local susceptibility data and pharmacoeconomic modeling before protocol inclusion, extending sales cycles.
- IV-to-oral step-down standardization:Medicare and commercial payor pressure for early discharge is forcing manufacturers to demonstrate bioequivalent oral formulations that maintain therapeutic coverage through transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intra Abdominal Infection Market |
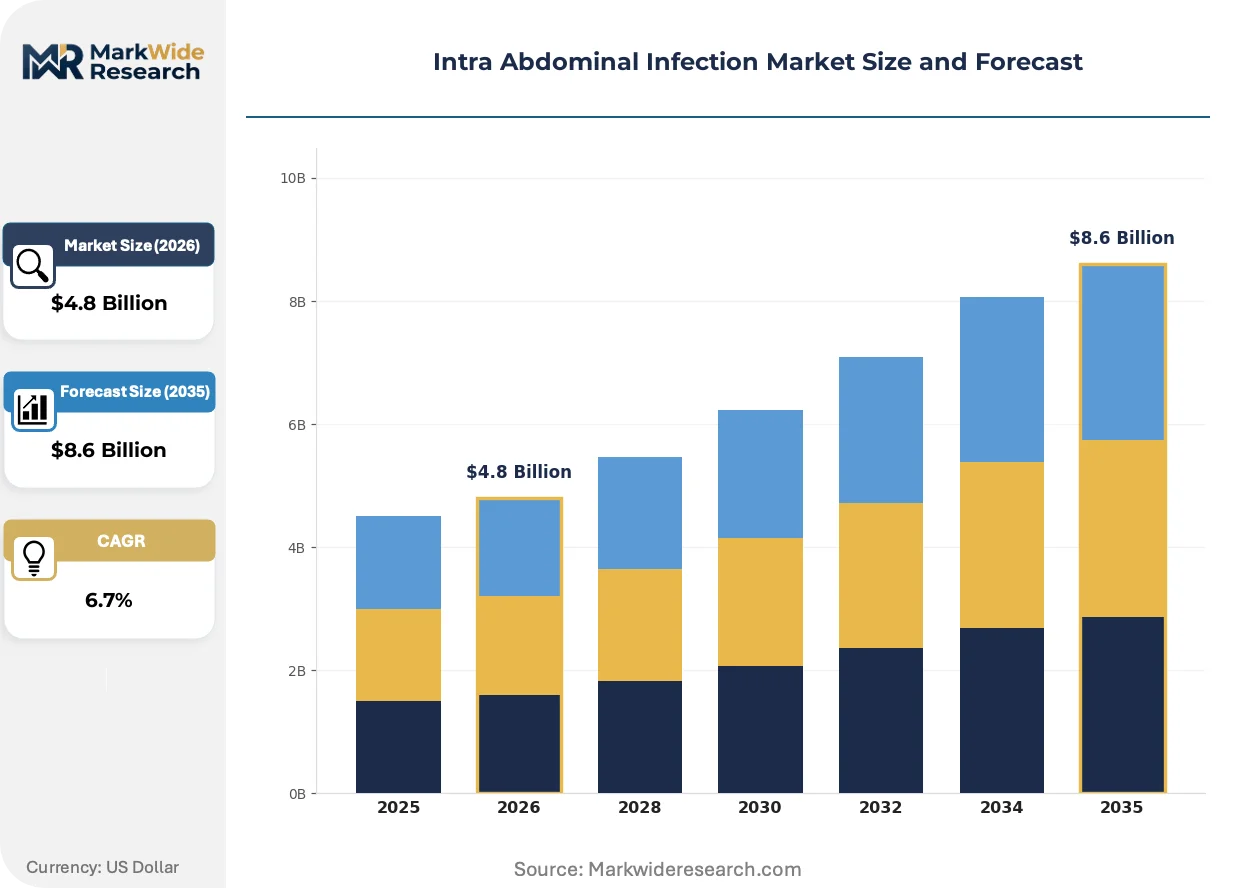
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Surgical Treatments, Supportive Care Delivery Mode: Intravenous, Oral, Topical, Intra-abdominal End User: Hospitals, Outpatient Clinics, Emergency Care, Homecare Therapy Area: Gastroenterology, General Surgery, Infectious Diseases, Trauma |
| Companies Covered | Pfizer Inc, Merck & Co, Johnson & Johnson, AbbVie Inc, AstraZeneca, Novartis AG, Bayer AG, Boehringer Ingelheim International GmbH, Gilead Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intra Abdominal Infection Market Shifts & Advancements
Pharmaceutical development is pivoting toward precision spectrum targeting and rapid diagnostic integration, with regulatory frameworks simultaneously tightening evidence requirements and creating accelerated pathways for resistance-addressing agents.
Rapid pathogen identification platforms are integrating into emergency department and surgical ward workflows to narrow empiric coverage within 24-48 hours. Hospital antibiotic stewardship teams are adopting these systems to satisfy Joint Commission core measures and reduce unnecessary broad-spectrum exposure. This diagnostic integration is compressing the window for branded agent differentiation and rewarding portfolios with documented rapid-bactericidal activity against priority pathogens.
The FDA's 2023 guidance on limited population antibacterial drugs is narrowing pivotal trial designs to specific resistance phenotypes, reducing development costs but constraining commercial addressable markets. EMA parallel scientific advice pathways are enabling simultaneous US-EU dossier preparation for agents targeting carbapenem-resistant Acinetobacter baumannii and Pseudomonas aeruginosa. These regulatory frameworks are segmenting development strategies between blockbuster-scale indications and targeted resistance-addressing agents with premium pricing but restricted deployment.
Hospital purchasing cooperatives are consolidating antibiotic procurement through sole-source contracts tied to resistance surveillance data sharing and formulary compliance guarantees. Large academic medical centers in the United States are negotiating multi-year agreements that bundle novel agent access with mandatory stewardship reporting, displacing traditional multi-source generic purchasing for perioperative prophylaxis. This channel concentration is most visible in California, Texas, and New York health systems where integrated delivery networks command sufficient volume to extract performance-based contracting terms.
Intra Abdominal Infection Market Segmentation
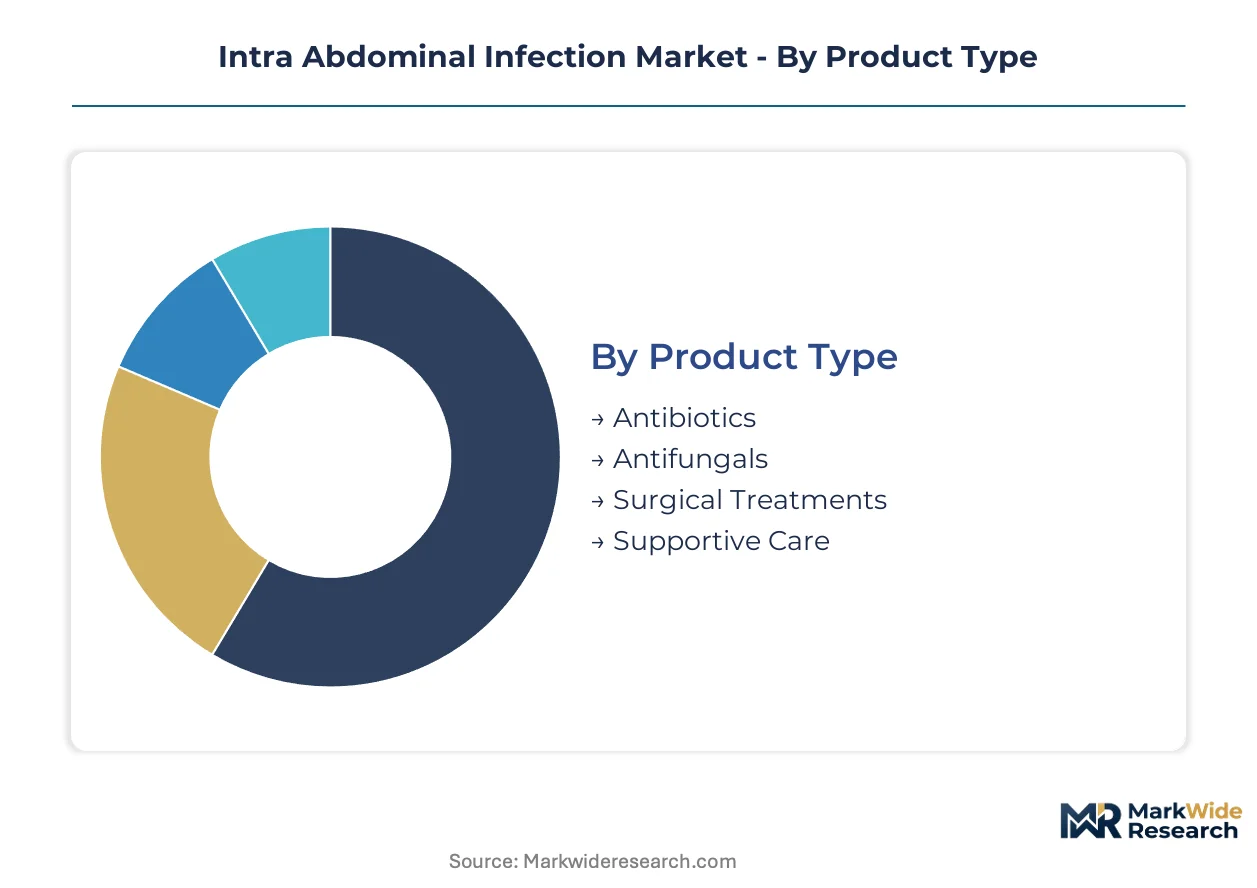
Segmentation in intra-abdominal infection therapeutics reveals how supply-side capabilities align with clinical workflow requirements. Hospital procurement patterns and regulatory compliance frameworks create distinct competitive arenas across product categories, delivery modalities, and care settings.
Product Type:
Supply concentration in active pharmaceutical ingredient manufacturing shapes competitive dynamics across therapeutic categories, with fermentation capacity and sterile formulation infrastructure determining market access.
- Antibiotics:Broad-spectrum agents targeting gram-negative aerobes, gram-positive cocci, and anaerobes dominate empiric protocols. Demand concentrates in United States and German hospital systems where perioperative prophylaxis mandates drive volume. FDA antimicrobial stewardship requirements are compressing formulary placement timelines for novel agents.
- Surgical Treatments:Percutaneous drainage catheters, laparotomy instruments, and source control devices constitute the procedural backbone of definitive management. Japanese and United States academic medical centers are deepening investment in minimally invasive technologies that reduce length-of-stay metrics. EMA guidance on surgical site infection prevention is reshaping device selection criteria.
- Antifungals:Azole and echinocandin formulations address Candida peritonitis in immunocompromised and post-surgical populations. Specialist infectious disease consultation governs utilization.
- Supportive Care:Fluid resuscitation, nutritional support, and organ function monitoring complete therapeutic protocols. Critical care infrastructure investment determines adoption intensity.
Antibiotics absorb the bulk of installed capacity; surgical treatments are expanding most quickly.
Delivery Mode:
Cost tier differentiation separates acute inpatient administration from transition-of-care and outpatient maintenance protocols, with bioavailability requirements governing modality selection.
- Intravenous:Rapid attainment of therapeutic concentrations in acute sepsis and perioperative settings. United States emergency departments and surgical wards command primary volume as time-to-antibiotic quality metrics harden. Medicare readmission penalties are extending IV therapy duration in observation units.
- Oral:Step-down formulations enabling early discharge and reducing central line-associated complications. German and Japanese reimbursement frameworks are accelerating bioequivalence requirements for oral alternatives. Commercial payor pressure for length-of-stay reduction is expanding addressable markets.
- Topical:Surgical site irrigation and wound dressing applications in open abdomen management. Protocol standardization varies across hospital systems.
- Intra-abdominal:Direct instillation into peritoneal cavity for localized infection control. Specialist surgical preference determines utilization patterns.
Intravenous delivery commands the largest revenue pool; oral formulations are climbing the fastest as step-down protocols standardize.
End User:
Customer type fragmentation creates distinct access pathways, with integrated delivery networks consolidating procurement leverage while emergency settings demand rapid availability.
- Hospitals:Inpatient surgical departments and intensive care units anchor therapeutic consumption. United States, German, and Japanese hospital systems are deepening investment in combination antimicrobial protocols. Antibiotic stewardship committee oversight is extending sales cycles for novel agent placement.
- Emergency Care:Triage protocols accelerating time-to-antibiotic administration are creating new channel entry points. United States emergency departments are adopting rapid-infusion IV formulations before admission decisions. Quality metrics are reshaping formulary requirements.
- Outpatient Clinics:Post-discharge monitoring and uncomplicated infection management. Reimbursement frameworks determine service intensity.
- Homecare:Outpatient parenteral antimicrobial therapy for prolonged courses. Infusion service infrastructure governs geographic penetration.
Hospitals absorb the bulk of installed capacity; emergency care is gaining share fastest as pre-admission protocols expand.
Therapy Area:
Maturity gradients across clinical specialties create differentiated evidence requirements, with established surgical protocols contrasting against evolving infectious disease stewardship approaches.
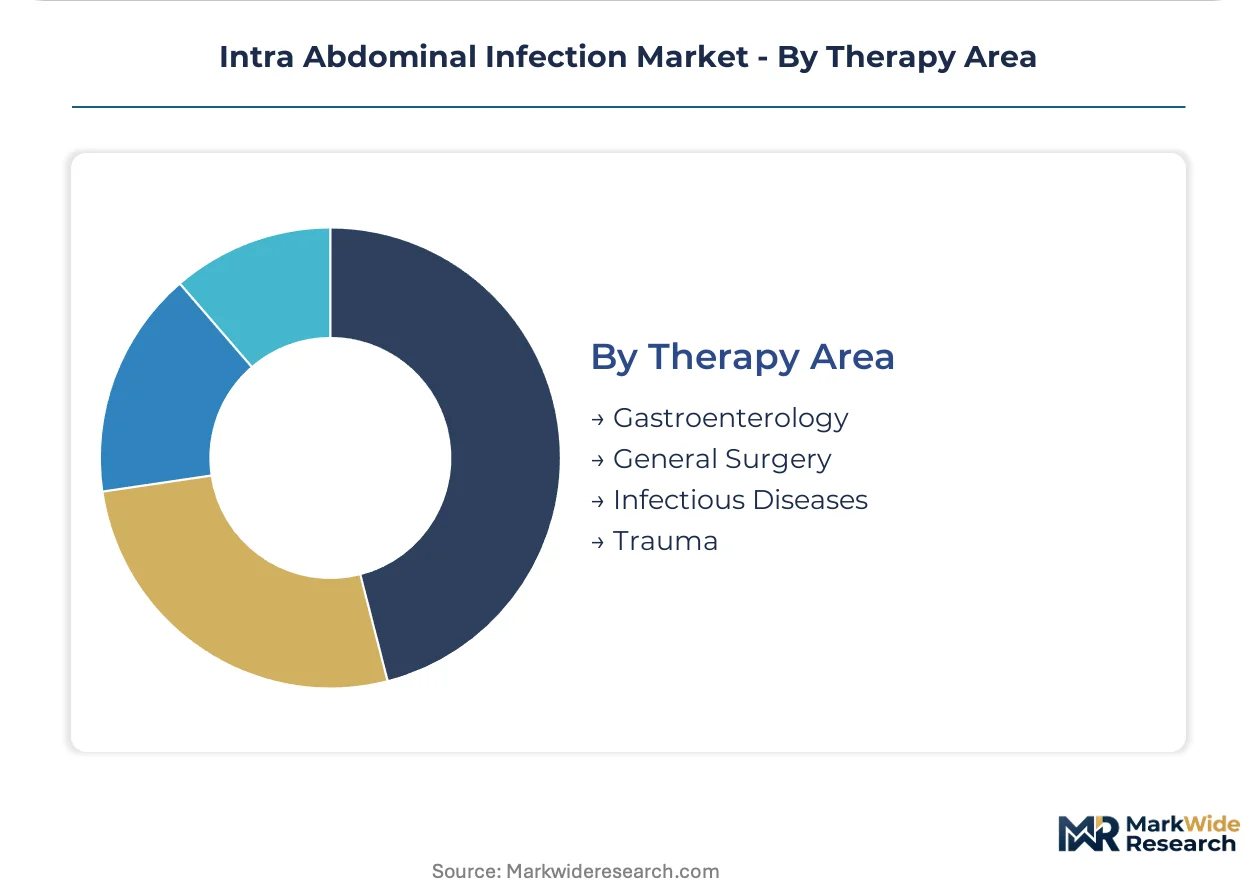
- General Surgery:Perforated viscus, appendicitis, and post-operative peritonitis management. United States and German surgical societies are emphasizing source control prioritization over prolonged antibiotic courses. Procedure volume and readmission penalty exposure drive therapeutic intensity.
- Infectious Diseases:Resistance surveillance, therapeutic drug monitoring, and stewardship protocol design. Japanese PMDA fast-track pathways are accelerating novel agent access for carbapenem-resistant pathogens. Specialist consultation requirements limit addressable markets.
- Gastroenterology:Spontaneous bacterial peritonitis and hepatobiliary infection management. Cirrhosis prevalence and transplant center density determine geographic concentration.
- Trauma:Penetrating abdominal injury and damage control surgery protocols. Level I trauma center distribution governs market access.
General surgery commands the largest therapeutic volume; infectious diseases is expanding most quickly as resistance surveillance intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors North American demand for advanced intra-abdominal infection therapeutics, with Massachusetts General Hospital and Brigham and Women's Hospital driving protocol innovation. German university hospitals in Munich and Heidelberg shape European carbapenem utilization patterns. Tokyo's metropolitan hospital networks set Asia-Pacific benchmarks for antimicrobial stewardship compliance.
United States
Hospital surgical departments in California and Texas are expanding combination antimicrobial protocols to reduce readmission penalties. FDA antimicrobial stewardship mandates are compressing formulary placement timelines for novel agents. The Cleveland Clinic and Mayo Clinic anchor midwestern resistance surveillance networks that influence national prescribing patterns.
Germany
University hospitals in Bavaria and Baden-Württemberg are deepening investment in post-operative infection control infrastructure. EMA guidance on antibacterial development pathways is channeling R&D toward agents with documented resistance profiles. The Berlin-Brandenburg health region is consolidating antibiotic procurement through sole-source contracts tied to stewardship reporting.
Japan
Metropolitan Tokyo and Osaka hospital systems are capturing incremental volume through emergency department triage protocols. PMDA fast-track pathways for antibacterial agents addressing unmet resistance needs are accelerating market entry for novel combination therapies. Nagoya's academic medical centers are pioneering rapid pathogen identification platform integration.
United Kingdom
NHS England's integrated care systems in London and the Midlands are standardizing IV-to-oral step-down protocols to reduce length-of-stay. NICE technology appraisals are tightening reimbursement thresholds for next-generation combination therapies. Manchester's specialist infectious disease units are elevating carbapenem differentiation in complicated case management.
India
Corporate hospital chains in Maharashtra and Karnataka are expanding perioperative prophylaxis capacity as surgical volume rises. CDSCO regulatory frameworks are tightening clinical evidence standards for new antibiotic entrants. Hyderabad's pharmaceutical manufacturing corridor is supplying API for generic broad-spectrum agents.
Intra Abdominal Infection Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the intra-abdominal infection therapeutics space, with integrated pharmaceutical conglomerates maintaining hospital formulary dominance through broad-spectrum portfolios while specialty antibiotic developers pursue accelerated regulatory pathways for resistance-addressing agents. The market structure concentrates around three strategic archetypes: diversified conglomerates with hospital contracting leverage, mid-cap specialists in carbapenem and β-lactamase inhibitor combinations, and emerging developers targeting carbapenem-resistant gram-negative pathogens. Dominant competitive moves include multi-year sole-source procurement agreements with integrated delivery networks and parallel FDA-EMA scientific advice submissions for limited-population antibacterial designations.
Within the diversified conglomerate tier, Pfizer Inc and Merck & Co occupy positions defined by hospital formulary dominance and carbapenem differentiation respectively. Pfizer's broad-spectrum portfolio exemplifies the contracting leverage archetype across North American and European markets. Merck & Co represents specialist preference formation in complicated intra-abdominal cases through differentiated anaerobic coverage. Among research-intensive developers, AstraZeneca sits within the emerging resistance-addressing segment pursuing accelerated regulatory pathways.
| Leading Market Players |
|---|
| Pfizer Inc |
| Merck & Co |
| Johnson & Johnson |
| AbbVie Inc |
| AstraZeneca |
| Novartis AG |
| Bayer AG |
| Boehringer Ingelheim International GmbH |
| Gilead Sciences |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up generic antibiotic manufacturers in India and China have compressed pricing floors while consolidating fermentation capacity, creating a bifurcated market where hospital purchasing cooperatives extract volume discounts from commoditized broad-spectrum agents while premium branded carbapenems retain formulary slots through documented resistance profiles and stewardship compliance guarantees.
Pricing Analysis
Outcome-based contracting tied to readmission reduction anchors hospital procurement negotiations for intra-abdominal infection therapeutics. Pricing stratifies across premium carbapenems with anaerobic coverage, standard cephalosporin-β-lactamase inhibitor combinations, and economy-tier generic penicillin derivatives. Cost compression in the economy tier stems from Indian API oversupply and Chinese sterile formulation capacity additions. Emergency departments demonstrate lowest price sensitivity due to time-to-antibiotic quality metrics, while outpatient clinics face highest sensitivity from Medicare step-down reimbursement pressure.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled antibiotics remain underdeveloped, creating environmental liability exposure and regulatory scrutiny around pharmaceutical waste disposal. Active pharmaceutical ingredient manufacturing concentrates in India, China, and Italy, with sterile formulation capacity clustering in the United States, Germany, and Japan. Fermentation-based β-lactam production draws from corn-derived dextrose and soy-based nitrogen sources, with energy costs representing a volatile input. Single-source vulnerability in carbapenem intermediate supply from select Chinese manufacturers poses concentration risk. Distribution runs through hospital purchasing cooperatives and specialty pharmaceutical wholesalers to acute care settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA antimicrobial stewardship mandates have erected a cost-of-compliance moat that rewards manufacturers with documented resistance surveillance data and penalizes generic-only portfolios lacking stewardship integration capabilities.
For Market Incumbents: Deploy formulary lock-in mechanisms through multi-year sole-source agreements with integrated delivery networks that bundle novel agent access with mandatory resistance data sharing. Consolidate position by acquiring rapid diagnostic platform capabilities to compress the empiric-to-targeted therapy window. Carbapenem-resistant Enterobacteriaceae surveillance expansion and Indian generic API price erosion represent primary threats requiring defensive R&D repositioning toward β-lactamase inhibitor combinations. For New Entrants and Emerging Players: Launch via emergency department triage protocol partnerships that bypass traditional pharmacy and therapeutics committee gatekeeping through pre-admission quality metric alignment. Target Japanese PMDA fast-track pathways for carbapenem-resistant gram-negative pathogens as the most penetrable regulatory entry point. White-space opportunities concentrate in oral step-down formulations with bioequivalence documentation for early discharge protocols and in combination therapies addressing MDR Acinetobacter baumannii. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap developers with Phase III-ready limited-population antibacterial designations in the United States and European Union markets. Long-term viability hinges on portfolio diversification beyond single-agent dependence toward diagnostic-antibiotic bundled offerings. Monitor FDA breakthrough therapy designation grants for carbapenem-resistant pathogens as the signal for inflection in specialist preference formation and premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Stewardship Data Partnership | Hospital systems in California and Texas mandate resistance surveillance sharing for formulary inclusion. |
| β-Lactamase Inhibitor Pipeline Expansion | Novel inhibitor moieties paired with established cephalosporin backbones accelerate development timelines. |
| Rapid Diagnostic Integration | Emergency departments in Boston and Tokyo adopt pathogen identification platforms to narrow empiric coverage. |
| Japanese PMDA Fast-Track Utilization | Priority review for MDR gram-negative agents compresses regulatory timelines in Asia-Pacific's highest-value market. |
| Oral Step-Down Formulation Development | German and Japanese reimbursement frameworks accelerate bioequivalence requirements for early discharge protocols. |
Research Methodology
Independent corroboration across hospital formulary directors, antibiotic stewardship committee chairs, infectious disease specialists, and emergency department operations managers underwrites the qualitative findings. Primary interviews with procurement officers at integrated delivery networks in the United States, Germany, and Japan were cross-referenced against secondary validation from FDA antimicrobial stewardship guidance documents, EMA parallel scientific advice pathways, PMDA priority review designations, and hospital purchasing cooperative contract disclosures. Bottom-up therapeutic volume estimates and top-down market sizing triangulate across the analysis window.
Rate-of-change decomposition separates volume effects from pricing and mix shifts across product type, delivery mode, end user, and therapy area segmentation dimensions. CAGRs derive from modeled progression of hospital surgical volume, resistance surveillance intensity, and regulatory pathway utilization. Forecast inputs incorporate antimicrobial stewardship mandate compliance timelines, generic API capacity expansion in India and China, and rapid diagnostic platform adoption curves in academic medical centers.
Regulatory guidance revisions, carbapenem resistance surveillance threshold adjustments, and hospital purchasing cooperative consolidation are the dominant revision risks. Forecasts reflect documented assumptions around stewardship committee influence trajectories and step-down protocol standardization rates. Practitioners should monitor FDA limited-population antibacterial drug designation grants and EMA parallel scientific advice uptake for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
North America Hand Sanitizer Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Infection Prevention Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Sterility Indicators Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Point of Care Infection Control Market
Infection Control
Sterilization Tunnel Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Hand Hygiene Products Market
Infection Control
Intra-Abdominal Infection Treatment Market