
 Pancreatic Elastase Testing Market | 2026-2036
Pancreatic Elastase Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pancreatic Elastase Testing Market Analytics
Multi-source procurement of enzyme-linked immunosorbent assay reagents is hardening among European reference laboratories seeking supply security. ScheBo Biotech AG leverages its proprietary monoclonal antibody production to dominate fecal elastase immunoassay supply in Germany. Immundiagnostik AG anchors its position through backward integration into recombinant antigen manufacturing. DiaSorin S.p.A. competes by extending its chemiluminescence platform into gastrointestinal diagnostics.
Pancreatic elastase testing quantifies fecal concentrations of human pancreatic elastase-1, a stable proteolytic enzyme resistant to intestinal degradation, to assess exocrine pancreatic function in patients with malabsorption syndromes. The assay typically employs sandwich immunoassay formats with monoclonal antibodies targeting specific epitopes, requiring stool sample collection and laboratory processing within defined temperature parameters. Immunoassays and enzyme-linked immunosorbent assays occupy the mature core of the product landscape, while lateral flow tests and rapid test kits represent the fastest-growing format as point-of-care testing expands. Among delivery modes, centralized testing still captures the largest volume, though point-of-care testing is displacing legacy workflows in outpatient clinics seeking same-day diagnostic turnaround.
The FDA's in vitro diagnostic regulations and the EU's In Vitro Diagnostic Regulation (IVDR) impose divergent conformity assessment burdens on manufacturers seeking dual-market access. ISO 13485 quality management standards and CLIA laboratory certification requirements in the United States further stratify competitive entry across production and service tiers. Stakeholders must monitor how IVDR transition timelines and FDA breakthrough device designations for novel biomarker panels reshape investment priorities in gastrointestinal diagnostics.
Market Dynamics
The transition from centralized laboratory processing to point-of-care testing is restructuring competitive advantage around assay portability and rapid turnaround rather than throughput scale alone.
Growth Catalysts
- IVDR Transition Deadlines:The EU's In Vitro Diagnostic Regulation implementation is accelerating manufacturer consolidation and quality system upgrades, elevating compliant suppliers above fragmented competitors.
- Gastroenterology Clinic Expansion:Outpatient digestive health networks in Germany are embedding fecal elastase protocols into malabsorption workups, creating dedicated test volume corridors.
- Monoclonal Antibody Stabilization:Advances in lyophilized reagent formulations are extending cold-chain tolerance, enabling distribution into resource-variable settings previously excluded from immunoassay access.
Market Restraints
- Recombinant Antigen Input Concentration:European supply chains depend on a narrow base of recombinant protein manufacturers, exposing assay producers to batch-to-batch variability and allocation constraints.
- FDA Classification Uncertainty:Ongoing refinement of enzyme-based assay rules is prolonging 510(k) review timelines and deterring mid-cap entrants from dual-market registration investments.
- Stool Sample Logistics:Temperature-controlled collection and transport requirements impose infrastructure costs that limit test penetration in ambulatory settings lacking cold storage.
Strategic Opportunities
- Lateral Flow Format Expansion:Rapid visual-read devices are capturing outpatient clinic demand for same-day diagnostic closure, compressing the traditional send-out workflow.
- India Diagnostic Infrastructure:Central government health scheme expansion into non-communicable disease screening is opening procurement channels for cost-optimized immunoassay platforms.
- Chemiluminescence Convergence:Integration of pancreatic function markers onto automated high-throughput analyzers is consolidating gastrointestinal testing into existing laboratory instrument footprints.
Industry Challenges
- ISO 13485 Implementation Burden:Small and mid-sized assay developers face capital intensity in building compliant quality management systems for IVDR and FDA parallel submissions.
- Antibody Specificity Validation:Cross-reactivity elimination for human pancreatic elastase-1 requires extended epitope mapping cycles that compress development timelines and inflate R&D burn rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancreatic Elastase Testing Market |
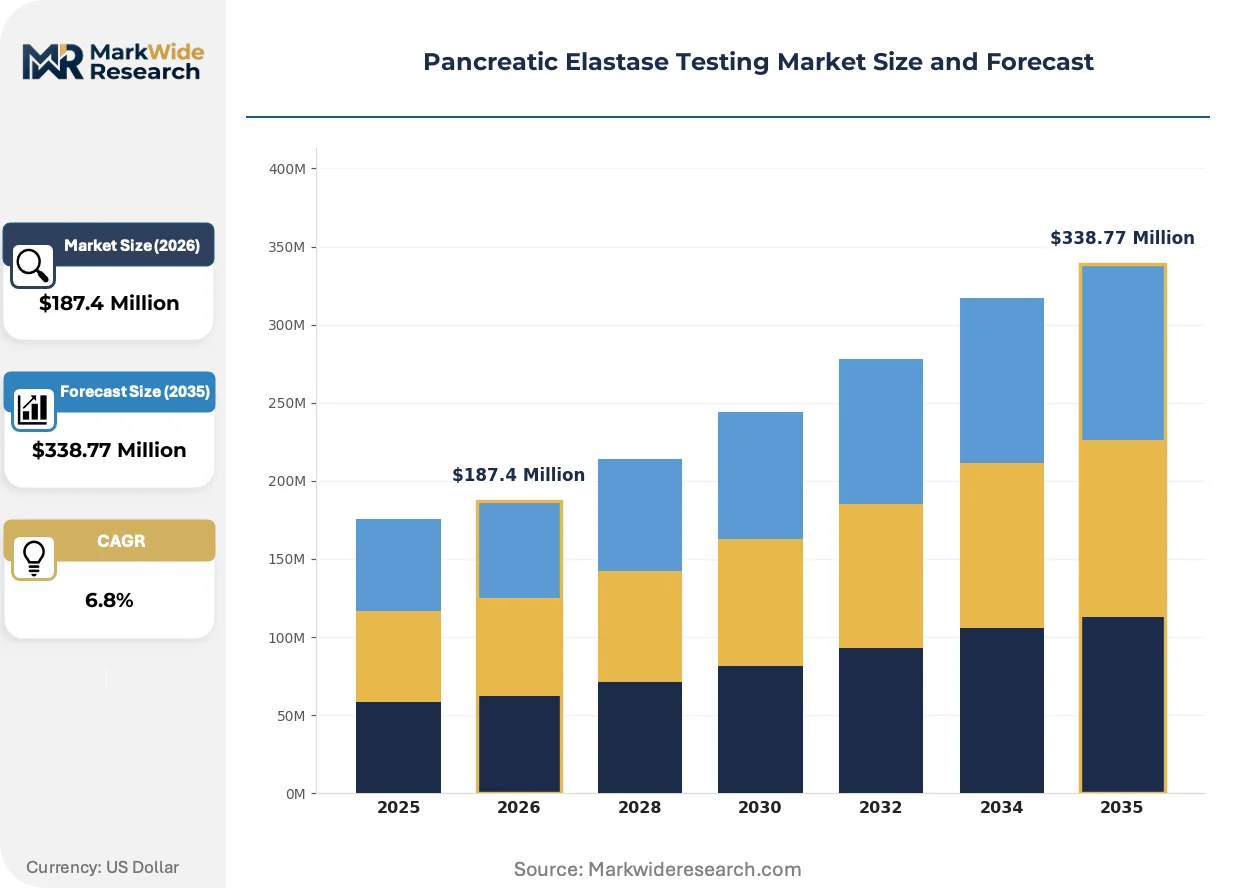
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Enzyme-Linked Immunosorbent Assays, Lateral Flow Tests, Rapid Test Kits End User: Hospitals, Diagnostic Laboratories, Outpatient Clinics, Research Institutes Technology: Enzymatic Assays, Chemical Assays, Chromatography, Spectrometry Delivery Mode: Point-of-Care Testing, Centralized Testing, Home Testing, Automated Testing |
| Companies Covered | ScheBo Biotech AG, Immundiagnostik AG, DiaSorin S.p.A., Verisana Laboratories, R-Biopharm AG, Bioserv Diagnostics GmbH, Thermo Fisher Scientific Inc., Abbott Laboratories, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancreatic Elastase Testing Market Evolving Landscape
Assay miniaturization and platform integration are converging to collapse the boundary between laboratory-grade precision and point-of-care convenience.
Microfluidic cartridge systems for fecal elastase quantification are modularizing the traditional ELISA workflow into disposable, instrument-agnostic consumables. Regional hospital networks in Spain are piloting these devices in satellite clinics, eliminating sample transport delays. This architecture is modularizing the value chain by separating assay chemistry from capital equipment ownership, enabling reagent rental models.
The EU IVDR's risk-classification elevation for immunological diagnostic devices is imposing notified body involvement timelines that stretch conformity assessments to 18-24 months. Manufacturers with legacy CE-marked products face portfolio triage decisions on renewal investments. German reference laboratories are responding by consolidating supplier relationships toward IVDR-designated entities with established quality system documentation.
Integrated service contracts bundling assay supply with analyzer placement and maintenance are displacing transactional reagent purchasing in United States health system procurement. Hospital laboratory directors in Texas and Florida are negotiating multi-year agreements that lock in volume commitments for preferred platform access. This shift is most pronounced in IDN-affiliated sites seeking to standardize gastrointestinal diagnostics across distributed care networks.
Pancreatic Elastase Testing Market Segmentation
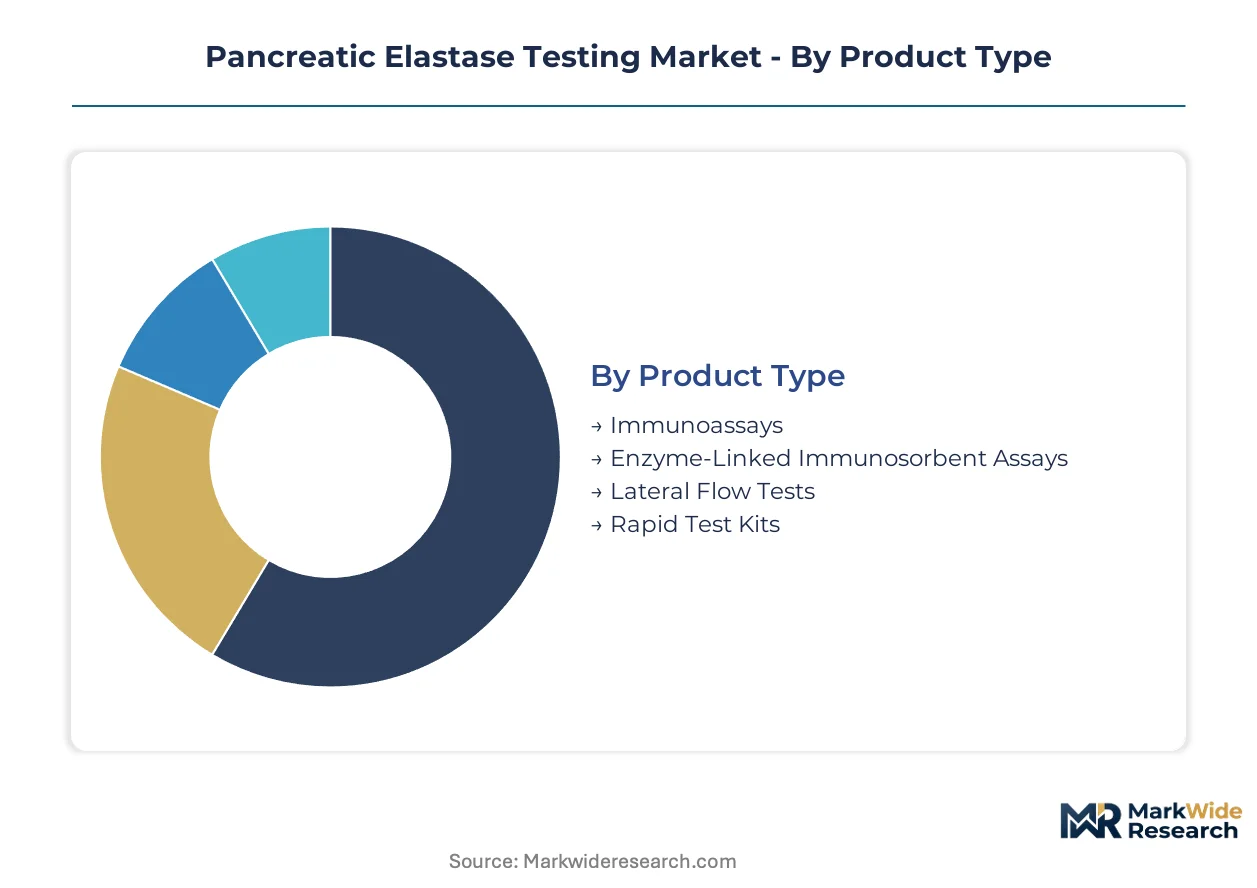
Pancreatic elastase testing segments diverge sharply in capital requirements and regulatory burden. Assay format choices determine cold-chain infrastructure needs, while delivery mode selection shapes whether manufacturers compete on throughput scale or portability.
Product Type:
Capital intensity peaks with immunoassay platforms requiring monoclonal antibody production facilities and lyophilization capacity.
- Immunoassays:Sandwich-format assays with monoclonal antibody pairs targeting human pancreatic elastase-1 epitopes demand bioreactor investment and extended validation cycles. German gastroenterology clinics in Bavaria and North Rhine-Westphalia now specify these for malabsorption workups, driven by IVDR compliance timelines that favor established antibody suppliers.
- Enzyme-Linked Immunosorbent Assays:Microplate-based quantification with enzyme-conjugated detection antibodies remains the reference standard for laboratory networks. Texas hospital systems bundle ELISA reagent contracts with analyzer placement, locking in multi-year volume commitments for preferred platform access.
- Lateral Flow Tests:Visual-read cassettes for qualitative screening compress workflow to fifteen minutes.
- Rapid Test Kits:Single-use devices with dried reagent matrices eliminate cold storage for ambulatory deployment.
Immunoassays absorb the bulk of installed capacity; lateral flow tests are expanding most quickly.
End User:
Customer type stratifies procurement sophistication from centralized laboratory tenders to clinic-level spot purchasing.
- Hospitals:Acute care networks in Florida and California negotiate integrated service contracts bundling pancreatic function testing with broader gastrointestinal panels. IDN-affiliated sites seek standardization across distributed laboratories, consolidating vendor relationships toward full-line suppliers.
- Diagnostic Laboratories:Reference labs in Germany and Spain run high-throughput ELISA batches on automated platforms. Multi-source procurement of enzyme-linked reagents is hardening as European facilities seek supply security against recombinant antigen allocation constraints.
- Outpatient Clinics:Gastroenterology practices in Berlin and Munich embed fecal elastase into malabsorption protocols.
- Research Institutes:Academic medical centers validate novel biomarker correlations against established elastase quantification.
Diagnostic laboratories command the highest reagent volumes; outpatient clinics are climbing the fastest as point-of-care adoption accelerates.
Technology:
Technical approach determines sensitivity specifications and cross-reactivity elimination burden.
- Enzymatic Assays:Proteolytic activity measurement leveraging elastase substrate specificity requires precise pH control and temperature stabilization. Batch-to-batch variability in recombinant protein inputs exposes European manufacturers to conformity assessment delays under IVDR risk-classification rules.
- Chemical Assays:Colorimetric detection of reaction products suits resource-variable settings with limited instrumentation.
- Chromatography:Separation-based quantification with mass spectrometry confirmation anchors research applications.
- Spectrometry:Absorbance or fluorescence endpoint detection integrates with automated analyzer footprints.
Enzymatic assays dominate clinical validation; spectrometry is gaining share fastest through platform consolidation.
Delivery Mode:
Distribution architecture determines whether manufacturers capture value through capital equipment or consumable repeat purchases.
- Point-of-Care Testing:Lateral flow and microfluidic cartridge formats enable same-day diagnostic closure in satellite clinics. Regional hospital networks in Spain pilot these devices to eliminate sample transport delays, modularizing the value chain through reagent rental models.
- Centralized Testing:Laboratory-based ELISA and chemiluminescence workflows sustain throughput economies for high-volume screening. Hospital laboratory directors in Texas negotiate multi-year agreements locking in preferred platform access across distributed care networks.
- Home Testing:Patient-collected stool samples with mail-in processing expand access beyond clinical infrastructure.
- Automated Testing:Random-access analyzer integration consolidates gastrointestinal diagnostics into existing instrument footprints.
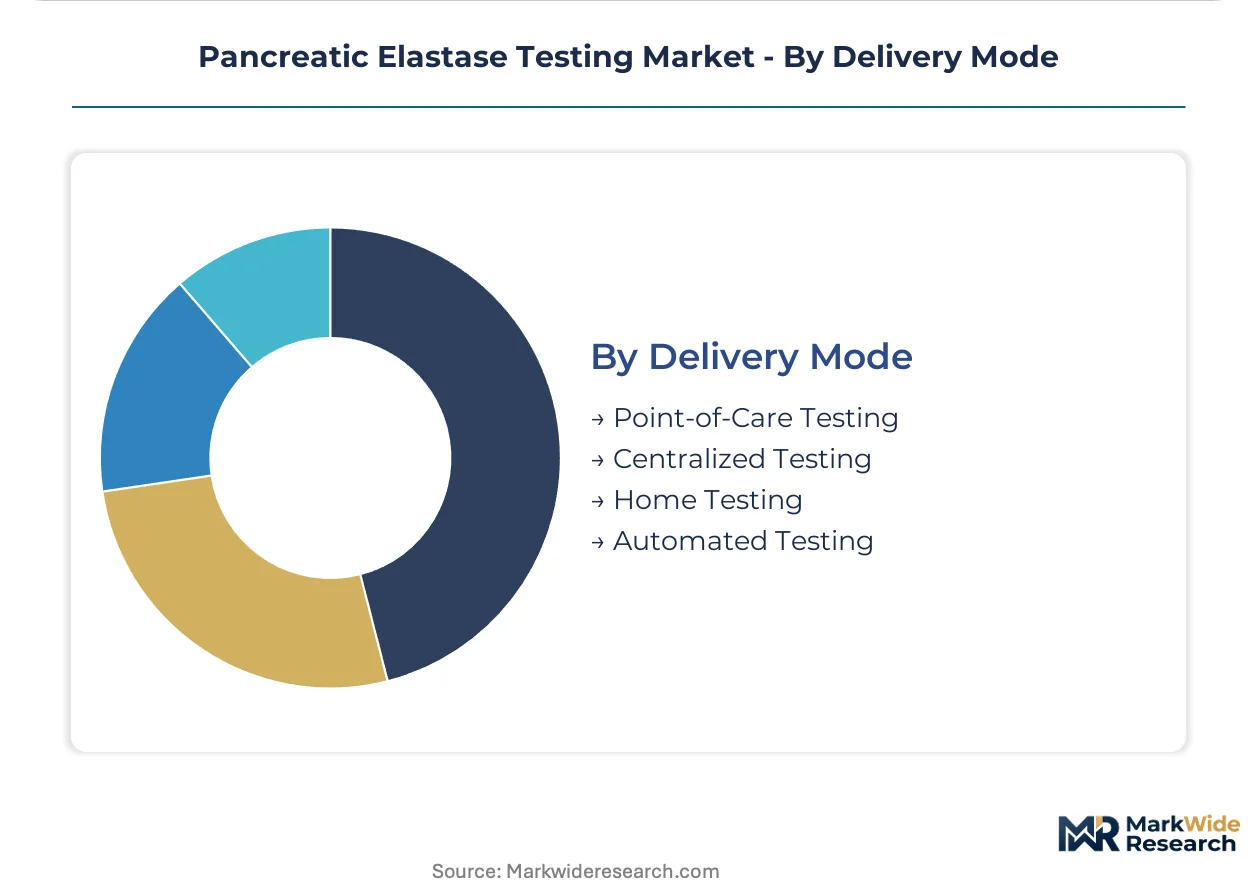
Centralized testing retains the largest volume base; point-of-care testing is displacing legacy workflows most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pancreatic elastase testing concentrates in aging populations with chronic pancreatitis prevalence, with procurement patterns diverging sharply between centralized laboratory networks and outpatient clinic expansion corridors.
United States
Hospital laboratory directors in Texas and Florida negotiate multi-year integrated service contracts bundling gastrointestinal diagnostics across distributed care networks. FDA refinement of enzyme-based assay classification rules prolongs 510(k) review timelines, deterring mid-cap entrants from dual-market registration. IDN-affiliated sites in the Southeast standardize testing protocols through preferred platform access agreements.
Germany
Gastroenterology clinics in Bavaria and North Rhine-Westphalia embed fecal elastase quantification into malabsorption workups, creating dedicated test volume corridors. EU IVDR implementation accelerates manufacturer consolidation toward compliant suppliers with established quality system documentation. Reference laboratories in Berlin consolidate supplier relationships toward IVDR-designated entities.
Spain
Regional hospital networks pilot microfluidic cartridge systems in satellite clinics to eliminate sample transport delays. The national pharmaceutical regulator enforces IVDR conformity assessment timelines stretching to 18-24 months for immunological diagnostic devices. Catalonia and Madrid anchor pilot programs modularizing value chains through reagent rental models.
India
Central government health scheme expansion into non-communicable disease screening opens procurement channels for cost-optimized immunoassay platforms. The national pharmaceutical regulator evaluates diagnostic platform registrations under revised medical device rules. Maharashtra and Karnataka host emerging distribution infrastructure for point-of-care testing deployment.
Japan
Aging demographics sustain high screening volumes for exocrine pancreatic insufficiency in metropolitan hospital networks. The national pharmaceutical regulator maintains stringent quality management requirements for in vitro diagnostic imports. The Kanto region around Tokyo concentrates automated analyzer integration for gastrointestinal testing consolidation.
Pancreatic Elastase Testing Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to bridge capability gaps in monoclonal antibody production and regulatory compliance infrastructure. The vendor base stratifies across three tiers: integrated diagnostics conglomerates with multi-platform portfolios, specialized immunoassay developers with captive antibody supply, and emerging point-of-care format innovators. Two archetypes define competitive positioning: antibody-integrated specialists leveraging proprietary bioreactor capacity, and platform-extenders converging gastrointestinal markers onto existing analyzer footprints. Geographic expansion into India's diagnostic infrastructure and technology licensing for lateral flow format migration represent the dominant competitive moves.
Among Germany-based specialists, ScheBo Biotech AG and Immundiagnostik AG occupy positions within the antibody-integrated tier, exemplifying backward integration into recombinant antigen manufacturing. DiaSorin S.p.A. represents the platform-extender archetype, anchoring competitive positioning through chemiluminescence convergence. These three entities illustrate how regulatory compliance capacity and production integration separate viable competitors from fragmented assay developers facing ISO 13485 implementation burdens.
| Leading Market Players |
|---|
| ScheBo Biotech AG |
| Immundiagnostik AG |
| DiaSorin S.p.A. |
| Verisana Laboratories |
| R-Biopharm AG |
| Bioserv Diagnostics GmbH |
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| Bio-Rad Laboratories, Inc. |
| Others |
Value Network & Pricing Analysis
Lyophilized monoclonal antibody reagent costs cascade from German bioreactor facilities through IVDR-certified manufacturers into tiered pricing structures that separate hospital laboratory contracts from ambulatory clinic spot purchases.
Pricing Analysis
High-volume reference laboratories in Germany and Texas capture per-test economies through multi-year integrated service contracts, while outpatient clinics absorb premium per-unit pricing for rapid-turnaround lateral flow formats. Price differentiation separates CE-marked IVDR-compliant assays from legacy products facing renewal investment decisions, with certification tier and cold-chain infrastructure requirements as primary drivers. Pricing pressure stems from recombinant antigen batch-to-batch variability exposing European manufacturers to allocation-driven cost compression. Research institutes exhibit lowest price sensitivity; ambulatory gastroenterology clinics in resource-variable settings demonstrate highest.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised stool samples drive specialized courier networks in Spain and Germany to maintain cold-chain verification protocols, with failed collections triggering replacement kit dispatch and reprocessing delays. Supply concentrates in Germany, Italy, and the United States for monoclonal antibody production, with recombinant antigen inputs drawing from Swiss and Austrian protein manufacturers. Single-source vulnerability in recombinant protein supply exposes assay producers to batch allocation constraints. Distribution runs through diagnostic distributor networks consolidating toward IVDR-designated entities with established quality documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pancreatic elastase testing market functions as a cost-of-compliance story where EU IVDR risk-classification elevation for immunological diagnostic devices constructs a barrier-to-entry moat favoring manufacturers with pre-existing quality system documentation and notified body relationships.
For Market Incumbents: Deepen backward integration into recombinant antigen manufacturing to insulate against European protein supplier allocation constraints. Lock in multi-year integrated service contracts with Texas and Florida hospital systems before IVDR transition deadlines consolidate procurement toward compliant suppliers. Priority levers include lyophilization capacity expansion and IVDR-designated entity certification maintenance. For New Entrants and Emerging Players: Begin with lateral flow format development targeting India's central government health scheme procurement channels for non-communicable disease screening. The most penetrable white space sits in cost-optimized immunoassay platforms for Maharashtra and Karnataka distribution infrastructure. Go-to-market angle emphasizes ambient-temperature stability eliminating cold-chain infrastructure requirements. For Investors and Strategic Acquirers: FDA breakthrough device designation for novel biomarker panels is the leading indicator that gastrointestinal diagnostics consolidation is accelerating toward platform-extenders with chemiluminescence convergence capabilities. Long-term viability over the coming decade rests on acquiring antibody-integrated specialists with captive bioreactor capacity and established IVDR technical documentation. Signal to watch: notified body backlog clearing rates for immunological device conformity assessments.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | Notified body engagement timelines stretching to 18-24 months favor early movers with complete quality system records. |
| Microfluidic Cartridge Platform Development | Regional hospital networks in Spain pilot disposable formats eliminating sample transport delays through reagent rental models. |
| Recombinant Antigen Manufacturing Scale-Up | Backward integration into protein production insulates assay manufacturers from European supplier allocation constraints. |
| India Distribution Infrastructure Partnership | Maharashtra and Karnataka emerging as anchor points for central government health scheme procurement channel access. |
| Chemiluminescence Analyzer Integration | Automated high-throughput platform consolidation captures gastrointestinal testing volume within existing laboratory instrument footprints. |
Research Methodology
Independent corroboration across hospital laboratory directors, gastroenterology clinic procurement officers, diagnostic distributor account managers, and regulatory affairs specialists at IVD manufacturers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU IVDR notified body guidance documents, hospital GPO contract databases, and German reference laboratory tender records. Bottom-up test volume modeling triangulates against top-down market sizing across assay format and delivery mode segments.
Comparable-period anchoring to historical ELISA and immunoassay adoption curves informs the projection horizon, with segmentation across product type, end user, technology, and delivery mode dimensions. CAGRs derive from test volume trajectory analysis incorporating aging demographic screening intensity and chronic pancreatitis prevalence patterns. Industry-specific inputs include IVDR transition timeline assumptions and point-of-care testing penetration rates in outpatient clinic settings.
Underlying measurement precision varies by segment; centralized laboratory ELISA volumes carry tighter precision than emerging point-of-care lateral flow adoption curves. Forecasts reflect assumptions regarding regulatory clearance timelines and recombinant protein supply stability. Material deviation in IVDR notified body capacity or FDA enzyme-based assay classification refinement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Influenza a/B Combo Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
South Korea GMP Testing Service Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Urine Sediment Testing Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Diagnostic Shipper Market
Testing Services
Trichomonas Rapid Testing Market