
 Urology Devices Market | 2026-2036
Urology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Urology Devices Market Intelligence
The substitution of traditional latex and silicone with advanced antimicrobial and hydrophilic polymers in catheter manufacturing is recalibrating product economics and patient outcomes. Boston Scientific Corporation leverages its R&D in materials science to develop next-generation devices. Coloplast A/S specializes in chronic care products, focusing on user comfort and infection prevention. Medtronic plc competes across multiple urology segments by integrating its device portfolio with surgical robotics.
Urology devices encompass a range of instruments and implants designed for diagnosing, treating, and managing disorders of the urinary tract and male reproductive system. These devices, from cystoscopes with high-definition imaging sensors to lithotripters using focused shockwaves, are engineered for procedural efficacy and patient safety. Catheters and surgical instruments form the high-volume base of the product landscape, while lithotripters represent a capital-intensive subsegment. Applications in kidney stone treatment and benign prostatic hyperplasia continue to drive procedural volumes, particularly within specialized urology clinics and ambulatory surgical centers.
Market access is governed by stringent regulatory approvals from bodies like the US FDA and the European Medicines Agency under the MDR framework. In China, the NMPA's requirements for clinical data and device classification create distinct entry barriers. Stakeholder success will depend on navigating these varied regulatory pathways while investing in technology that demonstrates clear clinical and economic value.
Market Dynamics
The convergence of advanced materials science with robotic-assisted surgical platforms is the central force shaping the urology devices market. This combination is enabling the development of more precise, minimally invasive instruments and implants that improve patient outcomes and procedural efficiency.
Growth Catalysts
- Advanced Polymer Adoption:The use of antimicrobial and hydrophilic polymers in catheters reduces infection rates and improves patient comfort, driving adoption in specialized urology clinics seeking superior clinical outcomes.
- Demographic Shifts in Developed Markets:Germany's aging population and high healthcare spending create sustained demand for devices treating age-related urological conditions like benign prostatic hyperplasia and incontinence.
- Shift to Ambulatory Surgical Centers:The migration of urological procedures from traditional hospitals to ambulatory surgical centers increases demand for cost-effective, single-use devices like flexible cystoscopes and stone retrieval baskets.
Market Restraints
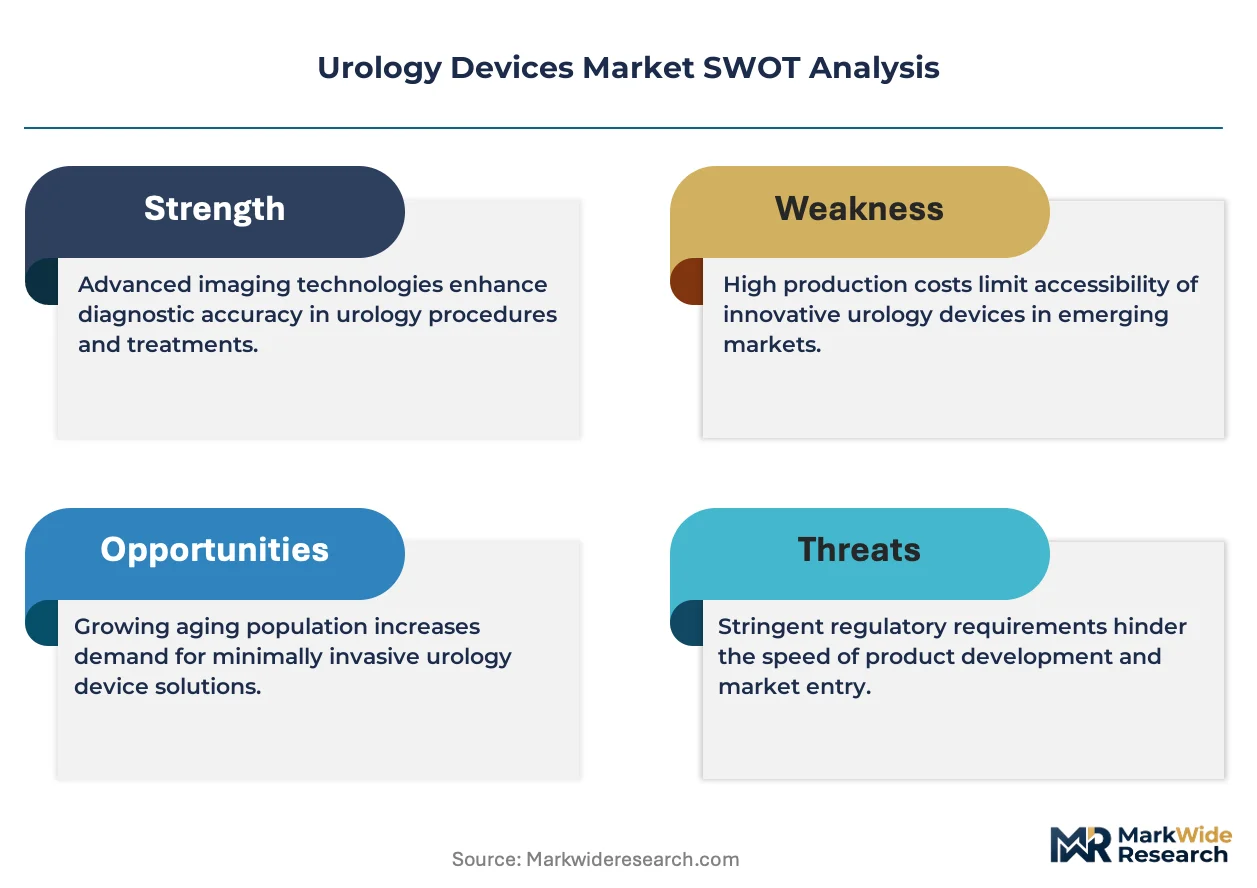
- Stringent Regulatory Hurdles:The European Union's Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance requirements, increasing time-to-market and compliance costs for manufacturers.
- High Capital Investment:The significant upfront cost of acquiring and maintaining capital-intensive systems like surgical robots and lithotripters restricts their adoption to large, well-funded hospitals and clinics.
- Reimbursement Pressure:Evolving reimbursement policies and pressure from payors to demonstrate cost-effectiveness can limit the adoption of premium-priced technologies, particularly in public healthcare systems.
Strategic Opportunities
- Expansion in Underserved Geographies:Markets like Brazil present significant growth opportunities as healthcare infrastructure improves and access to advanced urological care expands beyond major urban centers.
- Integration of Artificial Intelligence:Embedding AI algorithms into diagnostic imaging systems like cystoscopes and ultrasound machines offers the potential for automated lesion detection and improved diagnostic accuracy.
- Focus on Female Urology:Developing specialized devices and treatments for female-specific conditions such as pelvic organ prolapse and stress urinary incontinence represents a significant area for product innovation and market growth.
Industry Challenges
- Specialized Surgical Skill Gaps:The effective use of advanced robotic surgical systems for procedures like prostatectomies requires extensive training, creating a bottleneck based on the availability of qualified surgeons.
- Data Interoperability:Integrating smart urology devices and their data outputs with disparate hospital information systems and electronic health records (EHR) remains a significant technical and logistical challenge.
- Sterilization and Reprocessing Complexity:Reusable devices like endoscopes require complex and costly reprocessing procedures to prevent cross-contamination, posing operational challenges for healthcare facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urology Devices Market |
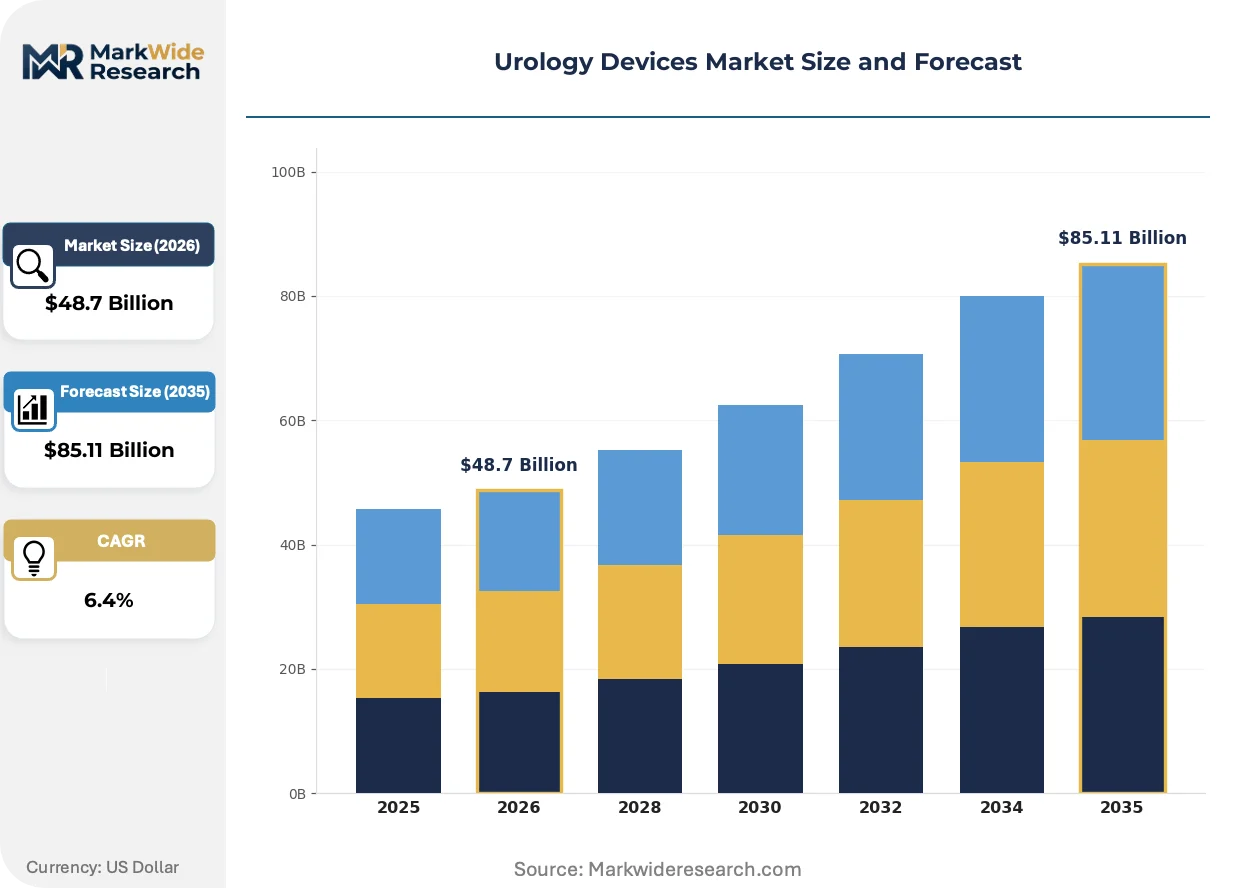
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cystoscopes, Uroflowmeters, Lithotripters, Catheters, Surgical Instruments End User: Specialized Urology Clinics, Diagnostic Centers, Ambulatory Surgical Centers, Research Laboratories Application: Urinary Incontinence, Kidney Stone Treatment, Prostate Disease Management, Bladder Cancer Diagnosis, Benign Prostatic Hyperplasia Technology: Laser Therapy, Robotic Surgery, Ultrasound Imaging, Electrophysiology Devices, Optical Coherence Tomography |
| Companies Covered | Boston Scientific Corporation, Fresenius Medical Care AG & Co. KGaA, Medtronic plc, Olympus Corporation, Coloplast A/S, Becton, Dickinson and Company, Cook Medical, Stryker, KARL STORZ SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urology Devices Market Strategic Shifts & Innovations
Miniaturization and embedded sensing technology are transforming single-function urological tools into intelligent diagnostic and therapeutic systems. This evolution is enabling a shift towards data-driven procedures that offer greater precision and real-time feedback within clinical settings.
Single-use digital endoscopes and sensor-integrated catheters provide high-resolution imaging and pressure data directly from the urinary tract. Specialized urology clinics and ambulatory surgical centers are primary adopters, valuing the elimination of reprocessing costs and the enhancement of diagnostic capabilities. The integration of sensing components into disposable formats is rewriting the value proposition for procedural diagnostics and post-operative care.
The US FDA's focus on the safety of reprocessed medical devices has accelerated the transition towards single-use urology instruments. This regulatory scrutiny compels manufacturers to innovate in disposable device design and performance to mitigate infection risks associated with reusable endoscopes. The flexible ureteroscope and cystoscope segments are most affected, with suppliers investing in cost-effective, high-performance disposable alternatives.
A distinct behavioral change is emerging in how hospitals acquire high-value equipment. Instead of direct capital purchases, healthcare systems in the US and parts of Europe are increasingly utilizing managed service agreements for technologies like surgical robotics. This model aligns expenditures with procedural volume, reducing financial risk and enabling facilities to access the latest technology without a prohibitive upfront investment.
Urology Devices Market Segmentation
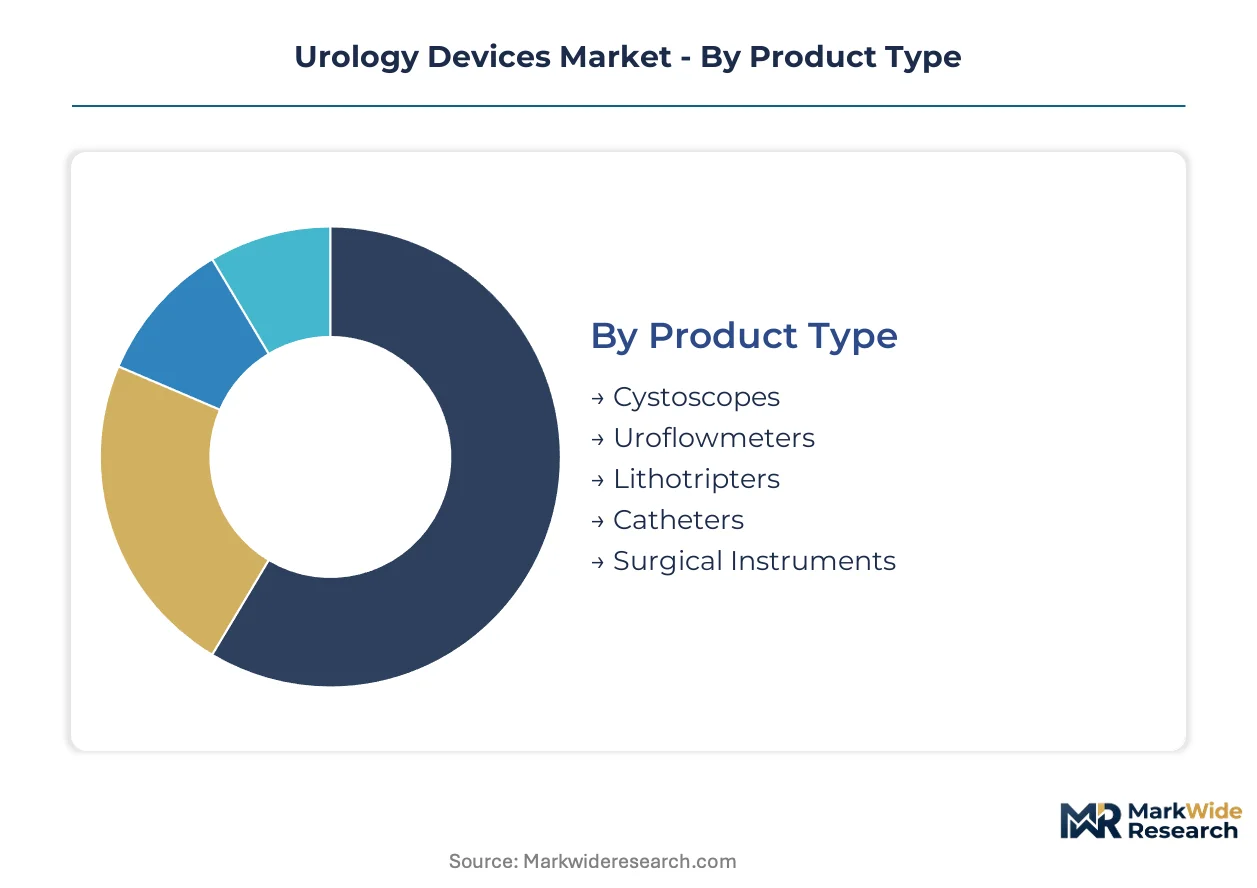
Understanding the Urology Devices Market through detailed segmentation reveals distinct value propositions and regulatory pathways across product types, end users, applications, and technologies. This granular analysis helps manufacturers and healthcare providers align product development and service delivery with specific market needs and compliance requirements.
Product Type:
Navigating the product landscape requires a clear understanding of device classification, with regulatory bodies like the US FDA and European Medicines Agency imposing varying levels of scrutiny. Devices with direct patient contact or long-term implantation face more stringent approval processes.
- Catheters:These flexible tubes drain urine from the bladder, manufactured with advanced antimicrobial and hydrophilic polymers to reduce infection risks and improve patient comfort. Demand for single-use, pre-lubricated catheters is high in both hospital and home care settings.
- Surgical Instruments:This segment includes a broad array of tools like forceps, scissors, and dilators, essential for both open and minimally invasive urological procedures. The shift towards single-use, sterile instruments is driven by infection control protocols and reprocessing complexities.
- Cystoscopes:These endoscopes visualize the bladder and urethra, with digital models offering high-definition imaging for improved diagnostic accuracy in specialized urology clinics.
- Lithotripters:Devices using focused shockwaves to break kidney stones into smaller fragments, representing a capital-intensive subsegment primarily found in larger hospitals.
- Uroflowmeters:Non-invasive devices measuring the rate of urine flow, primarily used for diagnosing lower urinary tract dysfunction in diagnostic centers.
Catheters sits at the top of the volume ranking, with Lithotripters climbing the fastest.
End User:
The operational cost structures and patient volume capabilities of different end-user facilities significantly influence device procurement decisions and technology adoption rates. Smaller centers prioritize cost-effective, easy-to-use solutions.
- Specialized Urology Clinics:These facilities offer focused diagnostic and therapeutic services, driving demand for advanced, often single-use, diagnostic tools like flexible cystoscopes. Their operational model supports patient-centric care for a range of urological conditions.
- Ambulatory Surgical Centers:ASCs perform outpatient urological procedures, favoring cost-effective, high-turnover devices that support efficient workflow and reduced patient recovery times. The shift of procedures to ASCs increases demand for single-use instruments.
- Diagnostic Centers:These centers focus on non-invasive and minimally invasive diagnostic procedures, utilizing devices such as uroflowmeters and advanced ultrasound imaging systems for patient assessment.
- Research Laboratories:These facilities utilize specialized urology devices for preclinical studies, device testing, and academic research, often requiring highly specific and customizable instrumentation.
Specialized Urology Clinics drive the highest procedural volumes, while Ambulatory Surgical Centers are gaining share through cost efficiencies.
Application:
The prevalence of specific urological conditions dictates the demand for specialized devices, with age-related disorders creating sustained market opportunities in developed economies. Treatment efficacy and patient outcomes remain central to device selection.
- Kidney Stone Treatment:This application involves devices like lithotripters, ureteroscopes, and stone retrieval baskets for managing nephrolithiasis. Procedural volumes are high, driven by dietary factors and demographic shifts.
- Benign Prostatic Hyperplasia:BPH management utilizes devices such as resectoscopes, lasers for prostatectomy, and implants for prostatic urethral lift. This application sees consistent demand due to the aging male population.
- Urinary Incontinence:Devices for incontinence include slings, artificial urinary sphincters, and neuromodulation systems. This segment addresses a widespread condition affecting both male and female populations.
- Prostate Disease Management:This broad application encompasses devices for diagnosing and treating various prostate conditions beyond BPH, including biopsy needles and imaging probes.
- Bladder Cancer Diagnosis:This application relies on cystoscopes with advanced imaging capabilities and biopsy instruments for early detection and surveillance of bladder malignancies.
Kidney Stone Treatment maintains the largest patient pool, with Benign Prostatic Hyperplasia applications showing consistent expansion.
Technology:
Innovation in technology platforms is transforming urological interventions, moving towards greater precision, reduced invasiveness, and improved patient recovery times. Integration of digital capabilities enhances diagnostic accuracy and therapeutic control.
- Robotic Surgery:Robotic-assisted platforms enhance precision and dexterity for complex urological procedures like prostatectomies and partial nephrectomies. This technology is driving the adoption of specialized instruments and imaging systems.
- Ultrasound Imaging:Ultrasound devices provide real-time visualization for diagnostic purposes, guiding biopsies, and monitoring treatment progress in various urological conditions. This non-invasive technology is widely adopted across clinical settings.
- Laser Therapy:Lasers are used for tissue ablation in procedures like BPH treatment and lithotripsy, offering precise energy delivery and reduced collateral damage. Holmium and thulium lasers are common in this segment.
- Electrophysiology Devices:These devices measure electrical activity in the bladder and pelvic floor, aiding in the diagnosis of neurogenic bladder and other functional disorders.
- Optical Coherence Tomography:OCT provides high-resolution, cross-sectional imaging of tissue microstructures, offering enhanced diagnostic capabilities within the urinary tract.
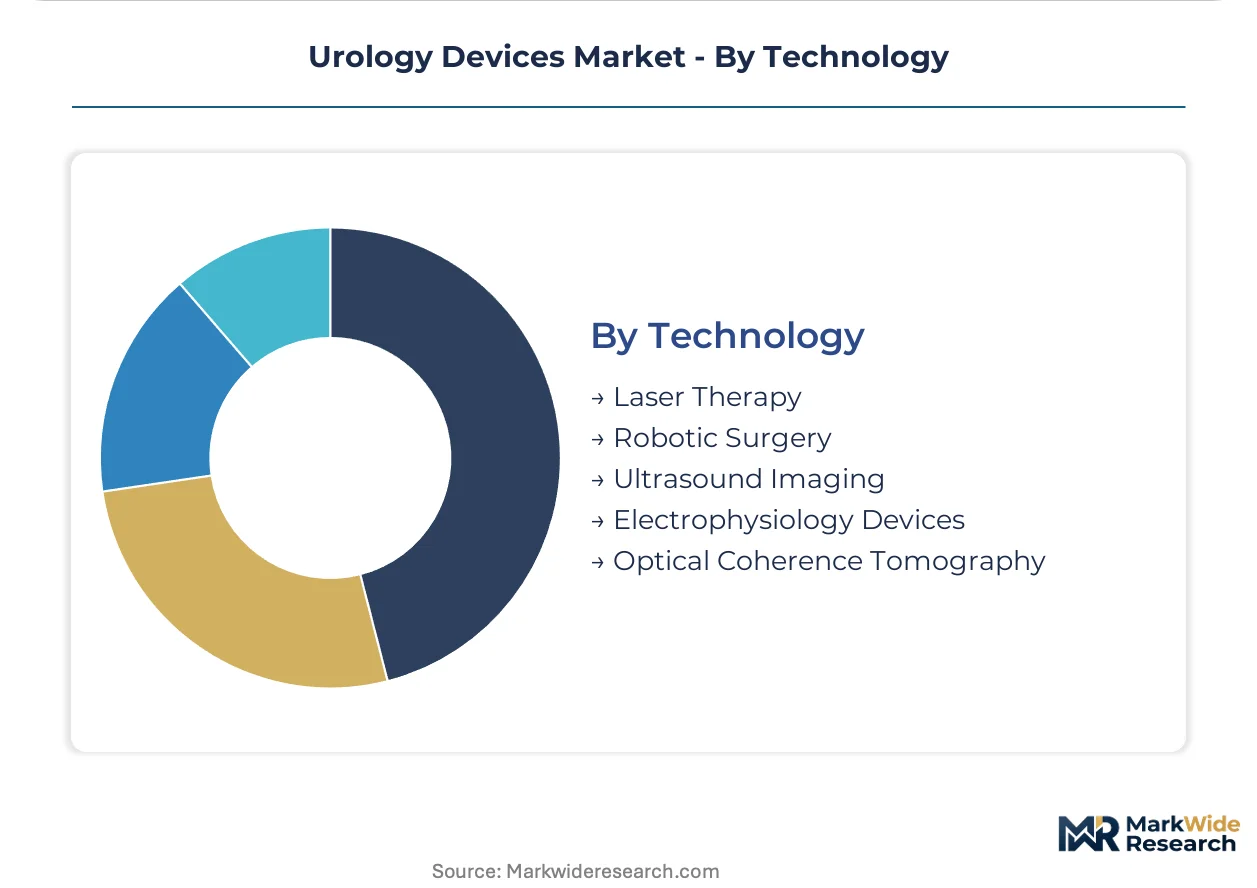
Robotic Surgery is revolutionizing complex procedures, while Ultrasound Imaging remains foundational for diagnostic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's medical technology cluster drives significant innovation in urology devices, influencing global market dynamics. High healthcare expenditure and a strong research ecosystem characterize the United States market. This region consistently adopts advanced diagnostic and therapeutic tools.
United States
The United States market sees robust demand for urology devices, driven by high prevalence of benign prostatic hyperplasia and kidney stones. US FDA approvals govern market access, emphasizing clinical efficacy and patient safety. California's medical device industry, around San Diego, focuses on developing next-generation robotic surgical systems.
Germany
Germany's aging population sustains demand for urological devices, particularly for benign prostatic hyperplasia and urinary incontinence treatments. The European Union's MDR framework imposes stringent requirements for device certification. Bavaria's strong medtech sector, with centers in Munich, focuses on precision manufacturing for surgical instruments.
China
China's expanding healthcare infrastructure fuels demand for urology devices, driven by a large patient pool and rising disposable incomes. The NMPA's stringent requirements for clinical data shape market entry strategies. The Yangtze River Delta region, especially Shanghai, emerges as a hub for domestic production and advanced device adoption.
Japan
Japan's rapidly aging demographic creates sustained demand for devices treating age-related urological conditions. The PMDA's rigorous approval processes ensure high standards for medical device safety and efficacy. Tokyo's medical device ecosystem focuses on miniaturization and high-precision components for endoscopes and robotic systems.
Brazil
Brazil presents significant growth opportunities as healthcare infrastructure improves and advanced urological care expands. ANVISA's regulatory pathways govern medical device imports and local manufacturing strategies. São Paulo's healthcare technology sector is a focal point for device distribution and the adoption of new surgical techniques.
Urology Devices Market Key Industry Players
Mergers and acquisitions dominate the current landscape, as companies seek to expand their product portfolios and technological capabilities. The market structure features a mix of large, diversified healthcare conglomerates and specialized urology device manufacturers. Strategic archetypes include integrated device providers, niche technology innovators, and regional distributors. Portfolio diversification and strategic partnerships are dominant competitive moves, aiming to capture new application areas and improve market access.
Specialists in advanced materials science and chronic care solutions exemplify key industry archetypes within the urology devices market. Boston Scientific Corporation, a US-based entity, represents a diversified player leveraging R&D in materials science for next-generation devices. Medtronic plc, an Irish-domiciled multinational, occupies a position across multiple urology segments by integrating its device portfolio with surgical robotics. Coloplast A/S, a Danish medical device company, sits within the chronic care product segment, focusing on user comfort and infection prevention.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Fresenius Medical Care AG & Co. KGaA |
| Medtronic plc |
| Olympus Corporation |
| Coloplast A/S |
| Becton, Dickinson and Company |
| Cook Medical |
| Stryker |
| KARL STORZ SE & Co. KG |
| Others |
Cost & Logistics Intelligence
The US FDA's heightened focus on reprocessed device safety drives demand for single-use urology instruments, compelling manufacturers to re-evaluate production costs and pricing strategies for disposable alternatives.
Pricing Analysis
Rising costs for advanced antimicrobial polymers and embedded sensing components influence device pricing across the urology market. Per-unit transactional pricing dominates for high-volume consumables like catheters. Value-based pricing applies to complex systems such as robotic platforms, differentiated by FDA/MDR certification and integrated service contracts. Pricing pressure stems from evolving reimbursement policies and payor demands for cost-effectiveness. Ambulatory surgical centers and public healthcare systems exhibit high price sensitivity, while specialized urology clinics prioritize clinical outcomes for premium diagnostic tools.
Supply Chain Analysis
Direct sales forces manage distribution for capital-intensive urology devices to large hospital systems. Consumables and single-use instruments often leverage specialized medical device distributors to reach clinics and ambulatory surgical centers. Supply concentration rests in Germany for precision surgical instruments and in the US for advanced robotic components. Raw material dependencies include specialized polymers and high-resolution imaging sensors. Regulatory compliance, particularly with EU MDR, presents a structural risk for manufacturers sourcing globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urology devices market presents a clear margin-expansion story, driven by the shift towards premium-priced, single-use devices with embedded sensing technology.
For Market Incumbents: Deploy strategic M&A to consolidate market share in high-growth segments like robotic surgery. Invest in R&D for next-generation antimicrobial polymers to counter infection risks and strengthen product differentiation against new entrants. Strengthen relationships with GPOs and hospital networks through managed service agreements to mitigate reimbursement pressure. This defends against generic device competition and regulatory tightening.
For New Entrants and Emerging Players: Capture white-space opportunities in female urology by developing specialized devices for pelvic organ prolapse and stress urinary incontinence. Target underserved geographies like Brazil, leveraging improving healthcare infrastructure for market entry. Focus on cost-effective, single-use diagnostic tools for ambulatory surgical centers, offering rapid adoption potential. A go-to-market angle involves partnering with local distributors for market access and regulatory navigation.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized technology innovators focusing on AI integration and miniaturized sensing for diagnostic accuracy. Long-term viability favors companies with strong intellectual property in advanced materials science and robotic-assisted platforms. Target acquisition archetypes include agile firms with novel disposable endoscope technologies or established market access in emerging economies. The signal to watch is the increasing rate of regulatory approvals for AI-powered diagnostic solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Advanced Materials | Enhances product performance and reduces infection rates in catheters. |
| Strategic Partnerships for AI | Integrates diagnostic intelligence into imaging systems for precision. |
| Expansion in Ambulatory Centers | Addresses demand for cost-effective, high-turnover urological procedures. |
| Managed Service Agreements | Reduces capital expenditure barriers for hospitals adopting robotics. |
| Regulatory Pathway Navigation | Secures market access for innovative devices in complex regulatory environments. |
Research Approach
Bottom-up end-user modeling reconciled against top-down device manufacturer tracking forms the analytical core for this urology devices market study. Primary interviews with clinicians, hospital procurement managers, R&D directors, and regulatory specialists provided qualitative insights. Secondary validation drew from US FDA filings, European Medicines Agency MDR reports, and NMPA device classifications. This blended approach ensures comprehensive data triangulation for market sizing and trend identification.
An input-output matrix correlates technology adoption rates with procedural volumes across the analysis window. Segmentation dimensions modeled include product type, end-user, application, technology, and key geographic markets like Germany and China. Compound annual growth rates were derived from historical data analysis and projected market drivers. Key forecast inputs included demographic shifts in developed economies and regulatory changes impacting device approvals.
Regulatory policy shifts, technological breakthroughs, and evolving reimbursement landscapes are the dominant revision risks for market forecasts. Forecasts reflect current market conditions and documented assumptions regarding healthcare spending. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Urology Forceps Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Obstructive Uropathy Treatment Market
Urology
Asia-Pacific Bladder Disorders Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Nocturia Market
Urology
Hematuria Treatment Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Benign Prostatic Hyperplasia Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Urology Laser Fibers Market
Urology
Urinary Incontinence Market
Urology
Varicocele Treatment Market
Urology
Global Urinary Tract Infections Therapeutics Market